
 Europe Palletizer Market | 2026-2036
Europe Palletizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Palletizer Market Foresight
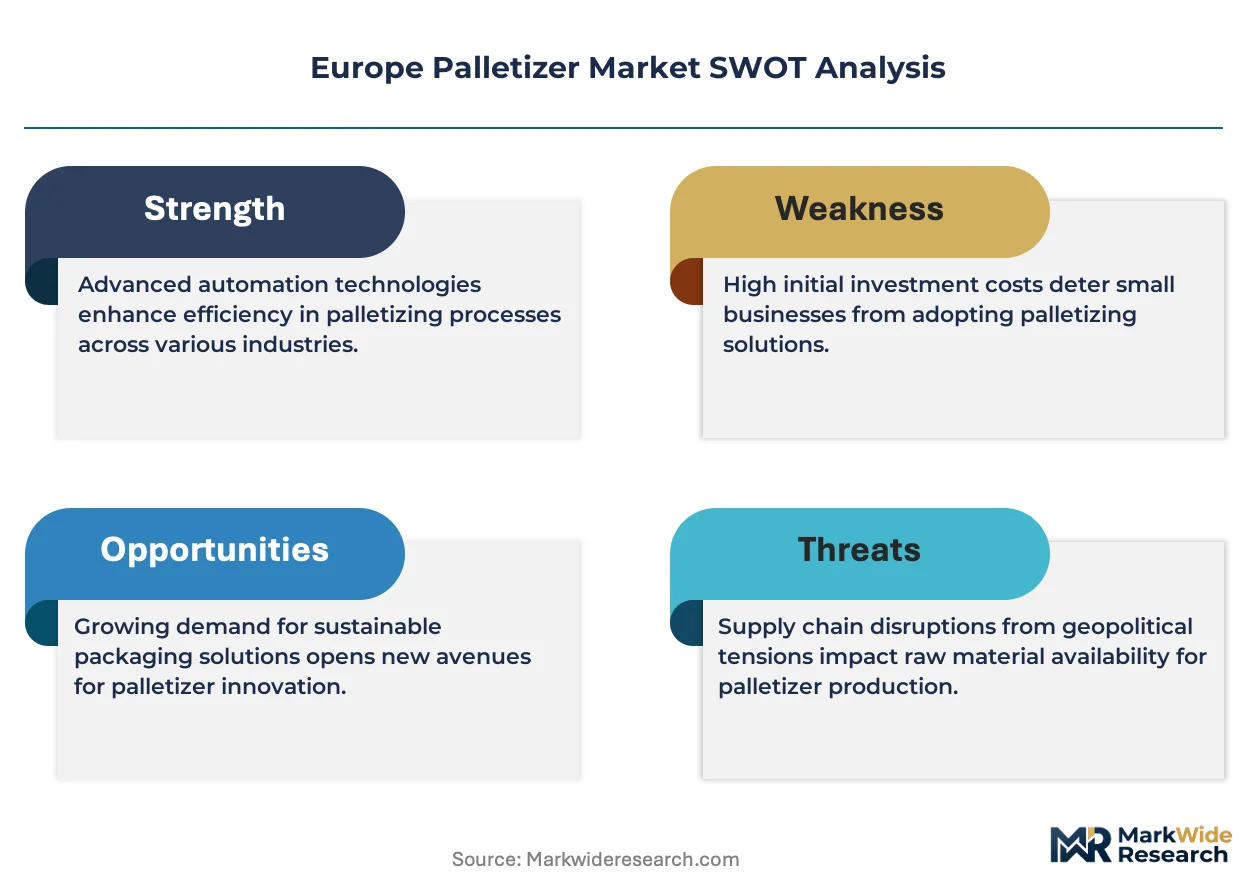
The gap between premium robotic palletizers and commodity semi-automated units is recalibrating procurement priorities across European packaging lines. ABB Ltd leverages its robotics heritage to dominate high-speed electric palletizing cells for beverage producers. KUKA AG anchors its position through deep integration with German automotive-tier logistics standards. Beumer Group GmbH and Co. KG competes on turnkey material-handling systems that bundle palletizers with upstream conveying.
A palletizer is an automated material-handling machine that arranges cases, bags, or containers into unitized loads on pallets, typically operating at throughputs of 10–200 cycles per minute depending on payload weight and gripper configuration. Its primary purpose is to eliminate manual stacking at the terminus of production lines while ensuring load stability for warehouse storage and over-the-road transport. Robotic palletizers now lead European order books as food and beverage processors replace aging mechanical gantries with articulated-arm systems offering SKU flexibility. Electric drive technology is displacing pneumatic and hydraulic alternatives where energy efficiency targets and maintenance cost reduction shape capital expenditure decisions. The semi-automated segment retains share among mid-tier consumer goods packagers with lower throughput requirements and constrained automation budgets.
The EU Machinery Directive and CE marking framework mandate safety interlocks and risk assessments that extend engineering lead times but lock out uncertified imports. REACH and RoHS constraints on materials and electronics components filter through to control-panel specifications and cable insulation choices. Germany's KBA-equivalent machinery safety enforcement and France's labor regulations on manual handling thresholds reinforce automation incentives. Stakeholders must monitor how the EU AI Act classification criteria apply to vision-guided robotic palletizers with autonomous collision-avoidance algorithms.
Market Dynamics
Electric drive architectures are compressing the performance gap between robotic and mechanical palletizing systems across European packaging halls. This technology shift is redistributing capital expenditure toward energy-efficient configurations while forcing incumbent suppliers to re-engineer legacy platforms.
Growth Catalysts
- REACH compliance mandates:Material restrictions on cable insulation and control-panel components accelerate replacement of pre-2010 equipment. Food processors in Germany's industrial corridor face the tightest compliance deadlines.
- France's manual handling thresholds:Labor regulations capping repetitive lifting weights push mid-tier beverage packagers toward articulated-arm systems. Enforcement has tightened since 2023 workplace safety audits.
- SKU proliferation in private-label food:Retailer demand for shorter production runs favors robotic flexibility over fixed mechanical gantries. Italian pasta and sauce producers report the highest SKU velocity.
Market Restraints
- Steel and servo motor cost volatility:Input price swings for precision mechanical components compress margin visibility on fixed-price turnkey contracts. German system integrators bear the heaviest exposure.
- CE marking engineering lead times:Safety interlock documentation and third-party conformity assessments extend project delivery by 8-14 weeks. Uncertified Turkish and Chinese imports face automatic exclusion.
- Pneumatic system residual value:Existing compressed-air infrastructure in older plants creates switching-cost resistance. Eastern European meat processors show the highest installed-base attachment.
Strategic Opportunities
- Poland's underpenetrated beverage sector:Bottling capacity expansion near Warsaw and Wrocław lacks corresponding palletizing automation. Regional dairy cooperatives represent untapped demand.
- EU AI Act classification for vision systems:Autonomous collision-avoidance algorithms in high-speed cells may trigger preferential treatment under regulatory sandboxes. Early certification creates first-mover positioning.
- Pharmaceutical serialization convergence:Track-and-trace mandates for secondary packaging create bundled demand for palletizers with integrated aggregation software. Belgian and Dutch contract packagers lead adoption.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of electric drive systems requires skills bridging PLC programming and mechanical alignment. German vocational pipelines produce insufficient certified specialists.
- Legacy SCADA integration complexity:Brownfield sites running 1990s-era Allen-Bradley or Siemens S5 platforms face protocol translation costs. Retrofit projects in Northern England show the highest abandonment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Palletizer Market |
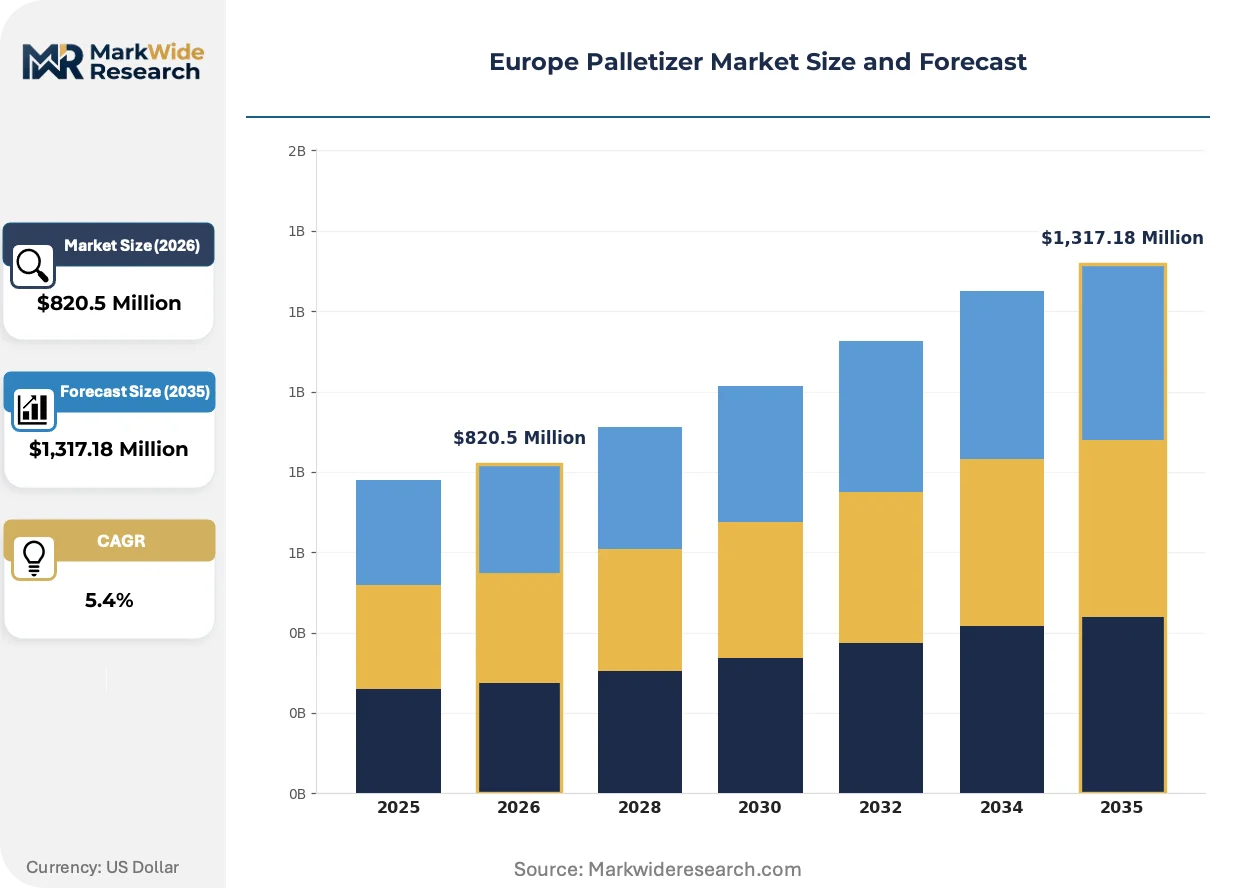
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,317.18 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Robotic, Automated, Semi-Automated, Manual End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Technology: Pneumatic, Hydraulic, Electric, Mechanical Installation: On-Site, Integrated, Portable, Permanent |
| Companies Covered | ABB Ltd, Beumer Group GmbH and Co. KG, KION Group AG, Krones AG, KUKA AG, Honeywell International Inc., Concetti S.P.A, Aetnagroup Spa, Sidel, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Palletizer Market Shifts & Advancements
Collaborative robot architectures are penetrating palletizing workflows previously reserved for caged industrial systems. This shift is compressing the traditional boundary between human-robot interaction standards and high-speed material handling.
Collaborative palletizing arms with force-limiting joints and area-scanning light curtains are rewriting safety zone requirements for end-of-line operations. Mid-sized Dutch cheese processors are piloting these systems at 15-20 cycles per minute. The technology is enabling floor-space reductions of 30-40% versus conventional guarding configurations.
EU AI Act risk classification criteria are reshaping engineering documentation for vision-guided robotic cells. Systems with autonomous path-planning algorithms now require algorithmic transparency dossiers. German automotive-tier suppliers have responded by segregating AI-enabled and deterministic control architectures in separate product lines.
Subscription-based maintenance contracts are displacing traditional time-and-materials service agreements for multi-cell installations. French beverage cooperatives now prioritize vendors offering guaranteed uptime clauses over capital purchase discounts. This preference is most visible in the Champagne region's mid-size houses modernizing bottling halls.
Europe Palletizer Market Segmentation
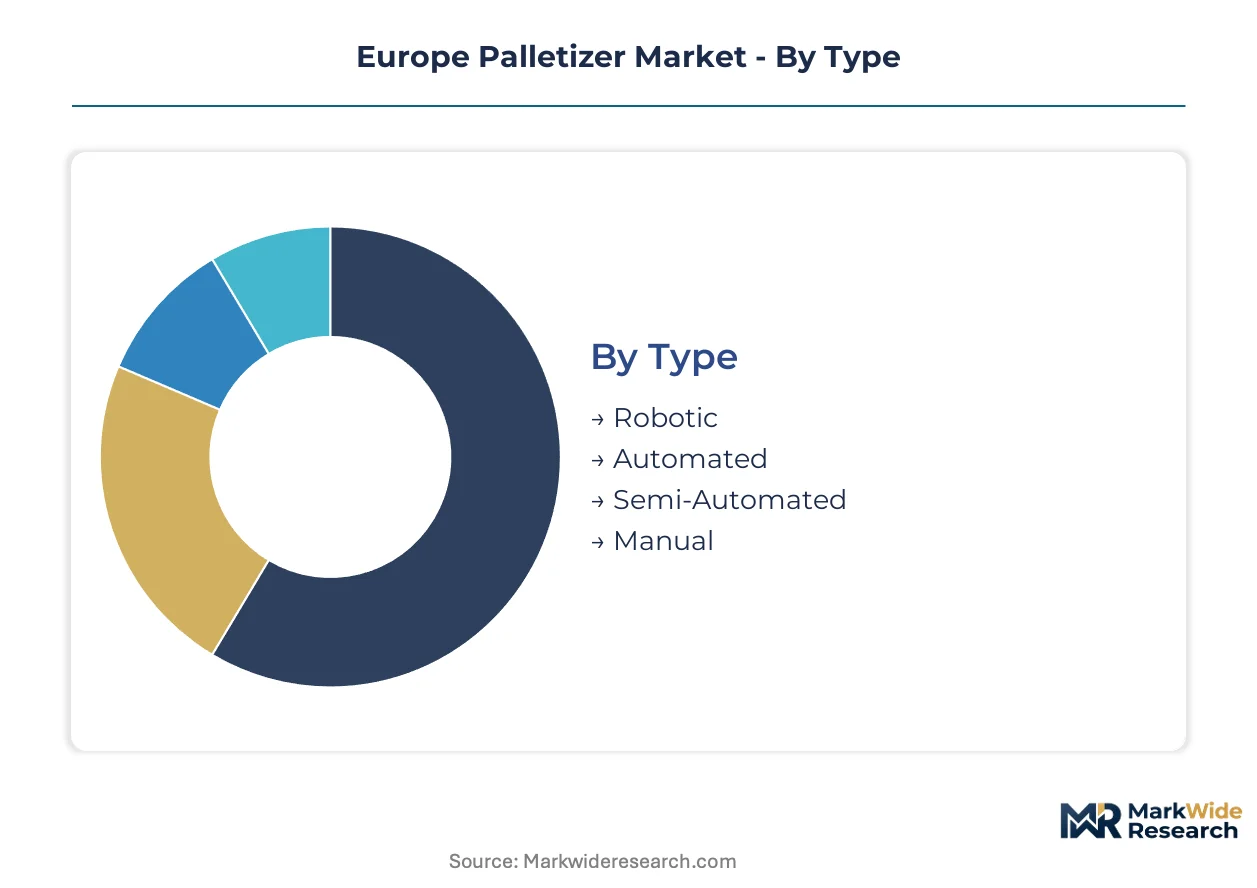
European palletizer procurement splits across four distinct axes that shape capital allocation patterns. Technology type determines energy efficiency compliance paths under EU Machinery Directive mandates. End-use concentration in Germany's food corridor and France's beverage belt drives specification requirements for throughput and SKU flexibility.
Type:
Technology sophistication defines the competitive tier and regulatory compliance burden for each configuration.
- Robotic:Articulated-arm systems with servo-driven joints execute 20–200 cycles per minute depending on payload and reach envelope. German beverage producers along the Rhine-Main industrial corridor specify these for multi-SKU bottling lines where changeover speed determines line efficiency. CE marking documentation for collaborative variants now incorporates EU AI Act risk classification for vision-guided path planning.
- Automated:Fixed-gantry mechanical systems with programmable logic controllers deliver consistent throughput for stable product mixes. French dairy cooperatives in Brittany deploy these for standardized cheese case handling where SKU velocity remains low. Energy efficiency mandates under EU Green Deal timelines accelerate replacement of pre-2010 pneumatic gantry installations.
- Semi-Automated:Operator-assisted layer forming with mechanical elevation reduces manual stacking without full robotics cost. Mid-tier Italian pasta packagers with constrained automation budgets favor these for seasonal demand spikes.
- Manual:Human-powered pallet building with ergonomic lift assists persists in Eastern European meat processing where labor costs offset throughput penalties.
Robotic configurations lead on scale; semi-automated units lead on momentum in margin-constrained segments.
End User:
Application environment dictates safety interlock specifications and throughput architecture.
- Food & Beverage:Stainless steel construction with IP65 washdown ratings handles moisture and chemical exposure in dairy and brewing operations. German malt houses and Dutch cheese processors drive specification standards for hygienic design under EHEDG guidelines.
- Pharmaceuticals:Cleanroom-compatible palletizers with serialization aggregation software bundle track-and-trace compliance into end-of-line automation. Belgian contract packagers near Antwerp lead adoption of integrated aggregation cells.
- Consumer Goods:High-speed layer forming for corrugated cases and shrink-wrapped bundles serves personal care and household product distribution. French private-label manufacturers prioritize flexibility over raw speed.
- Electronics:Gentle handling for ESD-sensitive components with vacuum or foam gripper configurations protects fragile payloads. Slovakian contract electronics manufacturers near Bratislava represent emerging demand.
Food and beverage dominates installed base; pharmaceuticals climbs fastest on serialization convergence.
Technology:
Drive architecture determines energy accounting, maintenance intervals, and retrofit compatibility.
- Electric:Servo motor precision with regenerative braking cuts energy consumption versus pneumatic alternatives. German automotive-tier logistics standards now mandate electric drives for new installations.
- Pneumatic:Compressed-air actuation retains installed-base presence in Eastern European plants with captive compressor infrastructure. Poland's meat processing sector shows highest residual attachment.
- Hydraulic:High-force density for heavy payload handling persists in bulk material applications. Limited new adoption due to oil containment and energy efficiency liabilities.
- Mechanical:Cam-driven and linkage-based motion control delivers deterministic repeatability for stable product formats. Italian machinery builders specialize in these cost-optimized configurations.
Electric systems command the expansion trajectory; pneumatic retains defensive share in legacy infrastructure.
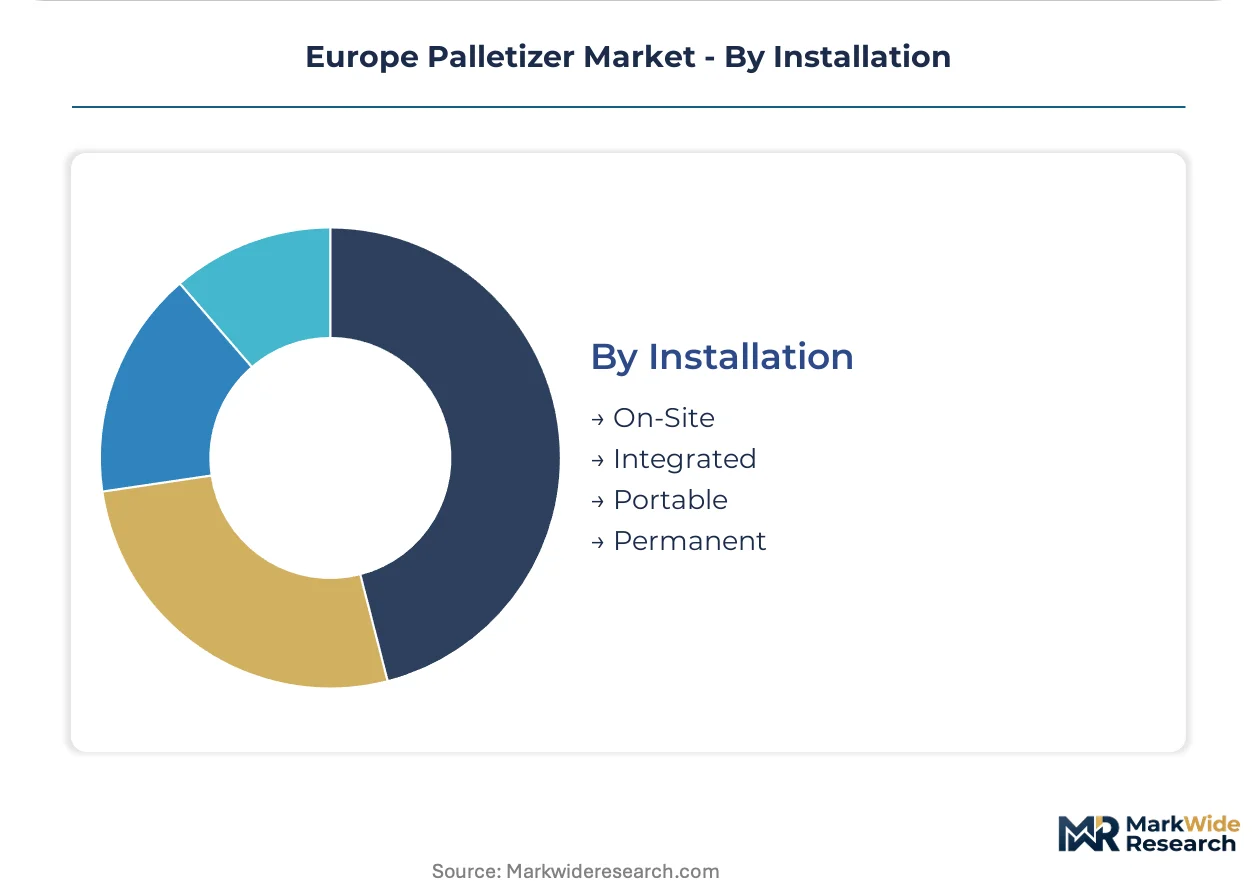
Installation:
Deployment model shapes project economics and operational flexibility.
- On-Site:Custom-engineered integration with existing conveyor infrastructure requires extended commissioning schedules. Northern England brownfield retrofits show highest engineering complexity.
- Integrated:Turnkey cells bundled with upstream depalletizing, conveying, and wrapping from single-source suppliers. Beumer Group and KUKA dominate this configuration in Germany.
- Portable:Skid-mounted units with plug-and-play utilities enable seasonal capacity scaling. French wine cooperatives deploy these for harvest-period bottling surges.
- Permanent:Fixed foundation installations with 15–20 year depreciation horizons suit high-volume continuous operations. Dutch brewery greenfield projects specify these exclusively.
Integrated installations anchor revenue concentration; portable configurations gain traction in seasonal industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics technician pipelines in Germany's industrial corridor anchor European palletizer deployment capacity. French automation engineers concentrate around Lyon and Paris packaging clusters. Italian machinery specialists in Emilia-Romagna sustain semi-automated system exports.
Germany
Beverage bottlers along the Rhine-Main corridor demand high-speed electric palletizing cells for multi-SKU flexibility. KBA machinery safety enforcement mandates certified safety interlocks under EU Machinery Directive timelines. Bavarian dairy processors near Munich upgrade aging pneumatic gantries to meet REACH cable insulation deadlines.
France
Manual handling thresholds from tightened workplace safety audits push mid-tier Champagne houses toward articulated-arm systems. ANSM and labor inspectorate coordination enforces repetitive lifting weight caps in food processing. The Champagne region's cooperatives modernize bottling halls with subscription-based maintenance contracts.
Italy
Pasta and sauce producers report Europe's highest SKU velocity, favoring robotic flexibility over fixed mechanical systems. CE marking documentation requirements filter equipment imports through certified channels. Emilia-Romagna machinery builders specialize in cost-optimized mechanical configurations for margin-constrained packagers.
Netherlands
Cheese processors pilot collaborative palletizing arms with force-limiting joints at 15-20 cycles per minute. EHEDG hygienic design guidelines govern stainless steel construction specifications. Dutch brewery greenfield projects specify permanent foundation installations with 15-20 year depreciation horizons exclusively.
Poland
Bottling capacity expansion near Warsaw and Wrocław lacks corresponding palletizing automation depth. The country's national machinery safety framework aligns with EU Machinery Directive transposition deadlines. Regional dairy cooperatives represent untapped demand for skid-mounted portable units enabling seasonal capacity scaling.
Europe Palletizer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across European palletizer supply. The vendor base concentrates around German automotive-tier robotics heritage and Italian mechanical engineering traditions. Three archetypes dominate: integrated turnkey system houses, standalone robotic cell suppliers, and regional machinery specialists. M&A activity consolidates conveying and palletizing capabilities while geographic expansion targets underpenetrated Central European beverage markets.
Within the integrated turnkey tier, Beumer Group GmbH and Co. KG and KION Group AG exemplify bundled material-handling strategies. ABB Ltd occupies a position bridging high-speed electric palletizing heritage with collaborative robotics adaptation. KUKA AG anchors German automotive-tier logistics standards that propagate through European packaging automation procurement specifications.
| Leading Market Players |
|---|
| ABB Ltd |
| Beumer Group GmbH and Co. KG |
| KION Group AG |
| Krones AG |
| KUKA AG |
| Honeywell International Inc. |
| Concetti S.P.A |
| Aetnagroup Spa |
| Sidel |
| Others |
Supply & Pricing Matrix
German automotive-tier logistics procurement teams anchor European palletizer demand, driving a contract-based pricing model where bundled turnkey installations command premium positioning over standalone robotic cells. This buyer concentration compresses margin visibility for system integrators facing volatile servo motor and precision steel input costs.
Pricing Analysis
Bundled maintenance subscriptions versus unbundled capital purchase splits the European palletizer market into divergent revenue streams. Three-tier pricing structure across premium robotic, standard automated, and economy semi-automated levels reflects CE certification grade and after-sales service depth. Cost compression in the semi-automated tier is intensifying because Turkish and Chinese imports face automatic exclusion under EU Machinery Directive mandates. Mid-tier Italian pasta packagers exhibit highest price sensitivity, while Rhine-Main beverage bottlers prioritize guaranteed uptime clauses over capital discounts.
Supply Chain Analysis
Warehouse-distribution layer configurations across Germany, Italy, and Poland shape downstream equipment fulfillment patterns for European palletizer deployment. Component sourcing draws from German servo motor specialists, Italian mechanical linkage fabricators, and Chinese control panel suppliers. Single-source vulnerability in precision harmonic drives creates bottleneck exposure for high-speed robotic cells. Distribution runs through integrated system houses in Bavaria and Emilia-Romagna that bundle conveying, palletizing, and wrapping into turnkey project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European palletizer procurement has shifted into late-cycle quality territory as food and beverage processors prioritize CE-certified electric drive systems over pneumatic alternatives. This demand migration toward premium specifications rewards vendors with established safety documentation and service infrastructure.
For Market Incumbents: Lock in service contract renewal rates by embedding predictive maintenance algorithms into installed electric drive bases. Consolidate conveying and palletizing capabilities through selective acquisition of regional machinery specialists in Poland and the Czech Republic. This defends against emerging Chinese entrants exploiting cost advantages in semi-automated configurations. For New Entrants and Emerging Players: Enter via Poland's underpenetrated beverage corridor, where bottling capacity expansion near Warsaw and Wrocław lacks corresponding palletizing automation depth. Target regional dairy cooperatives with skid-mounted portable units enabling seasonal capacity scaling. Lead with subscription-based maintenance contracts that mirror Champagne region procurement preferences. For Investors and Strategic Acquirers: Material handling conglomerates with conveying heritage represent the most active acquirer in this space, seeking palletizing capabilities to complete end-of-line automation portfolios. Five-to-ten year viability hinges on electric drive technology transition completion. Monitor EU AI Act certification timelines for vision-guided robotic cells as inflection signal for first-mover positioning in collaborative palletizing architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | German system integrators reduce exposure to input price volatility through captive supply of precision drive components. |
| EU AI Act Certification for Vision Systems | Early algorithmic transparency dossiers create regulatory sandbox positioning for autonomous collision-avoidance cells. |
| Subscription-Based Maintenance Contracts | French beverage cooperatives prioritize guaranteed uptime clauses over capital purchase discounts in modernization cycles. |
| Geographic Expansion into Polish Beverage Corridor | Bottling capacity expansion near Warsaw lacks corresponding palletizing depth, creating white-space demand for portable units. |
| Pharmaceutical Serialization Convergence | Belgian contract packagers drive bundled demand for palletizers with integrated track-and-trace aggregation software. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement team discussions, aftermarket service head consultations, and regulatory affairs dialogues — were reconciled against secondary validation. Primary engagement with maintenance directors at German dairy processors, packaging line managers at French beverage cooperatives, and technical directors at Italian machinery builders anchored demand-side intelligence. Secondary sources encompassed EU Machinery Directive transposition documents, CE marking conformity assessment records, EHEDG hygienic design guidelines, and customs trade data for palletizing equipment imports. Bottom-up equipment shipment tallies and top-down packaging automation investment flows were triangulated to constrain estimate variance.
Historical capacity deployment patterns were cross-referenced against expert panel input on technology transition timing. Segmentation modeling spanned technology type, end-use vertical, drive architecture, and installation configuration across the projection horizon. CAGRs were derived from slope analysis of replacement cycle acceleration and greenfield investment trajectories. Electric drive adoption curves and SKU proliferation indices in private-label food processing served as industry-specific forecast inputs.
Inputs from EU regulatory filing databases and national machinery safety enforcement records were available through the study window; gaps in real-time project pipeline visibility from mid-tier Italian packagers introduce uncertainty bands around near-term shipment estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallets Market