
 Pallet Pooling Market | 2026-2036
Pallet Pooling Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Pooling Market Intelligence
Modular packaging configurations across food and beverage supply chains is consolidating buyer preference toward standardized pallet dimensions that interchange seamlessly between manufacturers and retailers. Brambles Limited leverages its CHEP network to sustain global coverage through depot-based circulation systems. Rehrig Pacific Company anchors North American operations with proprietary plastic pallet designs optimized for automated handling. Euro Pool Group competes through closed-loop pooling services specialized for fresh produce logistics across European retail networks.
Pallet pooling denotes the shared-use system where standardized pallets circulate among multiple shippers, receivers, and logistics providers through rental, exchange, or managed service arrangements, typically constructed from high-density polyethylene, hardwood, or galvanized steel with load ratings between 1,500 and 2,800 kilograms. The primary commercial purpose eliminates capital expenditure on pallet ownership while ensuring consistent quality for automated warehouse systems and transportation optimization. Plastic pallet types lead service model adoption due to durability advantages in hygienic applications, while rental and leasing service models capture the dominant share of recurring revenue as operators prefer operational expenditure structures over asset ownership. Food and beverage end users generate the largest volume demand, though pharmaceutical applications command premium pricing through sanitized pallet certification requirements.
The EPA regulates wood treatment chemicals under pesticide application standards, while FDA food safety rules mandate pallet sanitation protocols for pharmaceutical and food contact applications. ISO 8611 testing standards govern pallet load performance certification, creating compliance barriers for unqualified manufacturers. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could impose end-of-life recycling obligations on pooling operators.
Market Dynamics
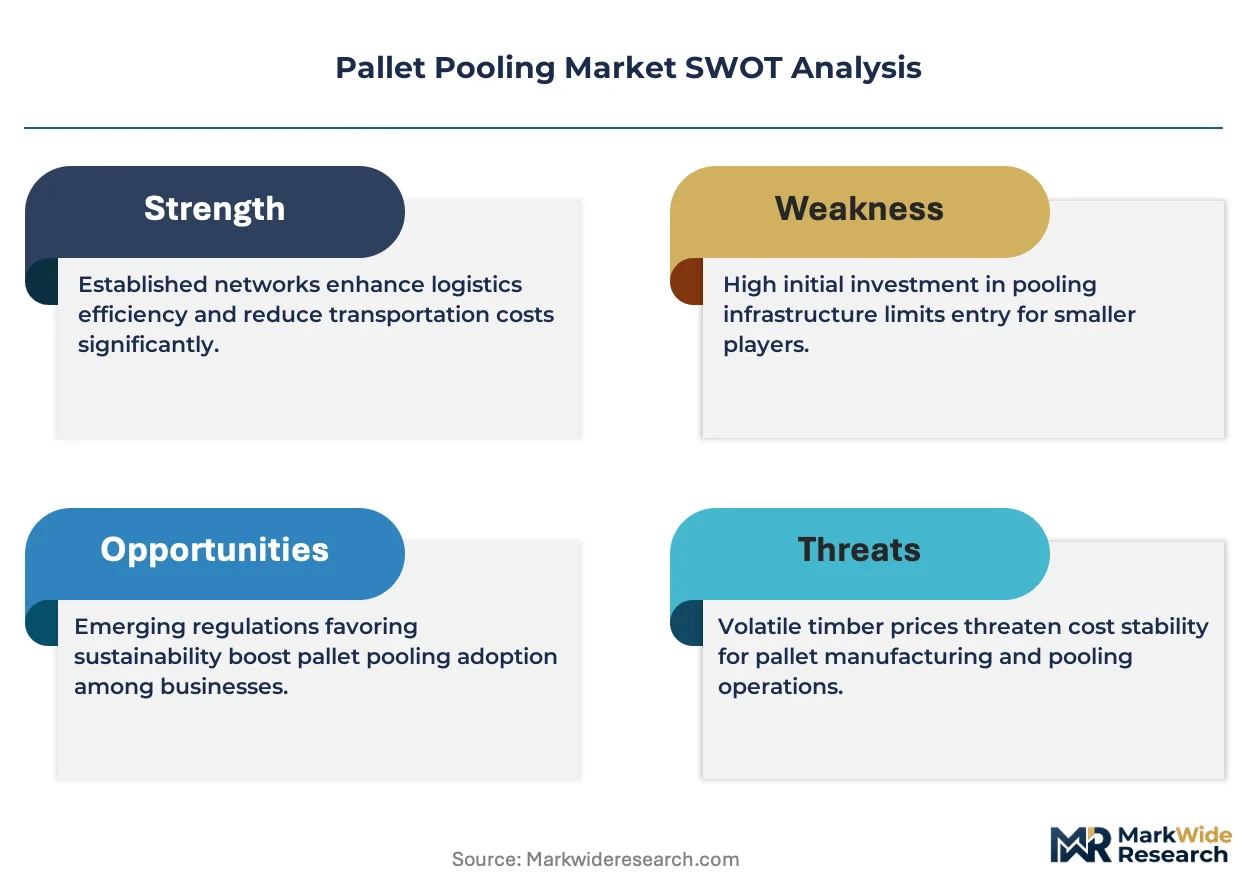
The EU Green Deal's circular economy mandates are forcing pooling operators to reengineer asset recovery systems and material composition strategies across European supply chains.
Growth Catalysts
- Cold Chain Expansion:Pharmaceutical distributors are adopting plastic pallet pooling to reduce breakage rates in temperature-sensitive logistics. FDA sanitation protocols for drug contact surfaces accelerate hygienic pallet certification demand.
- REACH Compliance:ECHA chemical registration requirements for wood treatment biocides are pushing manufacturers toward high-density polyethylene alternatives with lower regulatory burden.
- Just-in-Time Protocols:Germany's automotive supplier corridor concentrates demand for standardized pooling networks that interchange seamlessly between tier-one suppliers and OEM assembly plants.
Market Restraints
- Resin Price Volatility:High-density polyethylene feedstock costs fluctuate with crude oil indices, compressing margins for plastic pallet operators during energy price spikes.
- Depot Network Concentration:Pallet circulation efficiency depends on geographic density of service points, creating coverage gaps in rural Eastern European markets.
- Wood Pallet Substitution:Single-use hardwood pallets retain cost advantage for low-rotation, non-hygienic applications, limiting pooling penetration in commodity freight segments.
Strategic Opportunities
- Fresh Produce Specialization:Closed-loop pooling services for retail grocery networks remain underdeveloped in Southern European markets outside established Benelux operations.
- IoT-Enabled Asset Tracking:Integration of RFID and GPS telemetry with pallet management software is unifying physical circulation with digital supply chain visibility platforms.
- Extended Producer Responsibility:State-level recycling mandates in France and Italy create regulatory tailwinds for operators with established plastic recovery infrastructure.
Industry Challenges
- Sanitation Certification Timelines:FDA food safety validation for pharmaceutical-grade pallets requires extended laboratory testing cycles that delay new product commercialization.
- Legacy Warehouse Automation:Automated handling systems in older distribution centers require retrofitting to accommodate standardized pooling pallet dimensions, creating integration friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Pooling Market |
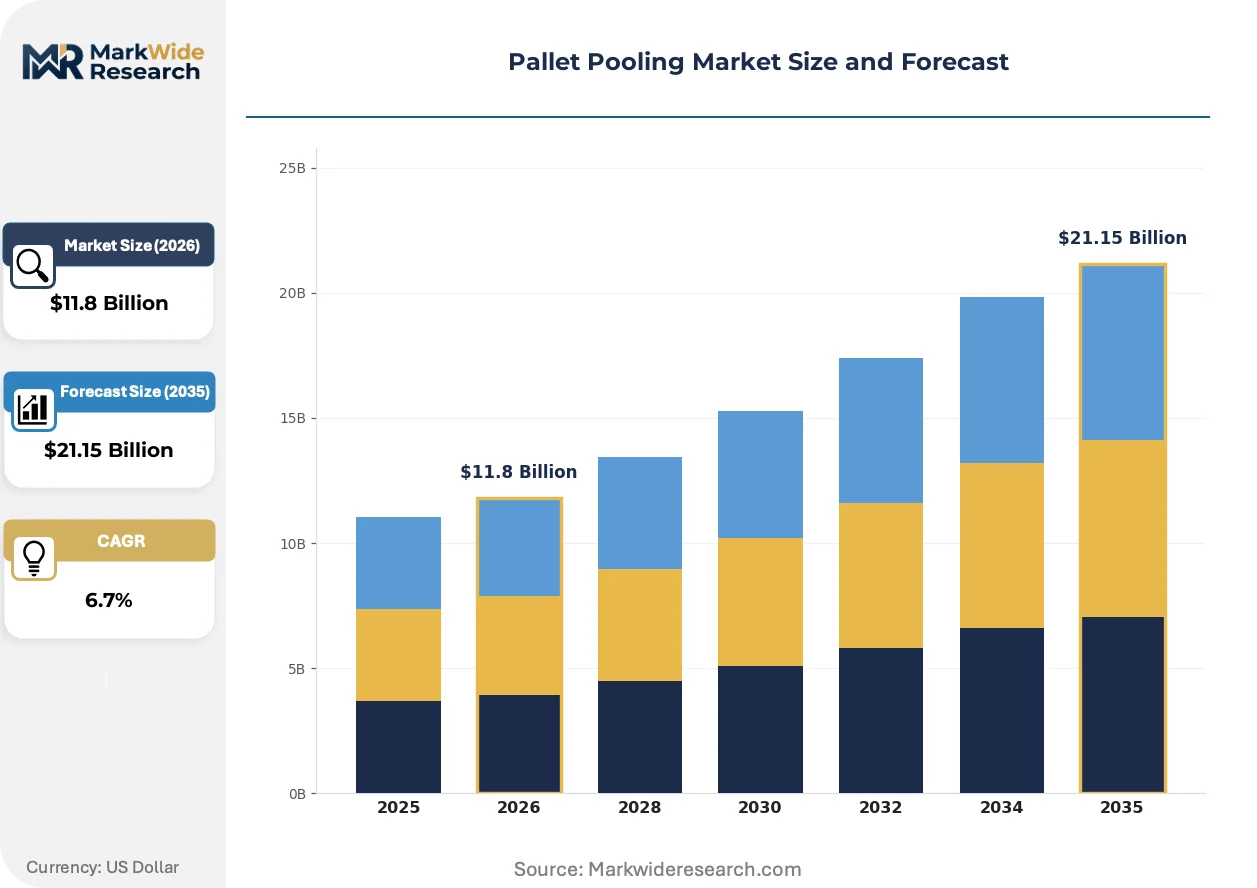
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pallet Type: Plastic, Wooden, Metal, Paperboard, Composite Service Model: Exchange, Rental, Leasing, Maintenance, Managed Services End User Industry: Food & Beverage, Pharmaceuticals, Automotive Tier-1 Suppliers, Consumer Electronics, Chemicals Distribution Channel: Direct Sales, Third-Party Logistics, Online Platforms, Wholesale Distributors |
| Companies Covered | China Merchants Loscam International Holdings, Rehrig Pacific Company, Brambles Limited (CHEP), Contraload NV, Euro Pool Group, PECO Pallet, IFCO Systems, Schoeller Allibert Services, iGPS Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Pooling Market Strategic Shifts & Innovations
Digital asset tracking and regulatory pressure on material circularity are converging to reshape how pooling operators manage fleet composition and customer accountability.
RFID-embedded pallet identification is unifying physical asset location with enterprise resource planning systems in real time. Food and beverage distributors with high inventory velocity are deploying these tags at scale. The technology is compressing invoice reconciliation cycles and reducing unaccounted asset losses in multi-party supply chains.
EU Green Deal packaging waste directives are mandating recycled content minimums for plastic logistics equipment. Pooling operators must certify post-consumer resin percentages through third-party verification. German automotive suppliers face the tightest compliance deadlines, accelerating supplier qualification processes for circular material streams.
Outcome-based rental contracts are displacing flat-rate per-trip pricing in pharmaceutical logistics. Sanitation guarantees and damage liability transfers now determine supplier selection more than unit economics alone. This preference shift concentrates procurement authority among large-scale 3PLs with integrated quality management systems.
Pallet Pooling Market Segmentation
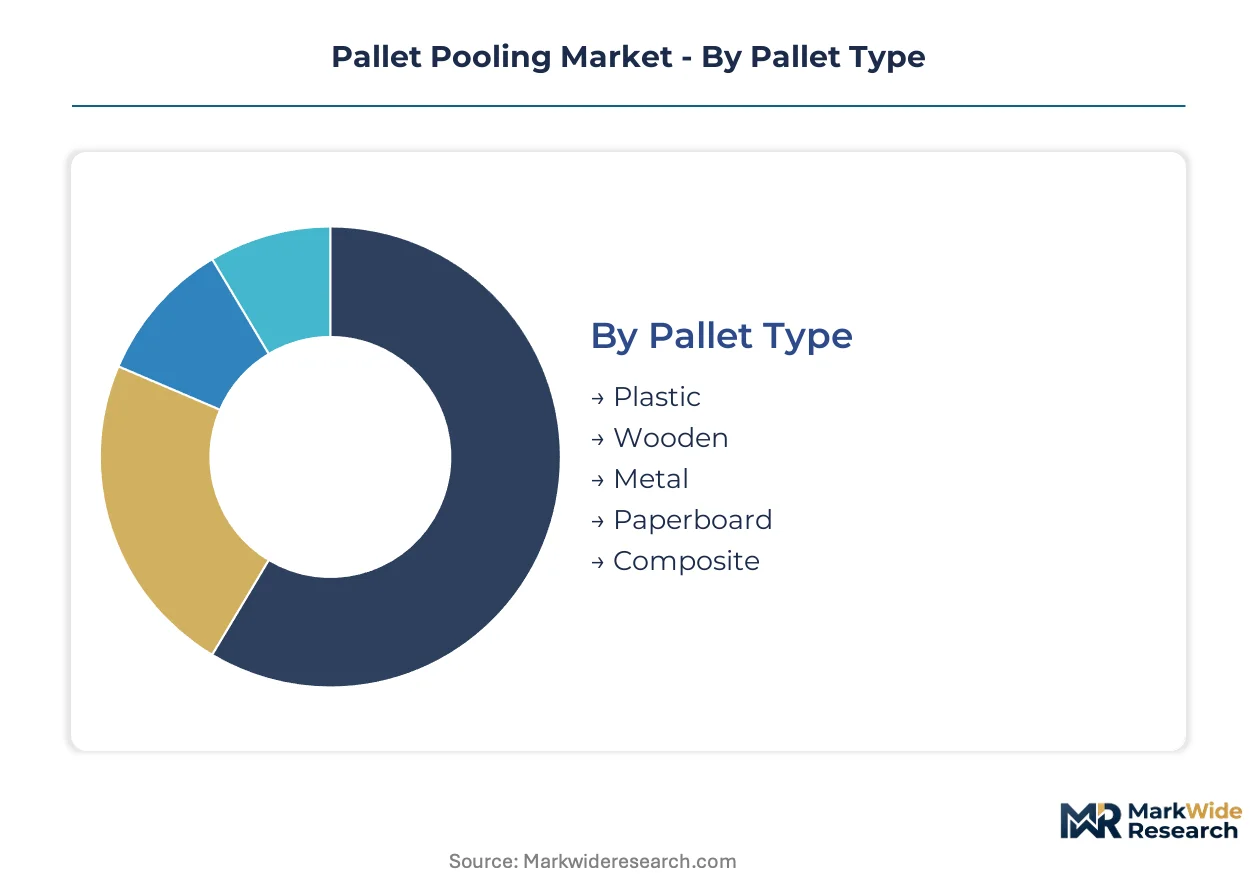
Pallet pooling operators segment their offerings to match asset durability with hygiene requirements, service intensity with customer capital preferences, and geographic coverage with industry-specific logistics patterns. Each segmentation axis reveals distinct margin structures and competitive barriers that shape operator positioning.
Pallet Type:
Material selection separates customers by hygiene sensitivity, load specification, and total cost of ownership over circulation cycles.
- Plastic:High-density polyethylene construction delivers consistent dimensional stability for automated handling systems. Pharmaceutical distributors in Germany's Rhine-Ruhr corridor specify plastic pallets to meet FDA sanitation protocols for drug contact surfaces, with ECHA REACH compliance reducing regulatory burden versus chemically treated alternatives.
- Wooden:Hardwood platforms dominate cost-sensitive applications with lower rotation frequency. Single-use wooden pallets retain price advantage for commodity freight segments across Eastern European markets where depot network density remains insufficient for efficient pooling returns.
- Metal:Galvanized steel construction serves extreme load ratings and fire-resistant warehouse requirements.
- Paperboard:Lightweight fiber-based pallets target air freight weight-sensitive logistics and single-trip export documentation.
- Composite:Hybrid material formulations blend plastic durability with wood cost structures for mid-tier applications.
Volume sits with Wooden pallets; growth tilts toward Plastic.
Service Model:
Contract structure reflects customer preference for operational expenditure versus asset control, with liability allocation determining procurement authority.
- Rental:Per-trip or time-based pricing eliminates capital expenditure while transferring damage liability to operators. Food and beverage distributors with high inventory velocity prefer rental structures to align pallet costs with shipment frequency rather than asset ownership.
- Leasing:Long-term contracts with purchase options appeal to customers seeking balance sheet treatment flexibility. Automotive tier-1 suppliers in Germany's supplier corridor leverage leasing to maintain standardized pooling networks without full capital commitment.
- Exchange:Trip-for-trip pallet substitution at depot points enables rapid turnaround for high-velocity supply chains.
- Maintenance:Repair and refurbishment services extend asset life for customers with captive pallet fleets.
- Managed Services:Full outsourcing of pallet procurement, tracking, and recovery integrates with customer ERP systems.
Revenue concentrates in Rental contracts; expansion is climbing the fastest in Managed Services.
End User Industry:
Industry verticals segment by hygiene certification requirements, load standardization, and supply chain velocity.
- Food & Beverage:High-volume rotation demands with moderate hygiene specifications. Fresh produce logistics across Benelux retail networks drives closed-loop pooling adoption, though Southern European markets remain underdeveloped outside established operations.
- Pharmaceuticals:Sanitized pallet certification commands premium pricing through extended FDA validation timelines. Cold chain operators adopt plastic pooling to reduce breakage rates in temperature-sensitive distribution, with outcome-based contracts displacing flat-rate pricing.
- Automotive Tier-1 Suppliers:Just-in-time delivery protocols in Germany favor standardized dimensions for seamless interchange between suppliers and OEM assembly plants.
- Consumer Electronics:High-value, lightweight cargo requires precise load distribution and anti-static properties.
- Chemicals:Hazardous material regulations dictate specialized containment and spill-resistant designs.
Demand volume favors Food & Beverage; value capture is expanding most quickly in Pharmaceuticals.
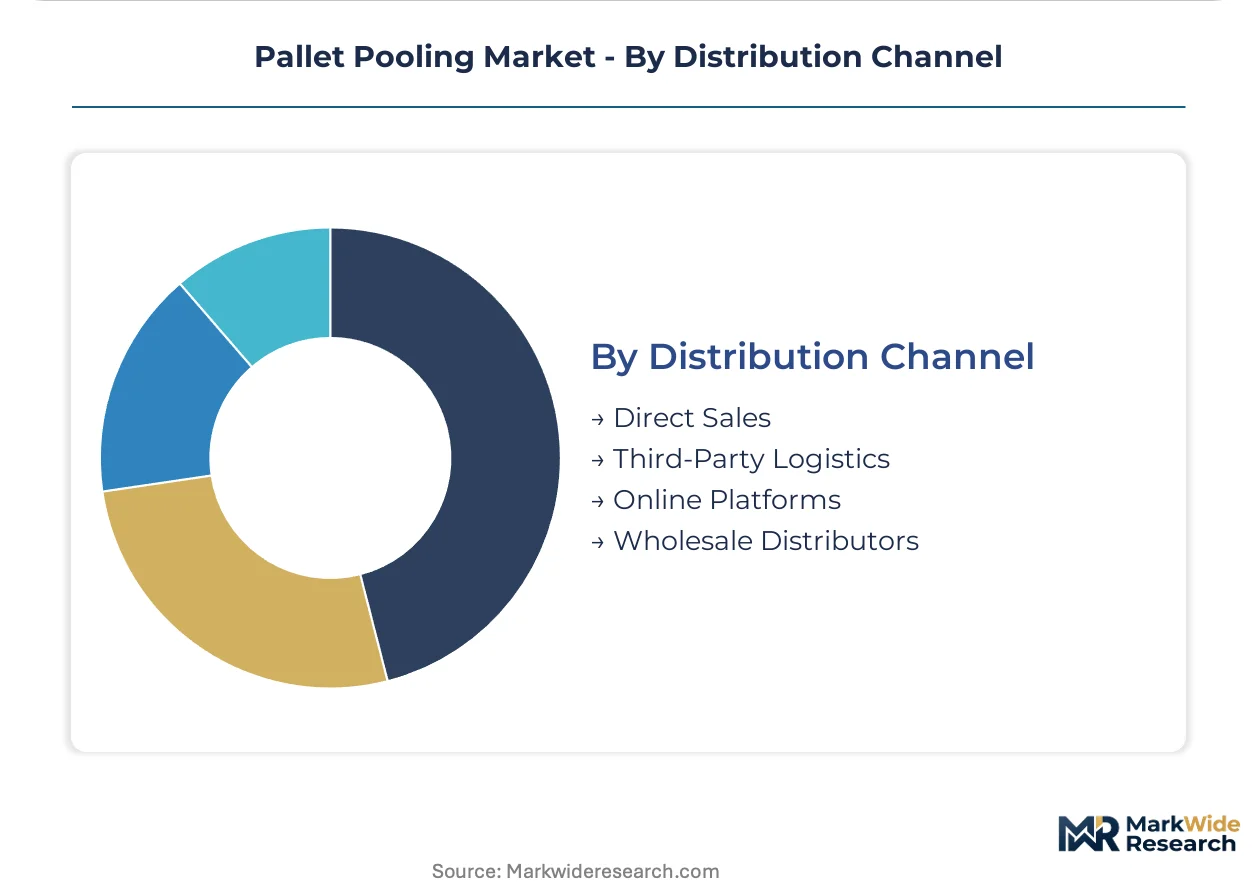
Distribution Channel:
Channel selection reflects customer scale, geographic coverage requirements, and integration depth with existing logistics relationships.
- Third-Party Logistics:Large-scale 3PLs concentrate procurement authority through integrated quality management systems. Pharmaceutical logistics providers bundle pallet pooling with warehousing and transportation, leveraging sanitation guarantees as supplier selection criteria.
- Direct Sales:National account relationships with major retailers and manufacturers enable customized service terms. Depot-based circulation systems in dense logistics corridors support direct operator engagement with high-volume shippers.
- Online Platforms:Digital marketplaces match spot demand with available pallet supply for irregular shipment patterns.
- Wholesale Distributors:Regional intermediaries extend coverage into rural markets where operator-owned depots prove uneconomical.
Transaction volume flows through Third-Party Logistics; channel development is gaining share fastest in Direct Sales as operators consolidate national accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pallet pooling infrastructure concentrates where manufacturing density and retail consolidation intersect. Consumption outpaces domestic production in several emerging logistics corridors, creating cross-border equipment flows.
Germany
Automotive tier-1 suppliers in the Rhine-Ruhr corridor drive standardized pooling adoption for just-in-time delivery protocols. EU Green Deal circular economy mandates accelerate plastic pallet recycling requirements. Stuttgart and Wolfsburg manufacturing clusters favor closed-loop networks that interchange seamlessly between suppliers and OEM assembly plants.
United States
Food and beverage distributors with high inventory velocity deploy RFID-embedded pallets at scale. FDA sanitation protocols for pharmaceutical logistics create certification demand for hygienic plastic platforms. Chicago and Dallas logistics hubs anchor depot-based circulation systems serving national retail networks.
China
E-commerce fulfillment centers expand pooling adoption to reduce packaging waste in last-mile distribution. SAMR logistics equipment standards govern pallet load performance certification. Yangtze River Delta manufacturing clusters generate equipment demand that outpaces domestic pooling infrastructure capacity.
France
Extended producer responsibility legislation imposes end-of-life recycling obligations on pooling operators. ECHA REACH compliance requirements for wood treatment biocides push manufacturers toward polyethylene alternatives. Paris Basin fresh produce logistics drives closed-loop service adoption across retail grocery networks.
Netherlands
Benelux retail consolidation concentrates demand for standardized pooling dimensions across fresh produce supply chains. EU packaging waste directives mandate recycled content minimums for plastic logistics equipment. Rotterdam port logistics cluster serves as equipment interchange point for cross-border European distribution.
Pallet Pooling Market Key Industry Players
The competitive structure tilts toward network-scale operators with dense depot coverage. Consolidation among pooling providers creates tiered service differentiation between global platform operators and regional specialists. Three archetypes dominate: integrated logistics conglomerates with captive pooling divisions, pure-play equipment pooling specialists, and packaging manufacturers extending into rental services. Geographic expansion and IoT-enabled asset tracking represent the dominant competitive moves.
Within the integrated conglomerate tier, Brambles Limited anchors global operations through its CHEP network, while China Merchants Loscam International Holdings represents Asia-Pacific market presence. Rehrig Pacific Company occupies a position among North American specialists with proprietary plastic pallet designs. These three exemplify how scale and regional density determine competitive positioning in asset-heavy pooling markets.
| Leading Market Players |
|---|
| China Merchants Loscam International Holdings |
| Rehrig Pacific Company |
| Brambles Limited (CHEP) |
| Contraload NV |
| Euro Pool Group |
| PECO Pallet |
| IFCO Systems |
| Schoeller Allibert Services |
| iGPS Logistics |
| Others |
Cost & Logistics Intelligence
EU Green Deal circular economy mandates gate both qualified supply and premium-tier pricing access, as operators must certify recycled content percentages through third-party verification to serve German automotive and French retail accounts. Plastic pallet manufacturers with established recovery infrastructure capture pricing power, while uncertified competitors face exclusion from high-margin pharmaceutical and fresh produce contracts.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects extended FDA sanitation validation timelines that compress supplier throughput. Three-tier pricing structure across certified hygienic, standard food-grade, and economy wooden tiers separates buyers by compliance burden and rotation velocity. Cost-down pressure on untreated wooden pallets accelerates because REACH wood treatment biocide restrictions raise chemical compliance costs. Automotive tier-1 suppliers show lowest price sensitivity due to just-in-time delivery penalties, while commodity freight brokers in Eastern Europe resist pooling premiums.
Supply Chain Analysis
Depot-based circulation networks handle high-velocity food and beverage demand through dense logistics corridors in Germany, the United States, and the Netherlands. Raw material inputs draw from high-density polyethylene resin markets, hardwood timber certification programs, and galvanized steel coil production. Single-source vulnerability concentrates in resin feedstock exposed to crude oil index volatility. Distribution runs through third-party logistics providers that bundle pallet pooling with warehousing and transportation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet pooling infrastructure rewards scale economics, and EU extended producer responsibility legislation is forcing sub-scale operators into asset sales or regional exit. Consolidation favors depot-dense networks with integrated sanitation certification.
For Market Incumbents: Extend RFID-enabled asset tracking deployment to compress invoice reconciliation cycles and reduce unaccounted losses in multi-party pharmaceutical supply chains. Acquire regional depot networks in Southern Europe to close coverage gaps outside established Benelux operations. Vertical integration into plastic recovery facilities secures post-consumer resin supply for EU Green Deal compliance deadlines. For New Entrants and Emerging Players: Extended producer responsibility legislation in France and Italy opens a window for specialized recycling operators to enter pooling markets through circular material certification. Target fresh produce logistics in Southern European retail networks where closed-loop services remain underdeveloped outside established operations. Lead with IoT-enabled pallet management software that unifies physical circulation with customer ERP systems. For Investors and Strategic Acquirers: Outcome-based contract proliferation in pharmaceutical logistics is the leading indicator that quality-integrated 3PLs will consolidate procurement authority over the next decade. Acquire mid-scale pooling operators with established sanitation infrastructure and dense depot coverage in automotive supplier corridors. Watch for FDA validation timeline compression as the signal that hygienic pallet supply shortages will intensify.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Expansion | Dense service points in Germany's Rhine-Ruhr corridor enable just-in-time automotive supplier coverage. |
| Plastic Recovery Infrastructure | Post-consumer resin certification secures EU Green Deal compliance for pooled equipment fleets. |
| RFID Telemetry Integration | Real-time asset location unification with enterprise resource planning systems reduces unaccounted losses. |
| Sanitation Certification Investment | FDA-validated hygienic pallet production captures pharmaceutical premium pricing tiers. |
| Managed Services Portfolio | Full outsourcing integration with customer ERP systems displaces flat-rate per-trip pricing models. |
Research Approach
Trade association filings, customs and logistics equipment import records, and regulatory agency certification databases formed the secondary backbone of this analysis. Primary interviews with pooling network operations directors, pharmaceutical logistics procurement managers, automotive tier-1 supplier material handling leads, and fresh produce retail category buyers validated segment assumptions. Bottom-up and top-down triangulation cross-checked equipment fleet counts against end-user industry shipment volumes.
Bottom-up modeling built forecasts from individual country depot network capacities, pallet rotation velocity assumptions, and service model pricing structures across the analysis window. Segmentation dimensions included pallet material type, service contract structure, end-user industry vertical, and geographic logistics corridor density. CAGRs derived from equipment stock growth rates and revenue per pallet circulation metrics. Forecast inputs incorporated EU Green Deal compliance timeline assumptions and FDA sanitation protocol adoption curves.
The model assumes a particular technology adoption path for RFID-enabled asset tracking; alternative pathways for GPS-telemetry integration would alter the outlook for real-time visibility premium capture. Forecasts reflect base-case assumptions regarding resin price stability and depot network expansion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
GCC Pallet Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market