
 Pallet Collar Market | 2026-2036
Pallet Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Collar Market Analytics
Aftermarket service revenue from pallet pooling and refurbishment is reshaping margin distribution in the Pallet Collar Market. CHEP (Brambles Limited) leverages its global pooling infrastructure to sustain recurring fee streams across closed-loop supply chains. Falkenhahn AG anchors German manufacturing demand through specialized steel collar production for heavy industrial loads. ORBIS Corporation competes in North American food and beverage logistics with plastic collar systems designed for hygienic washdown cycles.
Pallet collars are foldable, stackable frame structures—typically constructed from hinged wooden boards, injection-molded plastic, or formed steel—that mount atop standard pallets to create adjustable-height containment for loose or irregular loads. Wooden collars, governed by ISPM-15 heat-treatment standards for phytosanitary compliance, dominate international shipment corridors where customs inspections are frequent. Plastic collars represent the fastest-expanding product category, driven by pharmaceutical and fresh-produce sectors demanding moisture resistance and consistent dimensional stability across temperature zones. Application demand in industrial packaging carries the deepest margin pools, as manufacturers of precision components specify custom sizes with integrated dunnage and tracking features.
Regulatory frameworks including the EU Packaging and Packaging Waste Regulation, ISO 8611 pallet testing standards, and FDA sanitary transport rules under the Food Safety Modernization Act collectively elevate compliance costs while privileging certified, traceable collar suppliers over commodity producers. Stakeholders must monitor evolving extended-producer-responsibility thresholds and material-recovery targets, as these will determine whether pooling models or single-use alternatives capture incremental volume in regulated jurisdictions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to abandon single-use formats and invest in reusable, returnable pooling infrastructure that collapses total cost of ownership across multi-trip cycles.
Growth Catalysts
- ISPM-15 Heat-Treatment Mandates:Phytosanitary compliance requirements for wooden packaging materials in cross-border trade channel demand toward certified, trackable collar suppliers capable of documentation at customs checkpoints.
- Automotive Component Logistics:German OEMs and tier suppliers operate dense pallet-pooling networks for just-in-time delivery of precision parts, sustaining collar utilization rates above other industrial verticals.
- Fresh-Produce Cold Chains:Moisture-resistant plastic collars are displacing wood in European temperature-controlled distribution, driven by washdown hygiene protocols and dimensional stability across freezing cycles.
Market Restraints
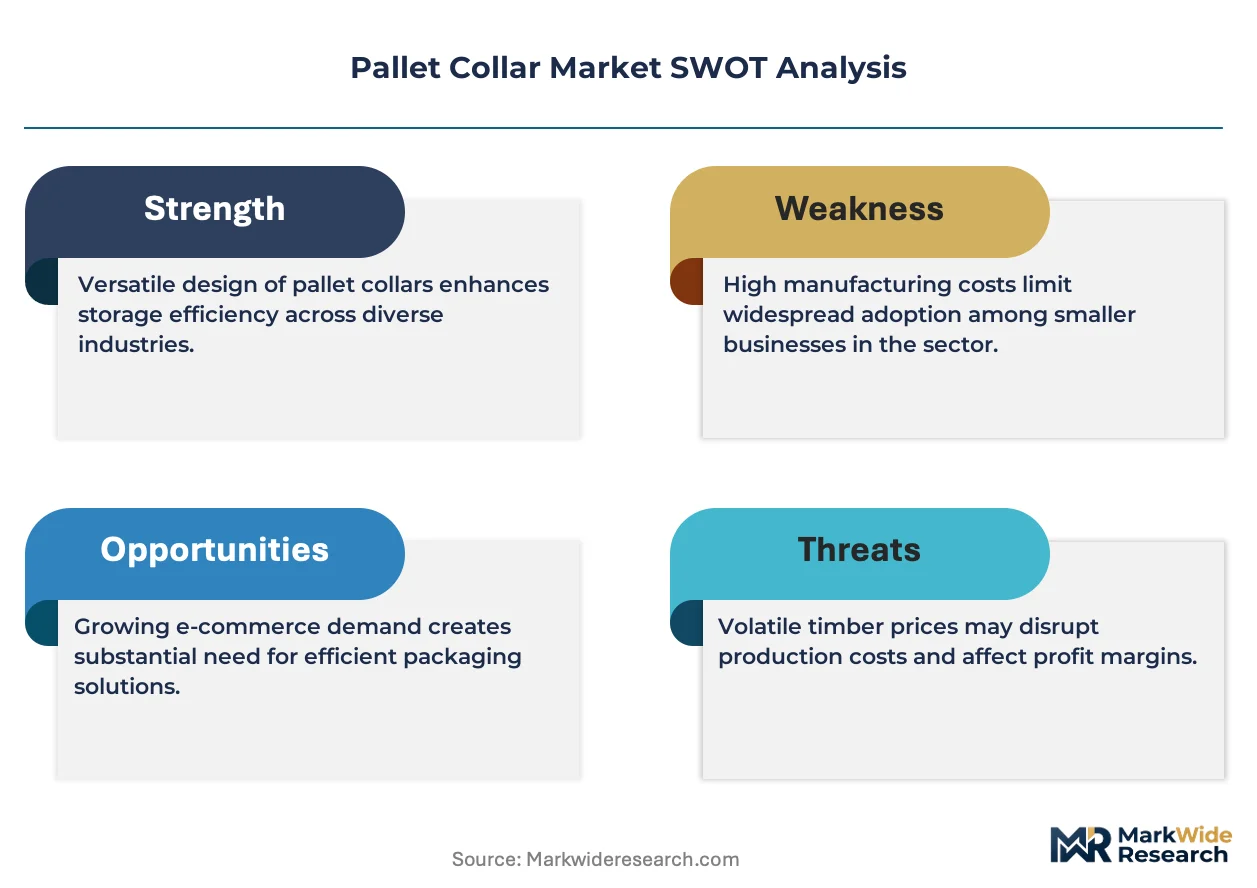
- Steel Input Volatility:Formed steel collar producers face margin compression from scrap metal price swings and energy-intensive galvanizing processes tied to European natural gas benchmarks.
- Substitution by Slip Sheets:Lightweight, single-use slip sheets with push-pull attachments are capturing volume in high-velocity consumer goods flows where return logistics prove uneconomical.
- REACH Chemical Compliance:Plastic collar additives including flame retardants and UV stabilizers face registration burdens and substance restrictions that elevate formulation costs versus untreated wood alternatives.
Strategic Opportunities
- Pharmaceutical Serialization Convergence:RFID-embedded plastic collars combined with track-and-trace mandates under the EU Falsified Medicines Directive create premium positioning for integrated packaging-data solutions.
- Indian Food Processing Expansion:Cold-chain infrastructure investments under the government's Pradhan Mantri Kisan SAMPADA Yojana scheme open adoption corridors for ISPM-15 compliant wooden collars in export-oriented horticulture.
- Reverse Logistics Platform Integration:Digital freight matching and empty-mile reduction algorithms enable independent pooling operators to compete against incumbents' captive fleet networks.
Industry Challenges
- ISPM-15 Certification Backlogs:Heat-treatment facility capacity constraints and inspector shortages delay market entry for new wooden collar suppliers in high-demand export corridors.
- Legacy ERP Integration:Pooling operators struggle to synchronize collar tracking data with shipper warehouse management systems, creating reconciliation friction in multi-party supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Collar Market |
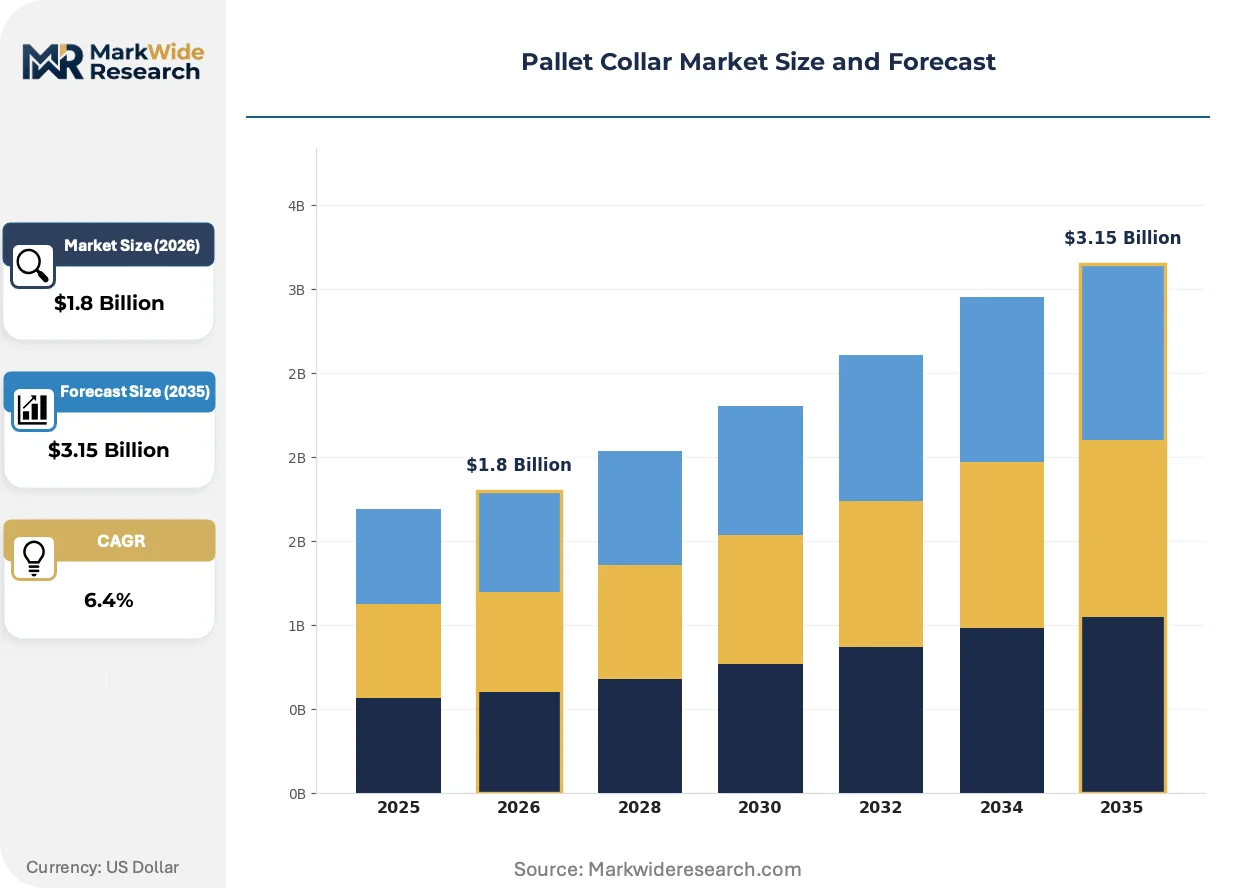
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Collars, Plastic Collars, Metal Collars, Composite Collars Application: Food Storage, Industrial Packaging, Retail Display, Agricultural Use End User: Manufacturers, Retailers, Distributors, Farms Size: Standard, Heavy Duty, Custom Sizes, Stackable |
| Companies Covered | ORBIS Corporation, Falkenhahn AG, CHEP (Brambles Limited), Craemer GmbH, NEFAB Group, UFP Industries, Inc., Mondi Plc, PalletBiz, EXZOD India Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Collar Market Evolving Landscape
Embedded sensor technology and blockchain verification protocols are compressing trust costs in multi-party pooling arrangements, while regulatory pressure on packaging waste accelerates format standardization across competing systems.
RFID and NFC-enabled smart collars are digitizing asset tracking and condition monitoring across pharmaceutical and high-value industrial supply chains. Third-party logistics providers in the Benelux region are deploying these systems at scale, capturing temperature excursion data and impact events in real time. This visibility layer is digitizing risk allocation between shippers and carriers, shifting liability frameworks and insurance pricing toward outcome-based models.
The EU Green Deal's packaging waste reduction targets are tightening extended producer responsibility thresholds and material recovery mandates. Industrial users now face compliance costs that privilege certified pooling operators over single-use purchases. Food and beverage manufacturers in Germany and France are responding by consolidating supplier relationships around vertically integrated pooling providers capable of closed-loop documentation.
Shippers are unbundling collar procurement from freight contracts and establishing direct pooling agreements with specialized asset managers. This disintermediation of traditional packaging distributors is most pronounced in automotive supply chains, where OEMs negotiate multi-year collar availability guarantees separate from transport rates. The shift compresses distributor margins while rewarding asset-light pooling platforms with dense network coverage.
Pallet Collar Market Segmentation
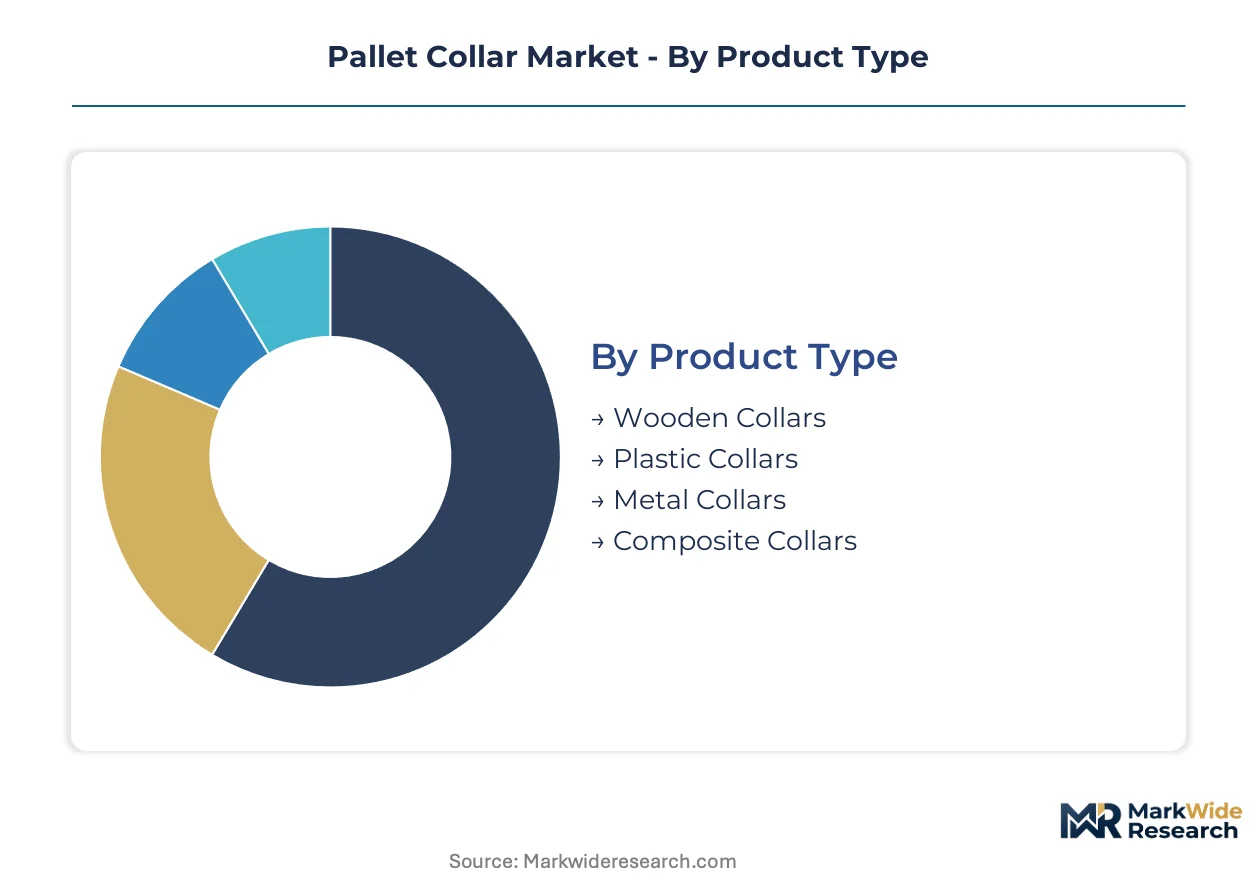
Pallet collar segmentation reveals divergent margin structures across material formats and application verticals. Aftermarket service intensity varies dramatically by product category, with pooling-dependent segments generating recurring revenue streams that reshape lifetime value calculations for asset managers.
Product Type:
After-sales service intensity peaks in metal and plastic collar categories, where refurbishment cycles and RFID tracking integration create sustained fee opportunities beyond initial hardware sales.
- Wooden Collars:Hinged pine or hardwood boards bound by galvanized steel corners, governed by ISPM-15 heat-treatment mandates for phytosanitary compliance. Demand concentrates in German automotive export corridors where customs documentation requirements channel volume toward certified suppliers with heat-treatment facility ownership.
- Plastic Collars:Injection-molded polypropylene or HDPE structures featuring interlocking corner posts and ventilated side panels. Fresh-produce cold chains across the Netherlands and Belgium are displacing wood with these moisture-resistant formats, driven by washdown hygiene protocols and dimensional stability across freezing cycles.
- Metal Collars:Formed steel with welded hinge assemblies, specified for heavy industrial loads exceeding 1,500 kg per unit. German precision component manufacturers anchor demand through captive pooling networks.
- Composite Collars:Hybrid constructions combining wood-plastic cores with metal reinforcement corners. Emerging adoption in pharmaceutical serialization applications where RFID embedding meets structural durability requirements.
Wooden collars hold the largest share; momentum sits with plastic collars.
Application:
Cost tier stratification separates premium integrated pooling contracts from commodity spot purchases across application verticals.
- Food Storage:Temperature-controlled distribution networks for dairy, meat, and prepared meals demand moisture-resistant collars with hygienic surface finishes. French and German cold-chain operators specify plastic formats with embedded tracking for regulatory traceability.
- Industrial Packaging:Precision component protection for automotive, aerospace, and electronics sectors. Custom-sized collars with integrated dunnage and shock-absorbing inserts command premium positioning in German OEM supply chains.
- Retail Display:Lightweight, collapsible formats for in-store merchandising of bulk goods. Supermarket chains in Spain and Italy favor standardized dimensions compatible with existing pallet footprints.
- Agricultural Use:Harvest collection and field-side staging for fresh produce. Wooden collars dominate export-oriented horticulture in India under Pradhan Mantri Kisan SAMPADA Yojana cold-chain investments.
Industrial packaging commands premium pricing; food storage is expanding most quickly.
End User:
Procurement sophistication varies sharply by customer type, with manufacturers driving standardization while farms tolerate higher format fragmentation.
- Manufacturers:Automotive and electronics producers negotiate multi-year collar availability guarantees separate from freight contracts, consolidating supplier relationships around vertically integrated pooling providers.
- Retailers:Grocery and mass-merchandise chains balance purchase cost against reverse logistics complexity, with dense network coverage determining pooling partner selection.
- Distributors:Third-party logistics providers in the Benelux region deploy smart collar systems at scale, capturing temperature and impact data for risk allocation between shippers and carriers.
- Farms:Smallholder and commercial agricultural operations prioritize acquisition cost over lifecycle tracking, sustaining spot-market demand for untreated wooden formats.
Manufacturers hold the largest share; momentum sits with distributors.
Size:
Volume concentration in standard dimensions contrasts with margin concentration in custom specifications.
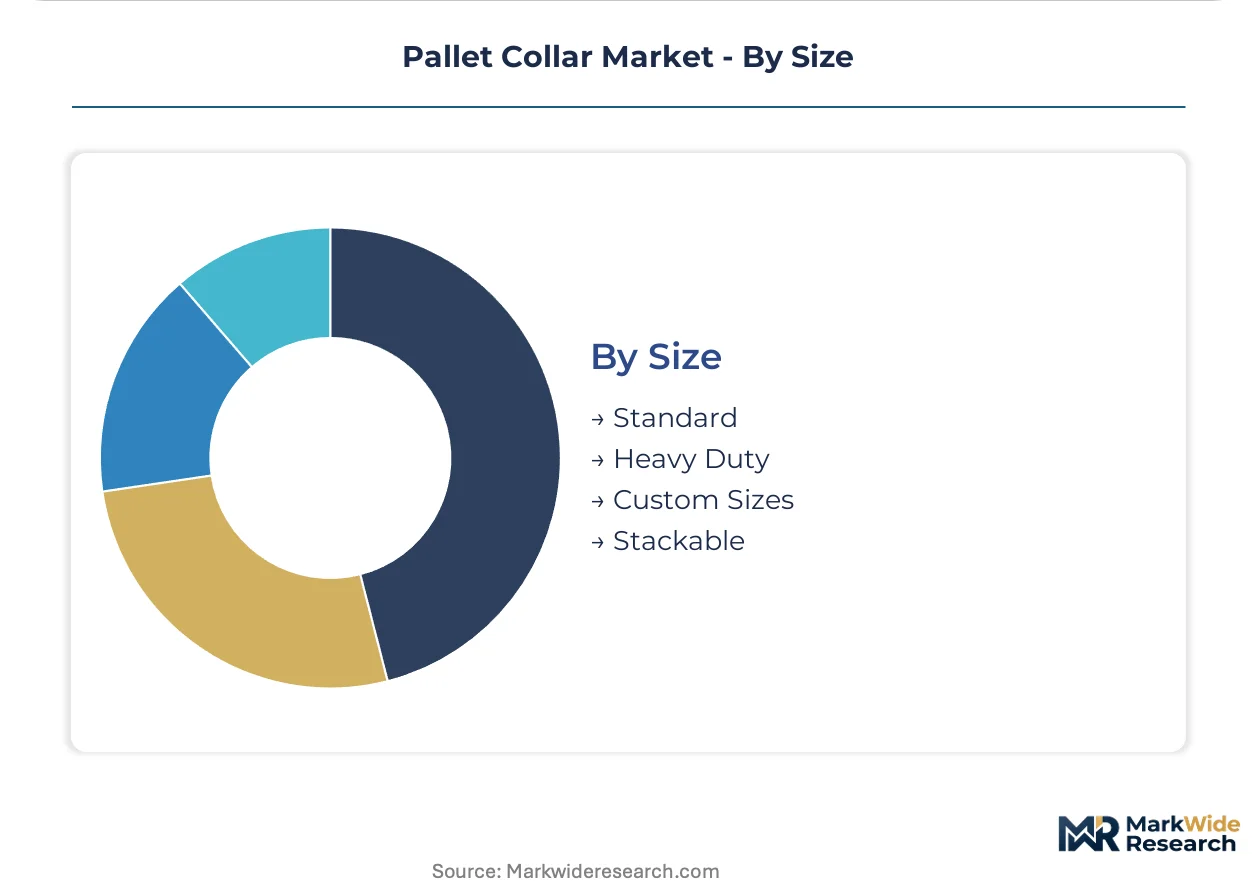
- Standard:800×1200 mm and 1000×1200 mm footprints matching EUR and ISO pallet bases. European pooling networks achieve maximum asset utilization through format uniformity.
- Heavy Duty:Reinforced corner posts and thicker board sections for loads exceeding standard ratings. German steel collar producers specialize in this tier for automotive component logistics.
- Custom Sizes:Non-standard dimensions with integrated dunnage, dividers, or cushioning for irregular loads. Aerospace and precision instrument manufacturers specify these for damage-sensitive shipments.
- Stackable:Nesting designs with reduced collapsed height for empty return transport. Pooling operators optimize fleet efficiency through stackable plastic formats.
Standard sizes hold the largest share; custom sizes show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive buyers accept premium pooling contracts with embedded tracking, while Indian agricultural users prioritize acquisition cost over lifecycle services.
Germany
Automotive OEMs and tier suppliers operate dense just-in-time networks requiring precision component protection. The EU Packaging and Packaging Waste Regulation mandates reusable formats, elevating certified pooling providers. Stuttgart and Wolfsburg industrial corridors sustain the deepest collar utilization rates in Europe.
United States
Food and beverage logistics drive plastic collar adoption for hygienic washdown compliance. FDA rules under the Food Safety Modernization Act elevate sanitary transport documentation burdens. Chicago and Dallas distribution hubs concentrate third-party logistics deployment of smart tracking systems.
Netherlands
Fresh-produce cold chains displace wood with moisture-resistant plastic formats across Rotterdam and Venlo logistics zones. REACH chemical compliance elevates formulation costs for additive-dependent plastics. Benelux third-party providers deploy RFID-enabled collars at scale for temperature monitoring.
India
Export-oriented horticulture under the Pradhan Mantri Kisan SAMPADA Yojana cold-chain investments channels ISPM-15 wooden collar demand. DGFT phytosanitary documentation requirements favor certified heat-treatment suppliers. Maharashtra and Karnataka agricultural processing clusters anchor adoption growth.
France
Dairy and prepared meal distribution networks specify plastic collars with embedded traceability for regulatory compliance. The EU Green Deal packaging waste targets consolidate supplier relationships around vertically integrated pooling operators. Lyon and Lille temperature-controlled logistics hubs drive format standardization.
Pallet Collar Market Competitive Landscape
Capability concentration sits with specialized fabricators commanding custom specification premiums; scale advantage sits with global pooling operators amortizing fixed costs across multi-trip cycles. The market structures around three archetypes: asset-heavy pooling networks, precision metal fabricators, and hygiene-focused plastics specialists. Dominant competitive moves include backward integration into heat-treatment certification capacity and geographic expansion through digital freight matching platforms.
Within the pooling infrastructure tier, CHEP (Brambles Limited) exemplifies scale-driven network economics, while Falkenhahn AG represents German precision metal specialization for heavy industrial loads. ORBIS Corporation occupies a position among North American hygiene-focused plastics fabricators serving food and beverage logistics. These three anchors illustrate how competitive positioning diverges across material formats and service intensity models.
| Leading Market Players |
|---|
| ORBIS Corporation |
| Falkenhahn AG |
| CHEP (Brambles Limited) |
| Craemer GmbH |
| NEFAB Group |
| UFP Industries, Inc. |
| Mondi Plc |
| PalletBiz |
| EXZOD India Private Limited |
| Others |
Value Network & Pricing Analysis
Steel input volatility determines both tiered pricing spreads and supply chain configuration in the Pallet Collar Market. Scrap metal price swings and energy-intensive galvanizing processes tied to European natural gas benchmarks compress margins for formed steel collar producers while channeling procurement toward certified pooling operators with captive heat-treatment capacity.
Pricing Analysis
Aftermarket service revenue from refurbishment cycles and RFID tracking integration drives lifetime value across plastic and metal collar categories. Three-tier pricing structure across premium, standard, and economy levels separates integrated pooling contracts with embedded traceability from commodity spot purchases of untreated wooden formats. Cost compression in standard wooden collars is intensifying because REACH chemical compliance elevates formulation expenses for plastic additives versus heat-treated wood alternatives. Smallholder agricultural operations in India exhibit the highest price sensitivity, while German automotive OEMs accept premium positioning for custom specifications with integrated dunnage.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from large pooling operators are restructuring working capital requirements for tier-2 fabricators. Manufacturing concentration rests on Germany for precision steel fabrication, China for injection-molded plastic components, and the Baltic states for ISPM-15 certified wooden board production. Raw material dependencies draw from European pine and hardwood lumber, polypropylene and HDPE resin, and galvanized steel sheet. Single-source vulnerability runs through heat-treatment facility capacity constraints that delay customs documentation for new wooden collar suppliers. Distribution runs through third-party logistics providers in the Benelux region deploying smart collar systems at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pallet Collar Market is approaching a platform-economics inflection as digital freight matching and empty-mile reduction algorithms enable independent pooling operators to compete against incumbents' captive fleet networks.
For Market Incumbents: Pre-empt disintermediation by automotive OEMs negotiating multi-year collar availability guarantees separate from transport contracts through backward integration into heat-treatment certification capacity. Consolidate supplier relationships around vertically integrated pooling providers capable of closed-loop documentation under the EU Packaging and Packaging Waste Regulation. For New Entrants and Emerging Players: Indian agricultural processing clusters in Maharashtra and Karnataka offer the most penetrable white-space target, where export-oriented horticulture under the Pradhan Mantri Kisan SAMPADA Yojana channels ISPM-15 compliant wooden collar demand. Enter through certified heat-treatment partnerships with DGFT-registered facilities, then expand into temperature-controlled distribution networks for dairy and prepared meals. For Investors and Strategic Acquirers: The EU Green Deal's packaging waste reduction targets reshape the acquisition landscape by privileging certified pooling operators over single-use commodity producers. Target asset-light pooling platforms with dense Benelux network coverage and embedded sensor technology capabilities. Watch for consolidation signals when independent operators achieve critical mass in digital freight matching algorithms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Certification | Captive ISPM-15 capacity secures customs documentation advantages in German export corridors. |
| RFID-Enabled Smart Collar Deployment | Real-time temperature monitoring shifts liability frameworks for Benelux pharmaceutical logistics. |
| Digital Freight Matching Platform Launch | Empty-mile reduction algorithms compete against CHEP's captive fleet network economics. |
| Composite Collar Development for Pharmaceutical Serialization | Hybrid wood-plastic-metal constructions meet EU Falsified Medicines Directive track-and-trace mandates. |
| Geographic Expansion into Indian Cold-Chain Infrastructure | Pradhan Mantri Kisan SAMPADA Yojana investments open adoption corridors for certified wooden collars. |
Research Methodology
The analysis maps wooden collar heat-treatment certification tiers, plastic collar injection-molding specifications, metal collar welded assembly standards, and composite hybrid constructions, each validated through pooling network operations directors, automotive tier-1 supplier procurement managers, third-party logistics technology heads, and agricultural export cooperative managers. Primary interview insights triangulate against customs and trade data from Eurostat and DGFT, SEC filings from listed packaging companies, ISO 8611 pallet testing standard documentation, and EU regulatory impact assessments. Bottom-up unit economics from individual collar fabrication facilities reconcile with top-down market sizing from regional logistics infrastructure investments.
The forecast framework holds steel scrap price volatility, REACH chemical compliance thresholds, and ISPM-15 inspector capacity within observed ranges while varying automotive production cycles, fresh-produce cold-chain expansion rates, and pharmaceutical serialization adoption curves. Segmentation dimensions span material format, application vertical, end-user procurement sophistication, and size specification tier across the projection horizon. CAGRs derive from logistic intensity coefficients by industry and pooling penetration rates by geography. Industry-specific inputs include European automotive just-in-time delivery frequency and Indian horticulture export growth trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native pooling platforms or unexpected REACH substance restrictions would shift outcomes. Macroeconomic deviation in steel and resin input costs, regulatory acceleration of extended producer responsibility thresholds, or technological breakthroughs in biodegradable composite materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Wooden Pallets Market