
 Asia-Pacific Lumber Pallet Market | 2026-2036
Asia-Pacific Lumber Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lumber Pallet Market Outlook
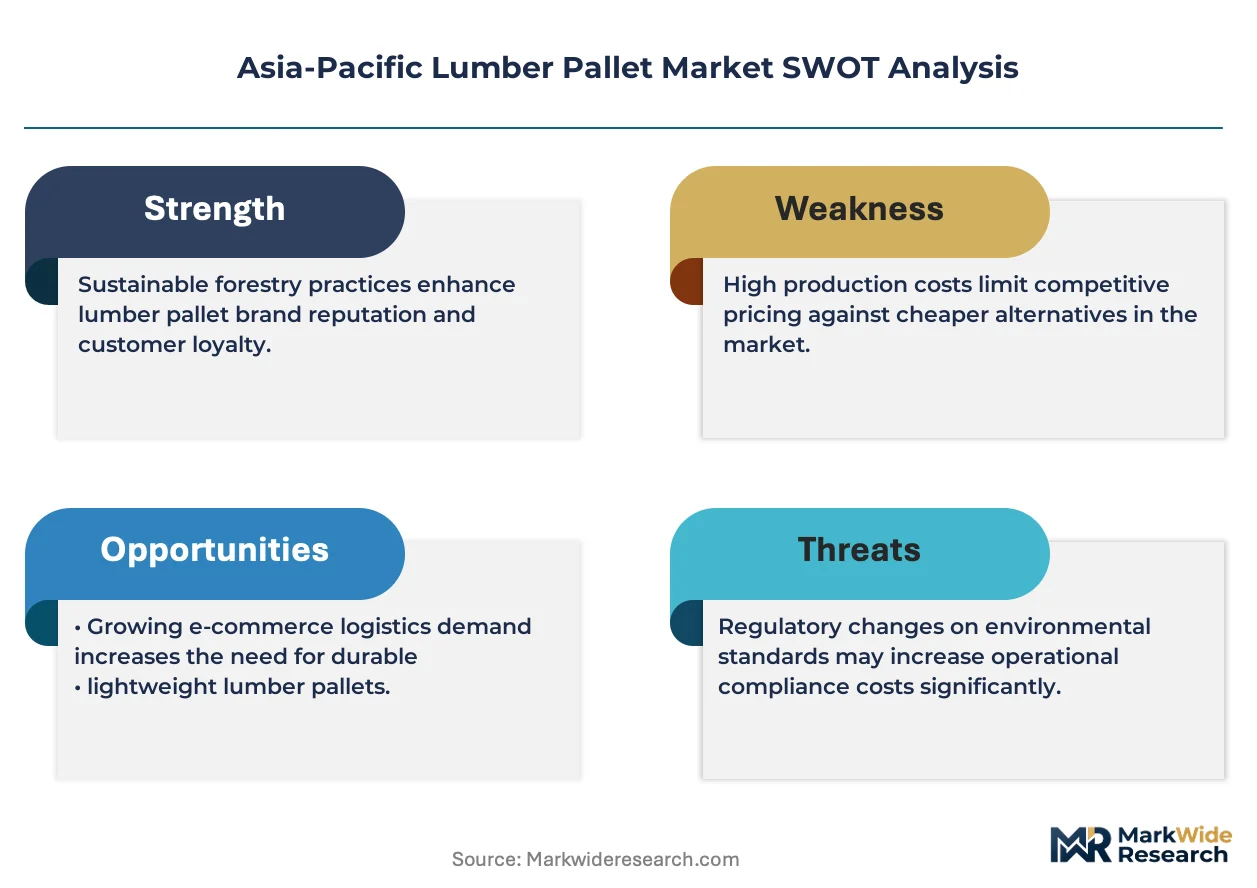
ISPM-15 heat treatment certification is reorganizing supplier hierarchies across the Asia-Pacific lumber pallet landscape. Brambles Limited leverages its pooled pallet network to dominate Australasian grocery supply chains. Loscam International Holdings Co., Ltd. anchors Greater China operations through captive hardwood sourcing and depot density. UFP Industries, Inc. competes via specialty-grade pine pallet production for electronics exporters.
Lumber pallets are load-bearing platforms constructed from sawn timber, typically pine or oak, assembled with nails or staples to dimensions such as 1200 mm by 1000 mm for ISO compliance; they function as the foundational interface between unitized cargo and material-handling equipment across manufacturing and logistics ecosystems. Stringer pallets retain volume leadership in warehouse storage applications due to lower material intensity and faster production cycles, while block pallets capture premium positioning in four-way entry scenarios where forklift maneuverability reduces terminal dwell time. Pine material grades sustain cost advantages across shipping applications, though oak variants penetrate construction end-use segments where load ratings exceed two metric tons.
China's SAMR enforces GB standards for pallet dimensional interoperability, while Australia's Department of Agriculture mandates ISPM-15 compliance for all imported wood packaging. India's BIS certification for engineered wood products adds a secondary compliance layer for domestic manufacturers serving food and beverage exporters. Stakeholders must monitor diverging national treatment standards and preemptively align heat-treatment capacity with destination-country phytosanitary protocols.
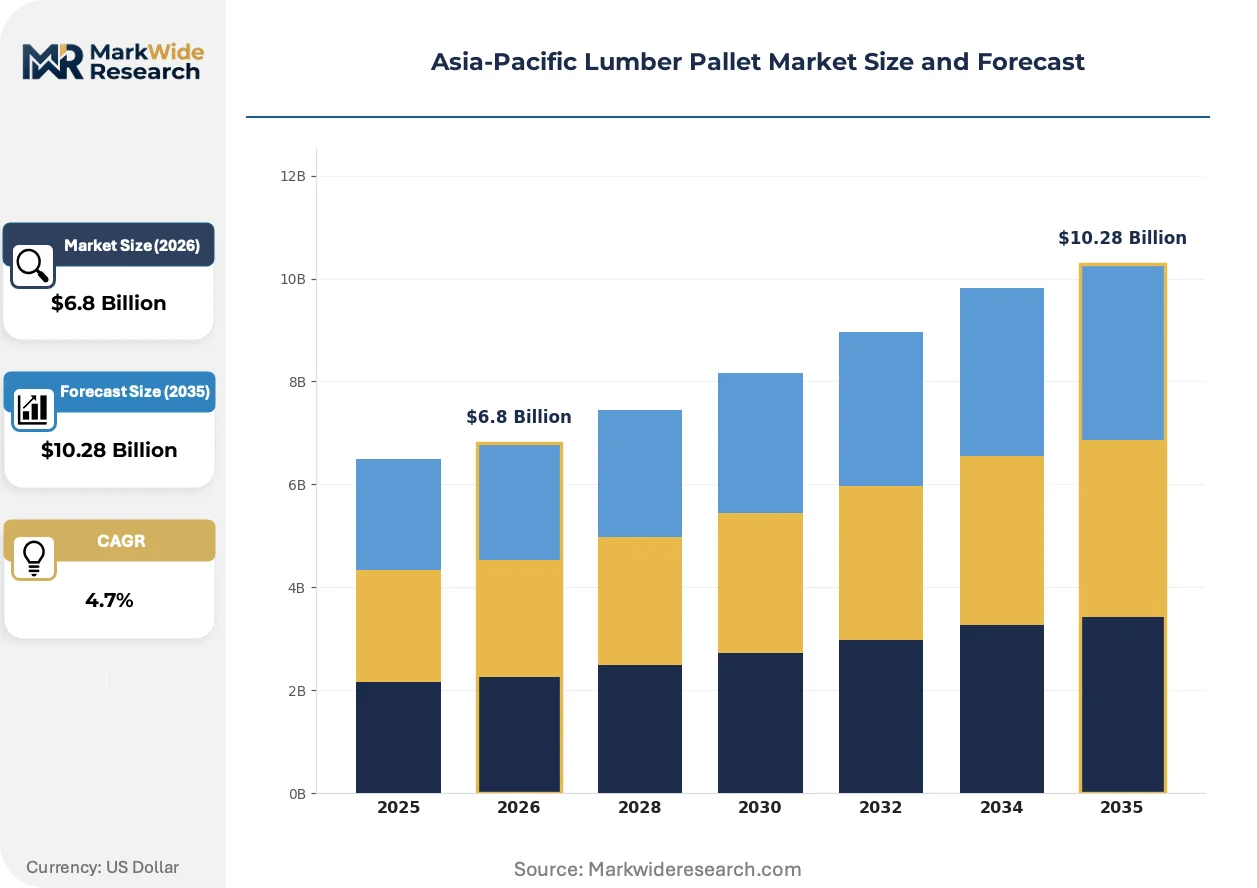
Market Dynamics
ISPM-15 heat treatment mandates are compressing supplier margins while redrawing cross-border trade corridors across Southeast Asia and Oceania. Australia's Department of Agriculture enforcement and China's SAMR dimensional standards create divergent compliance burdens that favor pooled pallet networks over single-use alternatives.
Growth Catalysts
- E-commerce fulfillment density:Vietnam's manufacturing corridors and Indonesia's logistics hubs drive standardized stringer pallet adoption for automated warehouse systems.
- GB/T 2934 interoperability:China's SAMR enforcement of unified pallet dimensions accelerates cross-docking efficiency across the Yangtze River Delta manufacturing belt.
- Pharmaceutical export compliance:India's pharmaceutical export zones generate engineered wood pallet demand meeting BIS certification and destination-country phytosanitary protocols.
Market Restraints
- Hardwood supply concentration:Captive sourcing from Malaysian and Indonesian timber concessions limits supplier flexibility and amplifies price volatility during monsoon disruptions.
- Heat treatment capex barriers:ISPM-15 certification requires kiln infrastructure investments that exclude small-scale sawmills from export-qualified production.
- Plastic pallet substitution:Nestable plastic alternatives penetrate food-grade applications where moisture resistance and washability outweigh lumber's cost advantage.
Strategic Opportunities
- India's underpenetrated cold chain:Temperature-controlled pharmaceutical distribution lacks standardized pallet infrastructure, creating first-mover positioning for ISPM-15-certified suppliers.
- Pooled network expansion:Asset-light pooling models reduce capital intensity for grocery retailers across Australasia while capturing recurring revenue streams.
- RFID-embedded pallet convergence:Track-and-trace integration with warehouse management systems enables outcome-based logistics contracts for electronics exporters.
Industry Challenges
- Treatment certification timelines:ISPM-15 audit backlogs at Australian biosecurity checkpoints delay export shipments and compress working capital cycles.
- Skill gaps in automated repair:Depot networks lack technicians trained in robotic nail placement and structural integrity assessment for pooled asset refurbishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lumber Pallet Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Pallets, Stringer Pallets, Double-Face Pallets, Four-Way Pallets Material: Pine, Oak, Birch, Softwood Usage Type: Warehouse Storage, Shipping, Retail Display, Transportation End User: Food & Beverage, Home Appliances, Electronics, Construction |
| Companies Covered | Brambles Limited, UFP Industries, Inc., Menasha Corporation, Loscam International Holdings Co., Ltd., PGS Group, Greif, Millwood, Inc., Rehrig Pacific Holding, Inc., Stora Enso Oyj, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lumber Pallet Market Strategic Shifts
Digital traceability and material substitution are fragmenting traditional pallet procurement patterns across Asia-Pacific logistics networks. Three developments merit attention.
Radio-frequency identification (RFID) tagging of lumber pallets is bifurcating the market between premium trackable assets and commodity single-use alternatives. Electronics exporters in South Korea and Taiwan adopt chip-embedded block pallets for high-value component shipments. This technology compression forces pooled network operators to justify hardware investments against per-trip tracking premiums.
Australia's Department of Agriculture has tightened ISPM-15 inspection protocols for all incoming wood packaging from January enforcement cycles. The industrial consequence is a 15-20% rejection rate at Brisbane and Sydney ports for non-compliant Asian suppliers. Vietnamese and Thai exporters are responding by pre-certifying through accredited third-party treatment facilities rather than port-of-entry fumigation.
Buyers in Japan's automotive supply chain now specify pallet-as-a-service contracts replacing outright purchase models. Tier-1 suppliers to Toyota and Honda lease standardized assets with embedded maintenance and rotation guarantees. This procurement evolution concentrates volume with Brambles and Loscam depot networks while marginalizing independent sawmill direct sales.
Asia-Pacific Lumber Pallet Market Segmentation
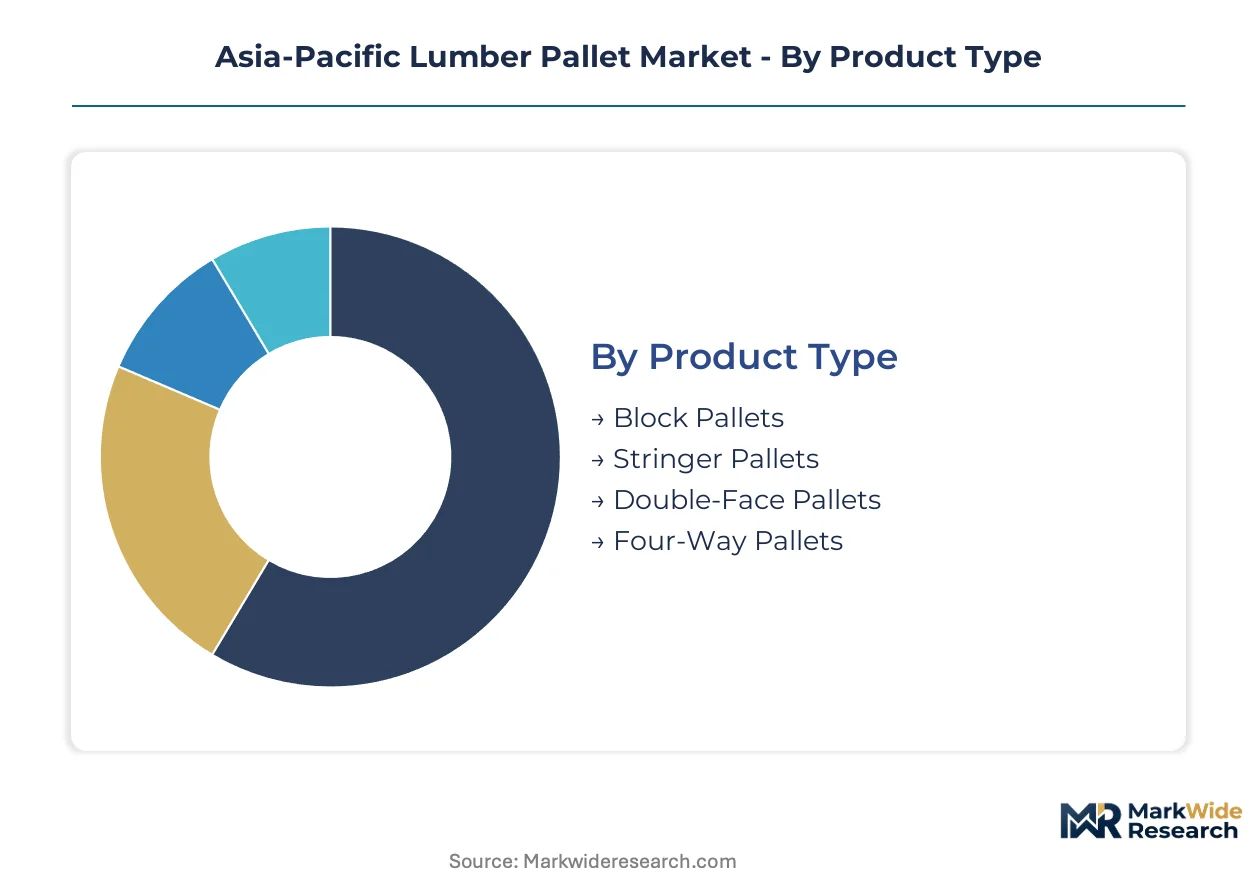
Segmentation in the Asia-Pacific lumber pallet market reveals where plastic substitution pressure concentrates and where lumber retains structural cost advantages. Product architecture, material grade, and end-use compliance requirements determine supplier positioning across diverging national regulatory environments.
Product Type:
Plastic pallet substitution pressure falls heaviest on single-use stringer configurations while four-way entry designs defend share through forklift efficiency premiums.
- Block Pallets:Four-way entry capability enables forklift access from all sides, reducing terminal dwell time in Vietnam's manufacturing corridors and Indonesia's logistics hubs. Electronics exporters in South Korea specify block pallets for high-value component shipments where maneuverability offsets lumber's moisture vulnerability.
- Stringer Pallets:Two-way entry platforms constructed with parallel longitudinal boards deliver lower material intensity and faster production cycles. Warehouse storage applications across China's Yangtze River Delta manufacturing belt favor stringer designs for automated racking systems where directional loading is predetermined.
- Double-Face Pallets:Reversible decks support unitized loads on either surface, extending service life in pooled network rotations. Brambles Limited deploys double-face hardwood variants across Australasian grocery supply chains for durability in multi-trip cycles.
- Four-Way Pallets:Notched stringer or block configurations enabling omnidirectional forklift entry command price premiums in port-centric logistics. Australian importers specify four-way designs to minimize handling delays at Brisbane and Sydney biosecurity checkpoints.
Stringer pallets anchor the volume base while block pallets gain share at the steepest rate.
Material:
Material cost tiers separate commodity shipping applications from engineered-grade pharmaceutical and food export segments.
- Pine:Softwood species harvested from plantation forests deliver cost advantages across high-volume shipping applications. China's GB/T 2934 standardized dimensions favor pine stringer production for domestic e-commerce fulfillment density.
- Oak:Dense hardwood withstands load ratings exceeding two metric tons, penetrating construction end-use segments where structural integrity justifies material premiums. Malaysian and Indonesian timber concessions supply oak feedstock to captive sawmill operations.
- Birch:Fine-grained hardwood offers surface uniformity for retail display applications where aesthetic presentation influences procurement specifications. Japanese automotive supply chains specify birch for leased pallet-as-a-service contracts.
- Softwood:Mixed conifer species provide intermediate density for general-purpose warehousing across India's pharmaceutical export zones requiring BIS certification compliance.
Pine dominates shipment volumes while oak captures margin concentration in heavy-load construction segments.
Usage Type:
Application-specific durability requirements determine whether pooled asset models or single-use procurement prevails.
- Warehouse Storage:Static load-bearing applications in automated facilities prioritize dimensional precision over weather resistance. China's SAMR enforcement of unified pallet dimensions accelerates cross-docking efficiency for warehouse storage deployments.
- Shipping:Export-qualified production demands ISPM-15 heat treatment certification, compressing supplier margins while favoring integrated treatment facilities over standalone sawmills. Vietnam's manufacturing corridors generate concentrated shipping pallet demand for electronics exporters.
- Retail Display:Point-of-sale presentation requirements drive surface finish specifications and color consistency standards. Australian grocery retailers specify retail display grades for in-store merchandising of produce and bulk goods.
- Transportation:Multi-modal handling cycles require impact resistance and repairability, positioning pooled network operators with depot refurbishment capabilities. Loscam International Holdings maintains transportation-grade asset pools across Greater China through captive hardwood sourcing.
Warehouse storage anchors the volume base while transportation applications expand most quickly through pooled network penetration.
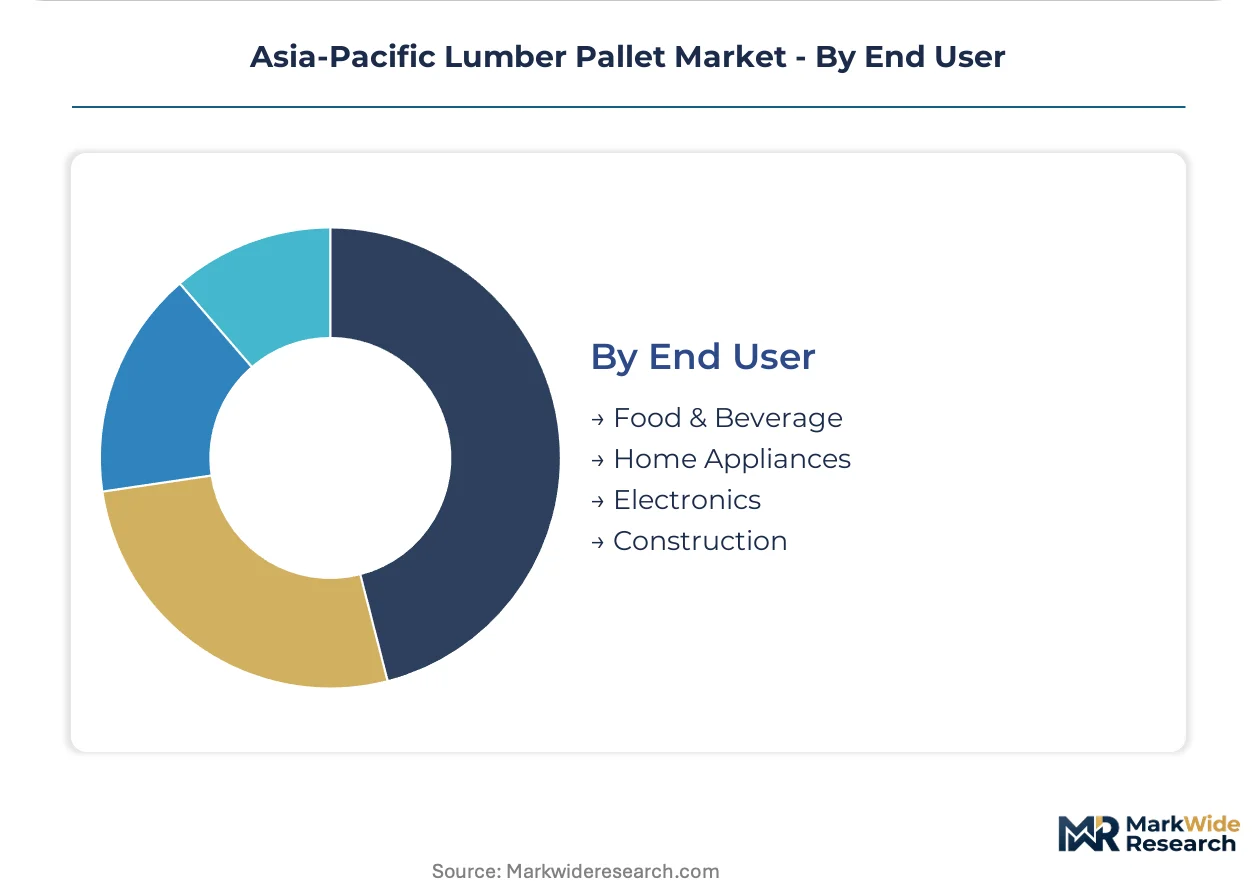
End User:
Customer-type segmentation reveals where phytosanitary compliance creates entry barriers versus where commodity procurement dominates.
- Food & Beverage:Washability requirements and moisture resistance standards expose lumber pallets to plastic substitution in chilled distribution. India's underpenetrated cold chain lacks standardized pallet infrastructure, creating positioning opportunities for ISPM-15-certified suppliers.
- Home Appliances:Bulky unitized cargo with moderate weight density favors cost-optimized stringer configurations. China's domestic appliance manufacturers source pine pallets through GB-standardized procurement frameworks.
- Electronics:High-value component shipments justify RFID-embedded trackable assets with embedded maintenance guarantees. Tier-1 suppliers to Toyota and Honda in Japan lease standardized electronics-grade pallets through depot network contracts.
- Construction:Load ratings exceeding two metric tons specify oak or engineered hardwood grades for raw material and prefabricated component transport. Australian construction importers face ISPM-15 rejection rates of 15-20% at port entry, reshaping supplier qualification hierarchies.
Food and beverage anchors the volume base while electronics gains share at the steepest rate through trackable asset premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in Asia-Pacific pallet demand, while Singapore's transshipment hub anchors Southeast Asian logistics corridors. Regional supply chains bifurcate between China's manufacturing belt and Australia's import-dependent markets.
China
E-commerce fulfillment density across the Yangtze River Delta drives standardized stringer pallet adoption for automated warehouse systems. SAMR enforces GB/T 2934 dimensional interoperability, compressing supplier margins while accelerating cross-docking efficiency. Shenzhen's electronics export clusters specify four-way entry block pallets for high-value component shipments to Japan and South Korea.
Japan
Automotive supply chains to Toyota and Honda generate pallet-as-a-service contract demand replacing outright procurement models. METI's circular economy guidelines incentivize asset pooling over single-use consumption. Nagoya's manufacturing corridor concentrates leased pallet depot networks serving tier-1 component suppliers.
India
Pharmaceutical export zones in Maharashtra and Gujarat generate engineered wood pallet demand meeting BIS certification and destination-country phytosanitary protocols. CDSCO's cold chain regulations for temperature-sensitive biologics create infrastructure gaps in standardized pallet deployment. Hyderabad's vaccine manufacturing cluster lacks ISPM-15-certified suppliers for European and North American export qualification.
Australia
The Department of Agriculture's ISPM-15 enforcement generates 15-20% rejection rates at Brisbane and Sydney ports for non-compliant Asian suppliers. Sydney's grocery retail consolidation favors pooled pallet networks with depot refurbishment capabilities over direct sawmill procurement. Melbourne's construction material imports specify oak-grade hardwood pallets exceeding two-metric-ton load ratings.
Vietnam
Manufacturing corridors from Ho Chi Minh City to Binh Duong Province drive electronics export pallet demand for Samsung and Intel suppliers. Pre-certification through third-party ISPM-15 treatment facilities replaces port-of-entry fumigation following Australian and Japanese protocol tightening. Da Nang's logistics hub development concentrates four-way entry pallet specifications for reduced terminal dwell time.
Asia-Pacific Lumber Pallet Market Competitive Environment
Listed leaders compete with private specialists across depot network density and captive hardwood sourcing. Brambles Limited's pooled pallet infrastructure dominates Australasian grocery supply chains through asset-light rotation models. Three archetypes structure competition: integrated pool operators with captive treatment facilities, regional sawmill consortia serving export-qualified production, and specialty-grade fabricators targeting electronics and pharmaceutical compliance tiers. Dominant competitive moves include backward integration into Malaysian and Indonesian timber concessions and RFID-embedded trackable asset development for high-value cargo segments.
Within the integrated pool operator tier, Brambles Limited and Loscam International Holdings Co., Ltd. exemplify depot-density strategies that capture recurring revenue from grocery retailers and automotive manufacturers. Among North American-originated specialists, UFP Industries, Inc. occupies a position emphasizing specialty-grade pine production for export-compliant segments. These three entities anchor the competitive structure through divergent capital intensity models: pooled network rotation versus direct manufacturing scale versus vertical integration into captive hardwood feedstock.
| Leading Market Players |
|---|
| Brambles Limited |
| UFP Industries, Inc. |
| Menasha Corporation |
| Loscam International Holdings Co., Ltd. |
| PGS Group |
| Greif |
| Millwood, Inc. |
| Rehrig Pacific Holding, Inc. |
| Stora Enso Oyj |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Malaysian and Indonesian hardwood concessions determines feedstock availability and establishes price floors for export-qualified pallet production across the Asia-Pacific. Scale advantages at integrated treatment facilities compress per-unit certification costs while marginalizing standalone sawmills from ISPM-15-compliant segments.
Pricing Analysis
Volume-discount tiering structures separate pooled network contracts from spot-market transactions. Three-tier pricing stratifies across ISPM-15-certified block pallets, GB-standardized stringer configurations, and untreated single-use alternatives. Price differentiation hinges on heat-treatment certification status and captive hardwood sourcing. Cost compression in untreated stringer segments is intensifying because Vietnamese electronics exporters pre-certify through third-party facilities rather than absorb port-of-entry rejection risk. Grocery retailers across Australasia demonstrate lowest price sensitivity due to asset-light pooling models, while Indian pharmaceutical exporters face acute cost pressure from BIS certification layering.
Supply Chain Analysis
Malaysia and Indonesia anchor hardwood feedstock supply for oak-grade construction pallets, while China dominates pine stringer production for domestic e-commerce fulfillment. Raw material flows draw from plantation softwood estates, tropical hardwood concessions, and engineered wood composite facilities. Single-source vulnerability concentrates in Malaysian timber concessions exposed to monsoon disruption and export permit volatility. Distribution runs through depot-network rotations for pooled assets and direct mill procurement for single-use export pallets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISPM-15 regulatory entrenchment creates defensive moats for integrated pool operators with accredited treatment infrastructure. Network effects at depot-density scale reinforce incumbent positioning against fragmented sawmill competition.
For Market Incumbents: Shield pooled asset rotations by accelerating RFID-embedded trackable pallet deployment for electronics exporters. Deepen backward integration into Indonesian hardwood concessions to secure oak-grade feedstock against monsoon supply disruption. ISPM-15 audit backlogs at Australian biosecurity checkpoints threaten working capital cycles for non-integrated competitors. For New Entrants and Emerging Players: ISPM-15 certification fast-tracks through accredited third-party treatment partnerships unlock Australia's grocery retail consolidation. India's underpenetrated cold chain for temperature-controlled pharmaceuticals offers the most penetrable white space. A depot-light model leasing certified assets to vaccine manufacturers bypasses capital-intensive kiln infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pooled network operators with embedded digital traceability capabilities. Long-term viability rests on recurring revenue streams from asset rotation rather than transactional manufacturing margins. Acquisition targets should demonstrate captive hardwood sourcing and ISPM-15 accreditation density. The signal to monitor is rejection rate volatility at Australian ports reshaping supplier qualification hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| ISPM-15 Certification Expansion | Accredited heat-treatment capacity secures access to Australian and Japanese import corridors. |
| RFID-Embedded Asset Deployment | Trackable pallets command per-trip premiums from South Korean electronics exporters. |
| Depot Network Densification | Rotation efficiency captures recurring revenue from Japan's automotive pallet-as-a-service contracts. |
| Captive Hardwood Sourcing | Malaysian and Indonesian timber concessions insulate against plantation softwood price volatility. |
| Automated Repair Infrastructure | Robotic nail placement reduces refurbishment costs for pooled network asset cycles. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with pallet pool operators, sawmill procurement directors, and grocery retail supply chain managers; and secondary validation through customs trade records, GB standards documentation, and ISPM-15 accreditation registries. Bottom-up triangulation cross-checked depot network capacity claims against top-down container throughput correlations at Shanghai, Singapore, and Sydney ports.
Across the projection horizon, the analytical framework modeled demand by product architecture, material grade, end-use compliance tier, and national regulatory cluster. CAGRs derived from segment-level volume trajectories weighted by treatment certification penetration and pooled network adoption curves. Forecast inputs incorporated e-commerce fulfillment density indices and pharmaceutical export zone infrastructure gaps.
Underlying assumptions cover sustained ISPM-15 enforcement stringency and hardwood concession access stability, with deviation risk concentrated in Australian biosecurity protocol amendments and Indian cold chain regulatory acceleration. Recalibration cycles align with material shifts in port rejection rate data and RFID adoption thresholds among electronics exporters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Canada Pallets Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Pallet Boxes Market