
 Palletizer Market | 2026-2036
Palletizer Market Size, Share, and Industry Trends Forecast 2026-2036
Palletizer Market Intelligence
Modular pallet-configurations with mixed-SKU bundling is realigning buyer specifications toward flexible end-of-line systems. ABB Ltd. leverages its servo-motion portfolio to dominate high-speed food-processing installations. FANUC Corporation sustains technology leadership in compact articulated-arm designs for dense warehousing footprints.
A palletizer is an automated material-handling machine that arranges cases, bags, or containers into unitized loads on pallets, typically operating at throughputs of 20–200 cycles per minute depending on layer-forming or robotic pick-and-place architecture. Its primary purpose is to eliminate manual stacking at distribution chokepoints while ensuring load stability for downstream transport. Robotic palletizers capture expanding margin pools in pharmaceuticals and electronics where batch sizes shrink and changeovers accelerate. Conventional layer palletizers still anchor high-volume beverage and chemicals applications where throughput consistency outweighs flexibility premiums.
The EU Machinery Directive, ISO 10218 robot safety standards, and OSHA lockout/tagout regulations in the United States collectively mandate interlocked guarding and collaborative speed-separation protocols, forcing OEMs to embed safety-rated monitored stops as standard rather than optional features. FDA cGMP guidelines for pharmaceutical packaging further constrain surface finishes and cleanability specifications in palletizer frame design. Stakeholders must weigh retrofit compatibility against greenfield collaborative installations as regional enforcement of safety standards diverges.
Market Dynamics
Food processing facilities are expanding automated palletizing lines to handle mixed-SKU fulfillment, forcing OEMs to redesign mechanical architectures around flexible end-of-line systems rather than fixed-format layer-forming machines.
Growth Catalysts
- EU Machinery Directive compliance mandates:European OEMs must embed safety-rated monitored stops and collaborative speed-separation protocols, accelerating retrofit demand for conventional-to-robotic system upgrades in Germany's automotive packaging plants.
- Pharmaceutical batch-size compression:Robotic palletizers capture expanding margin pools as FDA cGMP guidelines constrain surface finishes and cleanability specifications, driving specification changes in frame design.
- Automotive e-commerce fulfillment:Dense warehousing footprints in chemical packaging facilities require compact articulated-arm designs that maximize throughput per square meter.
Market Restraints
- Steel and servo-motor input volatility:Component cost fluctuations compress margin pools for mid-tier system integrators sourcing precision motion-control hardware.
- European OEM supply concentration:Safety-rated component fabrication clusters in Germany and Italy create bottleneck risk for collaborative robot interface redesign cycles.
- Conventional layer-palletizer substitution ceiling:Beverage and chemicals applications with throughput consistency requirements limit displacement potential for robotic architectures in high-volume lines.
Strategic Opportunities
- India food-processing automation:FSSAI packaging standards and PLI scheme incentives create greenfield demand for modular pallet-configurations with mixed-SKU bundling capability.
- Collaborative robot-human convergence:ISO 10218 safety standards and force-limiting end-effector technology enable new installation categories in semi-automated facilities.
- Pharmaceutical serialization integration:Track-and-trace mandates in secondary packaging lines create specification pull for palletizers with integrated vision verification and data-logging architecture.
Industry Challenges
- Mechatronics technician scarcity:Servo-motion programming and collaborative robot safety certification gaps constrain deployment velocity for OEM field service teams.
- Legacy SCADA integration complexity:Brownfield beverage plants face protocol translation friction when retrofitting robotic cells onto existing Allen-Bradley or Siemens control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palletizer Market |
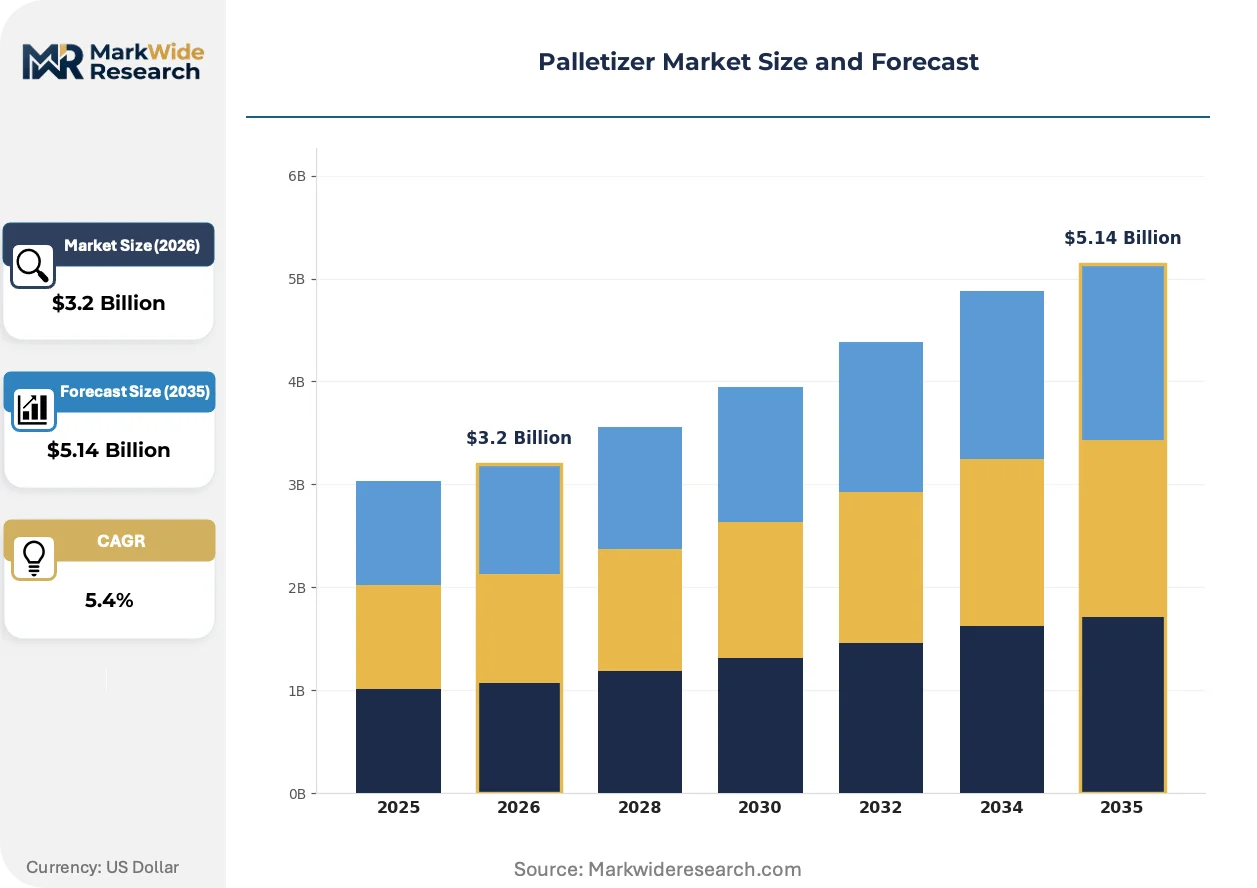
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic, Conventional, Semi-automatic, Layer, Mixed Technology: Servo Motor, Hydraulic, Pneumatic, Electric, Mechanical Application: Food Processing, Pharmaceuticals, Consumer Goods, Chemicals, Electronics End User: Packaging Plants, Manufacturing Units, Distribution Centers, Warehousing Facilities |
| Companies Covered | Daifuku Co., Ltd., Beumer Group GmbH & Co. KG, ABB Ltd., KION Group AG, Yaskawa Electric Corporation, FANUC Corporation, SSI Schaefer Holding GmbH, Comau SpA, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palletizer Market Strategic Shifts & Innovations
Vision-guided robotic cells are compressing changeover intervals while force-sensitive collaborative architectures expand into semi-automated facilities previously reserved for manual operations.
Articulated-arm palletizers with integrated 3D vision systems are automating mixed-case layer formation in food distribution centers. Retail consolidation is accelerating adoption among third-party logistics operators serving grocery chains. This technology is automating the elimination of manual touchpoints previously required for SKU variation handling.
OSHA lockout/tagout regulations in the United States now mandate interlocked guarding as standard rather than optional features. OEMs must embed safety-rated monitored stops into base configurations, eliminating the price differentiation between guarded and collaborative models. Pharmaceutical packaging lines in North America face the steepest compliance timeline pressure.
After-sales service unbundling is disrupting traditional turnkey procurement in the warehouse automation channel. End-users now separately source spare parts, remote diagnostics subscriptions, and field technician labor. This shift is most visible among German automotive suppliers operating multi-vendor palletizing fleets.
Palletizer Market Segmentation
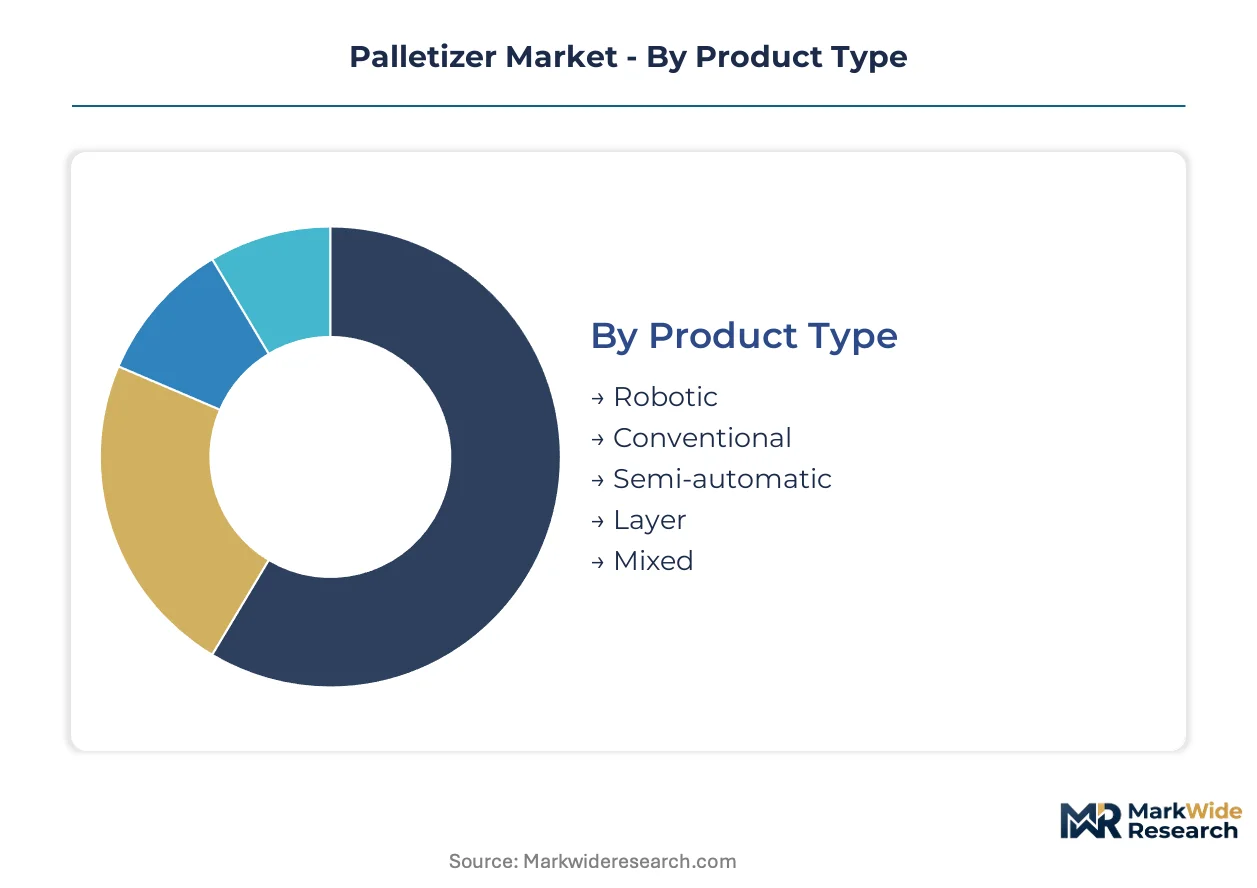
Palletizer procurement patterns diverge sharply across product architectures and downstream applications. OEMs configure their sales channels around these fault lines, with technology choice and end-use vertical determining specification intensity and service attach rates.
Product Type:
Supply concentration tilts toward robotic and conventional platforms, where German and Japanese motion-control specialists dominate component sourcing.
- Robotic:Articulated-arm and delta configurations execute pick-and-place operations through 6-axis servo control, enabling mixed-SKU layer formation without mechanical changeover. Pharmaceutical batch-size compression and electronics fulfillment in Germany are pulling specification toward force-limited collaborative variants with ISO 10218 safety certification.
- Conventional:Layer-forming machines with fixed mechanical patterns deliver 20-200 cycles per minute through continuous-motion layer accumulation. Beverage and chemical packaging plants in high-volume corridors anchor demand, where throughput consistency outweighs flexibility premiums.
- Semi-automatic:Operator-assisted palletizing stations bridge manual and fully automated operations in mid-tier food processing facilities.
- Layer:Dedicated layer-building architectures with slip-sheet insertion and compression functions serve bulk commodity distribution.
- Mixed:Hybrid configurations combining robotic handling with conventional layer accumulation target third-party logistics operators.
Conventional platforms absorb the bulk of installed capacity; robotic systems are expanding most quickly.
Technology:
Cost tiering separates precision motion architectures from commodity mechanical drives, with servo-electric systems commanding 40-60% price premiums over pneumatic alternatives.
- Servo Motor:Closed-loop position control with encoder feedback enables sub-millimeter placement accuracy and programmable acceleration profiles. High-speed food-processing lines and pharmaceutical cleanroom installations specify these for changeover flexibility.
- Hydraulic:Fluid-power actuation delivers high force density for heavy-load chemical and bulk material handling where positional precision is secondary to lifting capacity.
- Pneumatic:Compressed-air cylinder systems serve low-speed, low-precision applications in cost-constrained warehousing facilities.
- Electric:General-purpose motor drives without servo feedback occupy the mid-market for standard case handling.
- Mechanical:Cam-driven and linkage-based motion control persists in legacy beverage installations with minimal SKU variation.
Servo motor technology captures the steepest expansion trajectory as end-users prioritize energy efficiency and programmable flexibility.
Application:
Volume concentration clusters in food processing, though margin pools are deepest in pharmaceutical and electronics verticals with compliance-intensive specifications.
- Food Processing:Mixed-SKU fulfillment requirements are forcing OEMs to redesign mechanical architectures around flexible end-of-line systems. Retail consolidation among grocery chains is accelerating adoption of vision-guided robotic cells in distribution centers.
- Pharmaceuticals:FDA cGMP guidelines constrain surface finishes and cleanability specifications, driving frame design changes and integrated serialization verification. Track-and-trace mandates create specification pull for vision-enabled palletizers with data-logging architecture.
- Consumer Goods:E-commerce fulfillment pressures are compressing batch sizes and accelerating changeover intervals in personal care and household product packaging.
- Chemicals:Hazardous material handling requirements and throughput consistency needs anchor demand for conventional layer palletizers in bulk operations.
- Electronics:Dense warehousing footprints and damage-sensitive product handling favor compact articulated-arm designs with force-limiting end-effectors.
Food processing absorbs the bulk of installed capacity; pharmaceuticals are gaining share fastest.
End User:
Customer type determines procurement modality, with packaging plants favoring turnkey integration and distribution centers unbundling after-sales service.
- Packaging Plants:Integrated end-of-line operations require palletizers synchronized with fillers, case packers, and stretch wrappers through unified control architectures. German automotive suppliers operating multi-vendor fleets are driving unbundling of spare parts and remote diagnostics.
- Manufacturing Units:Captive packaging operations in chemical and electronics production facilities prioritize retrofit compatibility with existing SCADA infrastructure.
- Distribution Centers:Third-party logistics operators serving retail consolidation demand modular configurations with rapid SKU changeover capability.
- Warehousing Facilities:Storage-centric operations with lower throughput requirements specify semi-automatic or conventional systems for pallet consolidation and cross-docking.
Packaging plants absorb the bulk of installed capacity; distribution centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where motion-control specialists fabricate servo systems, while consumption spreads across food-processing corridors in the United States, India, and Western Europe. German and Japanese OEMs export precision components to packaging plants worldwide. Regional enforcement of safety standards is fragmenting procurement specifications.
Germany
Automotive packaging plants in Stuttgart and Wolfsburg drive retrofit demand for conventional-to-robotic system upgrades. The EU Machinery Directive and ISO 10218 standards mandate safety-rated monitored stops, forcing OEMs to redesign collaborative interfaces. Bavarian motion-control clusters supply servo-motor components to European integrators.
United States
Food distribution centers in Chicago and Dallas are expanding vision-guided robotic cells for mixed-SKU fulfillment. OSHA lockout/tagout regulations now require interlocked guarding as standard features. Pharmaceutical packaging corridors in New Jersey face compressed compliance timelines for FDA cGMP surface-finish specifications.
India
Food-processing automation is accelerating in Maharashtra and Gujarat under FSSAI packaging standards and PLI scheme incentives. The country's national food regulator mandates hygiene-grade specifications for end-of-line equipment. Pune-based system integrators are deploying modular pallet-configurations with mixed-SKU bundling.
China
E-commerce fulfillment hubs in Shanghai and Shenzhen are adopting compact articulated-arm designs for dense warehousing footprints. GB standards and SAMR regulations govern collaborative robot safety certification. Yangtze River Delta electronics manufacturers specify force-limiting end-effectors for damage-sensitive handling.
Japan
Compact robotic architectures dominate domestic electronics and automotive packaging operations in Aichi and Osaka prefectures. METI industrial automation policies support SME technology adoption. Nagoya-area precision-machining clusters fabricate harmonic drives for delta-configuration palletizers.
Palletizer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base separates into three strategic archetypes: diversified industrial automation conglomerates with broad motion-control portfolios, pure-play robotic specialists with concentrated palletizing expertise, and regional system integrators with local fabrication capabilities. Competitive moves center on M&A for safety-rated component access and strategic partnerships for software-integrated control architectures.
Among Japanese conglomerates, FANUC Corporation and Yaskawa Electric Corporation occupy positions emphasizing servo-motion technology and compact arm designs. ABB Ltd. anchors the European diversified tier with integrated end-of-line system capabilities. Daifuku Co., Ltd. represents the Japanese material-handling specialist archetype with concentrated intralogistics expertise. Beumer Group GmbH & Co. KG exemplifies the German family-owned engineering tradition in bulk-handling automation.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Beumer Group GmbH & Co. KG |
| ABB Ltd. |
| KION Group AG |
| Yaskawa Electric Corporation |
| FANUC Corporation |
| SSI Schaefer Holding GmbH |
| Comau SpA |
| KUKA AG |
| Others |
Cost & Logistics Intelligence
Mechatronics technician scarcity in Germany and Japan widens pricing-tier spreads between servo-electric precision systems and pneumatic commodity alternatives, with labor-cost differentials amplifying the 40-60% premium commanded by closed-loop motion architectures.
Pricing Analysis
Margin tightening in mid-tier robotic systems reflects steel and servo-motor input volatility compressing integrator profitability. Project-based pricing with modular configuration options dominates procurement, with ISO 10218 safety certification tier and after-sales service bundling as primary differentiation drivers. Cost-down pressure on conventional layer palletizers accelerates as beverage plants prioritize retrofit compatibility over greenfield flexibility premiums. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical packaging plants absorb certification-driven premiums for FDA cGMP-compliant surface finishes.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Nagoya precision-machining clusters tether component fabrication to established industrial corridors. Supply concentrates in Germany, Japan, and Italy for safety-rated servo systems and harmonic drive actuators, with steel and rare-earth magnet dependencies creating vulnerability to commodity price swings. Single-source concentration in German-Italian collaborative robot interface fabrication presents bottleneck risk. Distribution runs through OEM-direct channels for packaging plants and unbundled service contracts for multi-vendor fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive erects a compliance moat that advantages incumbents with certified collaborative architectures while forcing marginal players toward conventional system commoditization.
For Market Incumbents: Anchor market position through captive servo-motor production in Bavarian clusters and ISO 10218 certification depth that emerging Asian competitors cannot rapidly replicate. Defend against pure-play robotic specialists by integrating vision-guided mixed-SKU capabilities into legacy layer-palletizer installed bases through retrofit protocols. Prioritize backward integration into safety-rated monitored stop components to eliminate supply bottlenecks from Italian fabrication clusters. For New Entrants and Emerging Players: System integrators in India's Maharashtra-Gujarat food-processing corridor offer partnership pathways around FSSAI hygiene-grade specifications and PLI scheme incentives. White-space opportunity concentrates in semi-automatic operator-assisted stations for mid-tier processors bridging manual and fully automated operations. Pursue collaborative robot-human convergence installations in brownfield facilities where force-limiting end-effector technology enables new safety-certified categories. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play robotic specialists possessing ISO 10218 certification depth and pharmaceutical serialization integration capabilities given FDA track-and-trace mandate expansion. Long-term viability favors vendors with software-integrated control architectures over mechanical-legacy peers. Monitor enforcement divergence between EU Machinery Directive and OSHA lockout/tagout timelines as inflection indicator for regional competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Safety-Rated Component Backward Integration | In-house production of monitored stop systems eliminates Italian-German supply bottlenecks for collaborative interfaces. |
| Vision-Guided Mixed-SKU Retrofit Protocols | 3D vision layer formation upgrades extend conventional palletizer lifecycles in beverage distribution centers. |
| Pharmaceutical Serialization Partnership | Integrated track-and-trace data-logging architectures capture FDA cGMP-compliant margin pools. |
| India System Integrator Joint Venture | FSSAI hygiene-grade specifications and PLI incentives create greenfield automation demand in Maharashtra food processing. |
| After-Sales Service Unbundling Platform | Remote diagnostics subscriptions and spare parts marketplaces serve German automotive multi-vendor fleet operators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving plant engineers at beverage and pharmaceutical packaging facilities, OEM procurement teams specifying servo-motion architectures, aftermarket service heads managing multi-vendor fleets, and system integrators deploying modular configurations in India. FDA cGMP guidance documents, EU Machinery Directive compliance databases, and FSSAI packaging standard notifications provided regulatory validation. Bottom-up shipment data triangulated against top-down end-use demand estimates across food processing, pharmaceuticals, and chemicals verticals.
Data-stream reconciliation across product architecture segmentation, technology tiering, and application verticals shaped the analytical framework throughout the projection horizon. Servo-electric, hydraulic, pneumatic, and mechanical drive categories were modeled against robotic, conventional, and hybrid platform types. CAGRs derived from regression analysis of historical capital expenditure patterns and regulatory compliance cycle timing. Industry-specific inputs included pharmaceutical batch-size compression trajectories and automotive e-commerce fulfillment density requirements.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to ISO 10218 safety protocols, abrupt steel or rare-earth magnet commodity price dislocations, and geopolitical disruptions affecting German-Japanese precision component trade flows. Forecasts reflect assumptions regarding enforcement consistency across EU Machinery Directive and OSHA implementation timelines. Material deviation in collaborative robot certification adoption rates or pharmaceutical serialization mandate delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Japan Pallets Market