
 Pallet Labeler Market | 2026-2036
Pallet Labeler Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Labeler Market Analytics
Aftermarket service revenue is reconfiguring competitive economics in pallet labeling. Zebra Technologies Corporation leverages its extensive channel network to capture recurring maintenance contracts across installed print-and-apply systems. SATO Holdings Corporation anchors its position through deep specialization in thermal transfer durability for cold-chain pharmaceutical pallets. Domino Printing Sciences plc differentiates via inkjet technology leadership that reduces consumable costs for high-throughput logistics hubs.
A pallet labeler applies identification, tracking, or compliance markings to palletized loads using thermal transfer, direct thermal, inkjet, or laser imaging at speeds typically exceeding 30 pallets per minute in automated configurations. Its primary industrial purpose is enabling supply chain traceability, customs clearance, and end-customer verification through machine-readable codes and human-readable text. Print and apply systems command the dominant share of value given their integration with warehouse management software and conveyor infrastructure, while inkjet technology represents the fastest-expanding segment as operators seek reduced ribbon and label stock expenditures. Standard-grade labels still occupy volume leadership, though durable and eco-friendly variants are gaining share in pharmaceutical and retail compliance applications.
The EU Falsified Medicines Directive and the FDA's Drug Supply Chain Security Act shape product requirements by mandating serialized, aggregation-capable labeling at the pallet level. Brazil's ANVISA and South Korea's MFDS impose parallel track-and-trace standards that exporters must satisfy. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant equipment investments and ensure single-platform compliance across multiple destination markets.
Market Dynamics
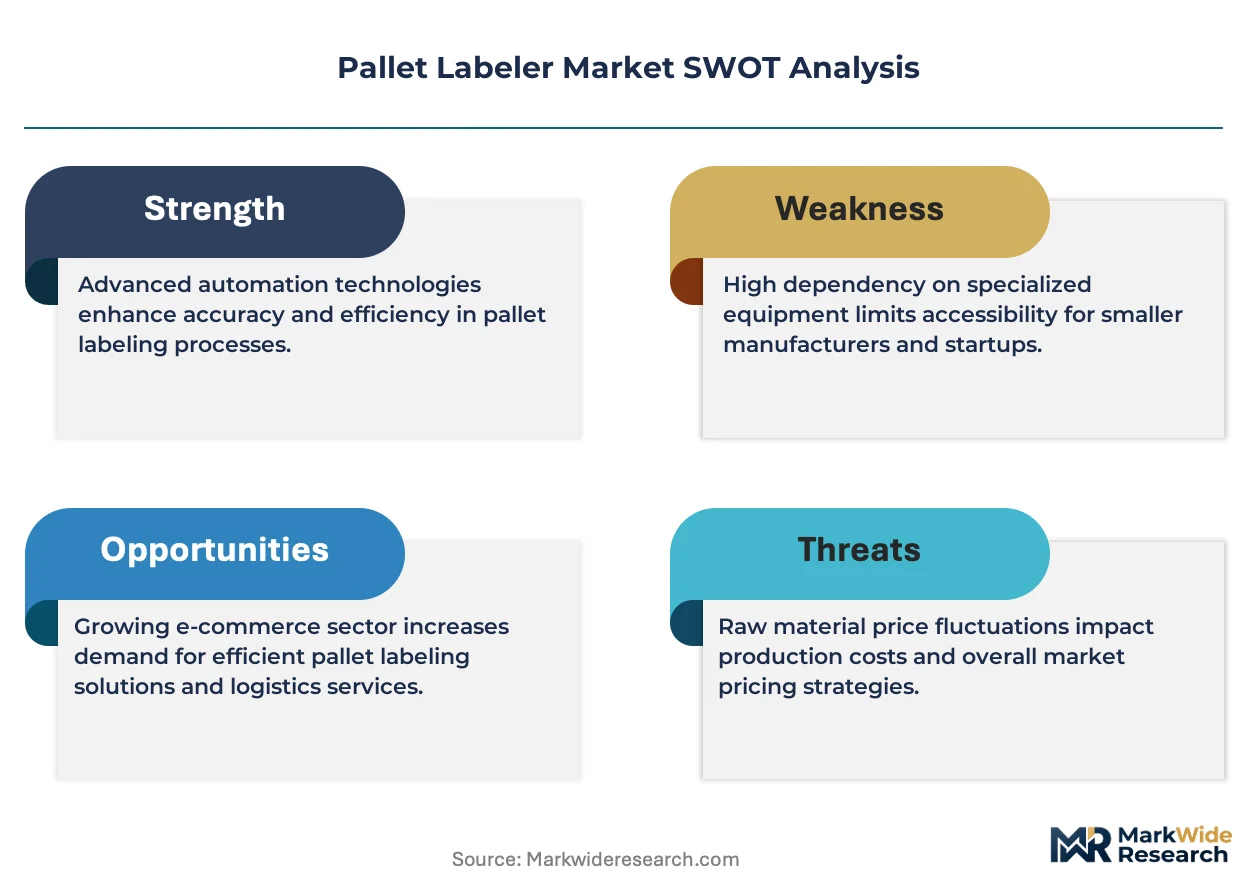
Warehouse operators face simultaneous pressure from pharmaceutical serialization mandates and the operational imperative to reduce consumable spend per pallet, forcing capital allocation toward systems that reconcile compliance durability with lower ribbon and label stock costs.
Growth Catalysts
- EU Falsified Medicines Directive aggregation requirements:Pharmaceutical exporters must implement pallet-level serialization with parent-child relationships to case and unit codes, driving system upgrades across distribution centers.
- Cold-chain logistics expansion:Thermal transfer durability specifications for frozen pharmaceutical pallets are tightening, requiring specialized print-and-apply configurations with extended adhesive performance ranges.
- Brazil ANVISA track-and-trace alignment:Exporters serving Latin American markets must duplicate EU-equivalent serialization infrastructure, creating parallel equipment demand from multinational pharmaceutical manufacturers.
Market Restraints
- Stainless steel and aluminum input volatility:Conveyor-integrated labeling frames require corrosion-resistant alloys, exposing system integrators to commodity price swings that compress project margins.
- Printhead supply concentration:Precision thermal and piezo-electric printhead manufacturing concentrates in Japanese and German component suppliers, creating single-source vulnerability for system builders.
- Legacy warehouse management system fragmentation:Proprietary communication protocols in older WMS installations force expensive middleware development for print-and-apply integration.
Strategic Opportunities
- South Korea MFDS serialization phase-in:The staged implementation through 2025 creates a defined equipment replacement window for exporters serving Korean pharmaceutical distribution.
- Inkjet-vision system convergence:Integration of high-resolution piezo inkjet with inline barcode verification cameras enables single-pass compliance labeling with reduced mechanical complexity.
- Third-party logistics provider channel development:Contract logistics operators managing pharmaceutical compliance for multiple manufacturers represent a concentrated buyer segment with standardized specification authority.
Industry Challenges
- Serialized aggregation validation skill scarcity:Commissioning engineers must reconcile line-level serialization with pallet aggregation logic, a competency gap that extends deployment timelines.
- Multi-jurisdiction compliance certification:Systems must simultaneously satisfy EU MDR, FDA DSCSA, and emerging market track-and-trace requirements, multiplying validation documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Labeler Market |
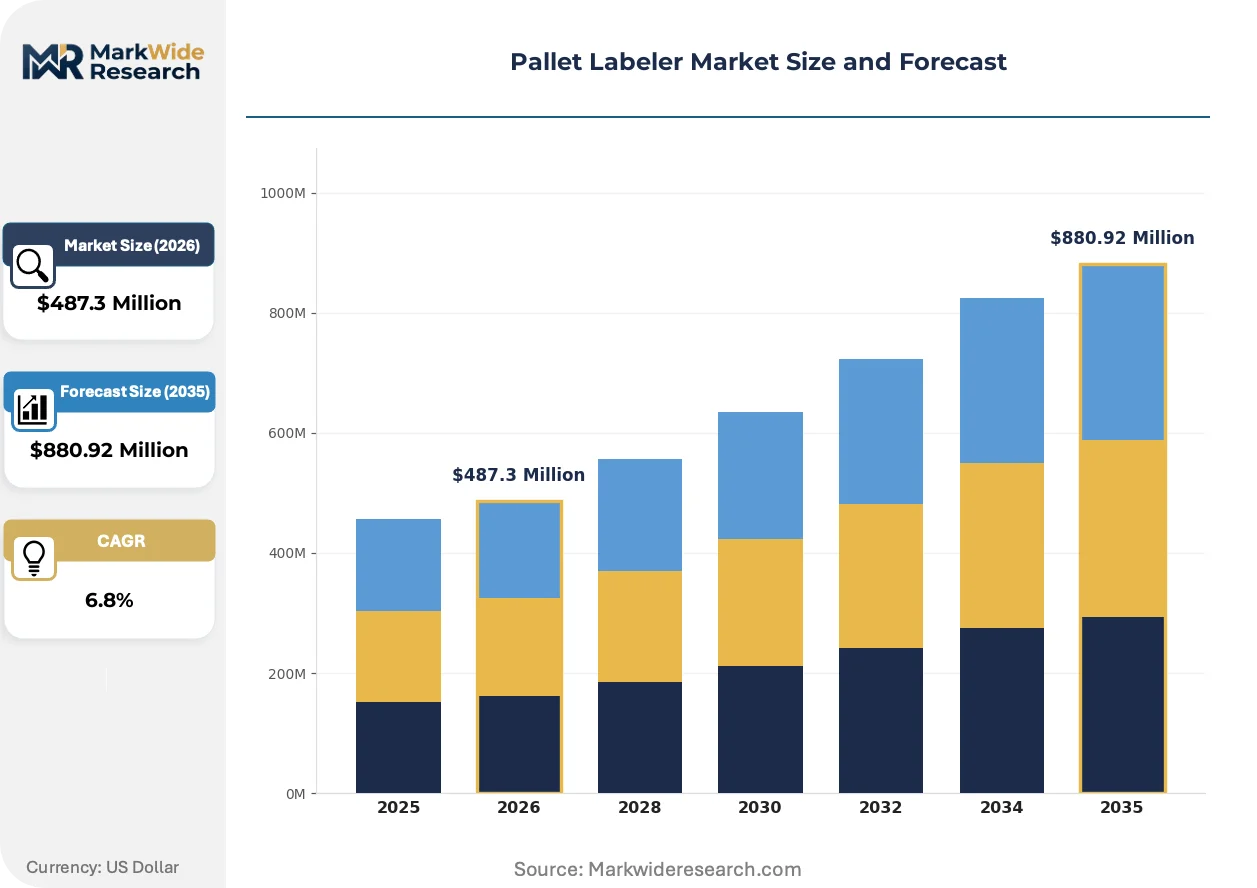
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Labelers, Semi-Automatic Labelers, Manual Labelers, Print and Apply Systems End User: Manufacturing, Logistics, Retail, Pharmaceuticals Label Quality: Standard, Premium, Durable, Eco-Friendly Technology: Thermal Transfer, Direct Thermal, Inkjet, Laser |
| Companies Covered | Zebra Technologies Corporation, Honeywell International Inc., SATO Holdings Corporation, Markem-Imaje Corporation, Avery Dennison Corporation, Weber Packaging Solutions, Videojet Technologies Inc., Domino Printing Sciences plc, Cab Produkttechnik GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Labeler Market Evolving Landscape
Pharmaceutical distribution economics are compressing acceptable cost per labeled pallet while serialization stringency intensifies, forcing technology convergence between compliance-grade durability and consumable minimization.
Inkjet technology is collapsing the traditional trade-off between consumable cost and label durability in high-throughput environments. Piezo-electric drop-on-demand systems now achieve pharmaceutical-grade barcode permanence without thermal transfer ribbon expenditure. Major contract logistics operators in Germany and the Netherlands are retrofitting existing conveyor lines with inkjet modules to capture operating cost advantages while maintaining EU FMD compliance.
REACH chemical restrictions on adhesive formulations are tightening specifications for pressure-sensitive labels used in pharmaceutical cold chains. The European Chemicals Agency's evolving substance of very high concern list is forcing labelstock suppliers to reformulate acrylic adhesives for freezer-grade applications. German pharmaceutical exporters and their third-party logistics partners are qualifying alternative adhesive chemistries ahead of anticipated restriction timelines.
Service unbundling is fragmenting traditional equipment-procurement relationships in pharmaceutical logistics. Buyers are separating hardware acquisition from installation commissioning and ongoing maintenance, creating discrete vendor selection decisions at each stage. This pattern is most pronounced in the Netherlands and Belgium, where large distribution hubs operate sufficient internal engineering capacity to self-perform integration while outsourcing specialized printhead maintenance.
Pallet Labeler Market Segmentation
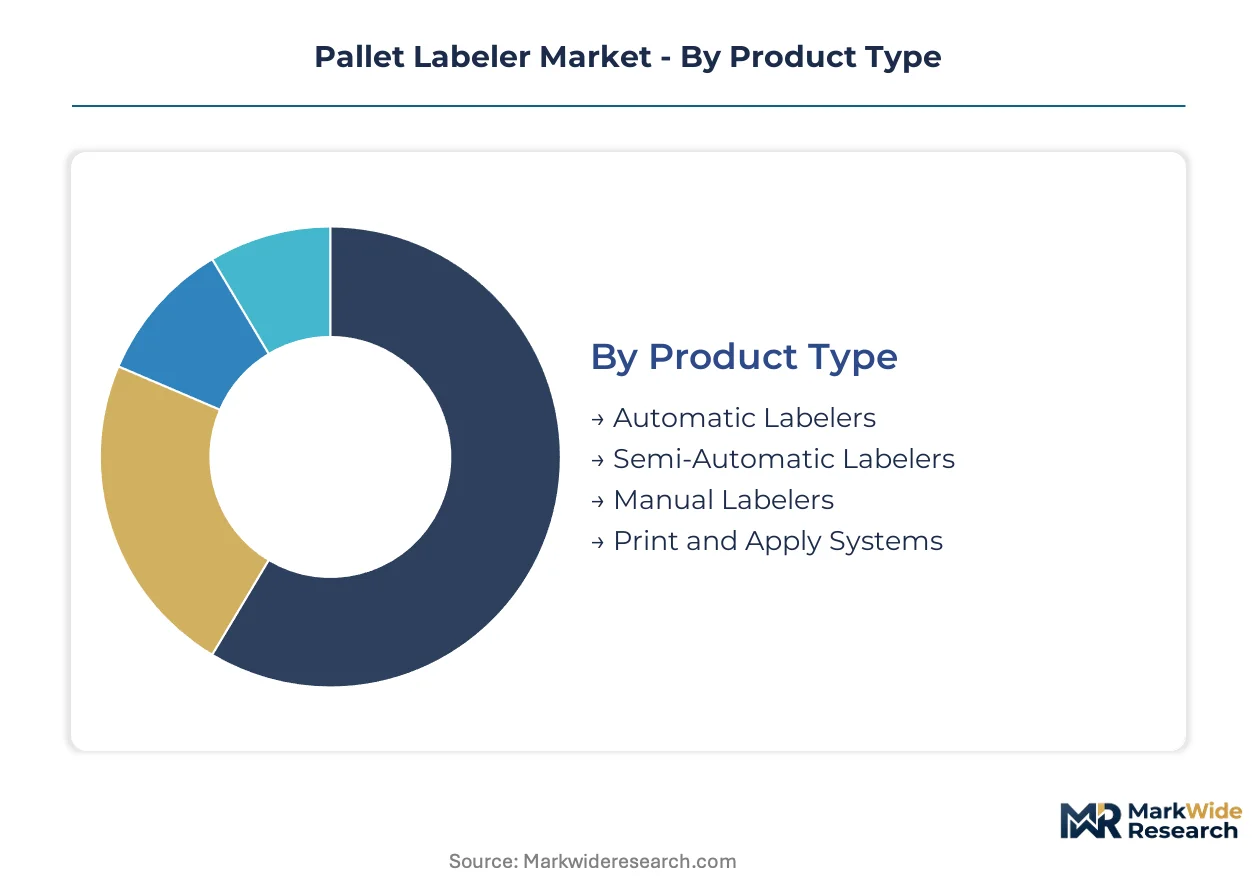
Pallet labeling configurations must reconcile throughput velocity with serialization compliance across divergent operational environments. Equipment selection varies dramatically between high-volume pharmaceutical distribution hubs and smaller manufacturing facilities with intermittent pallet movement.
Product Type:
Mature conveyor-integrated systems dominate pharmaceutical and retail fulfillment, while emerging modular configurations address mid-tier manufacturing flexibility requirements.
- Print and Apply Systems:These units integrate thermal or inkjet print engines with pneumatic applicator arms for synchronized labeling at conveyor speeds exceeding 30 pallets per minute. German pharmaceutical exporters and Dutch contract logistics operators specify these configurations to meet EU Falsified Medicines Directive aggregation mandates with minimal line disruption.
- Automatic Labelers:Fully automated systems detect pallet presence, trigger print jobs from warehouse management system data, and apply labels without operator intervention. Demand concentrates in Brazil and South Korea where ANVISA and MFDS serialization deadlines are forcing warehouse automation retrofits.
- Semi-Automatic Labelers:Operator-assisted systems requiring manual pallet presentation suit manufacturing facilities with variable batch sizes and lower throughput requirements.
- Manual Labelers:Handheld or benchtop units serve small-scale operations and backup labeling scenarios where capital constraints preclude automation investment.
Print and Apply Systems handle the majority of throughput; Inkjet technology within Automatic Labelers is climbing the fastest on share.
End User:
Cost tier segmentation separates capital-intensive compliance investments from operational efficiency plays across the value chain.
- Pharmaceuticals:Serialization mandates from FDA, EMA, and ANVISA drive specification authority here. Pallet-level aggregation with parent-child traceability to case and unit codes requires validated print-and-apply systems with inline barcode verification. Cold-chain durability specifications for frozen biologics add thermal transfer ribbon and adhesive performance requirements.
- Logistics:Third-party providers managing multi-manufacturer pharmaceutical compliance represent a concentrated buyer segment with standardized equipment specifications. Dutch and Belgian distribution hubs prioritize consumable cost reduction through inkjet retrofits.
- Manufacturing:Production facilities apply pallet labels for internal traceability and outbound shipment preparation, with demand varying by sector serialization requirements.
- Retail:Distribution centers serving omnichannel fulfillment use pallet labeling for cross-dock efficiency and returns processing, with less stringent durability specifications than pharmaceutical applications.
Pharmaceuticals commands the highest equipment specification tier; Logistics is expanding most quickly as contract operators aggregate compliance spend across client portfolios.
Label Quality:
Application environment determines grade selection, with freezer-grade durability commanding substantial specification premiums over standard warehouse applications.
- Durable:Cold-chain pharmaceutical pallets require acrylic adhesives with extended performance ranges from ambient through frozen storage. ECHA substance restrictions are forcing reformulation timelines ahead of anticipated restriction dates.
- Premium:High-contrast, smudge-resistant substrates serve high-value pharmaceutical and electronics shipments where label legibility failures trigger rejection penalties.
- Standard:General-purpose pressure-sensitive labels suit dry warehouse environments with moderate handling and short dwell times.
- Eco-Friendly:Recycled content and biodegradable adhesive formulations address corporate sustainability commitments, particularly in German and Benelux retail distribution networks.
Durable grade handles the majority of pharmaceutical throughput; Eco-Friendly is gaining share fastest as REACH compliance tightens adhesive formulation requirements.
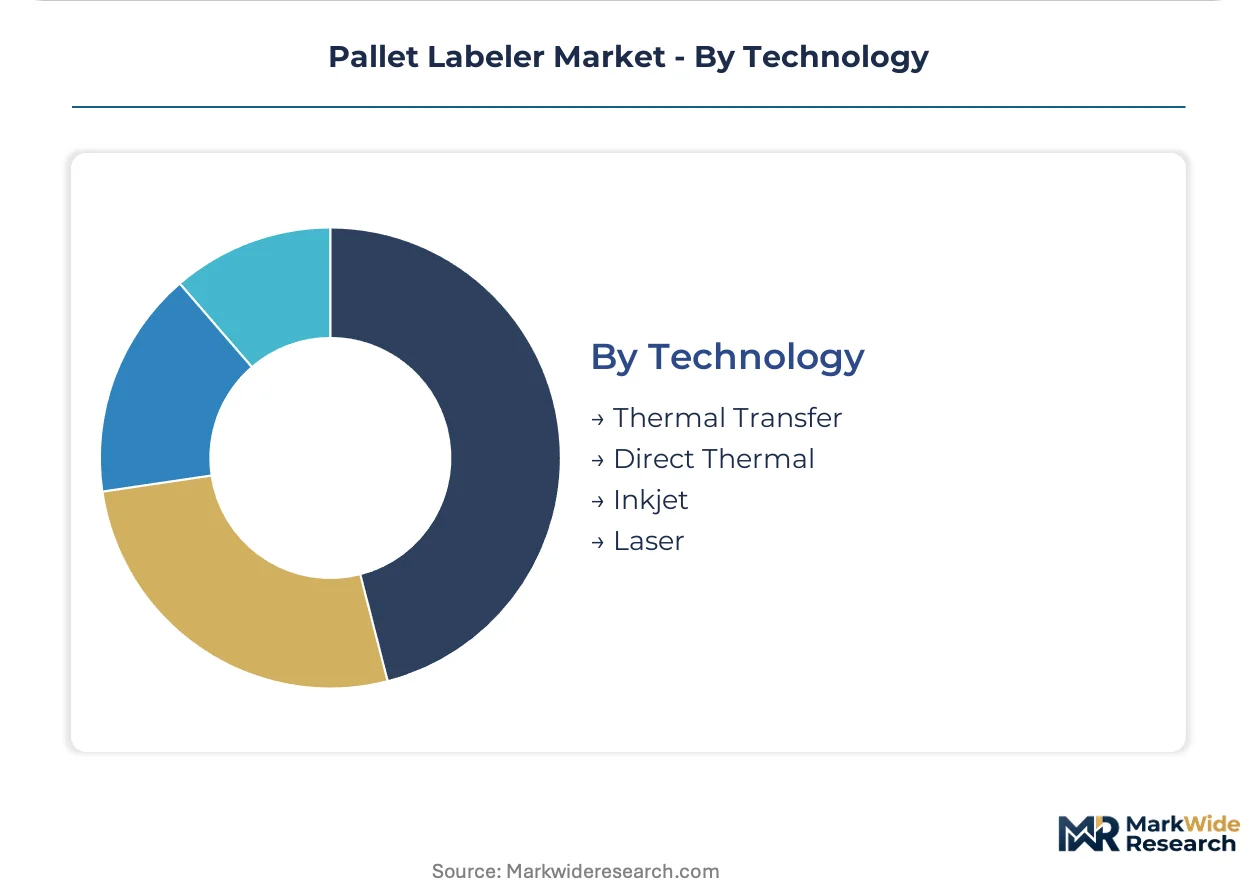
Technology:
Supply concentration in Japanese and German printhead manufacturing shapes technology adoption economics across end-use segments.
- Inkjet:Piezo-electric drop-on-demand systems eliminate thermal transfer ribbon expenditure while achieving pharmaceutical-grade barcode permanence. Major German and Dutch contract logistics operators are retrofitting existing lines to capture operating cost advantages.
- Thermal Transfer:Wax-resin ribbon imaging delivers proven durability for cold-chain applications with established validation documentation for FDA and EMA compliance submissions.
- Direct Thermal:Ribbon-free imaging suits short-term applications where heat-sensitive substrates and limited environmental exposure permit cost reduction.
- Laser:Ablation marking on synthetic substrates serves specialized applications requiring permanent, chemical-resistant identification without consumable expenditure.
Thermal Transfer retains the largest installed base; Inkjet is expanding most quickly on new equipment specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands exhibit the lowest price elasticity, prioritizing compliance validation and consumable efficiency over capital cost, while operators in Brazil and India face sharper budget constraints that favor modular retrofit configurations over integrated system investments.
Germany
Pharmaceutical exporters and third-party logistics providers drive specification authority for high-throughput print-and-apply systems. The EU Falsified Medicines Directive aggregation mandates compel warehouse operators to validate parent-child serialization relationships. The Rhine-Ruhr logistics corridor hosts concentrated retrofit activity as distribution centers modernize pallet handling lines for downstream compliance.
United States
FDA Drug Supply Chain Security Act deadlines force pharmaceutical distributors to deploy serialization-capable labeling infrastructure. Cold-chain logistics expansion for biologics storage tightens adhesive performance specifications in freezer-grade applications. The New Jersey-Pennsylvania pharmaceutical distribution belt concentrates demand for validated systems with inline barcode verification.
Brazil
ANVISA track-and-trace alignment requirements create parallel equipment demand for exporters serving Latin American markets. Warehouse operators face compressed implementation timelines with constrained capital budgets favoring semi-automatic configurations. São Paulo state anchors pharmaceutical distribution infrastructure where multinational manufacturers are qualifying serialization systems ahead of enforcement phases.
Netherlands
Contract logistics operators aggregate compliance spend across multiple pharmaceutical manufacturer clients, standardizing equipment specifications at scale. REACH chemical restrictions on adhesive formulations drive qualification of alternative chemistries for cold-chain applications. The Rotterdam-Antwerp distribution hub concentrates inkjet retrofit activity as operators seek ribbon cost reduction while maintaining EU FMD compliance.
South Korea
MFDS serialization phase-in through 2025 creates a defined replacement window for pallet labeling infrastructure. Pharmaceutical exporters must duplicate EU-equivalent aggregation capabilities to serve domestic distribution networks. The Incheon free economic zone hosts concentrated system commissioning activity as warehouse operators align with staged regulatory implementation.
Pallet Labeler Market Competitive Landscape
Industrial conglomerates and specialized printing equipment manufacturers split the market between scale-driven system integration and technology-specific component depth. The vendor base organizes around three strategic archetypes: diversified industrial technology holding companies with extensive service networks, pure-play marking and coding specialists with concentrated R&D in imaging technologies, and regional machinery fabricators serving mid-tier manufacturing flexibility requirements. Dominant competitive moves include technology licensing partnerships to access printhead supply and backward integration into labelstock formulation to capture adhesive specification premiums.
Among diversified industrial technology holding companies, Zebra Technologies Corporation and Honeywell International Inc. occupy positions anchored by extensive channel networks and recurring service contract penetration. SATO Holdings Corporation exemplifies the pure-play marking specialist archetype with concentrated expertise in thermal transfer durability. Domino Printing Sciences plc sits within the imaging technology leadership tier, representing inkjet system convergence with inline verification capabilities.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Markem-Imaje Corporation |
| Avery Dennison Corporation |
| Weber Packaging Solutions |
| Videojet Technologies Inc. |
| Domino Printing Sciences plc |
| Cab Produkttechnik GmbH & Co KG |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr logistics corridor anchors European print-and-apply system capacity, with German conveyor-integrators and Dutch contract manufacturers holding pricing leverage over pharmaceutical exporters facing EU FMD aggregation deadlines. Their concentrated engineering capacity allows premium positioning for validated systems with inline barcode verification, while buyers in Brazil and India encounter sharper cost constraints that favor modular retrofit configurations over integrated investments.
Pricing Analysis
Aftermarket service contracts and printhead replacement programs generate the dominant lifetime value streams in pallet labeling equipment. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-validated systems with FDA and EMA documentation from general warehouse configurations. Cost compression in mid-tier automatic labelers is intensifying because inkjet retrofits eliminate thermal transfer ribbon expenditure. Third-party logistics providers in the Netherlands exhibit the lowest price sensitivity, while Brazilian warehouse operators face acute budget constraints.
Supply Chain Analysis
Japanese and German component suppliers dominate precision thermal and piezo-electric printhead manufacturing, with additional module assembly concentrating in China and Taiwan. System builders draw from stainless steel and aluminum alloy feedstock for corrosion-resistant conveyor frames, alongside pressure-sensitive labelstock with acrylic adhesive formulations. Single-source vulnerability in printhead supply creates structural risk for equipment lead times. Distribution runs through authorized channel partners and direct sales forces serving pharmaceutical distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineers capable of reconciling line-level serialization with pallet aggregation logic remain scarce, extending deployment timelines and inflating implementation costs for pharmaceutical compliance projects. This capability gap shapes competitive positioning across equipment tiers.
For Market Incumbents: Entrench market position through backward integration into labelstock formulation to capture adhesive specification premiums driven by REACH restrictions. Lock in pharmaceutical distributors with multi-year service contracts covering printhead replacement and validation documentation updates. Counter inkjet substitution threats by demonstrating thermal transfer durability in freezer-grade biologics applications.
For New Entrants and Emerging Players: Build out modular inkjet retrofit kits targeting Dutch and Belgian contract logistics operators seeking ribbon cost reduction without line replacement. Focus initial penetration on semi-automatic configurations for Brazilian warehouse operators facing ANVISA deadlines with constrained capital budgets. Pursue channel partnerships with regional machinery fabricators rather than direct sales investment.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because serialization mandates are non-discretionary and expansionary across jurisdictions. Target acquisition candidates with validated FDA and EMA documentation libraries that accelerate customer compliance timelines. Monitor MFDS enforcement phase progression in South Korea as inflection indicator for replacement demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Captures REACH-driven specification premiums for cold-chain pharmaceutical pallets. |
| Inkjet-Vision System Convergence | Enables single-pass compliance labeling with reduced mechanical complexity for high-throughput hubs. |
| Third-Party Logistics Channel Development | Aggregates compliance spend across multiple pharmaceutical manufacturer clients at scale. |
| Multi-Jurisdiction Certification Investment | Satisfies simultaneous EU MDR, FDA DSCSA, and ANVISA requirements without redundant equipment. |
| Service Contract Unbundling | Creates discrete revenue streams for installation commissioning and ongoing maintenance separately. |
Research Methodology
Operator-level perspectives from warehouse managers, pharmaceutical compliance officers, third-party logistics procurement leads, and system integration engineers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through FDA guidance documents, EMA regulatory filings, ANVISA technical notices, and customs trade data for labeling equipment imports. Bottom-up equipment unit economics triangulated against top-down market sizing from pharmaceutical distribution network expansion.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning technology type, automation tier, end-use vertical, label durability grade, and regional regulatory cluster. CAGRs derived from equipment replacement cycles tied to serialization mandate phase-ins and cold-chain logistics expansion rates. Forecast inputs incorporated pharmaceutical distribution center buildout pipelines and REACH chemical restriction timelines affecting adhesive formulations.
Practitioners should monitor regulatory enforcement phase delays, printhead supply disruptions, and stainless steel commodity volatility for early signals of forecast revision. Quarterly review of pharmaceutical serialization mandate adherence rates and contract logistics operator capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Block Pallets Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Canada Pallets Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market