
 Stretch Hood Pallet Wrapping Market | 2026-2036
Stretch Hood Pallet Wrapping Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Hood Pallet Wrapping Market Outlook
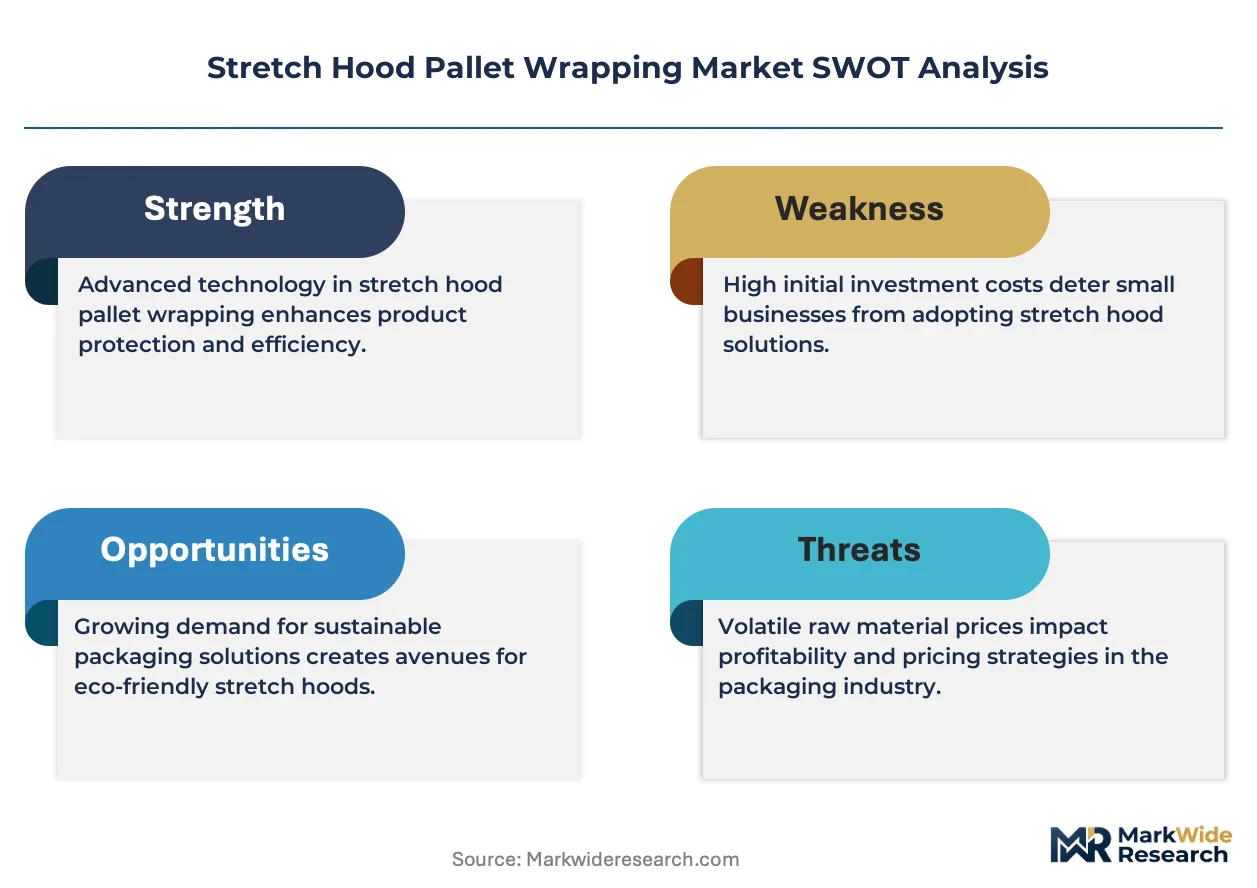
A capital-intensity divergence between integrated resin producers and film converters is rotating competitive advantage toward backward-integrated suppliers. Manuli Stretch S.p.A. leverages captive polyethylene extrusion capacity to sustain margin compression in commodity grades. Berry Global Inc. anchors its position through geographic dominance across North American beverage bottling corridors. Intertape Polymer Group Inc. differentiates via specialized high-performance films for chemical pallet loads.
Stretch hood pallet wrapping refers to a unitization method where a tubular film sleeve is stretched over a palletized load and heat-sealed at the base, typically employing linear low-density polyethylene resins at 25-150 micron gauges to secure goods during transit and storage. The technique replaces conventional stretch wrapping by eliminating top-sheet requirements and reducing total film consumption per pallet. Polyethylene formulations dominate product type segmentation due to established supply chains and recyclability credentials, while polypropylene grades capture niche applications demanding higher puncture resistance. Automated technology leads installation value given throughput requirements at beverage and chemical facilities, though semi-automated systems retain share among mid-scale warehousing operations serving fragmented retail distribution networks.
The EPA regulates plastic film manufacturing emissions under Clean Air Act provisions, while ISO 9001 and ISO 14001 certifications shape supplier qualification protocols for multinational logistics contracts. REACH compliance in European jurisdictions restricts certain phthalate plasticizers, redirecting formulation development toward non-orthophthalate alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and resin recycling infrastructure investments to anticipate feedstock cost trajectories and compliance positioning.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing virgin resin demand while automated beverage bottling corridors in Germany accelerate throughput requirements beyond semi-automated system capacity.
Growth Catalysts
- Recycled content mandates:The EU Packaging and Packaging Waste Regulation forces converters to source post-consumer polyethylene, creating captive demand for chemically recycled resins.
- Automotive export density:German automotive and chemical exporters operate automated packaging corridors requiring 200+ pallets per hour throughput.
- Linear low-density polyethylene advances:Next-generation metallocene catalysts enable 30% gauge reduction without puncture resistance loss.
Market Restraints
- Ethylene feedstock volatility:Naphtha crackers in the US Gulf Coast and Northwest Europe face margin compression from natural gas price spreads.
- Resin producer concentration:Five integrated polyethylene suppliers control 70% of European LLDPE supply for film extrusion.
- Mechanical recycling contamination:Multi-layer barrier films and printing inks degrade post-consumer polyethylene pellet quality.
Strategic Opportunities
- Underpenetrated chemical logistics:Indian and Southeast Asian chemical exporters still rely on manual stretch wrapping for pallet loads.
- Mass balance certification:ISCC PLUS certification enables premium pricing for chemically recycled content in EU-bound shipments.
- AI-driven film optimization:Machine vision systems paired with dynamic stretch algorithms reduce film consumption per pallet by 15-20%.
Industry Challenges
- Automation integration complexity:Legacy warehouse management systems in mid-scale European 3PLs lack API connectivity for stretch hood line controllers.
- Metallized film contamination:Detection and removal of aluminum oxide barrier layers complicates mechanical recycling feedstock preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Hood Pallet Wrapping Market |
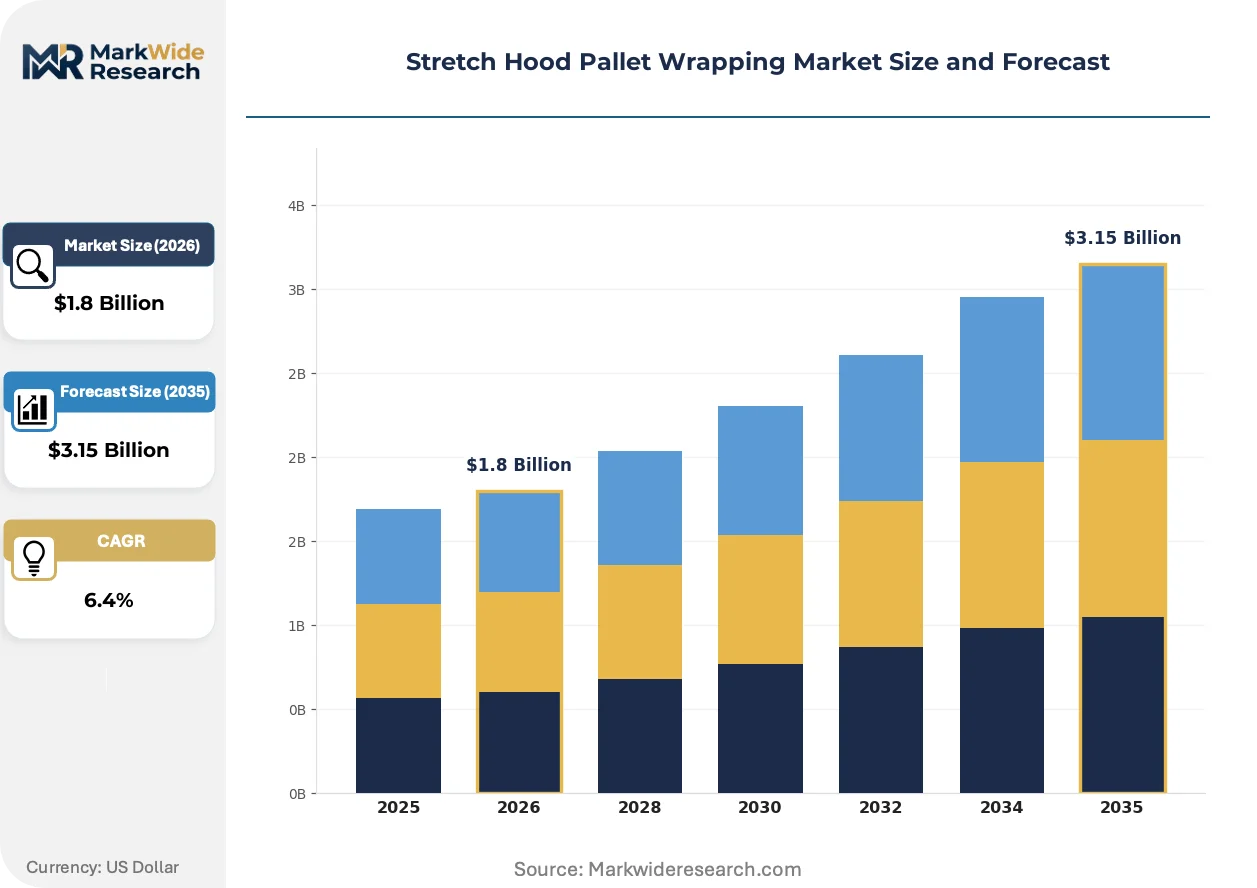
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others Application: Food & Beverage, Pharmaceuticals, Consumer Goods, Chemicals End User: Retail, Logistics, Manufacturing, Warehousing Technology: Automated, Manual, Semi-Automated, Integrated |
| Companies Covered | Intertape Polymer Group Inc., Manuli Stretch S.p.A., Amcor, RKW Group, Paragon Films Inc., Signode, Coveris Holdings S.A., Innova, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Hood Pallet Wrapping Market Strategic Shifts
Material science advances and regulatory pressure on plastic waste are splitting the market between commodity recyclability and high-performance barrier requirements.
Mono-material polyethylene formulations with enhanced puncture resistance are bifurcating the product landscape. Beverage bottlers in Germany and the Netherlands adopt these grades for automated lines running 150+ pallets hourly. The technology is bifurcating converter margins between premium certified-recyclable grades and legacy multi-layer films facing extended producer responsibility penalties.
REACH restrictions on orthophthalate plasticizers redirect formulation development toward bio-based and non-phthalate alternatives. ECHA substance evaluation dossiers force compounders to requalify food-contact stretch hoods for dairy and meat exports. European film converters accelerate migration testing investments to maintain multinational logistics contracts.
Shippers now specify ISCC PLUS or equivalent mass balance certification as a gate criterion for pallet wrapping film procurement. Tier-one automotive suppliers in Bavaria and Baden-Württemberg reject uncertified virgin resin shipments. This certification-driven preference shift concentrates demand among backward-integrated suppliers with pyrolysis partnerships.
Stretch Hood Pallet Wrapping Market Segmentation
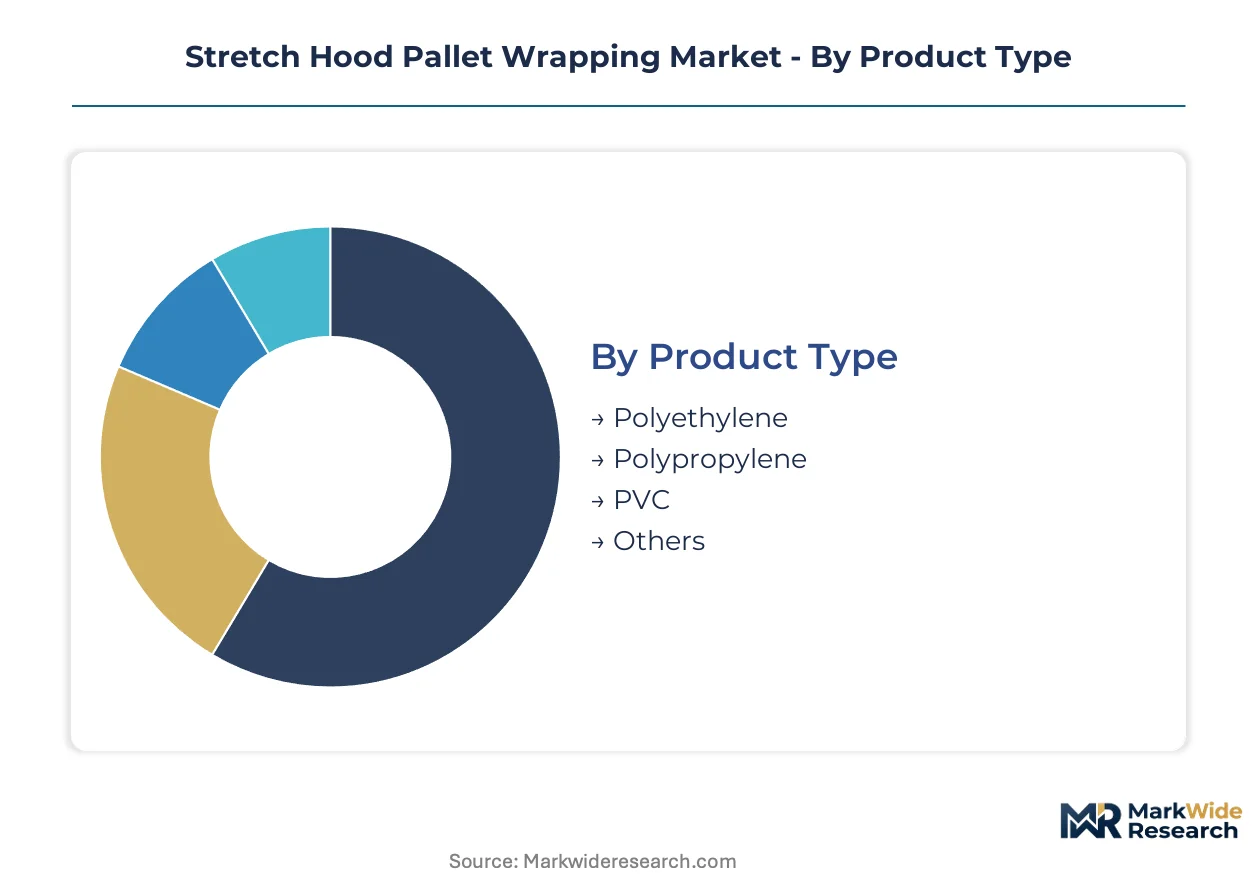
Segmentation in stretch hood pallet wrapping reveals how resin chemistry, automation intensity, and end-use requirements partition margin capture across the value chain. Film gauge specifications and throughput demands create distinct supplier qualification tiers that reshape competitive positioning.
Product Type:
Margin pools concentrate in specialized resin grades where formulation expertise and recycling certification create pricing power.
- Polyethylene:Linear low-density polyethylene resins at 25-150 micron gauges dominate automated beverage and chemical corridors. German automotive exporters specify metallocene-catalyzed grades for 200+ pallets per hour throughput, with REACH-compliant non-phthalate plasticizers now mandatory for EU-bound shipments.
- Polypropylene:Higher puncture resistance captures chemical pallet loads with abrasive surface characteristics. Indian and Southeast Asian chemical exporters are converting from manual wrapping, driving demand for biaxially oriented grades that withstand stacking stress during containerized export.
- PVC:Legacy applications in corrosion-sensitive chemical storage retain niche demand despite recyclability penalties under extended producer responsibility frameworks.
- Others:Bio-based and chemically recycled alternatives are emerging for ISCC PLUS-certified shipments to Bavarian tier-one automotive suppliers.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
Application:
Cost tier differentiation separates high-volume beverage automation from specialized pharmaceutical barrier requirements.
- Food & Beverage:Dairy and meat exports drive ECHA-mandated migration testing investments. Dutch bottlers running 150+ pallets hourly specify mono-material polyethylene formulations to avoid extended producer responsibility penalties.
- Chemicals:Puncture-resistant films secure pallet loads of fertilizers, agrochemicals, and industrial intermediates. Southeast Asian exporters still rely heavily on manual stretch wrapping, creating conversion headroom for automated hood systems.
- Pharmaceuticals:Barrier specifications against moisture and oxygen ingress command premium pricing.
- Consumer Goods:Mid-scale warehousing operations serve fragmented retail distribution with semi-automated systems.
Food & Beverage commands the steepest expansion trajectory. Chemicals is climbing the fastest in absolute volume terms.
End User:
Customer type determines whether procurement prioritizes throughput maximization or capital expenditure minimization.
- Logistics:Third-party logistics operators in mid-scale European markets face automation integration complexity from legacy warehouse management systems lacking API connectivity for stretch hood line controllers.
- Manufacturing:Integrated production facilities specify captive film supply from backward-integrated resin producers to manage feedstock cost volatility.
- Retail:Fragmented distribution networks sustain semi-automated system share.
- Warehousing:High-turnover operations prioritize AI-driven film optimization with machine vision systems.
Logistics holds installed capacity. Manufacturing is rotating up the share rankings.
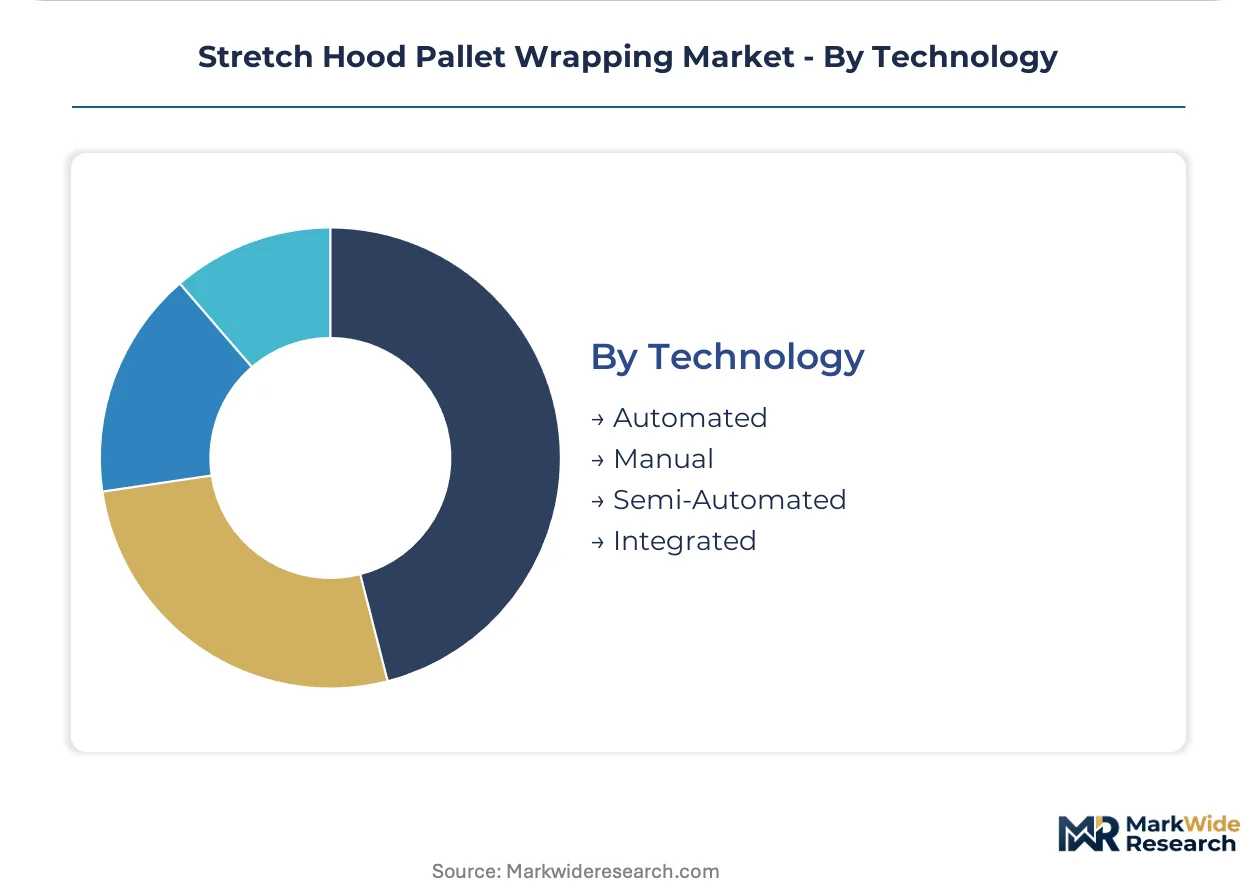
Technology:
Maturity gradients separate established automated corridors from emerging semi-automated adoption curves.
- Automated:Throughput requirements at German beverage and chemical facilities exceed 200 pallets per hour. Dynamic stretch algorithms paired with machine vision reduce film consumption by 15-20%.
- Semi-Automated:Mid-scale warehousing operations serving fragmented retail networks retain significant share due to lower capital barriers.
- Manual:Indian and Southeast Asian chemical exporters still rely on hand-applied stretch wrapping, representing underpenetrated conversion potential.
- Integrated:Line controllers with warehouse management system connectivity command premium positioning for new facility builds.
Automated holds installed capacity. Semi-Automated is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beverage bottlers run automated hood systems at 200 pallets per hour, while Indian chemical exporters still wrap pallets manually. This consumption-mix differential splits regional investment priorities between throughput maximization and first-time automation conversion.
Germany
Automotive and chemical exporters in Bavaria and Baden-Württemberg drive demand for metallocene-catalyzed polyethylene grades. The EU Packaging and Packaging Waste Regulation mandates post-consumer recycled content, forcing converters to source chemically recycled resins. Stuttgart's packaging corridors now reject uncertified virgin resin shipments.
United States
Beverage bottling facilities across the Midwest and Southeast prioritize AI-driven film optimization systems. EPA Clean Air Act provisions regulate emissions from LLDPE extrusion operations. Chicago's logistics hubs deploy dynamic stretch algorithms paired with machine vision to cut film consumption per pallet.
China
Chemical and consumer goods manufacturers in the Yangtze River Delta scale automated installations for export palletization. MIIT industrial standards govern plastic film quality certifications for food-contact applications. Shanghai's port logistics operators specify mono-material formulations to meet EU-bound shipment requirements.
India
Fertilizer and agrochemical exporters in Gujarat and Maharashtra represent underpenetrated conversion headroom from manual wrapping. The country's national packaging regulator enforces BIS quality standards for plastic films. Mumbai's chemical logistics corridors still rely predominantly on hand-applied stretch systems.
Netherlands
Dairy and meat exporters in Rotterdam's port hinterland drive ECHA-mandated migration testing investments for food-contact stretch hoods. REACH restrictions on orthophthalate plasticizers redirect formulation development toward non-phthalate alternatives. Dutch bottlers specify mono-material polyethylene to avoid extended producer responsibility penalties.
Stretch Hood Pallet Wrapping Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in stretch hood pallet wrapping supply. Backward-integrated resin producers with captive polyethylene extrusion capacity command pricing power in commodity grades, while film converters lacking upstream control face margin compression from feedstock volatility. The market organizes around three archetypes: integrated petrochemical suppliers, geographic-scale converters, and performance-specialist compounders. Dominant competitive moves include pyrolysis partnerships for chemical recycling certification and machine vision integration for film optimization.
Among integrated suppliers, Manuli Stretch S.p.A. exemplifies the backward-integrated archetype through captive resin production. Berry Global Inc. anchors the geographic-scale tier with North American beverage corridor dominance. Intertape Polymer Group Inc. occupies a position within the performance-specialist segment, representing high-performance film formulation expertise for demanding chemical pallet loads.
| Leading Market Players |
|---|
| Intertape Polymer Group Inc. |
| Manuli Stretch S.p.A. |
| Amcor |
| RKW Group |
| Paragon Films Inc. |
| Signode |
| Coveris Holdings S.A. |
| Innova |
| Berry Global Inc. |
| Others |
Value Chain & Pricing Dynamics
Metallocene-catalyzed polyethylene substitution for conventional LLDPE grades simultaneously shifts supply geography toward German resin corridors and compresses pricing economics for non-specialized converters. This chemistry migration rewards backward-integrated suppliers with captive extrusion capacity while squeezing margin pools for film converters exposed to spot resin markets.
Pricing Analysis
After-market service contracts for stretch hood line maintenance and film optimization software subscriptions now drive lifetime customer value beyond initial equipment sales. Three-tier pricing structure across ISCC PLUS-certified premium, REACH-compliant standard, and uncertified economy grades separates procurement tiers. Cost compression in commodity polyethylene grades is intensifying because naphtha cracker margin spreads favor integrated producers. Small-scale warehousing operators serving fragmented retail networks exhibit highest price sensitivity, while German automotive exporters prioritize throughput reliability over unit film cost.
Supply Chain Analysis
Rotterdam port transit and Rhine corridor barge underwrites European resin distribution efficiency for stretch hood film supply. Raw material sourcing draws from Saudi ethane crackers, US Gulf Coast naphtha facilities, and Northwest European integrated petrochemical complexes. Feedstock volatility from natural gas price spreads creates structural risk for non-integrated converters. Distribution runs through converter-direct relationships with beverage bottling corridors and third-party logistics operators managing automated packaging lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states on extended producer responsibility implementation creates niche opportunities for certified-recyclable film specialists. This demand-side shift rewards players who front-run compliance rather than follow baseline mandates.
For Market Incumbents: Consolidate pyrolysis partnerships for chemical recycling certification to defend against emerging resin producers with mass balance credentials. Add metallocene catalyst capacity in German production corridors to capture automotive exporter specification lock-in. Prioritize API connectivity investments for legacy warehouse management system integration.
For New Entrants and Emerging Players: Lead with AI-driven film optimization systems targeting mid-scale European third-party logistics operators struggling with automation integration complexity. Capture conversion headroom in Indian and Southeast Asian chemical export corridors still reliant on manual stretch wrapping. Position through machine vision bundling with semi-automated hood system sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed film converters lacking upstream resin integration. Five-to-ten year viability hinges on feedstock cost pass-through mechanics and certification portfolio breadth. Watch for ISCC PLUS certification penetration rates in Bavarian tier-one automotive supplier procurement as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Partnership Formation | Chemical recycling certification unlocks premium pricing for EU-bound automotive shipments. |
| Machine Vision Integration | Dynamic stretch algorithms reduce film consumption per pallet at Dutch bottling facilities. |
| Metallocene Capacity Expansion | Gauge reduction capabilities capture German automotive corridor specification requirements. |
| API Connectivity Development | Warehouse management system integration addresses mid-scale European logistics automation gaps. |
| Mass Balance Certification | ISCC PLUS credentials become gate criterion for Stuttgart packaging corridor procurement. |
Study Parameters
Cross-validation between primary interviews with plant engineers at beverage bottling facilities and secondary analysis of customs trade data anchors the qualitative findings. Conversations with procurement leads at German automotive exporters, technical R&D directors at film converters, aftermarket service heads at equipment OEMs, and distribution channel partners in chemical logistics informed demand-side dynamics. Secondary sources included SEC 10-K filings from integrated packaging suppliers, Cefic resin production reports, EPA Clean Air Act enforcement databases, and ECHA substance evaluation dossiers. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and technology segments.
Sensitivity analysis around ethylene feedstock price trajectories and recycled content mandate enforcement timelines shapes the projection framework. The analytical framework models polyethylene versus polypropylene resin chemistry splits, automated versus semi-automated technology adoption curves, food and beverage versus chemical end-use intensity, and geographic production hub concentration. CAGRs were derived from segment-level volume build-ups applied to pricing tier assumptions. Industry-specific forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation pace and metallocene catalyst penetration in European extrusion capacity.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or naphtha-to-ethane feedstock cost inversion would require recalibration. Forecasts reflect assumptions on resin recycling infrastructure build-out rates and automation capital expenditure cycles at mid-scale warehousing operations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Pallet Jacks Market