
 Italy Pallets Market | 2026-2036
Italy Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Pallets Market Insights
The EU Green Deal is broadening demand for sustainably sourced pallet materials across Italian supply chains. Martini Alfredo S.p.A. leverages its domestic manufacturing footprint to serve premium food exporters requiring ISPM-15 certified wooden pallets. Toppy anchors automation-adjacent pallet handling systems for pharmaceutical distribution centers in Lombardy. Capp-Plast S.r.l. specializes in hygienic plastic pallet formats that compete for pharmaceutical and dairy sector contracts.
A pallet is a portable platform, typically constructed from wood, plastic, or metal, designed to support goods during storage, handling, and transport via forklifts or pallet jacks; standard Euro pallets measure 1200 mm by 800 mm and must withstand dynamic loads exceeding one metric ton. Wooden pallets retain dominant share in Italy due to low unit cost and repairability, though plastic pallets are gaining traction in pharmaceutical and cold-chain applications where washability and dimensional consistency matter. Food and beverage applications absorb the largest volume of pallet flows, while custom-size segments command margin premiums from specialized machinery and automotive exporters. Heavy-duty pallets occupy a niche but defendable position in steel and construction material logistics.
Italy's pallet sector operates under EU REACH chemical safety standards for plastic resin compositions, alongside national fire safety protocols enforced by the Ministry of the Interior for warehouse storage density. ISPM-15 phytosanitary rules, administered through regional forestry authorities, govern heat treatment requirements for wooden pallets in international trade. Stakeholders must weigh timber certification costs against plastic pallet lifecycle claims as buyer audit requirements tighten across European retail and pharmaceutical procurement codes.
Market Dynamics
EU Green Deal packaging sustainability mandates are compressing demand toward certified timber and recycled plastic formats across Italian supply chains, forcing converters to absorb certification costs while defending unit economics against lower-cost Eastern European imports.
Growth Catalysts
- ISPM-15 Compliance:Phytosanitary heat-treatment rules administered through regional forestry authorities are locking in domestic wooden pallet demand for food and beverage exporters serving non-EU markets.
- Cold-Chain Expansion:Italian pharmaceutical distributors in Lombardy are scaling hygienic plastic pallet deployments to meet temperature-integrity requirements for biologics distribution.
- Northern Industrial Corridor Concentration:Manufacturing density across Milan, Turin, and Bologna generates pooled procurement volumes that justify automation-adjacent pallet handling investments.
Market Restraints
- Timber Input Volatility:Softwood lumber prices fluctuate with Baltic supply disruptions, compressing margins for domestic wooden pallet producers unable to pass through cost swings.
- Plastic Resin Cost Exposure:EU REACH chemical safety standards for plastic resin compositions add compliance overhead that disadvantages small-batch recycled plastic converters against virgin-material competitors.
- Eastern European Supply Competition:Lower-cost pallet manufacturers in Poland and Romania capture price-sensitive volume from Italian logistics providers serving pan-European distribution networks.
Strategic Opportunities
- Central-Southern Underpenetration:Campania and Sicily logistics hubs remain underserved by ISPM-15 certified domestic production, creating whitespace for regional manufacturing footprint expansion.
- EU CSRD Reporting Tailwind:Corporate sustainability disclosure requirements are elevating buyer preference for lifecycle-documented pallet formats with verified recycled content claims.
- Rental-Pool Model Convergence:Shared pallet pooling systems combining RFID tracking with pay-per-use pricing are penetrating automotive and retail verticals previously dominated by outright purchase.
Industry Challenges
- ISPM-15 Certification Timeline Compression:Regional forestry authority inspection backlogs delay heat-treatment certification for wooden pallet exporters, constraining just-in-time delivery commitments to non-EU markets.
- Automation Integration Complexity:Pharmaceutical distribution centers in Lombardy face retrofit costs when legacy pallet dimensions conflict with robotic handling system specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Pallets Market |
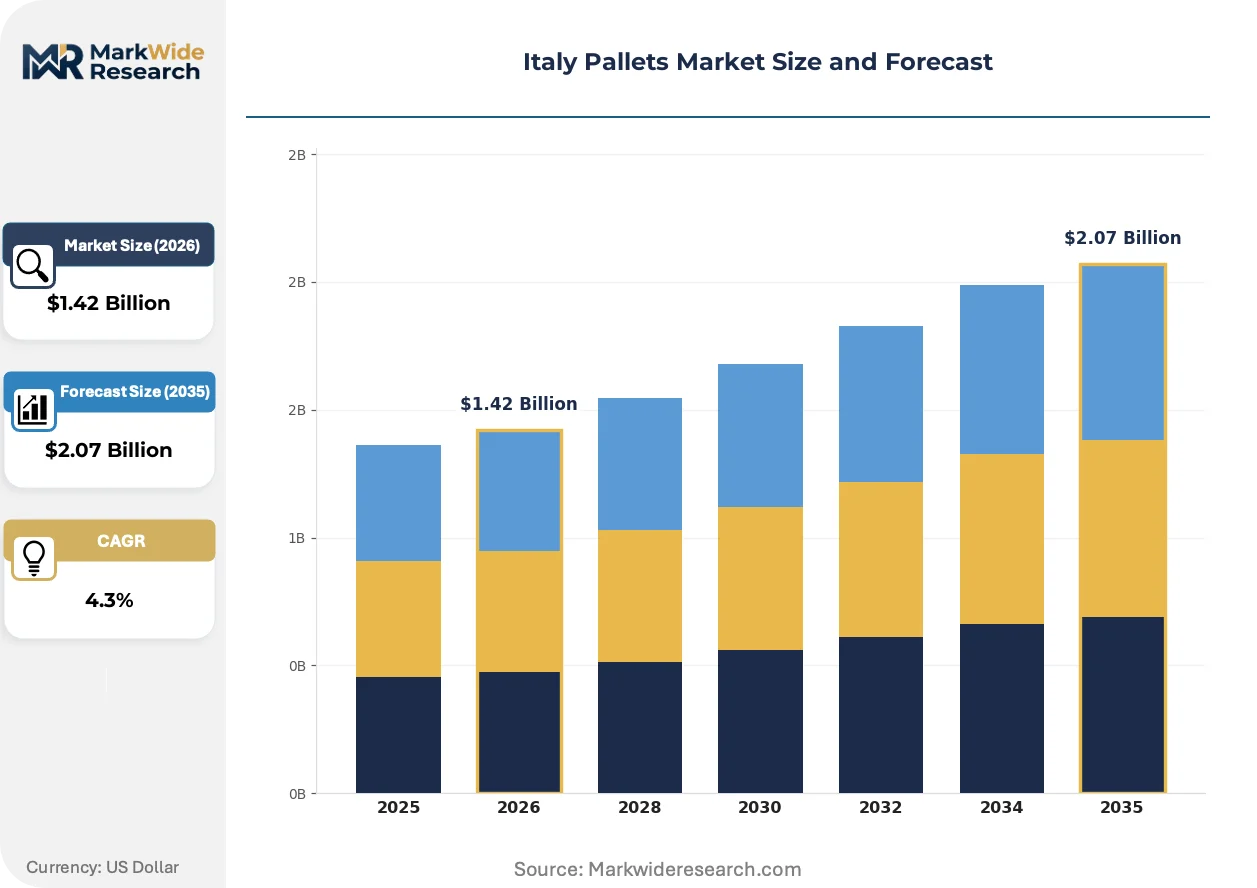
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.07 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wooden, Plastic, Metal, Corrugated Application: Food & Beverage, Pharmaceuticals, Electronics, Retail End User: Manufacturers, Distributors, Wholesalers, Exporters Size: Standard, Custom, Heavy-duty, Lightweight |
| Companies Covered | Martini Alfredo S.p.A., Toppy, Monoflo International, Orbis Investment Management Limited, Port Erie Plastics, The Nelson Company, Capp-Plast S.r.l., Buckhorn Inc., US Plastic Pallets & Handling, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Pallets Market Trends and Innovations
Italian pallet markets are experiencing material-format divergence as sustainability compliance and automation requirements pull demand toward specialized solutions, compressing the middle tier of undifferentiated commodity supply.
RFID-embedded plastic pallets are consolidating track-and-trace capabilities into unit-load infrastructure. Pharmaceutical distributors in Emilia-Romagna are adopting these formats at accelerated pace to satisfy serialization mandates. The technology is consolidating visibility-layer value previously captured by separate logistics software providers into the physical pallet asset itself.
EU Green Deal packaging sustainability requirements are tightening recycled-content thresholds for plastic formats entering European supply chains. Italian converters must document post-consumer resin percentages through mass-balance certification. Dairy and pharmaceutical cold-chain applications face the steepest compliance ramps, driving specification changes ahead of the 2030 target horizon.
Buyer preference is rotating toward lifecycle-service contracts that bundle pallet supply with reverse logistics and hygiene maintenance. Large food retailers are displacing spot procurement with multi-year agreements covering pool management and damage replacement. This shift concentrates most visibly in the northern industrial corridor where buyer scale supports vendor consolidation.
Italy Pallets Market Segmentation
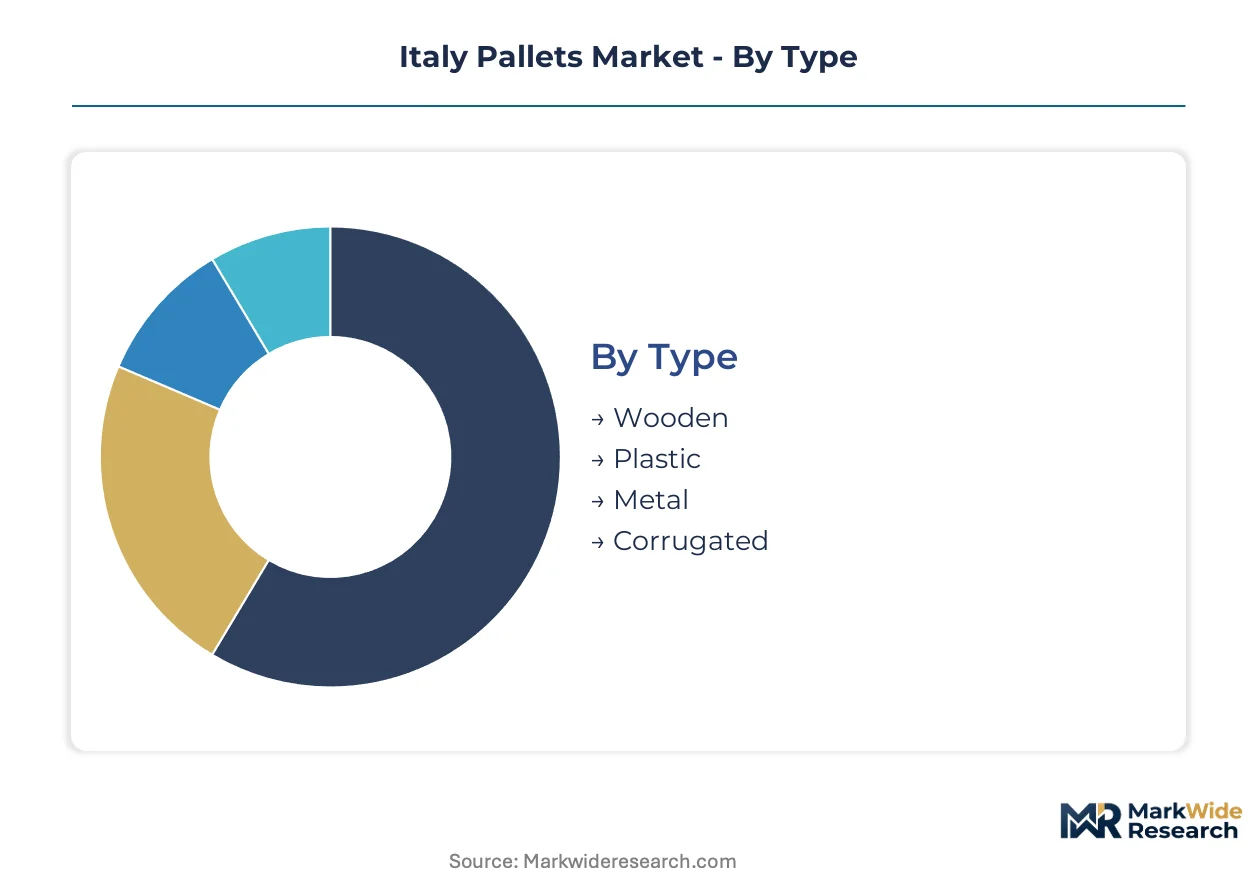
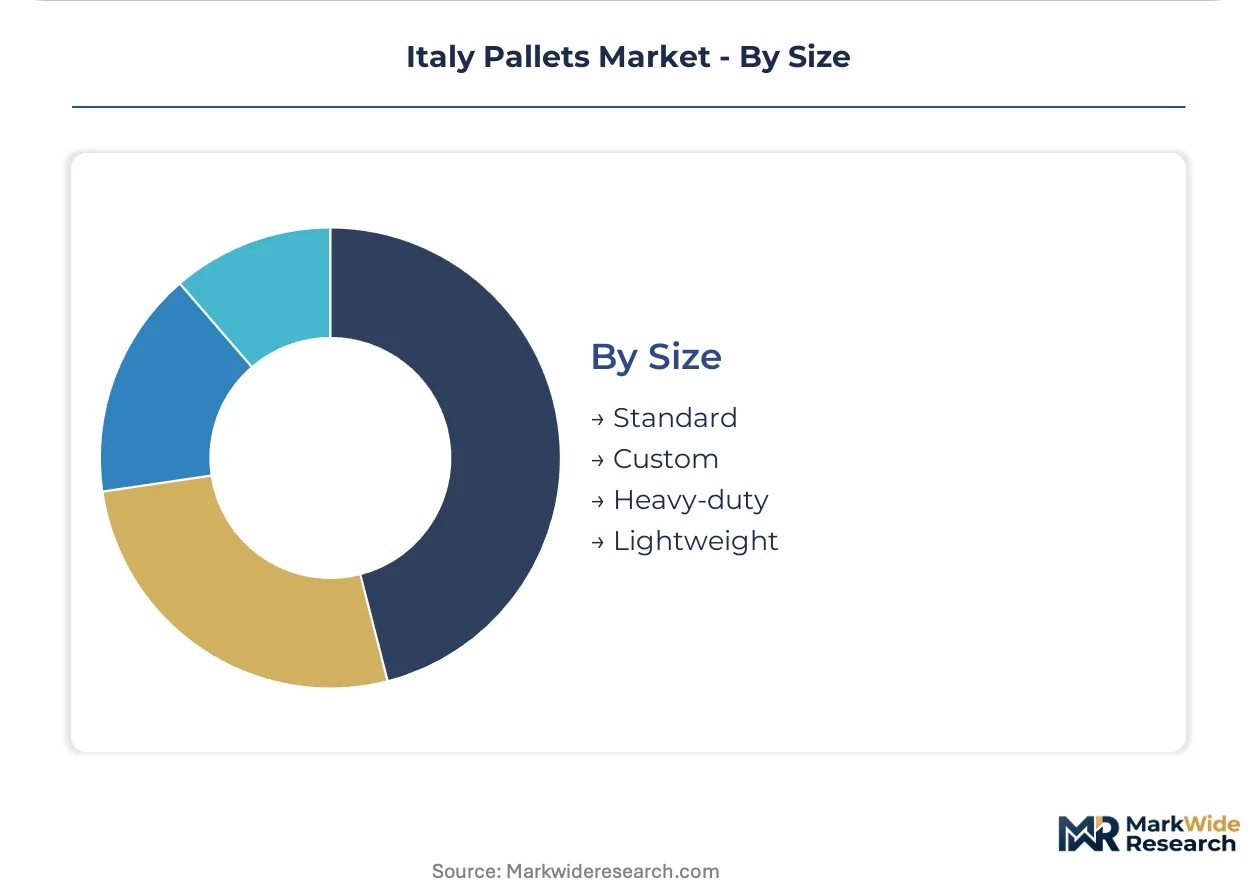
Pallet specification choices in Italy trace directly to regulatory exposure and automation readiness. Material selection, application vertical, and dimensional standards each carry distinct compliance burdens that reshape procurement priorities across the northern industrial corridor.
Type:
Material categories divide sharply between standalone commodity formats and embedded systems requiring certification layering.
- Wooden:Heat-treated softwood construction satisfies ISPM-15 phytosanitary mandates for non-EU export corridors. Regional forestry authority bottlenecks in Lombardy and Emilia-Romagna constrain certification velocity for food and beverage exporters serving Middle Eastern and North African markets.
- Plastic:Injection-molded HDPE and PP resins deliver dimensional consistency for automated pharmaceutical handling systems in Milan-Turin distribution clusters. EU REACH compliance on resin compositions elevates documentation costs for small-batch recycled-content producers competing against virgin-material imports.
- Metal:Steel and aluminum formats serve closed-loop automotive component logistics with extreme load ratings. Limited penetration outside captive OEM supply chains reflects weight penalties and corrosion management costs.
- Corrugated:Fiberboard disposable pallets target lightweight retail display shipments with minimal return logistics. Single-use economics restrict adoption to promotional and seasonal product flows.
Volume placements concentrate in Wooden formats; the faster expansion belongs to Plastic.
Application:
End-use verticals stratify by hygiene intensity and temperature-control requirements.
- Food & Beverage:Cold-chain compliance for dairy and wine exports drives specification toward ISPM-15 certified wood and washable plastic alternatives. Northern Italian processing clusters generate pooled procurement volumes that justify pallet pooling system investments.
- Pharmaceuticals:Biologics distribution in Lombardy demands RFID-embedded plastic pallets with serialization track-and-trace integration. Temperature-integrity mandates from EMA guidelines reshape handling infrastructure specifications.
- Electronics:Static-control and shock-absorption requirements favor plastic and corrugated formats for semiconductor and consumer device logistics. Limited domestic production of ESD-grade pallets creates import dependency.
- Retail:Fast-moving consumer goods distributors balance unit economics against display-ready presentation standards. Private-label consolidation among northern Italian retailers drives standardization toward Euro pallet dimensions.
Food & Beverage absorbs the largest shipment volumes; Pharmaceuticals is climbing the fastest on automation and compliance tailwinds.
End User:
Procurement authority sits at different supply chain nodes depending on shipment ownership structure.
- Manufacturers:Captive pallet fleets dominate automotive and machinery producers in Turin and Bologna industrial zones. Vertical integration into in-house repair and heat-treatment facilities defends against certification delays.
- Distributors:Third-party logistics providers in Milan corridor operate mixed fleets serving multi-tenant pharmaceutical and food warehouses. Pallet pooling subscriptions displace outright purchase for mid-scale operators.
- Wholesalers:Price-sensitive procurement from Eastern European suppliers compresses margins for domestic wooden pallet producers serving commodity produce and dry goods flows.
- Exporters:ISPM-15 certification timelines directly constrain just-in-time delivery commitments to non-EU markets. Regional forestry authority inspection backlogs create operational risk for wine and specialty food shippers.
Manufacturers deploy the deepest captive fleets; Exporters face the steepest compliance-driven specification changes.
Size:
Dimensional categories map to load requirements and handling system compatibility.
- Standard:Euro pallet 1200 mm by 800 mm specifications dominate pan-European retail and automotive supply chains. Interchangeability requirements lock in procurement even where custom dimensions might optimize cube utilization.
- Custom:Machinery and automotive component exporters in Emilia-Romagna specify non-standard footprints for irregular loads. Engineering and tooling costs defend margin premiums against commodity competition.
- Heavy-duty:Steel-reinforced and thick-deck constructions serve construction materials and metal coil logistics. Niche positioning limits addressable market but insulates against price-driven substitution.
- Lightweight:Reduced-load corrugated and thin-wall plastic formats target air freight and parcel distribution weight restrictions. Durability trade-offs restrict reuse cycles and resale recovery.
Standard sizes command the broadest placement base; Custom specifications carry the highest margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Milan-Turin-Bologna industrial corridor concentrates Italy's pallet demand, with Lombardy alone absorbing the bulk of pharmaceutical and food distribution volumes. This northern density shapes procurement patterns and certification infrastructure across the peninsula.
Lombardy
Pharmaceutical distribution centers in Milan deploy RFID-embedded plastic pallets to meet EMA serialization mandates for biologics. EU REACH compliance on resin compositions elevates documentation costs for small-batch producers. The Milan hinterland generates pooled procurement volumes that justify automation-adjacent pallet handling investments from third-party logistics operators.
Piedmont
Automotive component manufacturers in Turin operate captive wooden pallet fleets with in-house heat-treatment facilities. ISPM-15 phytosanitary rules administered through regional forestry authorities constrain certification velocity for exporters serving North African markets. The Turin industrial zone defends against Eastern European supply competition through vertical integration into repair and certification infrastructure.
Emilia-Romagna
Dairy processors and wine exporters in Bologna and Modena drive demand for washable plastic alternatives alongside certified timber formats. The EU Green Deal's packaging sustainability requirements pressure converters toward mass-balance certification for recycled content claims. Food and beverage clusters in Parma and Reggio Emilia generate contract volumes that attract pallet pooling system operators.
Veneto
Prosecco and specialty food exporters in Treviso and Verona face ISPM-15 certification timeline compression from regional forestry authority inspection backlogs. The national Ministry of the Interior enforces warehouse fire safety protocols that limit storage density for untreated wooden pallet stocks. Port logistics in Venice and Trieste create transshipment demand for standard Euro pallet formats serving Central European distribution networks.
Lazio
Retail distribution hubs around Rome balance unit economics against display-ready presentation standards for fast-moving consumer goods. Private-label consolidation among central Italian retailers drives standardization toward Euro pallet dimensions. The Rome logistics corridor remains exposed to price-sensitive procurement from Eastern European suppliers serving pan-European distribution networks.
Italy Pallets Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and material-format dimensions. Wooden pallet specialists with ISPM-15 heat-treatment capabilities capture food and beverage export contracts, while plastic format providers serve pharmaceutical automation requirements. Three archetypes dominate: domestic certified-timber converters, hygiene-focused plastic molders, and automation-adjacent handling system integrators. Competitive moves concentrate on backward integration into timber sourcing and resin compounding, plus geographic expansion into underserved southern logistics corridors.
Among Italy-based specialists, Martini Alfredo S.p.A. and Capp-Plast S.r.l. occupy positions across the timber-to-plastic material spectrum, while Toppy anchors automation-adjacent handling systems for pharmaceutical distribution. These named entities exemplify how domestic manufacturing footprints defend against lower-cost Eastern European imports through certification proximity and service responsiveness. The archetype mix reflects a market pulled toward compliance-heavy export formats and automation-ready hygiene specifications, compressing the middle tier of undifferentiated commodity supply.
| Leading Market Players |
|---|
| Martini Alfredo S.p.A. |
| Toppy |
| Monoflo International |
| Orbis Investment Management Limited |
| Port Erie Plastics |
| The Nelson Company |
| Capp-Plast S.r.l. |
| Buckhorn Inc. |
| US Plastic Pallets & Handling |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISPM-15 heat-treated timber and EU REACH-compliant recycled plastics splits Italian pallet procurement into parallel cost structures. Premium food exporters absorb certification premiums for phytosanitary compliance, while pharmaceutical distributors pay hygiene premiums for dimensional consistency, with each tier feeding distinct supply chain configurations anchored in Lombardy versus Eastern European import corridors.
Pricing Analysis
Throughput-based pooling contracts now anchor pharmaceutical procurement in Milan-Turin distribution clusters, displacing spot purchasing. Three-tier pricing structure across ISPM-15 certified timber, virgin plastic, and mass-balance recycled formats reflects compliance documentation burdens. Cost compression in commodity wooden grades intensifies because Polish and Romanian producers undercut domestic heat-treatment overhead. Wholesalers serving produce flows exhibit highest price sensitivity; biologics distributors accept premium positioning for serialization-ready RFID formats.
Supply Chain Analysis
Single-source vulnerability sits with Baltic softwood suppliers feeding Lombardy sawmills. Raw material flows draw from Swedish, Finnish, and Romanian timber basins alongside German and Belgian resin compounding for plastic formats. Tariff exposure on Eastern European pallet imports threatens margin recovery for domestic converters. Distribution runs through Milan third-party logistics hubs with satellite pooling depots in Bologna and Turin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISPM-15 certification bottlenecks at regional forestry authorities constrain supply elasticity, propping pricing power for accredited domestic producers. This supply-constrained dynamic favors incumbents with captive heat-treatment infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into certified timber sourcing in Piedmont and Emilia-Romagna. Lock in multi-year pooling contracts with pharmaceutical distributors before RFID standardization commoditizes track-and-trace premiums. Regional forestry authority inspection delays threaten just-in-time export commitments; vertical control over heat-treatment capacity neutralizes this operational risk.
For New Entrants and Emerging Players: Third-party logistics providers represent the most penetrable channel partner type for pooling system penetration. Campania and Sicily logistics corridors offer whitespace with minimal ISPM-15 certified domestic production. Target dairy cooperatives in southern Italy with washability-focused plastic formats. A rental-pool go-to-market angle bypasses capital intensity barriers that block outright purchase competition.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap plastic molders possessing mass-balance certification infrastructure given EU Green Deal recycled-content mandates. Long-term viability hinges on automation-readiness for pharmaceutical handling specifications. Acquisition targets should demonstrate documented post-consumer resin supply chains. The signal to watch is EMA serialization mandate expansion beyond biologics into broader therapeutic categories.
| Strategic Initiative | Industry Significance |
|---|---|
| ISPM-15 Certification Infrastructure Expansion | Regional forestry authority partnerships in Lombardy and Emilia-Romagna defend export corridor access for food shippers. |
| Mass-Balance Recycled Content Certification | EU Green Deal compliance documentation unlocks pharmaceutical and dairy sector procurement against virgin plastic imports. |
| RFID-Embedded Format Development | EMA serialization mandates consolidate track-and-trace value into physical pallet assets for biologics distributors. |
| Southern Logistics Corridor Manufacturing Footprint | Campania and Sicily underpenetration offers first-mover positioning for ISPM-15 certified domestic production. |
| Pooled Rental System Platform Launch | Pay-per-use pricing penetrates automotive and retail verticals previously locked in outright purchase patterns. |
Research Methodology
Independent corroboration across pallet converter executives, third-party logistics procurement directors, pharmaceutical distribution operations managers, and regional forestry authority inspectors underwrites the qualitative findings. Secondary validation draws from EU REACH substance registration databases, Italian Ministry of the Interior fire safety protocols, ISPM-15 phytosanitary certification records, and customs trade flow documentation. Bottom-up demand modeling from end-use verticals triangulates against top-down supply capacity assessments across Lombardy, Piedmont, and Emilia-Romagna production clusters.
Rate-of-change decomposition separates volume expansion from mix-shift effects across material type, application vertical, and end-user procurement authority. Segmentation dimensions modeled include wooden versus plastic versus metal formats, food and beverage versus pharmaceutical versus automotive applications, and manufacturer captive fleets versus distributor pooled systems versus wholesaler spot procurement. CAGRs derive from elasticity-adjusted demand curves incorporating EU Green Deal compliance timeline assumptions and automation penetration rates in Lombardy pharmaceutical handling infrastructure.
Caveats apply where Baltic timber supply disruptions, regional forestry authority inspection backlog resolution, or EMA serialization mandate scope expansion could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and buyer procurement code evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
GCC Pallet Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
Pallet Bands Market