
 North America Adhesives Market | 2026-2036
North America Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Adhesives Market Analytics
UV-curable adhesive platforms is reconfiguring assembly line economics across electronics and medical device manufacturing in North America. Henkel AG & Co. KGaA leverages its radiation-curing expertise to dominate high-precision bonding for circuit board miniaturization. H.B. Fuller Company anchors its position through water-based polymer R&D intensity aimed at packaging converters seeking EPA compliance pathways. Dow competes on hydrocarbon feedstock integration, operating integrated acrylic monomer plants along the US Gulf Coast that extend cost advantages into pressure-sensitive tape formulations.
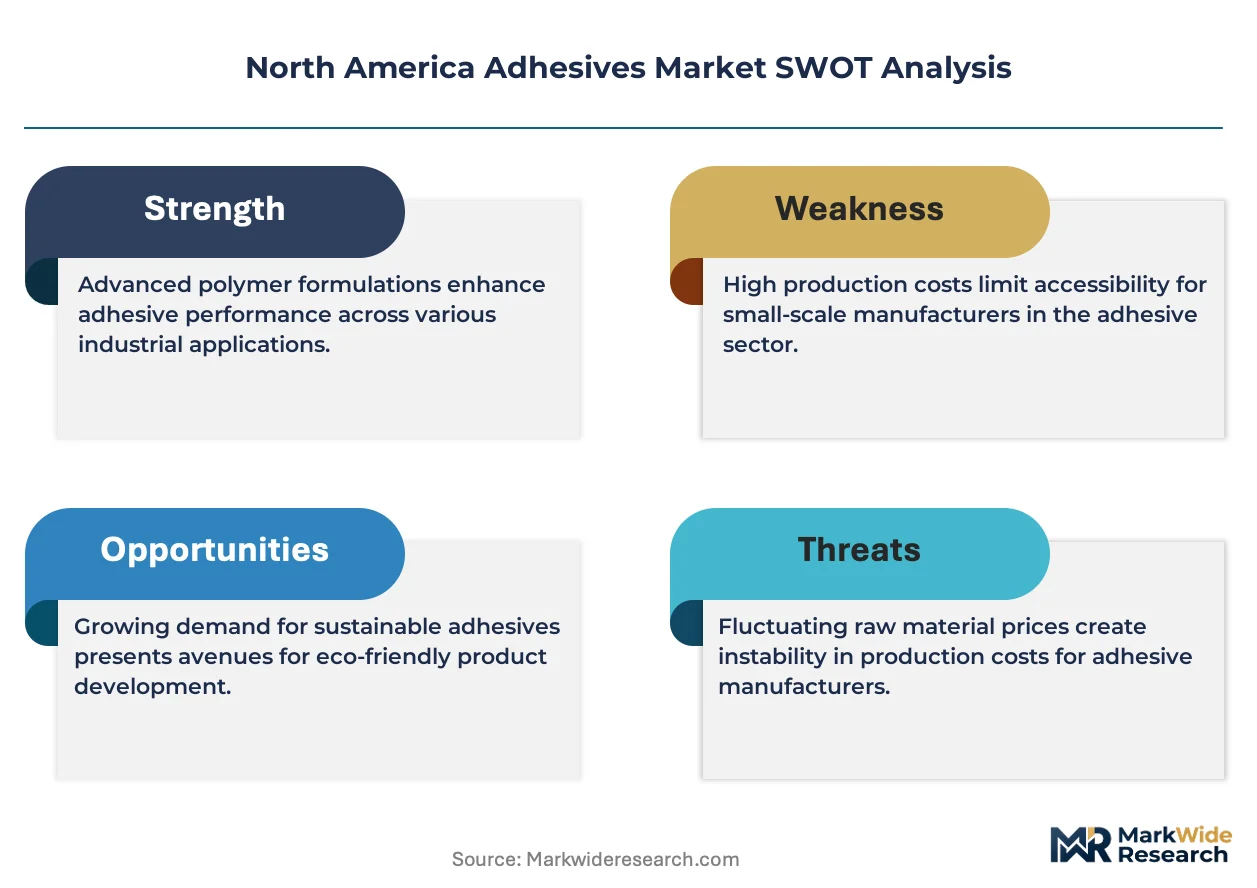
Adhesives in North America encompass polymer-based substances formulated from acrylics, polyurethanes, epoxies, silicones, or rubber elastomers, typically achieving shear strengths from 0.1 MPa for repositionable tapes to 35 MPa for structural aerospace bonds, designed to join substrates through surface wetting and cohesive or chemical cure mechanisms. Their primary industrial purpose spans permanent assembly, temporary fixation, sealing, and vibration damping across dissimilar materials where welding or mechanical fastening proves impractical. Pressure-sensitive adhesives lead volume consumption in packaging and label applications, while reactive systems command premium margins in automotive structural bonding where crashworthiness standards apply. Water-based technology segments face raw material volatility but retain regulatory tailwinds from EPA VOC emission limits, whereas UV-curable platforms represent the fastest-expanding margin pool despite higher capital equipment requirements.
EPA regulations on hazardous air pollutants and OSHA workplace exposure limits shape formulation choices, pushing manufacturers toward low-VOC water-based and hot-melt systems in states with stringent state implementation plans. Health Canada and PMRA oversight on chemical substances in consumer goods creates dual compliance obligations for suppliers operating across the US-Canada border, particularly for adhesives used in food-contact packaging. The Federal Trade Commission's Green Guides further constrain environmental marketing claims, requiring substantiated biodegradability assertions. Stakeholders must monitor state-level extended producer responsibility legislation emerging in California and New York, as these frameworks will determine collection and recycling infrastructure costs for adhesive-containing products.
Market Dynamics
Automotive lightweighting mandates in Michigan and Ontario are systematically displacing mechanical fasteners with structural bonding systems, while EPA VOC enforcement redirects formulation investment toward water-based and hot-melt platforms across the US Gulf Coast petrochemical corridor.
Growth Catalysts
- EPA VOC Regulations:Federal emission limits on hazardous air pollutants compel packaging converters and automotive OEMs to adopt low-VOC water-based adhesives, creating sustained demand pull for compliant formulation platforms.
- Automotive Lightweighting:Crashworthiness standards in structural bonding applications expand polyurethane and epoxy consumption as OEMs replace welded joints with adhesive assemblies to achieve mass reduction targets.
- UV-Curable Platforms:Radiation-curing technology penetrates electronics assembly and medical device manufacturing, enabling high-precision bonding for circuit board miniaturization with reduced energy and floor-space requirements.
Market Restraints
- Acrylic Monomer Volatility:Crude-linked propylene feedstock costs transmit price instability through the US Gulf Coast resin supply chain, compressing margins for pressure-sensitive adhesive producers.
- Capital Equipment Barriers:UV-curable systems require substantial investment in radiation-curing infrastructure, limiting adoption among mid-scale converters without balance-sheet capacity for line retrofits.
- Health Canada PMRA Compliance:Dual chemical substance oversight across the US-Canada border extends product registration timelines and elevates formulation documentation costs for cross-border suppliers.
Strategic Opportunities
- Extended Producer Responsibility:California and New York state legislation on adhesive-containing product collection and recycling creates first-mover advantage for suppliers designing recyclable bonding systems and take-back infrastructure.
- Hot-Melt Advancement:Reactive polyurethane hot-melt technology convergence with moisture-cure chemistry opens durable assembly applications in furniture and construction previously reserved for solvent-based systems.
- Medical Device Miniaturization:Biocompatible cyanoacrylate and silicone platforms penetrate wearable diagnostics and drug-delivery device assembly, capitalizing on FDA Class II device approval pathways for adhesive components.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in radiation-curing chemistry and bio-based polymer synthesis concentrates among senior practitioners, constraining R&D throughput for mid-tier manufacturers.
- Legacy Equipment Integration:Water-based adhesive conversion demands corrosive-resistant drying systems and modified application heads, complicating retrofit economics for established coating operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Adhesives Market |
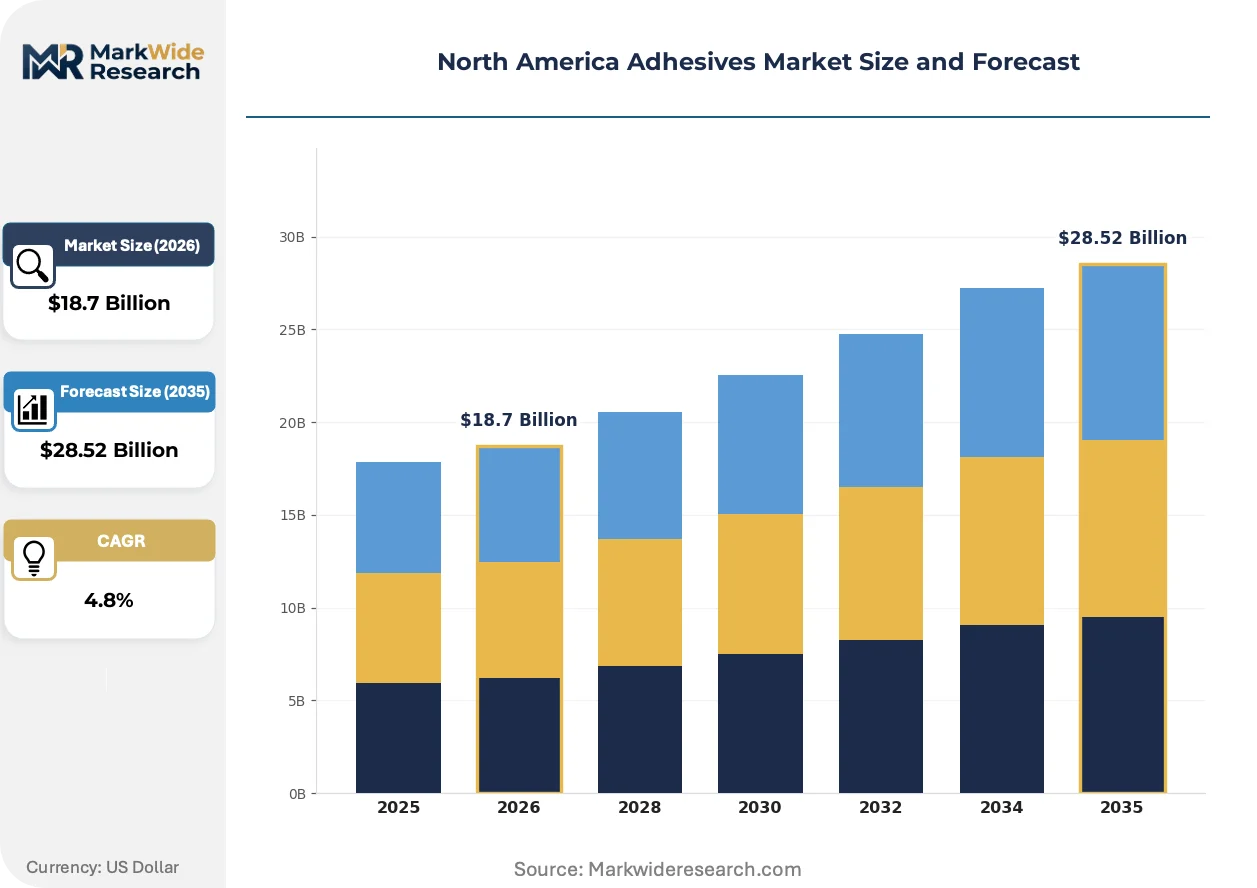
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Reactive, Structural, Hot Melt Application: Automotive, Construction, Electronics, Packaging End User: Manufacturers, Contractors, Retailers, Consumers Technology: Water-Based, Solvent-Based, UV-Curable, Thermosetting |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Arkema Group, Dow, RPM International Inc., Evonik Industries, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Adhesives Market Evolving Landscape
Digital manufacturing integration and bio-based feedstock development are actively reconfiguring how adhesives are formulated, specified, and consumed across North American industrial value chains.
Smart dispensing systems embedded with real-time viscosity monitoring and automated bead-placement feedback are digitizing quality assurance in automotive final assembly. Tier-1 suppliers in Ontario and Michigan deploy these platforms to eliminate manual inspection stations and compress defect-response cycles from hours to seconds.
OSHA workplace exposure limits and EPA National Emission Standards for Hazardous Air Pollutants tighten permissible solvent content in industrial adhesives. Formulators respond with hybrid water-based-UV systems that achieve structural performance while satisfying dual compliance obligations in states with stringent State Implementation Plans.
Buyers in food-contact packaging increasingly demand third-party certified biodegradable assertions validated against FTC Green Guides. This certification-driven preference shift elevates suppliers with substantiated environmental claims while exposing unsubstantiated marketing to regulatory and commercial risk, particularly among private-label converters serving California and New York markets.
North America Adhesives Market Segmentation
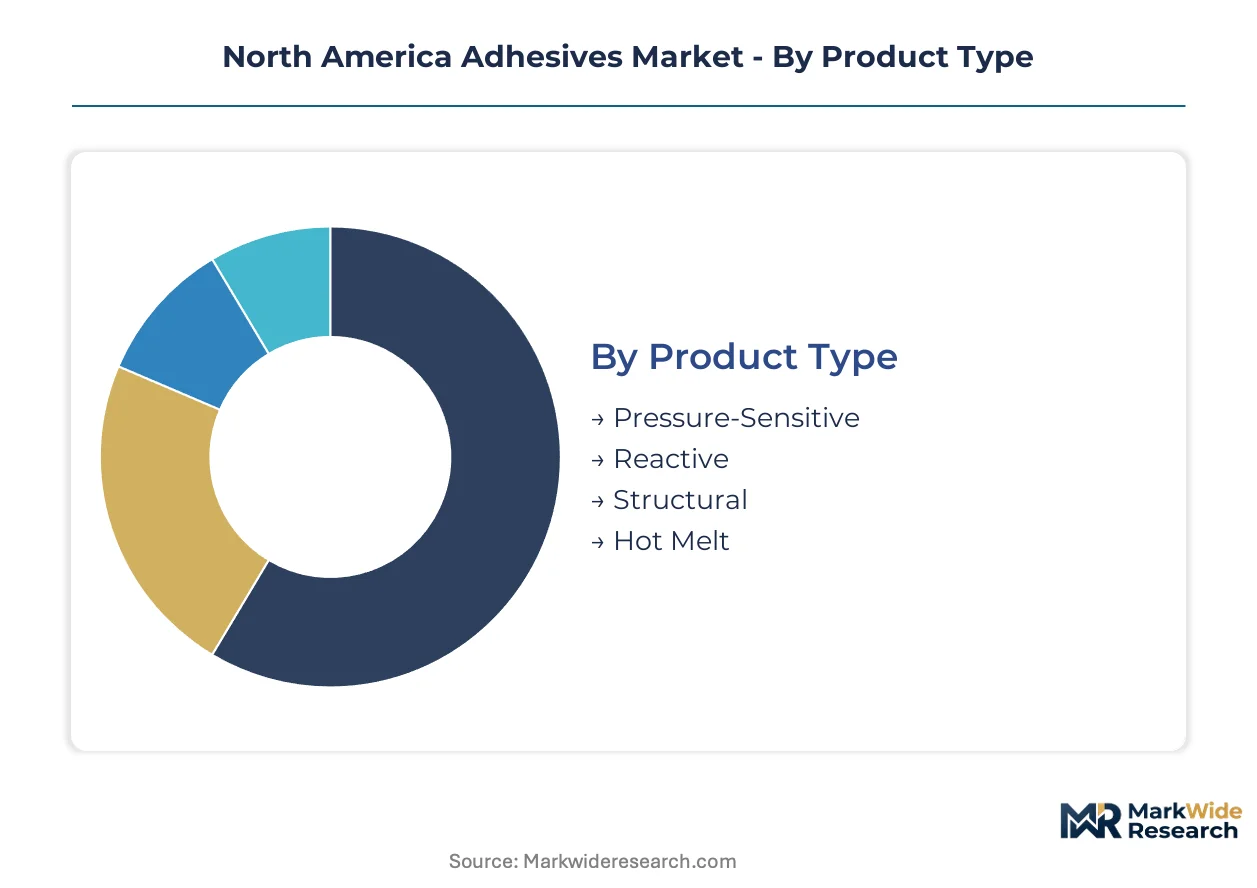
Adhesive performance requirements diverge sharply across bonding applications, from repositionable labels demanding 0.1 MPa shear strength to aerospace structural assemblies requiring 35 MPa crashworthiness. Segmentation clarity enables suppliers to align formulation investments with specific compliance obligations and end-use specifications.
Product Type:
Use cases span temporary fixation through permanent structural assembly, with performance tiers determining resin chemistry and cure mechanism selection.
- Pressure-Sensitive:Acrylic and rubber elastomer formulations enable immediate tack without activation, dominating label and tape applications across Michigan and Ontario automotive supply chains where repositionable bonding accelerates assembly sequencing.
- Reactive:Polyurethane and epoxy systems cure through moisture or thermal activation, commanding premium positioning in structural applications where OEMs substitute adhesive joints for welded fasteners to achieve mass reduction targets.
- Structural:High-modulus epoxy and methacrylate platforms achieve load-bearing performance for metal-to-composite bonding in aerospace and heavy-duty transport assembly.
- Hot Melt:Thermoplastic EVA and polyolefin formulations deliver rapid set times for packaging line speeds, though temperature sensitivity limits exterior automotive exposure.
Established volume favors Pressure-Sensitive; emerging adoption favors Reactive.
Application:
End-use sectors impose distinct regulatory and performance specifications that reshape formulation priorities across the value chain.
- Automotive:Structural bonding applications in Michigan and Ontario assembly plants drive polyurethane consumption as crashworthiness standards displace mechanical fastening, with EPA VOC limits simultaneously redirecting interior trim adhesive selection toward water-based platforms.
- Construction:Moisture-cure polyurethane and hybrid polymer sealants dominate commercial building envelope applications, though seasonal application temperature constraints compress installation windows in northern climates.
- Electronics:Miniaturized circuit board assembly demands UV-curable acrylic precision with minimal thermal exposure, concentrating demand in California and Texas semiconductor packaging corridors.
- Packaging:Food-contact compliance obligations under FDA and Health Canada oversight elevate certified formulations, with FTC Green Guide enforcement exposing unsubstantiated biodegradability claims to regulatory risk.
Construction anchors current volume; Electronics climbs the fastest on device miniaturization.
End User:
Procurement scale and technical specification authority separate volume buyers from specification influencers in adhesive value capture.
- Manufacturers:Tier-1 automotive and electronics OEMs in Michigan, Ontario, and California drive formulation co-development, locking suppliers into multi-year qualification cycles with substantial switching costs.
- Contractors:Commercial construction applicators in Texas and Florida prioritize open-time and temperature performance, with seasonal demand spikes compressing inventory planning.
- Retailers:Big-box distribution channels in the US and Canada concentrate private-label sourcing, exposing suppliers to price compression and extended payment terms.
- Consumers:DIY repair and craft applications favor cyanoacrylate and epoxy convenience formats, with minimal brand loyalty and high price elasticity.
Manufacturers command specification authority; Contractors drive regional volume concentration.
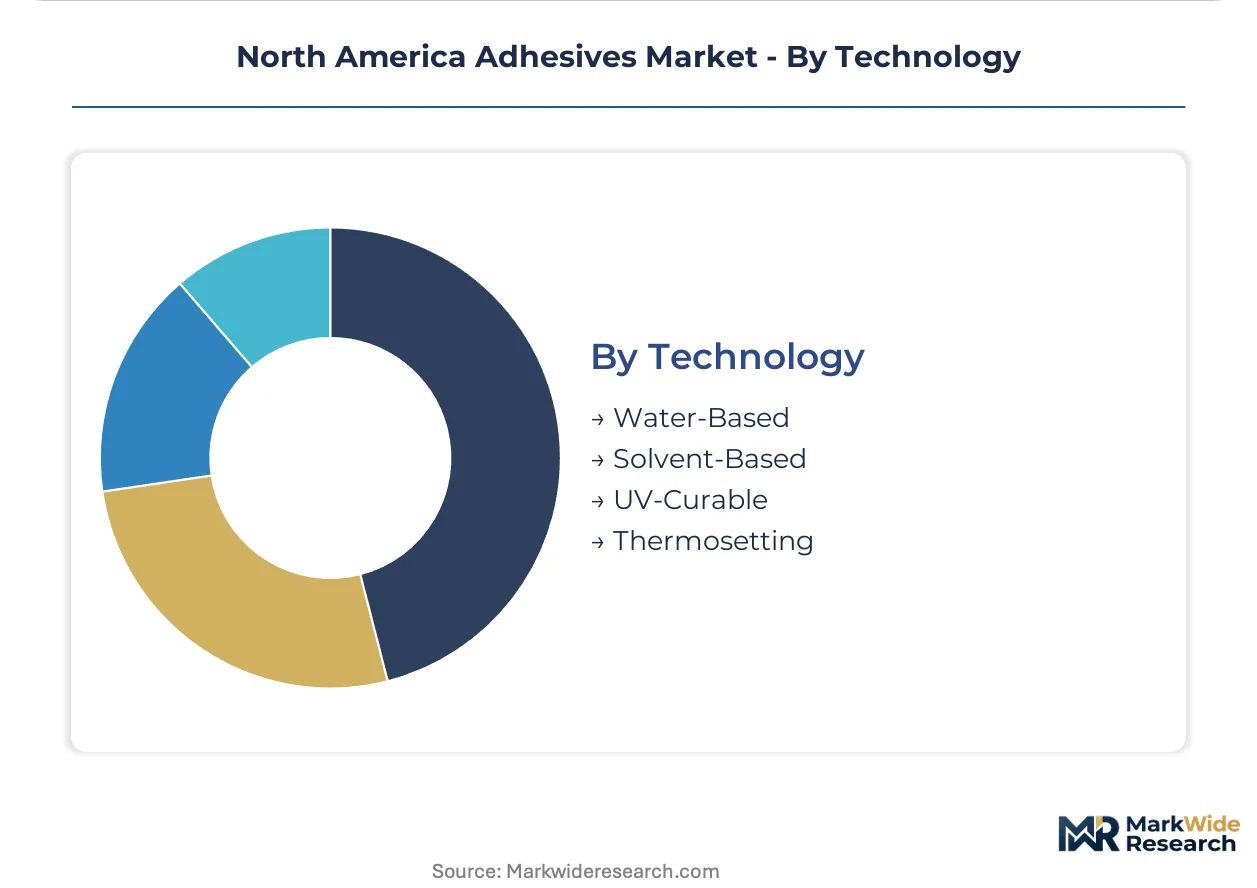
Technology:
Regulatory pressure and capital equipment requirements segment adoption by converter scale and compliance exposure.
- Water-Based:Acrylic and polyurethane dispersions satisfy EPA VOC emission limits in states with stringent State Implementation Plans, though corrosive-resistant drying infrastructure demands retrofit investment from established coating operations.
- Solvent-Based:Remaining applications concentrate in aerospace and specialty industrial bonding where performance specifications exceed water-based capabilities, with OSHA exposure limits elevating workplace compliance costs.
- UV-Curable:Radiation-curing acrylics penetrate electronics and medical device assembly with instant cure and minimal floor-space requirements, though capital equipment barriers limit mid-scale converter adoption.
- Thermosetting:Epoxy and phenolic systems dominate high-temperature structural applications in aerospace and power generation, with extended cure cycles constraining high-volume throughput.
Water-Based holds volume leadership; UV-Curable gains share fastest on electronics assembly expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Volume procurement concentrates among Tier-1 automotive OEMs and electronics contract manufacturers operating across the US Gulf Coast, Ontario automotive corridor, and California semiconductor packaging clusters. These buyers command multi-year qualification cycles with substantial switching costs. EPA VOC enforcement and Health Canada PMRA oversight create dual compliance obligations for cross-border suppliers.
United States
Automotive lightweighting programs in Michigan and structural bonding demand from Texas wind turbine assembly drive polyurethane and epoxy consumption. EPA National Emission Standards for Hazardous Air Pollutants compel packaging converters toward water-based formulations. The US Gulf Coast petrochemical corridor hosts integrated acrylic monomer production feeding pressure-sensitive adhesive manufacturers.
Canada
Ontario automotive assembly plants displace mechanical fasteners with crashworthy adhesive joints to achieve mass reduction targets. Health Canada and PMRA oversight on chemical substances extends product registration timelines for cross-border suppliers. The Toronto-Windsor corridor concentrates Tier-1 supplier operations serving Detroit-area OEMs.
Mexico
Expanding automotive OEM assembly in Nuevo León and Guanajuato generates structural adhesive demand for metal-to-composite bonding applications. Mexican environmental regulations under SEMARNAT align with EPA frameworks for VOC emission controls. The Bajío Region attracts packaging converter investment serving US export markets with compliant water-based systems.
North America Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation platforms, with consolidated positions in radiation-curing and water-based technologies against fragmented competition in solvent-based specialties. The vendor base organizes into three strategic archetypes: integrated petrochemical players with captive resin supply, radiation-curing specialists dominating electronics assembly, and water-based formulators serving packaging compliance markets. Dominant competitive moves include backward integration into acrylic monomer production and strategic partnerships with automotive OEMs for structural bonding qualification.
Among diversified chemical conglomerates, 3M, Henkel AG & Co. KGaA, and Dow occupy positions spanning multiple technology platforms and end-use segments. These entities represent scale-driven archetypes with broad formulation portfolios, though their competitive positioning diverges by technology emphasis and geographic supply chain configuration.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Arkema Group |
| Dow |
| RPM International Inc. |
| Evonik Industries |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
The US Gulf Coast petrochemical corridor freight dynamics transmit crude-linked propylene volatility directly into acrylic monomer pricing, concentrating cost-plus contract power among integrated resin producers while forcing non-integrated formulators toward indexation clauses that pass through feedstock swings to automotive OEMs and packaging converters.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate acrylic pressure-sensitive adhesive supply agreements, with pricing stratifying across automotive structural qualification tiers, food-contact FDA certification levels, and volume scale brackets. Price differentiation centers on EPA VOC compliance grade and captive monomer supply status. Pricing pressure stems from acrylic monomer volatility transmitting through the US Gulf Coast resin chain. Retail private-label channels exhibit highest price sensitivity; aerospace structural qualifications show lowest.
Supply Chain Analysis
Export-control restrictions on advanced radiation-curing photoinitiator chemistry limit UV-curable adhesive technology flows from German and Japanese specialty chemical producers, constraining North American converter access to high-precision electronics bonding platforms. Raw material dependencies center on US Gulf Coast propylene, Canadian natural gas derivatives for polyurethane polyols, and imported epoxy resins from South Korea. Single-source vulnerability concentrates in photoinitiator supply. Distribution runs through regional chemical distributors serving Michigan automotive clusters and California electronics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks automotive production cycles, with adhesive demand recovery tethered to Michigan and Ontario OEM assembly rate normalization following inventory destocking periods.
For Market Incumbents: Pre-empt margin compression from acrylic monomer volatility by securing captive propylene supply through backward integration into US Gulf Coast petrochemical assets or long-term offtake agreements with integrated producers. Accelerate water-based platform R&D to defend against EPA VOC enforcement expansion into additional state implementation plans. For New Entrants and Emerging Players: Establish a beachhead in medical device miniaturization segments where FDA Class II adhesive component approvals create qualification barriers protecting niche margins. Target biocompatible cyanoacrylate and silicone platforms for wearable diagnostics, leveraging contract manufacturing partnerships with Texas and California device assemblers as the primary go-to-market channel. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio simplification, particularly radiation-curing divisions with stranded technology assets and qualified automotive OEM relationships. Long-term viability favors suppliers with dual US-Canada regulatory registration capabilities. Watch Michigan automotive assembly rate inflection as the demand recovery signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer | Captive propylene supply from US Gulf Coast crackers insulates margin pressure from crude-linked feedstock swings. |
| Water-Based Platform R&D Expansion | EPA VOC compliance pathways in stringent state implementation plans lock in packaging converter switching costs. |
| UV-Curable Electronics Qualification | Radiation-curing expertise captures circuit board miniaturization demand from California semiconductor packaging clusters. |
| Medical Device Biocompatibility Certification | FDA Class II adhesive component approvals open wearable diagnostics and drug-delivery device assembly markets. |
| Cross-Border US-Canada Registration | Dual EPA and Health Canada PMRA compliance extends product registration timelines but creates switching cost barriers. |
Research Methodology
Desk research of SEC 10-K filings, ACC industry reports, and customs trade data preceded structured interviews with adhesive formulator R&D directors, Tier 1 automotive procurement managers, packaging converter operations heads, and chemical distribution channel partners. Primary fieldwork across Michigan, Ontario, and Texas manufacturing corridors validated secondary estimates. Bottom-up volume modeling triangulated against top-down petrochemical feedstock consumption analysis.
Assumptions held fixed include EPA VOC regulatory enforcement intensity, automotive lightweighting program continuity, and crude-linked propylene pricing correlation coefficients across the analysis window. Segmentation dimensions modeled encompass product type performance tier, end-use industry regulatory cluster, technology platform capital requirements, and regional production hub concentration. CAGRs derived from adhesive consumption intensity ratios applied to named end-use production forecasts, with automotive build rates and electronics assembly volumes as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, automotive demand cyclicality, or interest rate environments affecting capital equipment investment would shift the trajectory. Material shifts in EPA hazardous air pollutant standards or Health Canada PMRA substance review timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
North America Adhesives and Sealants Market