
 Fuel Resistant Sealant Market | 2026-2036
Fuel Resistant Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Resistant Sealant Market Foresight
Germany's specialty chemical manufacturing corridor is fragmenting as new entrants challenge established supply positions for fuel-resistant formulations. Dow Inc. leverages integrated silicone precursor operations to sustain cost discipline across European distribution. PPG Industries anchors its position through aerospace-certified polysulfide production lines serving OEM Manufacturers. BASF SE competes via hybrid polymer R&D platforms that address both solvent-based legacy demand and water-based regulatory transitions.
Fuel resistant sealant denotes an elastomeric or resin-based compound engineered to withstand hydrocarbon swelling, thermal cycling, and permeation, typically formulated with polysulfide, fluorosilicone, or nitrile rubber binders exhibiting Shore A hardness between 40 and 60 and service temperatures from -54°C to 121°C. These materials create impermeable barriers in fuel-wetted joints, preventing leakage, corrosion, and structural degradation in aircraft integral tanks, automotive fuel systems, and marine storage vessels. Polysulfide sealant retains dominance in aerospace applications where FAR 25.963 fire resistance mandates govern specification, while polyurethane sealant captures share in automotive assembly where faster cure cycles reduce line downtime. Water-based technology remains nascent but attracts investment as OEM Manufacturers face escalating VOC compliance costs.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation volumes, while REACH restrictions on isocyanate content reshape polyurethane chemistry investments in Europe. FAA certification requirements for fuel tank sealants create steep qualification barriers that limit supplier pools for Aircraft Assemblers. Stakeholders must monitor regulatory divergence between EPA and ECHA frameworks to anticipate reformulation timelines and qualification costs.
Market Dynamics
EPA National Emission Standards for Hazardous Air Pollutants and REACH isocyanate restrictions are forcing simultaneous reformulation across solvent-based and polyurethane chemistries, compressing supplier margins while extending qualification timelines for Aircraft Assemblers and OEM Manufacturers.
Growth Catalysts
- FAR 25.963 fire resistance mandates:Aerospace OEMs in the United States face mandatory compliance for integral fuel tank sealing, sustaining polysulfide demand despite higher formulation costs.
- Germany's automotive supplier corridor:Stuttgart and Wolfsburg production clusters generate concentrated demand for fast-cure polyurethane sealants in fuel system assembly.
- Hybrid polymer R&D platforms:Water-based technology investment accelerates as regulatory compliance costs escalate for solvent-based legacy formulations.
Market Restraints
- Silicone precursor concentration:Dow Inc.'s integrated operations create supply-side dependency for European distributors seeking cost discipline.
- FAA certification barriers:Qualification requirements limit supplier pools for Aircraft Assemblers, extending time-to-market for new entrants.
- Isocyanate input volatility:REACH restrictions on isocyanate content reshape polyurethane chemistry investments and constrain formulation flexibility.
Strategic Opportunities
- Water-based regulatory transitions:EPA and ECHA framework divergence creates first-mover advantage for suppliers with dual-compliant platforms.
- Marine storage vessel applications:Fuel-wetted joint sealing in commercial shipping represents underpenetrated demand outside aerospace and automotive.
- Direct OEM Manufacturer contracting:Channel disintermediation enables margin capture for qualified suppliers with aerospace-certified production lines.
Industry Challenges
- Reformulation timeline compression:Suppliers must synchronize VOC compliance deadlines across EPA and ECHA frameworks without interrupting qualified supply.
- Hybrid polymer integration complexity:Water-based technologies require revalidation of Shore A hardness and service temperature performance (-54°C to 121°C) against legacy specifications.
- Specialized elastomer formulation talent:Shortage of chemists experienced in fluorosilicone and nitrile rubber binder development constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Resistant Sealant Market |
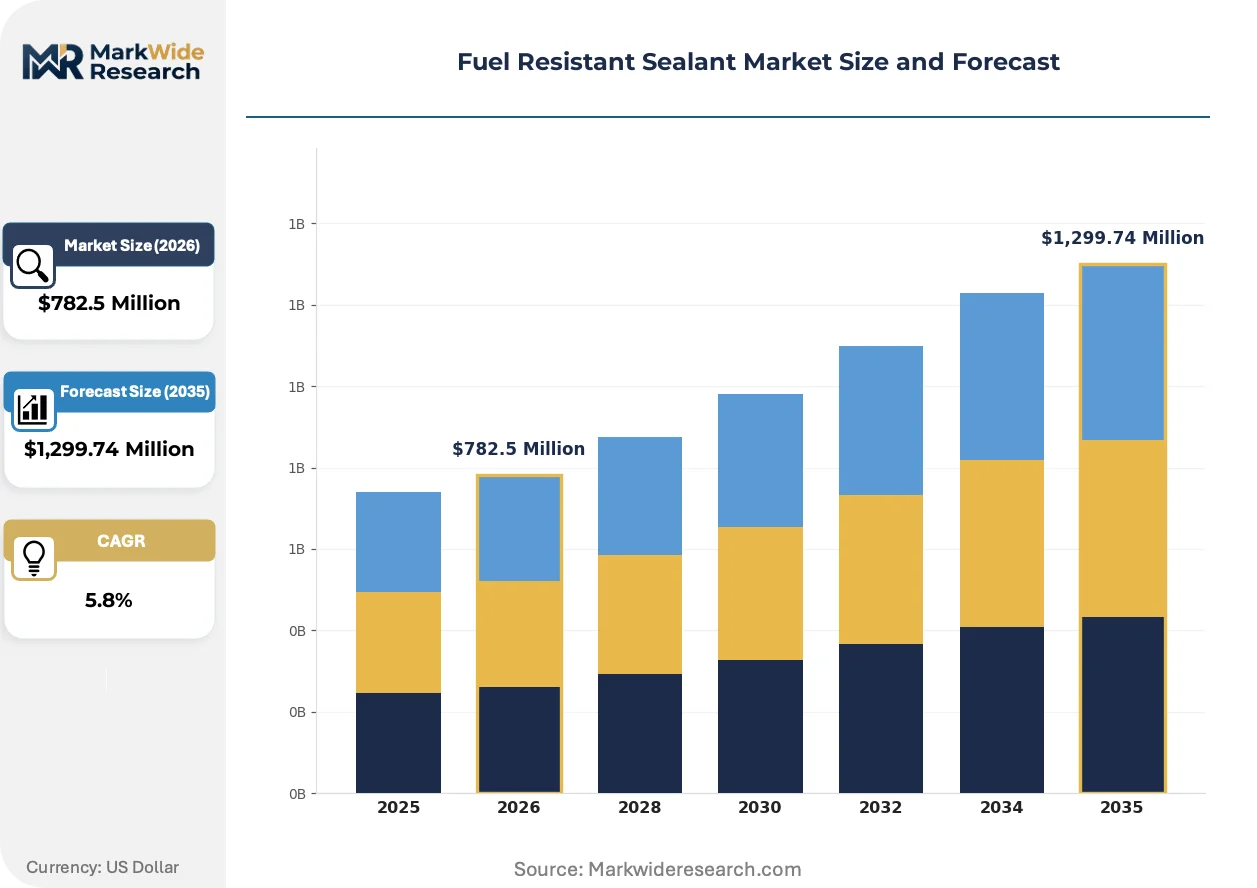
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,299.74 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Sealant, Polyurethane Sealant, Polysulfide Sealant, Acrylic Sealant, Butyl Sealant Technology: Solvent-Based, Water-Based, Two-Component, UV Cure, Hybrid Application: Fuel Tank Sealing, Pipe Sealing, Engine Gasket, Automotive Assembly, Marine Vessel Maintenance End User: OEM Manufacturers, Aftermarket Suppliers, Marine Equipment Makers, Aircraft Assemblers, Chemical Processors |
| Companies Covered | Dow Inc., PPG Industries, Inc., 3M Company, Sika AG, BASF SE, Henkel AG & Co. KGaA, Bostik Inc., H.B. Fuller Company, Lord Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Resistant Sealant Market Shifts & Advancements
Formulation chemistry is bifurcating between legacy solvent-based systems and emerging water-based platforms, with regulatory compliance costs now determining competitive viability more than raw performance metrics.
Fluorosilicone sealant technology is collapsing the performance gap between aerospace-grade polysulfide and automotive-grade polyurethane. Aircraft Assemblers in the United States are piloting fluorosilicone formulations for non-structural fuel tank applications where FAR 25.963 compliance can be demonstrated with reduced cure cycles. The structural consequence is compressing the traditional segmentation between aerospace and automotive specification tiers.
REACH restrictions on isocyanate content are reshaping polyurethane chemistry investments across European manufacturing. BASF SE and competing suppliers face reformulation mandates that extend qualification timelines while increasing R&D expenditure. Automotive OEM Manufacturers in Germany's supplier corridor are responding by consolidating procurement around hybrid polymer platforms that address both solvent-based legacy demand and water-based regulatory transitions.
Buyer concentration around aerospace-certified suppliers is shortening switching cycles for fuel tank sealant procurement. OEM Manufacturers are unbundling after-sales service contracts from material supply, favoring suppliers with captive technical support capabilities. This pattern is most visible in North America, where Boeing and Lockheed Martin procurement teams are consolidating qualified supplier lists to reduce compliance audit burden.
Fuel Resistant Sealant Market Segmentation
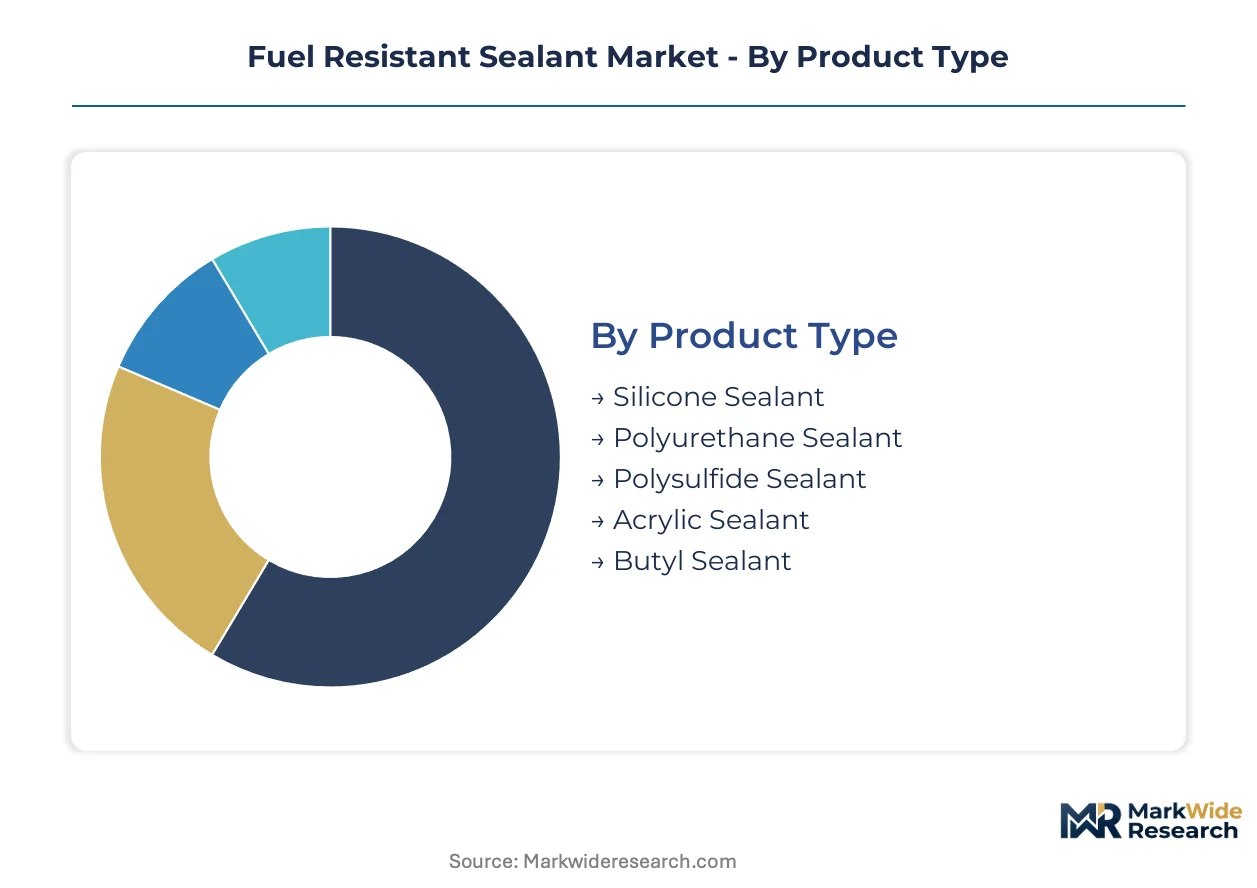
Fuel resistant sealant procurement splits across formulation chemistry, cure technology, and end-use certification tiers. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Mature polysulfide formulations coexist with emerging hybrid chemistries as aerospace and automotive specifications diverge.
- Polysulfide Sealant:Polysulfide binders deliver Shore A hardness between 40 and 60 with service temperatures spanning -54°C to 121°C. Aircraft Assemblers in the United States specify these formulations for integral fuel tank sealing under FAR 25.963 fire resistance mandates, sustaining premium pricing despite extended cure cycles.
- Polyurethane Sealant:Fast-cure polyurethane systems dominate automotive assembly lines where line downtime reduction outweighs maximum temperature performance. Stuttgart and Wolfsburg production clusters in Germany generate concentrated demand for these grades.
- Silicone Sealant:Fluorosilicone variants are collapsing the performance gap between aerospace-grade polysulfide and automotive-grade polyurethane.
- Acrylic Sealant:Acrylic formulations serve secondary containment and non-structural applications where fuel exposure is intermittent.
- Butyl Sealant:Butyl rubber compounds address marine storage vessel maintenance with moderate hydrocarbon resistance at lower cost points.
Polysulfide sealant handles the majority of aerospace throughput; polyurethane sealant is the fastest mover on share.
Technology:
Regulatory compliance costs now determine competitive viability more than raw performance metrics across cure chemistry platforms.
- Solvent-Based:Legacy solvent carriers face EPA National Emission Standards for Hazardous Air Pollutants constraints that compress formulation volumes and extend reformulation timelines.
- Water-Based:Water-based platforms attract investment as OEM Manufacturers face escalating VOC compliance costs, though revalidation of Shore A hardness and service temperature specifications remains incomplete.
- Two-Component:Two-component systems dominate aerospace-certified production lines where pot life control and cure reliability govern specification.
- UV Cure:UV-initiated cure technology is gaining traction in automotive assembly applications where line speed requirements exceed thermal cure capabilities.
- Hybrid:Hybrid polymer R&D platforms address simultaneous solvent-based legacy demand and water-based regulatory transitions.
Solvent-based technology retains installed base dominance; water-based platforms are expanding most quickly as compliance deadlines tighten.
Application:
End-use segmentation reflects divergent certification barriers and performance envelopes across mobility sectors.
- Fuel Tank Sealing:Integral fuel tank applications demand impermeable barriers preventing leakage, corrosion, and structural degradation under cyclic thermal loading. FAA certification requirements create steep qualification barriers that limit supplier pools for Aircraft Assemblers.
- Automotive Assembly:Fuel system assembly in Germany's automotive supplier corridor favors fast-cure polyurethane sealants that reduce line downtime.
- Pipe Sealing:Pipeline applications emphasize hydrocarbon swelling resistance and permeation control in continuous fuel contact environments.
- Engine Gasket:Engine gasket sealing combines fuel resistance with elevated temperature performance and compression set resistance.
- Marine Vessel Maintenance:Commercial shipping fuel-wetted joint sealing represents underpenetrated demand outside aerospace and automotive core markets.
Fuel tank sealing commands premium qualification overhead; marine vessel maintenance is climbing the fastest as fleet renewal accelerates.
End User:
Buyer concentration patterns favor suppliers with captive technical support capabilities and aerospace-certified production lines.
- OEM Manufacturers:Original equipment procurement teams are consolidating qualified supplier lists to reduce compliance audit burden, unbundling after-sales service contracts from material supply.
- Aircraft Assemblers:Boeing and Lockheed Martin procurement patterns in North America demonstrate preference for suppliers with integrated polysulfide production lines serving aerospace-certified specifications.
- Aftermarket Suppliers:Aftermarket channels face margin compression as OEM Manufacturers extend direct contracting relationships.
- Marine Equipment Makers:Marine equipment procurement emphasizes cost discipline over maximum performance specification.
- Chemical Processors:Chemical process industry demand concentrates on solvent-resistant formulations for storage and handling infrastructure.
OEM Manufacturers handle the majority of qualified volume; Aircraft Assemblers are gaining share fastest as production backlogs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated silicone precursor operations cluster in the United States and Germany, while aerospace-certified polysulfide production concentrates around Stuttgart and Wolfsburg corridors. Chemical manufacturers face divergent EPA and ECHA compliance timelines that fragment regional formulation standards.
United States
Boeing and Lockheed Martin procurement teams consolidate qualified supplier lists for integral fuel tank sealing under FAR 25.963 mandates. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation volumes. Aerospace OEMs in the Pacific Northwest and Southern California production clusters sustain polysulfide demand despite extended qualification barriers.
Germany
Automotive OEM Manufacturers in Stuttgart and Wolfsburg generate concentrated demand for fast-cure polyurethane sealants in fuel system assembly. REACH restrictions on isocyanate content reshape polyurethane chemistry investments across Baden-Württemberg and Lower Saxony. BASF SE anchors hybrid polymer R&D platforms addressing simultaneous solvent-based legacy demand and water-based regulatory transitions.
China
MIIT standards for automotive fuel system materials tighten domestic formulation requirements for hydrocarbon-resistant compounds. GB standards for chemical emissions create compliance layering with international OEM specifications. Yangtze River Delta manufacturing clusters attract investment in fluorosilicone sealant production serving both aerospace subcontracting and domestic automotive assembly.
Japan
METI industrial material roadmaps prioritize high-performance elastomer development for aerospace and automotive fuel containment. JIS standards for fuel resistance create qualification pathways parallel to FAA and EASA frameworks. Kansai and Chubu industrial corridors concentrate precision chemical manufacturing for export-oriented sealant formulations.
France
ANSM chemical safety assessments influence formulation registration timelines for fuel-resistant compounds entering aerospace supply chains. Île-de-France and Auvergne-Rhône-Alpes host aerospace subcontractor networks demanding FAR 25.963 compliant polysulfide grades. Safran and Airbus procurement patterns favor suppliers with dual EPA-ECHA compliant production platforms.
Fuel Resistant Sealant Market Competitive Landscape
Integrated chemical conglomerates and specialized adhesive formulators split the market along aerospace certification tiers. The vendor base concentrates around three strategic archetypes: silicone precursor integrators with captive raw material control, aerospace-certified polysulfide specialists with FAA-qualified production lines, and hybrid polymer developers bridging solvent-based legacy and water-based regulatory transitions. Dominant competitive moves include backward integration into specialty elastomer precursors and geographic expansion through qualified distributor networks.
Among North American chemical conglomerates, Dow Inc. exemplifies the integrated precursor archetype through silicone raw material control. PPG Industries occupies a position within the aerospace-certified tier, anchoring polysulfide production capabilities serving OEM Manufacturers. BASF SE represents the hybrid polymer development vector, competing via R&D platforms that address regulatory transitions across multiple geographies.
| Leading Market Players |
|---|
| Dow Inc. |
| PPG Industries, Inc. |
| 3M Company |
| Sika AG |
| BASF SE |
| Henkel AG & Co. KGaA |
| Bostik Inc. |
| H.B. Fuller Company |
| Lord Corporation |
| Others |
Supply & Pricing Matrix
Dow Inc.'s captive silicone precursor operations in the United States and Germany concentrate upstream margin capture, forcing downstream formulators to compete on qualification speed rather than raw material cost discipline. This concentration elevates pricing power for integrated suppliers while compressing margins for distributors dependent on spot market elastomer sourcing.
Pricing Analysis
EPA National Emission Standards for Hazardous Air Pollutants dictate the pricing tier structure across solvent-based, water-based, and hybrid polymer platforms. Aerospace-certified polysulfide grades command premium positioning against automotive polyurethane tiers based on FAR 25.963 qualification overhead and extended cure cycle requirements. Cost compression in water-based formulations is intensifying because REACH isocyanate restrictions extend R&D revalidation timelines. Aftermarket suppliers exhibit highest price sensitivity due to unbundling of service contracts from material supply.
Supply Chain Analysis
Toll manufacturing capacity for aerospace-certified polysulfide production concentrates in the United States, Germany, and France. Formulation draws from fluorosilicone precursors, nitrile rubber binders, and hybrid polymer intermediates as primary inputs. Single-source vulnerability runs through FAA-qualified production lines where requalification timelines exceed regulatory compliance deadlines. Distribution feeds from qualified supplier networks directly into Boeing, Lockheed Martin, and Airbus assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aerospace production backlogs signal cyclical recovery for fuel-resistant sealant demand. OEM procurement consolidation around qualified supplier lists accelerates margin capture timing for positioned players.
For Market Incumbents: Build regulatory moats through dual EPA-ECHA compliant production platforms. Accelerate water-based hybrid polymer R&D to preempt qualification barriers that new entrants cannot surmount. Capture channel control by unbundling after-sales technical support from material supply contracts, denying margin pools to distributor intermediaries. For New Entrants and Emerging Players: Establish a beachhead in marine vessel maintenance applications where FAA certification requirements do not govern specification. Target Germany's automotive supplier corridor with fast-cure polyurethane formulations that address REACH isocyanate restrictions ahead of incumbent reformulation timelines. Lead with direct OEM Manufacturer contracting to bypass qualified distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid polymer specialists with simultaneous solvent-based legacy demand and water-based regulatory transition capabilities. Long-term viability centers on five-to-ten year compliance cost escalation trajectories rather than near-term volume expansion. Monitor EPA-ECHA framework divergence as the critical inflection signal for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorosilicone Precursors | Dow Inc.'s captive supply model demonstrates margin protection against raw material volatility. |
| Water-Based Platform Qualification | BASF SE's hybrid polymer R&D addresses EPA and REACH compliance deadlines simultaneously. |
| Aerospace-Certified Production Line Expansion | PPG Industries anchors position through FAR 25.963 qualified capacity serving Boeing procurement. |
| Direct OEM Manufacturer Contracting | Channel disintermediation captures service-margin pools previously allocated to aftermarket distributors. |
| Marine Application Specification Development | Commercial shipping fuel-wetted joint sealing represents underpenetrated demand outside core aerospace-automotive markets. |
Research Methodology
Cross-validation between primary interviews with aircraft assembler procurement directors, automotive OEM fuel system engineers, chemical plant managers, and aerospace-certified toll manufacturers anchors the qualitative findings. Secondary validation draws from FAA certification databases, EPA enforcement records, ECHA registration dossiers, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up segmentation modeling triangulates against top-down trade flow analysis across the analysis window.
Calibration against historical qualification timeline data and regulatory compliance cost trajectories shapes the projection framework. Segmentation dimensions span formulation chemistry, cure technology, end-use certification tier, and geographic production cluster. CAGRs derive from elasticity-adjusted demand modeling incorporating OEM production backlog data and fleet renewal schedules. Aerospace delivery timelines and automotive assembly line speed requirements serve as industry-specific volume drivers.
Macroeconomic conditions sit as an overlay; deviation in commercial aerospace production rates and automotive platform launch cadences would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory deadline adherence and qualification pathway completion. Quarterly review of EPA enforcement patterns, ECHA substance restriction proposals, and OEM supplier consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market