
 United Kingdom Sealants Market | 2026-2036
United Kingdom Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Sealants Market Analytics
A capital-intensity divergence between integrated resin producers and formulation specialists is redrawing competitive boundaries in the United Kingdom sealants sector. Dow leverages captive silicone intermediates to sustain margin resilience across construction-grade portfolios. Sika AG anchors its position through specification-grade polyurethane systems for infrastructure waterproofing. Hodgson Sealants competes on regional distribution density and same-day availability for building maintenance contractors.
United Kingdom sealants comprise elastomeric compounds—typically silicone, polyurethane, acrylic, or butyl-based—formulated to fill joints, exclude moisture, and accommodate substrate movement across temperature ranges from minus forty to plus one hundred and fifty degrees Celsius. Their primary purpose spans structural glazing, facade weatherproofing, automotive seam sealing, and electronics encapsulation. Silicone dominates facade and high-temperature applications where UV stability and joint movement tolerance command premium positioning. Polyurethane captures groundworks and civil engineering demand where tensile strength and paint compatibility matter most. Butyl retains niche insulation and primary sealing roles in automotive and building envelopes, though growth lags the faster-expanding silicone and polyurethane categories.
British Standards Institution certification under BS EN 15651, together with Building Regulations Approved Document B fire-safety requirements and Construction Products Regulation CE/UKCA marking obligations, shapes product development priorities and market access conditions for sealant suppliers. The Health and Safety Executive's REACH enforcement arm further constrains formulation chemistry, particularly for isocyanate-containing polyurethane systems. Stakeholders must monitor evolving post-Grenfell facade safety standards and the transition from CE to UKCA marking regimes to anticipate specification shifts and compliance cost trajectories.
Market Dynamics
The United Kingdom sealants market is being reshaped by the Building Safety Act's post-Grenfell fire-performance mandates, which are forcing wholesale reformulation of facade-grade silicone and polyurethane systems across high-rise remediation programmes.
Growth Catalysts
- Building Safety Act remediation mandates:Government-funded cladding replacement programmes across Greater London and the South East are generating sustained procurement volume for intumescent and fire-rated sealant grades.
- Retrofit energy efficiency targets:The UK's net-zero building stock commitments are accelerating demand for high-performance air-sealing systems in residential and commercial envelope upgrades.
- Transport infrastructure renewal:HS2 phase completions and Network Rail bridge waterproofing programmes are expanding specification-grade polyurethane consumption for civil engineering joints.
Market Restraints
- Silicone intermediate supply concentration:European chlorosilane production bottlenecks and energy cost volatility at German and Belgian precursor facilities are compressing margins for UK formulation specialists without captive upstream supply.
- REACH isocyanate restrictions:The Health and Safety Executive's enforcement of diisocyanate occupational exposure limits is forcing costly reformulation of high-performance polyurethane construction sealants.
- Acrylic substitution in interior applications:Lower-cost water-based acrylic systems are capturing paint-compatible joint-sealing demand in residential interiors, eroding volume for premium silicone grades.
Strategic Opportunities
- Northern Powerhouse construction acceleration:Manchester, Leeds and Liverpool high-rise residential clusters present underpenetrated demand for specification-grade facade sealants outside the saturated South East corridor.
- UKCA marking transition services:The displacement of CE marking with UK-specific conformity assessment creates advisory and testing revenue streams for certification-capable suppliers.
- Hybrid silicone-polyurethane chemistries:Convergence of silicone UV stability with polyurethane mechanical strength is opening specification opportunities in structural movement joints previously served by single-chemistry systems.
Industry Challenges
- Fire-testing certification timelines:BS EN 15651-4 facade fire-performance testing backlogs at UKAS-accredited laboratories are extending product launch cycles by six to twelve months.
- Technical specification workforce gaps:Shortages of qualified facade engineers capable of calculating joint movement and specifying appropriate modulus grades are constraining contractor execution capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Sealants Market |
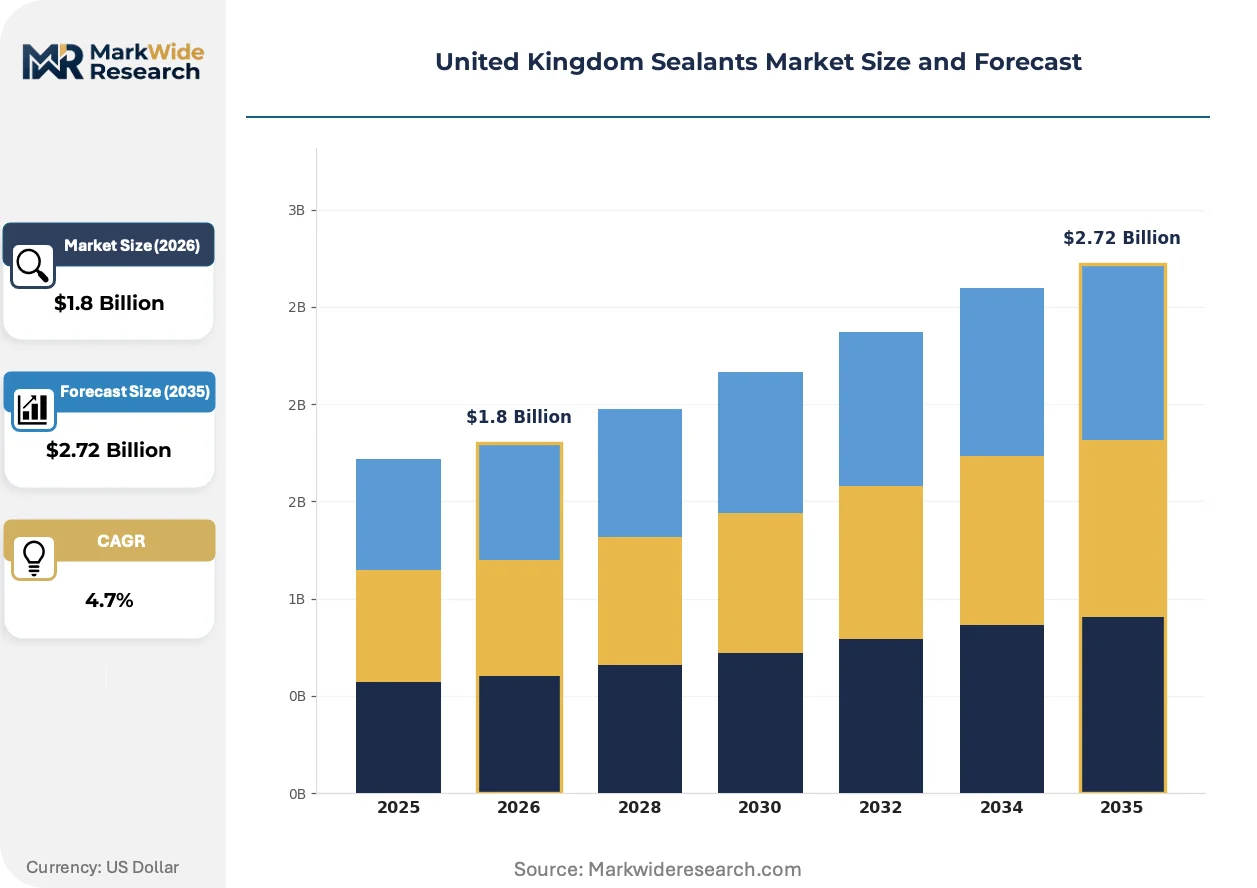
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Butyl End User: Construction, Automotive, Electronics, Aerospace Application: Insulation, Waterproofing, Adhesion, Sealing Form: Caulk, Tape, Liquid, Gel |
| Companies Covered | Dow, Hodgson Sealants, Sika AG, 3M, Adshead Ratcliffe & Co Ltd., Henkel AG & Co. KGaA, Soudal Holding N.V., RPM International Inc., Arkema Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Sealants Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture and procurement channel structures are undergoing simultaneous transformation, with sustainability performance and digital specification tools emerging as decisive competitive differentiators.
Low-VOC neutral-cure silicone sealants are supplanting acetoxy-cure formulations in interior commercial applications. Facility managers and healthcare estates teams are specifying neutral-cure systems to eliminate acetic acid emissions during installation. This transition is compressing demand for traditional acetoxy grades while rewarding suppliers with certified low-emission product portfolios.
The UK's transition from CE to UKCA marking under the Construction Products Regulation is fragmenting conformity assessment pathways. British Standards Institution and UKAS-approved bodies are processing divergent test protocols, creating compliance complexity for pan-European suppliers. Small and mid-sized formulation houses are responding by consolidating UK-specific certification investments ahead of full regulatory separation.
Digital specification platforms are displacing traditional merchant-driven procurement for large-scale construction programmes. Tier-one contractors in the South East are adopting cloud-based sealant selection tools that integrate BIM models with performance databases. This channel shift is most pronounced in London commercial tower developments where design-and-build contracts consolidate material decisions at the pre-construction phase.
United Kingdom Sealants Market Segmentation
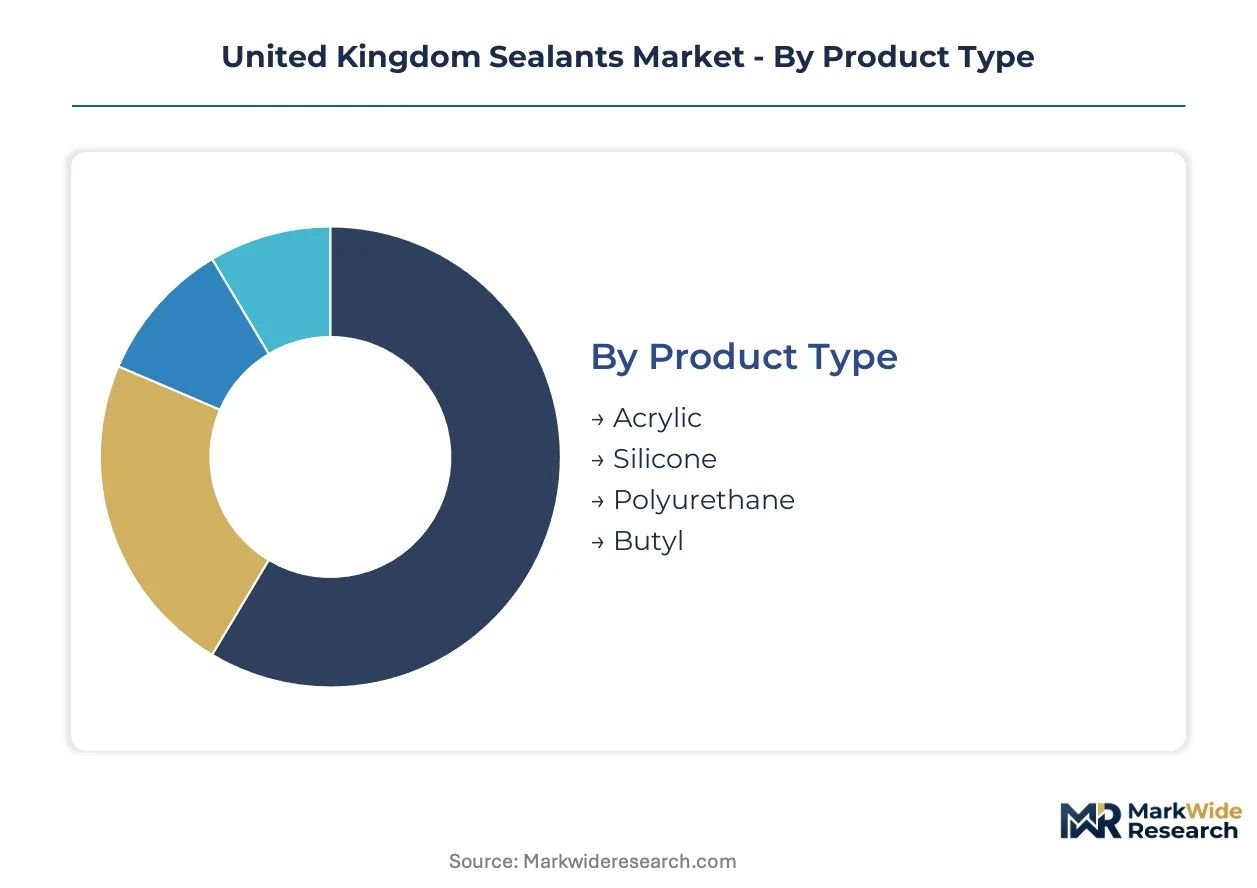
Segmentation reveals how formulation chemistry, end-use requirements, and application methods concentrate procurement power across distinct customer clusters. Understanding these divisions exposes where specification-grade premiums command pricing leverage versus commodity substitution risks.
Product Type:
Silicone and polyurethane formulations dominate domestic specification work, while acrylic and butyl grades serve cost-sensitive maintenance and export-adjacent production.
- Silicone:UV-stable elastomeric systems formulated from chlorosilane intermediates deliver joint movement tolerance from minus forty to plus two hundred degrees Celsius. Demand concentrates in Greater London high-rise remediation where Building Safety Act fire-performance mandates require intumescent silicone grades for facade glazing and movement joints.
- Polyurethane:Isocyanate-cured systems offering tensile strength above six hundred kilopascals and paint compatibility capture civil engineering waterproofing contracts. HS2 phase completions and Network Rail bridge programmes across the Midlands and North West are expanding specification-grade procurement for structural movement joints.
- Acrylic:Water-based emulsion sealants serve interior residential joint-sealing where paint compatibility and low material cost outweigh durability requirements.
- Butyl:Solvent-free rubberized compounds retain primary sealing roles in automotive glazing and building envelope vapour barriers, though volume growth lags silicone and polyurethane categories.
Silicone commands the established base. The steepest expansion runs through polyurethane civil engineering applications.
End User:
Construction procurement dwarfs other sectors in absolute volume, yet automotive and electronics demand concentrates in precision-formulation contracts with tighter specification tolerances.
- Construction:Residential retrofit, commercial cladding, and infrastructure waterproofing collectively absorb the majority of UK sealant volume. Building Safety Act remediation programmes across Greater London and the South East are generating sustained demand for fire-rated facade systems.
- Automotive:OEM seam sealing and glazing applications require validated formulations meeting OEM-specific durability testing. West Midlands manufacturing clusters source specification-grade polyurethane and butyl systems for assembly-line integration.
- Electronics:Encapsulation and thermal management applications demand ultra-low-ionic-content silicone gels. Cambridge and Bristol technology corridors are expanding procurement for high-reliability grades.
- Aerospace:Fuel-resistant polysulfide and fluorosilicone formulations serve airframe sealing and fuel tank applications. Broughton and Bristol aerospace clusters specify certified grades for defence and commercial aviation contracts.
Construction absorbs the volume base. Aerospace and electronics deliver the steepest margin expansion.
Application:
Waterproofing and sealing applications concentrate procurement in specification-grade systems, while adhesion and insulation segments split between premium formulations and commodity substitutes.
- Waterproofing:Below-grade and bridge deck applications demand elastomeric membranes with crack-bridging capability exceeding one hundred percent. Transport infrastructure renewal programmes are expanding polyurethane consumption for civil engineering joints.
- Sealing:Facade weatherproofing and structural glazing require movement-capable formulations certified to BS EN 15651-4 fire-performance standards. London commercial tower developments consolidate material decisions at the pre-construction phase through BIM-integrated specification platforms.
- Adhesion:Structural bonding applications in cladding and flooring split between high-modulus silicones and hybrid polymer systems.
- Insulation:Air-sealing and vapour-control layers in residential retrofit are expanding demand for low-VOC neutral-cure silicones.
Sealing commands the established base. Waterproofing infrastructure applications are climbing the fastest.
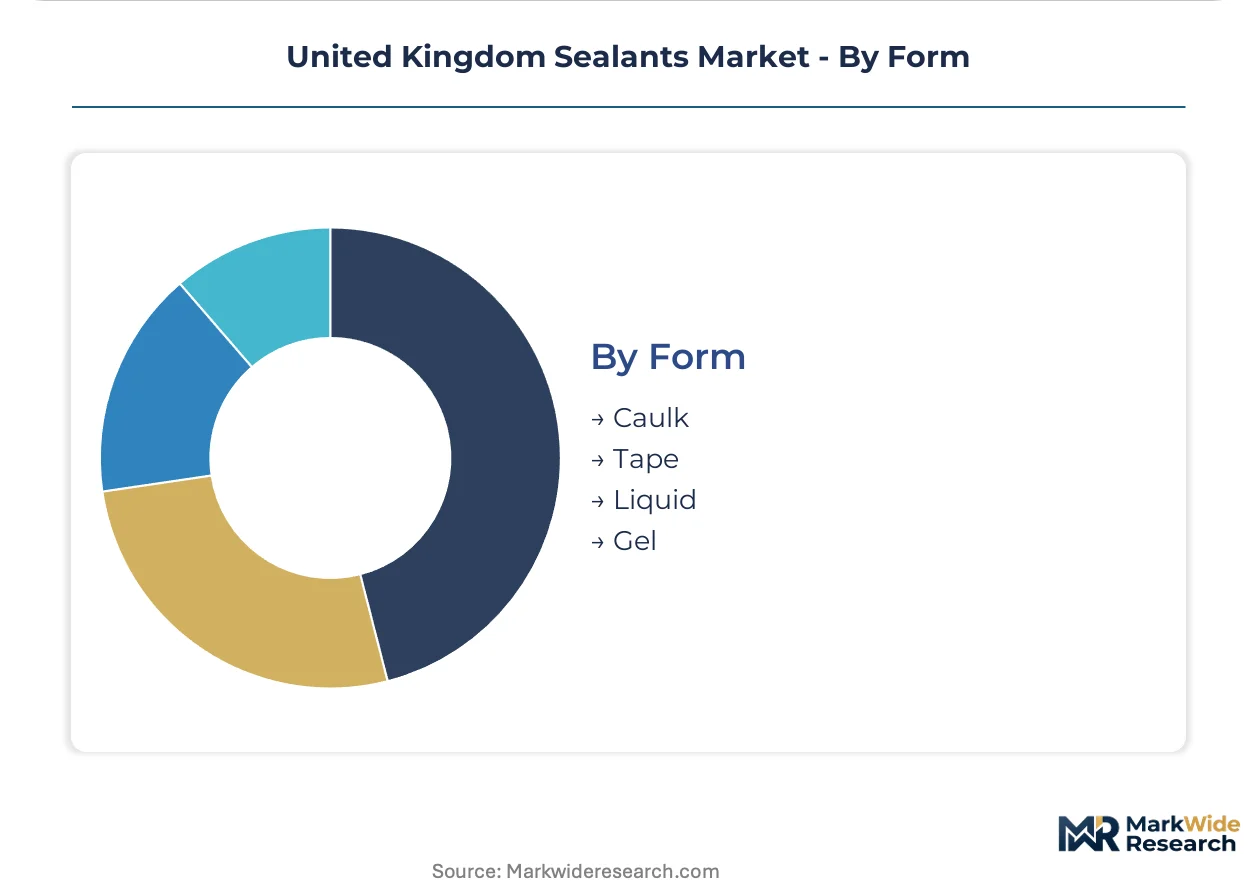
Form:
Liquid and caulk formats dominate construction-site application, while tape and gel forms concentrate in manufacturing-integrated and precision-electronics segments.
- Liquid:Pump-grade and pourable formulations serve expansion joints, bridge decks, and horizontal waterproofing. Civil engineering contractors specify self-levelling polyurethane liquids for movement joints exceeding fifty millimetres width.
- Caulk:Cartridge-dispensed pastes remain the standard format for facade and interior joint sealing. Building maintenance contractors across Greater London prioritize same-day availability of standard caulk grades.
- Tape:Preformed butyl and acrylic tapes serve glazing rebate bedding and temporary sealing applications in offsite construction manufacturing.
- Gel:Soft silicone encapsulants protect electronic assemblies from moisture and thermal cycling. Electronics manufacturing in the South East and South West is expanding procurement for potting and conformal coating grades.
Caulk commands the established base. Gel formats for electronics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between the cladding-intensive South East and infrastructure-heavy Northern regions, with Scotland and Wales exhibiting distinct procurement profiles tied to their public sector construction pipelines.
Greater London and South East
High-rise remediation programmes under the Building Safety Act dominate procurement, with government-funded cladding replacement driving sustained volume for intumescent silicone grades. Approved Document B fire-safety requirements mandate wholesale reformulation of facade systems. London commercial tower developments consolidate material decisions through BIM-integrated specification platforms.
Midlands
HS2 phase completions and Network Rail bridge waterproofing programmes are expanding specification-grade polyurethane consumption for civil engineering joints. Transport infrastructure renewal concentrates procurement around Birmingham and the East Midlands construction corridor. West Midlands automotive manufacturing clusters source validated sealant formulations for OEM seam sealing and glazing integration.
North England
Manchester, Leeds and Liverpool high-rise residential clusters present underpenetrated demand for specification-grade facade sealants outside the saturated South East corridor. Northern Powerhouse construction acceleration is redirecting distributor investment toward regional specification support. Yorkshire bridge maintenance programmes are consuming pourable polyurethane liquids for expansion joints exceeding fifty millimetres width.
Scotland
Public sector housing retrofit and offshore wind foundation sealing are distinctive demand drivers diverging from English construction patterns. Scottish Building Standards fire-performance requirements align with but predate UK-wide post-Grenfell tightening. Aberdeen energy sector maintenance contracts sustain niche demand for chemically resistant grades in coastal environments.
Wales
Social housing energy efficiency retrofits and steel-framed industrial construction shape a procurement mix weighted toward air-sealing and weatherproofing applications. Welsh Government net-zero building stock commitments are accelerating residential envelope upgrade programmes. Cardiff and Newport construction activity concentrates demand for low-VOC neutral-cure silicones in healthcare and education estates.
United Kingdom Sealants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin producers commanding margin resilience through captive upstream supply while formulation specialists compete on specification relationships and distribution density. Dow leverages captive silicone intermediates to sustain construction-grade portfolio margins. Sika AG anchors position through infrastructure waterproofing specification. Hodgson Sealants competes on regional same-day availability for building maintenance contractors. Strategic moves center on UKCA marking transition services and hybrid chemistry development.
Among integrated material science conglomerates, Dow and Sika AG exemplify the upstream-control archetype, with geographic origins evident in their corporate structures. Within the regional specialist tier, Hodgson Sealants occupies a position defined by distribution proximity to London maintenance markets. Henkel AG & Co. KGaA and 3M represent diversified adhesive-sealant portfolios spanning construction and industrial applications. Arkema Group and RPM International Inc. sit within the specialty chemicals archetype, with corporate suffixes indicating their structural positioning. The competitive dynamic pits captive supply resilience against specification-grade technical service capabilities.
| Leading Market Players |
|---|
| Dow |
| Hodgson Sealants |
| Sika AG |
| 3M |
| Adshead Ratcliffe & Co Ltd. |
| Henkel AG & Co. KGaA |
| Soudal Holding N.V. |
| RPM International Inc. |
| Arkema Group |
| Others |
Value Network & Pricing Analysis
Chlorosilane capacity utilization at German and Belgian precursor facilities shapes both supply concentration and price floors for UK formulation specialists lacking captive upstream integration. Scale economies in silicone intermediate production compress margins for non-integrated competitors while sustaining premium positioning for specification-grade facade systems.
Pricing Analysis
After-sales certification support and UKCA marking advisory services drive lifetime value for specification-grade suppliers. Three-tier pricing structure across premium intumescent grades, standard construction silicones, and economy acrylic alternatives stratifies procurement by project scale and regulatory exposure. Price differentiation hinges on BS EN 15651-4 fire-performance certification tier and volume contract terms. Cost compression in standard-grade silicone runs through European chlorosilane supply bottlenecks and energy input volatility. Residential maintenance contractors exhibit highest price sensitivity, while London commercial tower developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Germany and Belgium anchor chlorosilane intermediate production for silicone sealant feedstocks, while China and South Korea supply isocyanate precursors for polyurethane systems. UK formulation specialists draw from concentrated European resin supply for facade-grade silicones and Asia-Pacific chemical inputs for civil engineering polyurethanes. Single-source vulnerability in chlorosilane supply exposes margin compression risk from energy cost spikes at German precursor facilities. Distribution runs through merchant builders' merchants and specification-direct channels to tier-one contractors, with BIM-integrated platforms consolidating procurement decisions at pre-construction phase.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK sealants market is accelerating through post-Grenfell regulatory disruption, with Building Safety Act remediation mandates forcing wholesale reformulation of facade systems and creating specification-grade premium capture opportunities.
For Market Incumbents: Shield specification-grade positioning through accelerated UKCA marking certification investment ahead of full CE displacement, and anchor margin resilience through backward integration into silicone intermediate sourcing or long-term offtake agreements with German chlorosilane producers. Acrylic substitution in interior residential applications threatens volume erosion for standard-grade silicones. For New Entrants and Emerging Players: UKAS-accredited laboratory testing fast-tracks open specification access for hybrid silicone-polyurethane chemistries targeting structural movement joints previously served by single-chemistry incumbents. Northern Powerhouse high-rise residential clusters in Manchester and Leeds present underpenetrated demand outside saturated South East corridors. Specification-direct technical service capabilities, not merchant channel presence, secure initial contractor adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification-capable formulation specialists with UKCA advisory service attach rates. Five-to-ten year viability favors targets with established BS EN 15651 testing relationships and hybrid chemistry R&D pipelines over commodity acrylic distributors. Monitor UKAS laboratory capacity expansion as inflection signal for certification backlog clearance and product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Certification Investment | Accelerates market access ahead of full CE marking displacement under Construction Products Regulation. |
| Hybrid Chemistry Development | Captures structural movement joint specifications previously divided between silicone and polyurethane incumbents. |
| Backward Integration into Precursors | Insulates margin resilience from German chlorosilane supply bottlenecks and energy cost volatility. |
| Digital Specification Platform Integration | Aligns procurement channel presence with BIM-adopted tier-one contractor pre-construction decision consolidation. |
| Northern Powerhouse Distribution Expansion | Secures first-mover positioning in Manchester and Leeds high-rise residential clusters ahead of incumbent redirection. |
Research Methodology
Operator-level perspectives from facade engineers, building maintenance contractors, merchant procurement managers, and UKAS laboratory technical directors anchored the qualitative base for this analysis. Primary field engagement with tier-one construction specification teams and sealant formulation R&D heads combined with secondary validation through British Standards Institution certification databases, Health and Safety Executive REACH enforcement disclosures, and Construction Products Regulation marking transition guidance. Customs trade data and UK construction output statistics provided volume triangulation against bottom-up segment modeling.
Sensitivity analysis across chlorosilane price volatility scenarios and UKCA certification timeline assumptions informed projection robustness. The analytical framework modeled formulation chemistry, end-use construction segment, application method, and geographic procurement cluster dimensions across the projection horizon. CAGRs derived from segment-level volume build-ups incorporating Building Safety Act remediation spend allocation and infrastructure pipeline commitments. Fire-testing certification backlogs and qualified facade engineer workforce availability served as key forecast inputs.
Underlying assumptions cover sustained government cladding remediation funding, stable REACH isocyanate enforcement trajectory, and UKCA marking transition adherence to announced timelines, with deviation risk concentrated in laboratory testing capacity constraints and precursor supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Removable Adhesive Market