
 Urethane Adhesives Market | 2026-2036
Urethane Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Urethane Adhesives Market Outlook
The gap between premium structural-grade urethane adhesives and commodity construction sealants is hardening as automotive OEMs demand certified crash-durable formulations while price-sensitive building contractors prioritize bulk volume. Henkel AG & Co. KGaA leverages its European automotive certification portfolio to anchor high-margin supply contracts with German and Chinese EV manufacturers. H.B. Fuller Company competes through geographic dominance in North American woodworking and furniture assembly channels. Dow Inc. differentiates via captive polyol supply and in-house isocyanate production that insulates margin structures from raw material volatility.
Urethane adhesives are polymers formed from polyol and isocyanate reactions, typically exhibiting tensile strengths of 20–40 MPa and Shore A hardness values between 40 and 90 depending on crosslink density formulation. These adhesives bond dissimilar substrates—metals, composites, plastics, and wood—through chemical curing mechanisms that produce durable elastomeric joints resistant to thermal cycling and moisture ingress. Two-component systems command the deepest margin pools due to custom formulation services and on-site technical support requirements from aerospace and wind energy clients. Water-based technology is expanding fastest as EPA VOC limits and EU solvent emissions directives push manufacturers away from solvent-borne systems, though hot melt urethanes retain cost advantages in high-speed packaging and textile lamination.
EPA VOC regulations under the Clean Air Act and REACH substance restrictions administered by ECHA are forcing reformulation investments across solvent-based product lines, while China's MEE enforces GB standards on industrial adhesive emissions in manufacturing zones. The EU Green Deal's carbon border adjustments will raise compliance costs for imported adhesive precursors, favoring regional producers with certified low-carbon supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D spending.
Market Dynamics
Automotive OEMs in Germany and China are consolidating specification authority around crash-durable bonding systems, forcing adhesive suppliers to absorb certification costs while commodity construction demand fragments toward price-only procurement.
Growth Catalysts
- Electric vehicle platform bonding:EV manufacturers in China are scaling bonded aluminum-composite structures to reduce chassis weight, creating specification pull for structural-grade formulations.
- REACH substance restrictions:ECHA's evolving SVHC list is accelerating reformulation investment toward low-toxicity isocyanate alternatives, opening technical differentiation windows for compliant suppliers.
- Wind energy blade assembly:Offshore turbine OEMs are specifying two-component urethane systems for root-to-blade bonding, demanding on-site technical support that deepens supplier relationships.
Market Restraints
- MDI price volatility:Methylene diphenyl diisocyanate feedstock costs swing with crude oil and benzene markets, compressing margin predictability for non-integrated formulators.
- Supply concentration in polyether polyols:Captive production at Dow, BASF, and Covestro limits independent adhesive producers' negotiating leverage on key raw materials.
- Cyanoacrylate substitution in electronics:Instant-bonding acrylics are displacing urethanes in consumer device assembly where thermal cycling resistance is secondary.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for domestic manufacturing are creating adhesive demand in Gujarat and Tamil Nadu automotive clusters where local formulation capacity remains scarce.
- Water-borne system conversion:EPA VOC limits and EU solvent emissions directives are mandating aqueous technology transitions, rewarding suppliers with proven low-VOC platforms.
- Digital dispensing integration:Robotic application systems in German automotive plants are converging with adhesive telemetry, creating service revenue streams around precision dosing.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in isocyanate-polyol stoichiometry and catalyst selection is concentrating at incumbent suppliers, constraining new entrant R&D velocity.
- Dual certification timelines:Parallel OEM approvals from German KBA and Chinese MIIT extend qualification cycles, tying up working capital in inventory dedicated to unapproved specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urethane Adhesives Market |
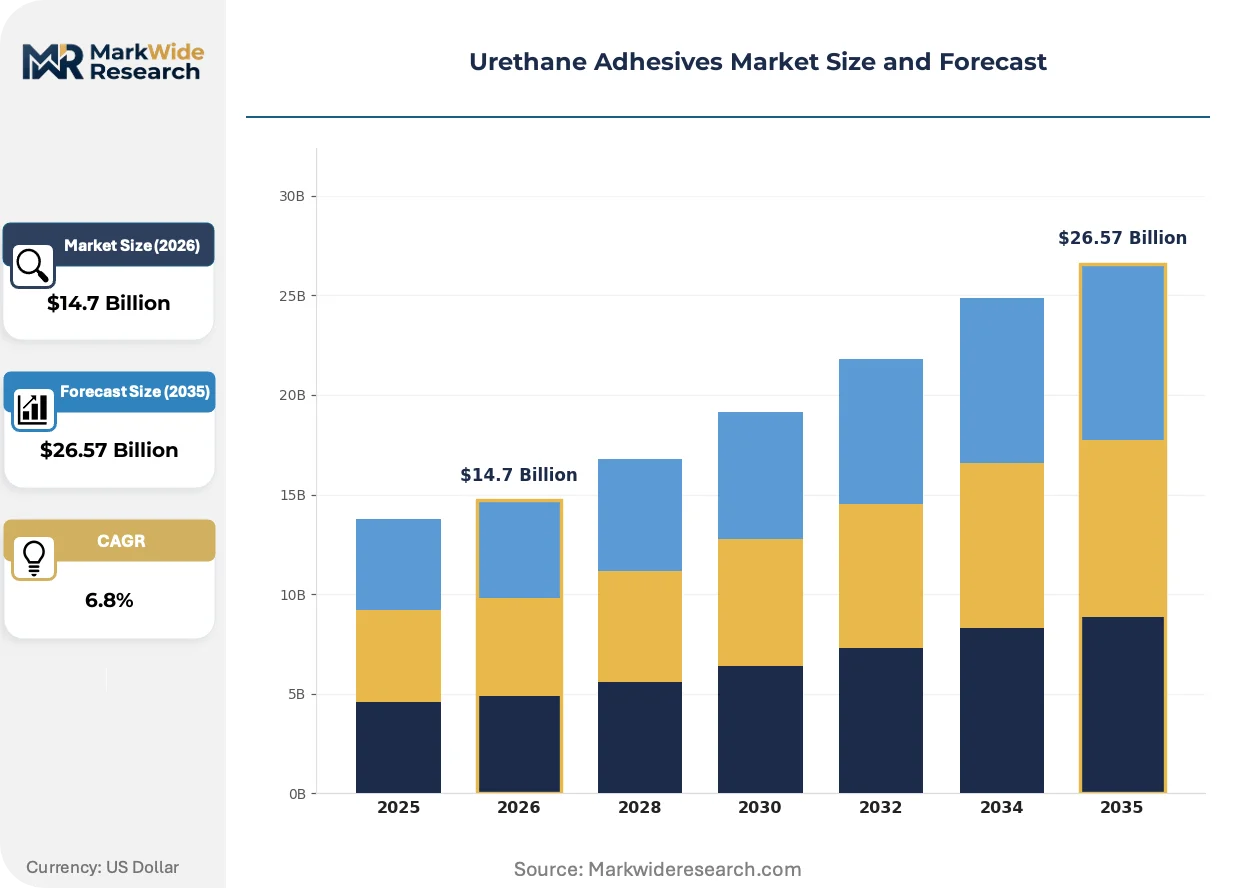
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Component, Two-Component, Moisture-Cure, Reactive End User: Automotive, Construction, Woodworking, Aerospace Application: Bonding, Coating, Sealing, Potting Technology: Solvent-Based, Water-Based, Hot Melt, UV-Curable |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, 3M, Dow Inc., Huntsman International LLC, Arkema, BASF, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urethane Adhesives Market Strategic Shifts
Formulation science and application technology are diverging along regulatory fault lines, with water-borne systems gaining specification share in regulated markets while hot-melt platforms defend cost-sensitive segments.
UV-curable urethane acrylate hybrids are decentralizing production workflows by enabling on-demand curing without thermal ovens. Furniture manufacturers in Poland and Vietnam are adopting these systems to eliminate drying bottlenecks. The technology is compressing batch processing economics and reducing floor space requirements for mid-scale fabricators.
REACH authorization requirements for diisocyanate professional use are forcing training mandates across EU member states. Industrial adhesive applicators must now document certified safe handling protocols. German automotive suppliers are absorbing compliance costs into service contracts, while smaller construction distributors are exiting professional-grade product lines.
Specification authority is migrating from general contractors to OEM engineering departments in automotive and wind energy verticals. Tier-1 suppliers now source adhesives through approved vendor lists rather than open procurement. This concentration is most visible in China's Yangtze River Delta EV manufacturing corridor, where battery pack bonding specifications are locked years ahead of production ramp.
Urethane Adhesives Market Segmentation
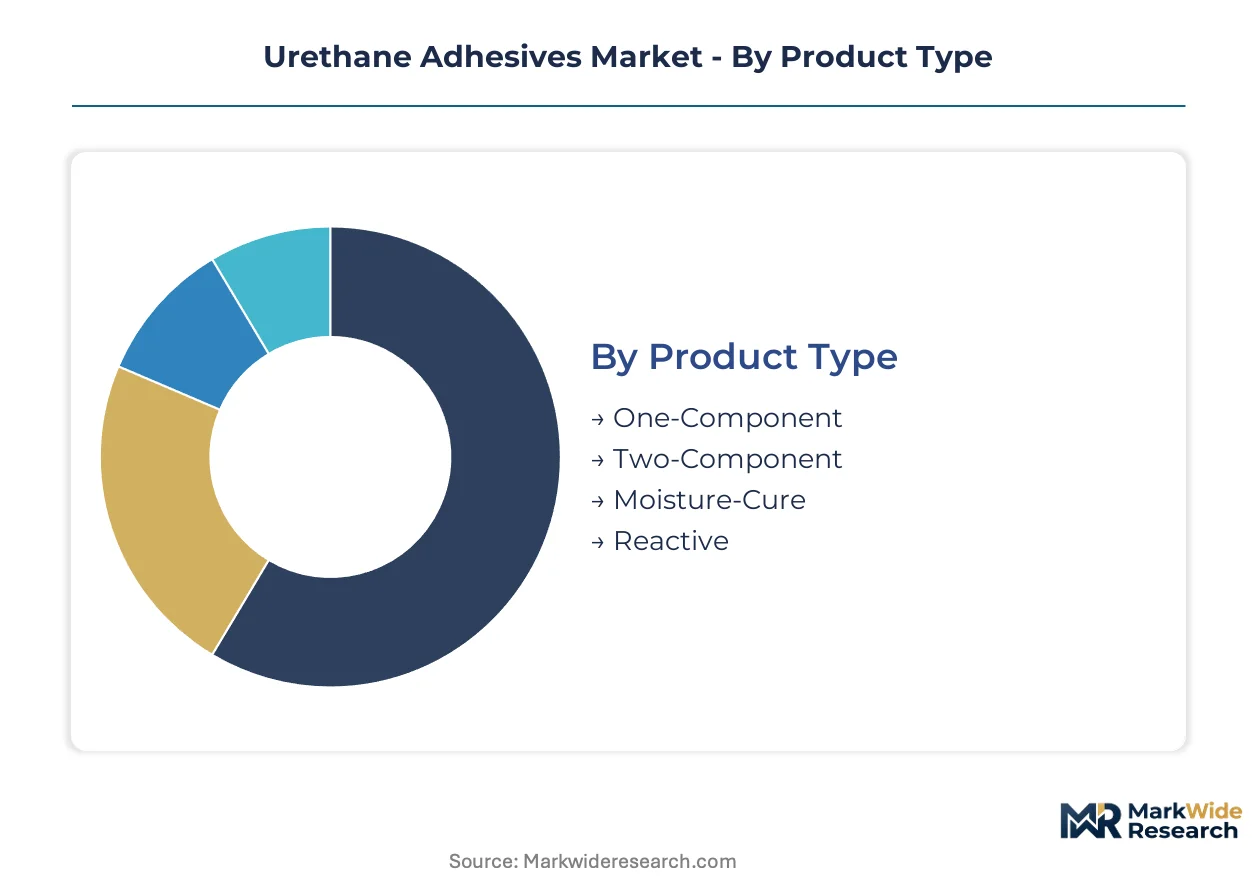
Urethane adhesive formulations diverge sharply in curing chemistry and application complexity, creating distinct margin pools and technical support requirements. Segmentation by product architecture, end-use vertical, functional application, and formulation technology determines supplier qualification pathways and capital deployment priorities.
Product Type:
Integration depth varies from standalone moisture-reactive systems to engineered two-component platforms requiring precision metering equipment.
- One-Component:Pre-formulated systems cure via ambient moisture or heat activation without on-site mixing. Automotive assembly lines in Germany specify these for interior trim bonding where process simplicity outweighs customization needs.
- Two-Component:Separate resin and hardener streams combine at the point of application, enabling tunable cure rates and superior structural performance. Wind turbine blade manufacturers in China's Jiangsu province demand these systems for root-to-blade joints requiring load-bearing integrity.
- Moisture-Cure:Atmospheric humidity triggers polymerization, eliminating oven requirements for field repairs and on-site construction.
- Reactive:Catalyzed systems offer rapid fixture times for high-throughput manufacturing environments.
Volume placements concentrate in One-Component formulations; the faster expansion belongs to Two-Component systems.
End User:
Customer sophistication spans from specification-driven OEM engineering departments to price-sensitive bulk procurement.
- Automotive:Crash-durable bonding specifications for aluminum-composite chassis structures command premium pricing and multi-year qualification cycles. EV platforms in China's Yangtze River Delta and Germany's Baden-Württemberg region anchor demand concentration.
- Construction:Building envelope sealing and structural glazing applications favor high-volume, lower-margin formulations where contractors prioritize per-unit cost over technical service.
- Woodworking:Furniture and flooring manufacturers value hot-melt compatibility for high-speed lamination lines.
- Aerospace:FAA and EASA certification requirements for cabin interior bonding restrict supply to qualified vendors with documented flame-smoke-toxicity compliance.
Automotive procurement dominates value capture; Construction absorbs the highest absolute tonnage.
Application:
Functional role determines performance specifications and failure-mode tolerance.
- Bonding:Structural load transfer between dissimilar substrates—metal to composite, plastic to wood—requires tailored modulus matching and thermal expansion compensation.
- Coating:Protective films and wear-resistant layers leverage urethane toughness for abrasion protection in industrial equipment.
- Sealing:Elastic joint fillers accommodate movement in building envelopes and transportation vehicle bodies.
- Potting:Encapsulation of electronic assemblies demands dielectric stability and moisture barrier properties.
Bonding commands the deepest technical margins; Potting is climbing the fastest as electronics miniaturization accelerates.
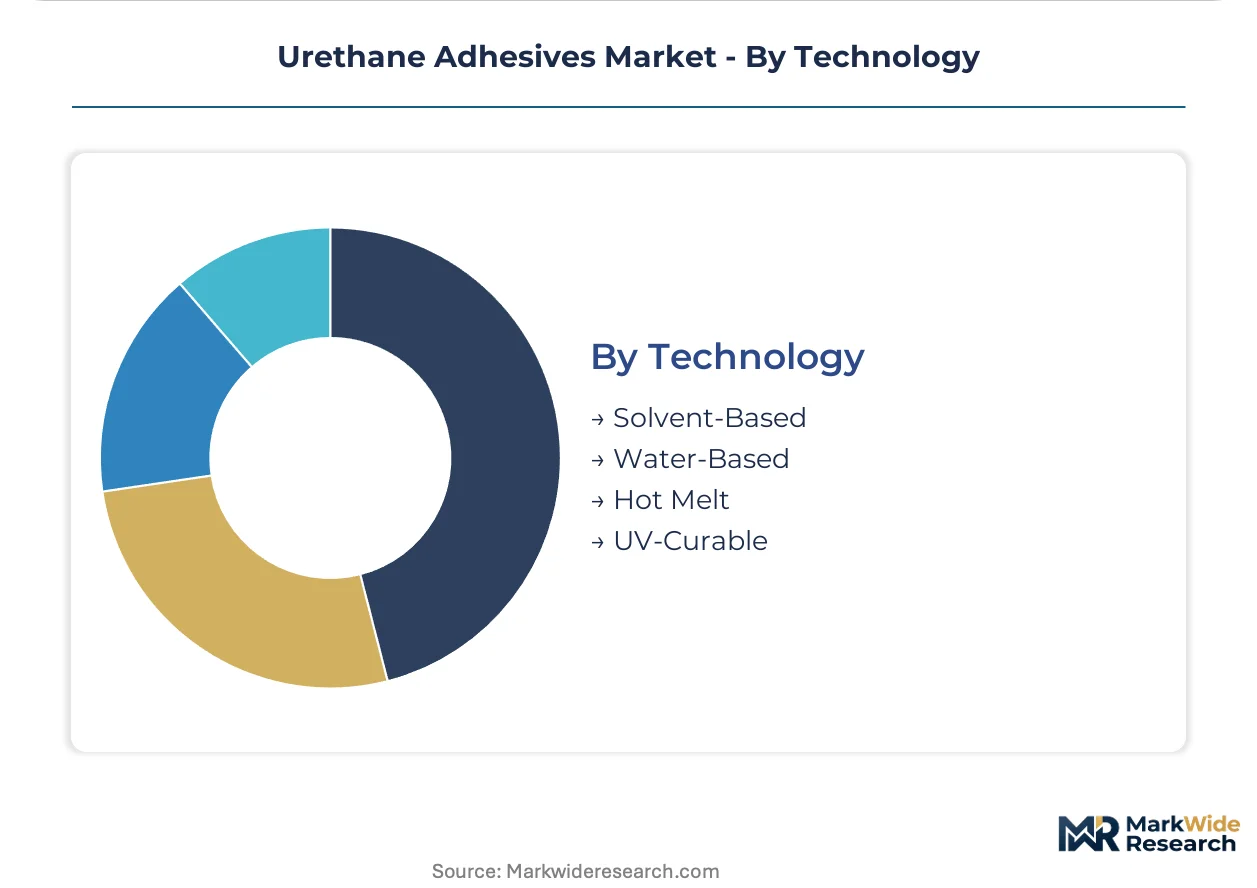
Technology:
Regulatory pressure and application economics are fragmenting formulation chemistry across jurisdictions.
- Solvent-Based:Traditional systems offer rapid drying and substrate wetting but face EPA VOC limits and EU solvent emissions directives. Reformulation investments are concentrating at Dow and BASF facilities.
- Water-Based:Aqueous dispersions eliminate volatile organic content while retaining elastomeric performance. China's MEE enforcement of GB standards in manufacturing zones is accelerating specification shifts.
- Hot Melt:Thermoplastic urethanes enable clean, fast processing without cure time delays. Packaging and textile lamination lines in Vietnam and Poland favor these for throughput economics.
- UV-Curable:Urethane acrylate hybrids cure on demand under ultraviolet exposure, eliminating thermal ovens. Furniture fabricators are adopting these systems to compress batch processing cycles.
Solvent-Based retains legacy volume; Water-Based platforms are gaining share fastest under tightening emissions frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global urethane adhesive demand concentration, with EV battery pack bonding specifications locked years ahead of production ramp across Suzhou, Ningbo, and Shanghai manufacturing corridors.
China
Electric vehicle platform scaling in Jiangsu province drives structural-grade formulation demand for aluminum-composite chassis bonding. MIIT enforces GB standards on industrial adhesive emissions in manufacturing zones. The Yangtze River Delta EV corridor concentrates specification authority with OEM engineering departments rather than open procurement channels.
Germany
Automotive assembly lines in Baden-Württemberg expand consumption for lightweight vehicle bonding applications. REACH compliance administered by ECHA tightens formulation standards and reshapes supplier qualification requirements. KBA certification timelines for crash-durable systems extend qualification cycles, tying up working capital in inventory dedicated to unapproved specifications.
United States
Woodworking and furniture assembly channels in the Southeast and Midwest absorb high-volume hot-melt formulations. EPA VOC regulations under the Clean Air Act push manufacturers away from solvent-borne systems. Industrial clusters in Michigan and Ohio face reformulation investments as emissions frameworks tighten.
India
PLI scheme incentives for domestic manufacturing create adhesive demand in Gujarat and Tamil Nadu automotive clusters. BIS standards on industrial chemical emissions apply pressure on imported precursor compliance. Local formulation capacity remains scarce in the Chennai-Bengaluru industrial corridor where bonded composite structures are scaling.
Japan
Electronics miniaturization accelerates potting application demand for dielectric stability and moisture barrier properties. METI oversees industrial chemical safety protocols affecting adhesive handling mandates. Precision manufacturing clusters in the Nagoya-Chubu region specify urethane systems for high-reliability electronic encapsulation.
Urethane Adhesives Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and raw material integration. The vendor base organizes into three tiers: integrated chemical conglomerates with captive polyol supply, formulation specialists with automotive OEM approvals, and regional distributors serving price-sensitive construction channels. Dominant competitive moves include backward integration into isocyanate production and geographic expansion through qualified vendor list penetration.
Within the integrated chemical tier, Dow Inc. and BASF exemplify archetypes with upstream control over key precursors. Among formulation specialists, Henkel AG & Co. KGaA and H.B. Fuller Company occupy positions anchored by automotive certification portfolios and regional channel dominance respectively. Sika AG represents the construction-specialist archetype with technical service capabilities in building envelope applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| 3M |
| Dow Inc. |
| Huntsman International LLC |
| Arkema |
| BASF |
| Illinois Tool Works Inc. |
| Others |
Value Chain & Pricing Dynamics
MDI and polyether polyol feedstock costs cascade through three pricing tiers from captive producers like Dow and BASF to independent formulators serving automotive OEMs, construction contractors, and packaging converters. This input-cost architecture stratifies margin pools across certification-grade structural adhesives and commodity sealants.
Pricing Analysis
Crash-durable bonding outcomes for aluminum-composite EV chassis anchor value-based pricing at the premium tier, with German KBA and Chinese MIIT certification levels differentiating price bands. Volume-scale construction procurement drives cost compression at the commodity tier, while automotive OEMs show lowest price sensitivity due to qualification lock-in. Pricing pressure stems from MDI volatility and REACH reformulation investments, compressing margins for non-integrated suppliers.
Supply Chain Analysis
Empty adhesive container returns and spent catalyst recovery flows remain underdeveloped across the urethane value chain, with most formulators lacking closed-loop logistics infrastructure. Captive polyol production concentrates in the United States, Germany, and China, while isocyanate supply draws from benzene-crude oil nexus points. Single-source vulnerability runs through MDI feedstock concentration at integrated chemical conglomerates. Distribution runs through qualified vendor lists for automotive and wind energy verticals, with open wholesale channels serving construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH diisocyanate authorization requirements and EPA VOC limits have erected a cost-of-compliance barrier that favors incumbents with certified low-carbon supply chains and documented safe-handling protocols.
For Market Incumbents: Anticipate cyanoacrylate substitution threats in electronics assembly by deepening formulation expertise in potting applications for electric vehicle battery packs. Prioritize backward integration into specialty polyols to insulate margin structures from Dow and BASF supply concentration. Channel control through approved vendor list penetration in China's Yangtze River Delta offers defensive positioning against emerging regional competitors. For New Entrants and Emerging Players: Regional distributors serving India's Gujarat and Tamil Nadu automotive clusters represent the most penetrable channel archetype, given scarce local formulation capacity and PLI scheme demand acceleration. Target water-borne system conversion mandates as a technical differentiation wedge, with on-site dispensing integration services as the go-to-market anchor. Avoid direct confrontation with Henkel and H.B. Fuller in saturated German and North American certification channels. For Investors and Strategic Acquirers: MIIT approval timelines extending beyond 18 months for crash-durable formulations is the leading indicator that qualified vendor list scarcity will deepen acquisition premiums for certified suppliers. Five-to-ten year viability favors formulators with automotive OEM relationships and captive precursor supply, not pure-play construction distributors. Monitor ECHA SVHC list expansions for signals of forced reformulation investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Production | Captive MDI supply insulates margin structures from benzene price volatility at Dow and BASF. |
| Water-Borne Platform Conversion | EPA VOC limits and EU solvent emissions directives mandate aqueous technology transitions. |
| Digital Dispensing Integration | Robotic application telemetry in German automotive plants creates recurring service revenue streams. |
| Regional Manufacturing Footprint Expansion | India's PLI scheme incentives in Gujarat and Tamil Nadu clusters address formulation capacity scarcity. |
| Joint Venture with Polyol Producer | Partnerships with Covestro or Huntsman secure precursor supply for independent formulators. |
Study Parameters
SEC 10-K filings, customs and trade databases, and Cefic chemical industry reports formed the secondary backbone, cross-referenced with primary interviews involving adhesive formulation chemists, automotive Tier 1 procurement leads, wind energy blade manufacturing engineers, and construction distribution channel managers. Bottom-up and top-down triangulation validated volume estimates across product architectures and end-use verticals.
Bottom-up modeling aggregated segment-level demand from application-specific consumption rates, while top-down verification anchored totals to macroeconomic drivers across the projection horizon. Segmentation dimensions included curing chemistry, end-use vertical, functional application, and formulation technology, with CAGRs derived from regression analysis against automotive production indices and construction spending trends. Wind energy installation forecasts and EV platform penetration curves served as industry-specific demand inputs.
Caveats apply where MDI price spikes, REACH substance restrictions, or MIIT certification delays could materially shift the outlook. Practitioners should monitor ECHA SVHC list updates, EPA enforcement patterns, and Chinese GB standard revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Glue Pen Market