
 Reactive Adhesives Market | 2026-2036
Reactive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Reactive Adhesives Market Outlook
High-performance specification grades for electric vehicle battery packs and aerospace structural joints is bifurcating the competitive landscape into technology leaders and commodity suppliers. Henkel AG & Co. KGaA anchors its position through deep automotive OEM relationships and specialized two-part epoxy systems for crash-resistant bonding. Dow competes on material science integration, leveraging its upstream control over acrylic and polyurethane precursor chemistry. Sika AG dominates construction-sector specification tiers with silicone and hybrid reactive technologies engineered for seismic and thermal cycling endurance.
Reactive adhesives are thermosetting polymer systems that cure through chemical reaction rather than solvent evaporation, typically achieving lap-shear strengths exceeding 15 MPa and operating temperatures from -40°C to 180°C depending on base chemistry. Their primary industrial purpose is permanent structural bonding of dissimilar substrates where mechanical fastening fails or adds unacceptable weight. Epoxy formulations occupy the highest-margin specification tier in aerospace and electronics potting applications where outgassing control and dielectric stability command premium positioning. Polyurethane segments sustain volume leadership across automotive and construction bonding where flexibility and impact resistance balance cost performance. Reactive hot melt formulations represent the fastest-growing structural category, eliminating clamping time in automated assembly while delivering thermoset durability.
EPA VOC regulations and OSHA workplace exposure limits are forcing solvent-containing adhesive conversions toward 100% solid and reactive hot melt systems in U.S. manufacturing facilities. REACH substance restrictions and the EU Green Deal chemical sustainability criteria are reshaping raw material qualification across European supply chains, favoring bio-based epoxy hardeners and low-isocyanate polyurethane formulations. Stakeholders must monitor regulatory divergence between California Air Resources Board thresholds and EU ECHA authorization lists when configuring regional product portfolios and capital allocation for formulation asset upgrades.
Market Dynamics
Automotive lightweighting mandates and EV battery pack assembly requirements are pulling specification-grade epoxy and polyurethane systems into structural load-bearing applications previously dominated by mechanical fastening.
Growth Catalysts
- EV Battery Bonding Specifications:Electric vehicle manufacturers specify thermally conductive reactive adhesives for module-to-pack assembly, creating dedicated demand for flame-retardant epoxy grades with dielectric stability.
- REACH Substance Restrictions:The EU Green Deal chemical sustainability criteria accelerate solvent-free system development, favoring bio-based hardeners and low-isocyanate polyurethane formulations across European supply chains.
- Shanghai-Shenzhen Manufacturing Corridor:Electronics assembly and EV battery production in China's eastern seaboard consume premium reactive adhesive grades at volumes unmatched by other national clusters.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane precursor costs fluctuate with crude oil derivatives, compressing margin stability for formulation specialists without captive supply.
- Isocyanate Supply Concentration:Polyurethane adhesive production depends on MDI and TDI supply concentrated among Asian petrochemical complexes, exposing converters to allocation risk during upstream maintenance cycles.
- Cure Time Limitations:Two-part epoxy systems require controlled temperature and humidity conditions for full structural development, restricting field application in uncontrolled construction environments.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device assembly create first-mover advantage for reactive adhesive suppliers establishing localized technical service.
- Reactive Hot Melt Automation:Automated dispensing systems eliminate clamping time in high-speed assembly lines, opening automotive tier-one supplier specifications previously held by mechanical joining.
- FAA Outgassing Certification:Aerospace adhesive qualification for satellite and crewed vehicle applications commands 3-5x pricing premiums over industrial grades with limited qualified supplier lists.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in thermoset kinetics and substrate-specific adhesion testing concentrates among senior technical staff approaching retirement without adequate pipeline replacement.
- OEM Qualification Timelines:Automotive and aerospace structural bonding approvals require 18-36 month validation cycles, locking working capital in development programs before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reactive Adhesives Market |
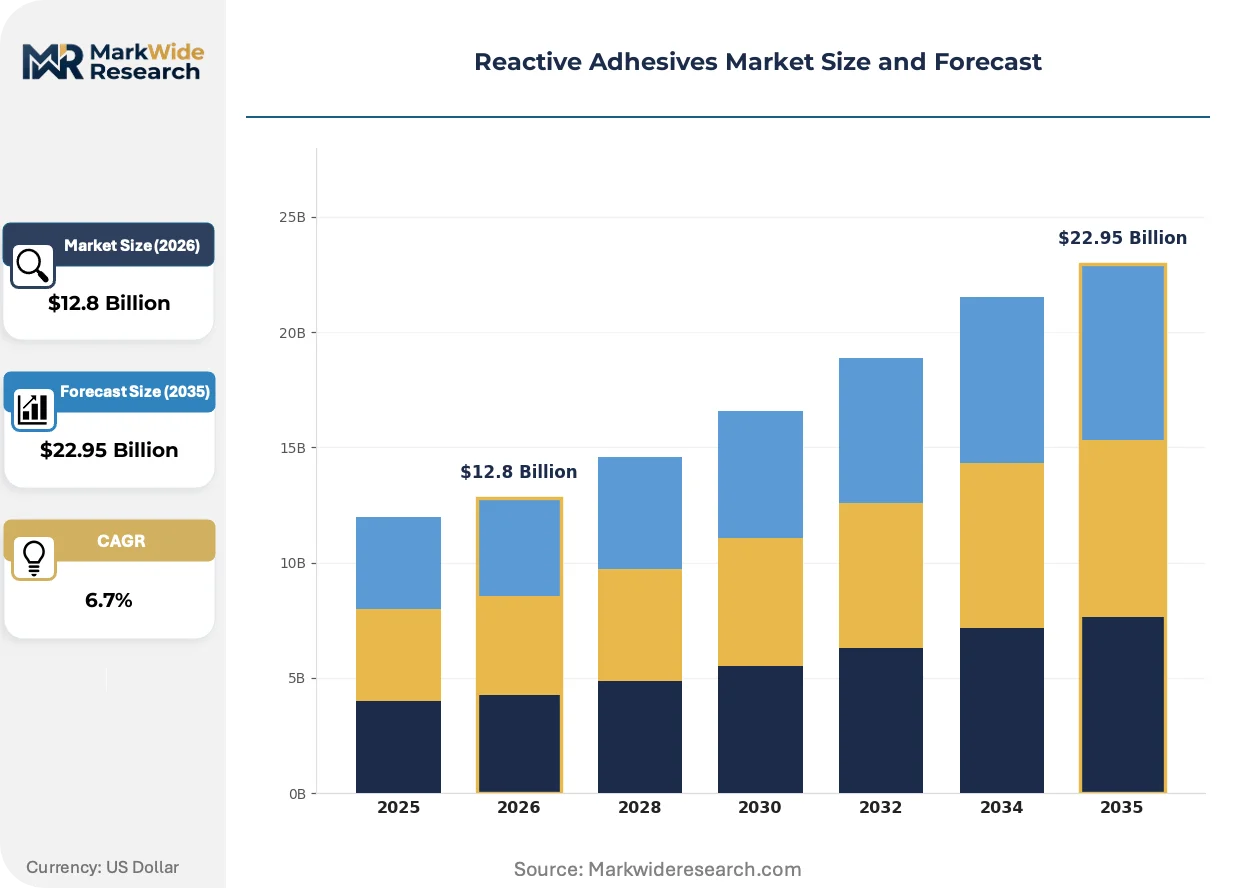
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Formulation: One-Part, Two-Part, 100% Solid, Reactive Hot Melt End Use: Construction, Automotive, Electronics, Aerospace Application: Bonding, Coating, Sealing, Potting |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Arkema Group, Dow, BASF, Illinois Tool Works, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reactive Adhesives Market Strategic Shifts
Formulation chemistry and curing equipment are converging to eliminate process bottlenecks that have historically restricted reactive adhesives to batch manufacturing environments.
Hybrid reactive technologies combining polyurethane backbone with silane terminal groups are fragmenting the construction sealant category. These systems cure through ambient moisture while delivering thermoset durability previously requiring heat-activated epoxies. European facade contractors adopt them for structural glazing applications demanding seismic movement accommodation and thermal cycling endurance.
EPA VOC regulations and OSHA workplace exposure limits are forcing solvent-containing adhesive conversions toward 100% solid systems in U.S. manufacturing facilities. The agency's National Emission Standards for Hazardous Air Pollutants directly impact adhesive formulation decisions in automotive assembly plants across Michigan and Tennessee. Manufacturers respond with reactive hot melt investments that eliminate solvent handling infrastructure.
Buyer consolidation among automotive OEMs and tier-one suppliers concentrates procurement leverage, compressing supplier lists to those with multi-continent technical service capability. Tier-one seating and electronics module suppliers in Germany and Japan now require formulation partners to maintain application engineering staff at their design centers. This behavioral shift favors integrated material science platforms over standalone adhesive specialists.
Reactive Adhesives Market Segmentation
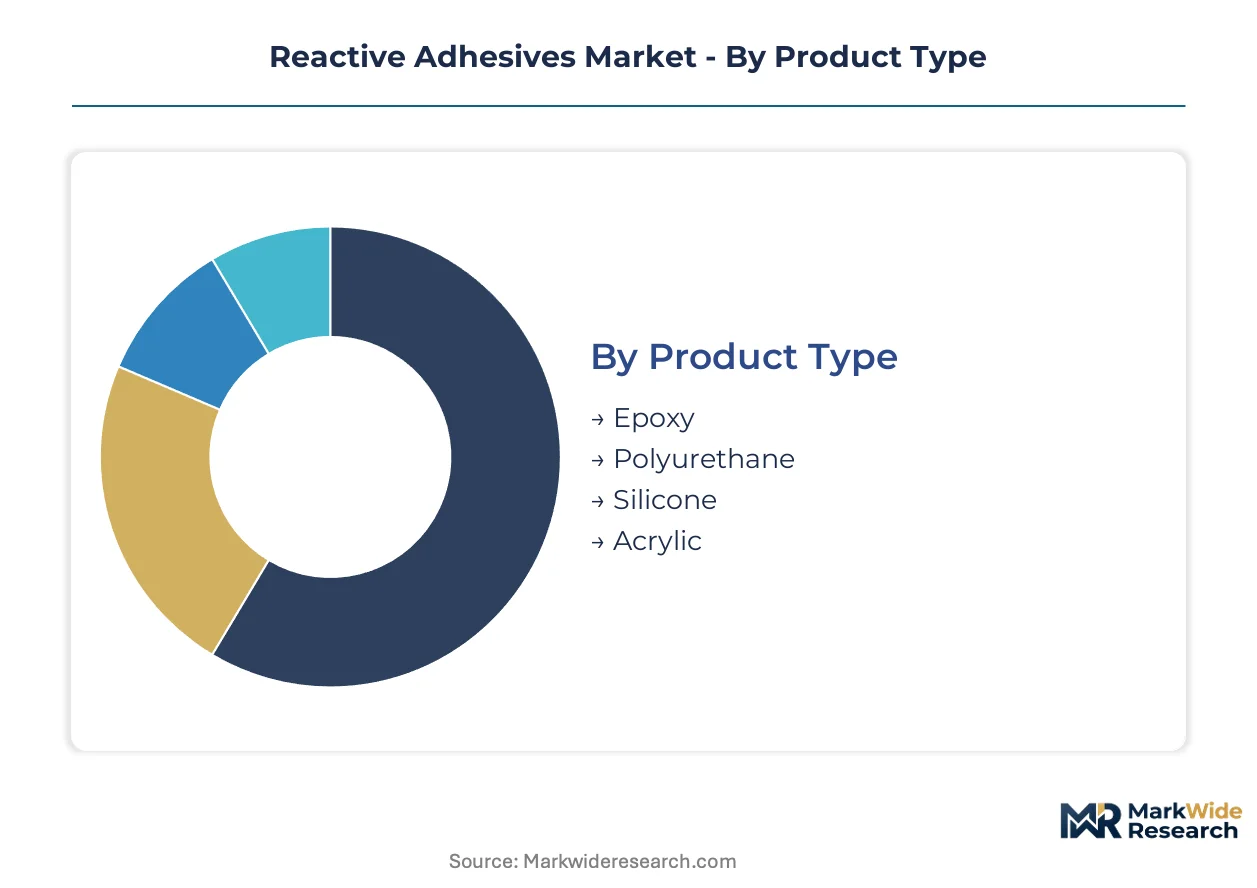
Reactive adhesives fragment across four distinct segmentation axes, each revealing divergent margin structures and qualification barriers. Product chemistry determines specification tiers, while formulation architecture dictates automation compatibility and regulatory compliance pathways.
Product Type:
Epoxy and polyurethane formulations dominate export-led demand for aerospace and automotive OEM qualifications, while silicone and acrylic grades serve more geographically dispersed construction and industrial maintenance applications.
- Epoxy:Thermoset systems built from bisphenol-A or novolac resins with amine or anhydride hardeners achieve glass transition temperatures exceeding 150°C. Demand concentrates in Germany and Japan where automotive lightweighting programs specify crash-resistant structural bonding for aluminum-intensive vehicle platforms, constrained by 18-36 month OEM qualification timelines.
- Polyurethane:Isocyanate-terminated prepolymers reacting with polyol blends deliver flexibility and impact resistance across -40°C to 120°C operating windows. China's eastern manufacturing corridor consumes premium grades for EV battery pack assembly where thermal cycling endurance and dielectric stability command supplier certification.
- Silicone:Moisture-curing polydimethylsiloxane systems provide UV stability and thermal expansion accommodation for facade glazing and semiconductor encapsulation.
- Acrylic:Radical-curing methacrylate and cyanoacrylate formulations target high-speed industrial assembly with rapid fixture times and bonding of oily or contaminated substrates.
Epoxy holds the largest share; momentum sits with polyurethane as EV production scales.
Formulation:
Cost tier stratification separates capital-intensive 100% solid systems from commodity one-part moisture cures, with reactive hot melt investments climbing fastest among automotive tier-one suppliers.
- One-Part:Pre-mixed systems curing through ambient moisture, heat activation, or UV exposure eliminate metering equipment and mixing ratios. Construction contractors across seismic zones favor silicone and hybrid one-part technologies for structural glazing where field conditions preclude two-part processing control.
- Two-Part:Meter-mix-dispense systems combining resin and hardener at point of application achieve highest structural performance with pot-life constraints. Aerospace manufacturers in the United States and France specify two-part epoxies for satellite and crewed vehicle bonding where FAA outgassing certification limits qualified supplier pools.
- 100% Solid:Solvent-free formulations meeting EPA VOC and REACH substance restrictions command formulation asset upgrades across European and North American manufacturing footprints.
- Reactive Hot Melt:Thermoplastic application with thermoset final properties eliminates clamping time in automated assembly, gaining share fastest among Japanese and German automotive seating and electronics module producers.
Two-part systems dominate specification-grade revenue; reactive hot melt is expanding most quickly through automation retrofit cycles.
End Use:
Customer type concentration varies sharply: automotive and electronics procurement consolidates among tier-one suppliers with multi-continent technical service requirements, while construction specification remains fragmented across regional contractors.
- Construction:Structural glazing, concrete repair, and facade sealing applications specify hybrid reactive technologies for seismic movement and thermal cycling endurance. European facade contractors adopt silane-terminated polyurethane systems for high-rise projects where heat-activated epoxy curing is impractical.
- Automotive:OEM lightweighting mandates displace mechanical fastening with structural bonding in body-in-white and closure panel assembly. Germany's KBA crashworthiness standards and Japan's METI fuel efficiency regulations accelerate specification-grade epoxy and polyurethane adoption.
- Electronics:Semiconductor packaging, display bonding, and PCB potting applications demand low-outgassing, ionically pure formulations. China's MIIT domestic semiconductor initiatives and India's PLI scheme for mobile device assembly create localized technical service requirements.
- Aerospace:Satellite structures, radomes, and interior cabin bonding command 3-5x pricing premiums over industrial grades with limited qualified supplier lists maintained by FAA and EASA certification protocols.
Automotive holds the largest share; electronics is gaining share fastest through semiconductor reshoring incentives.
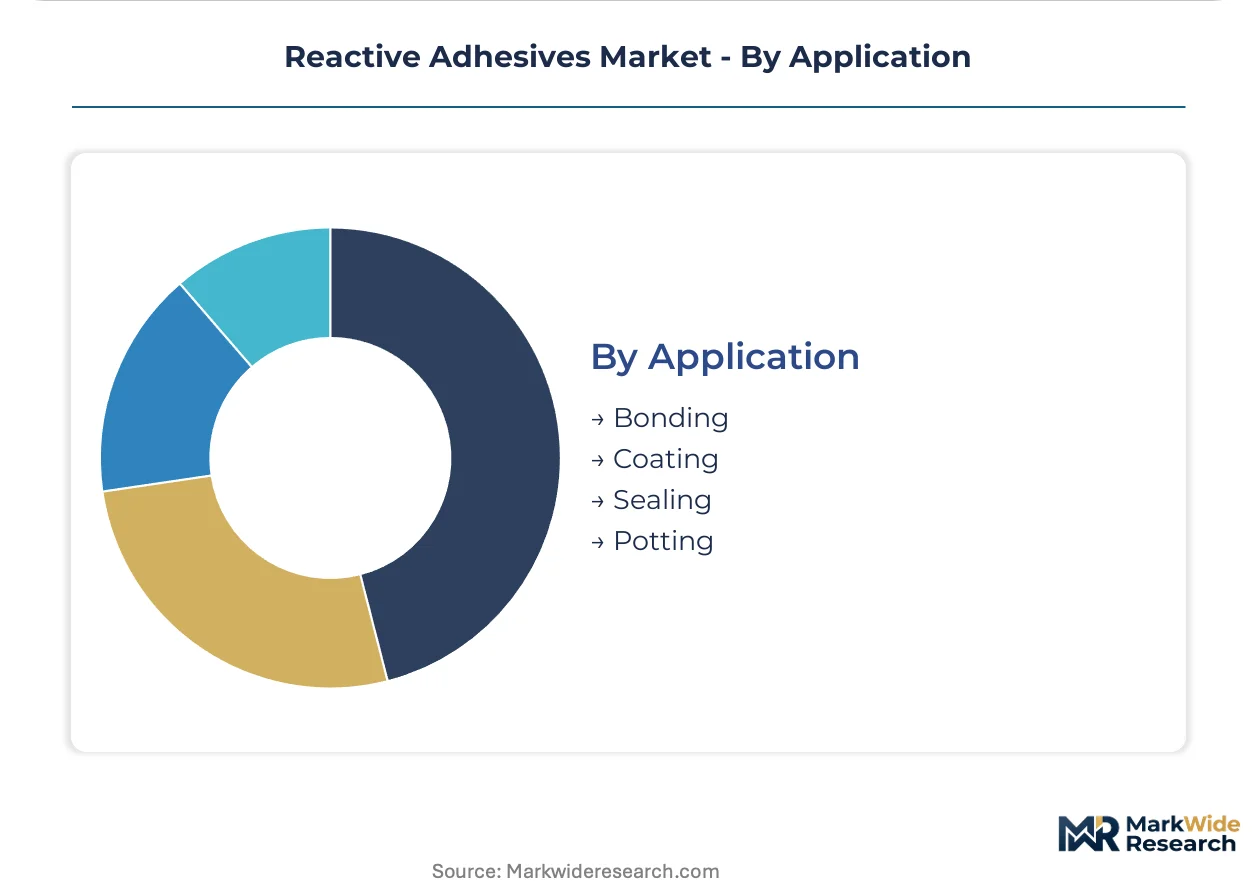
Application:
Maturity differentiation separates established bonding and sealing categories from emerging potting demand in EV battery and power electronics protection.
- Bonding:Primary structural load transfer between dissimilar substrates where mechanical fastening adds unacceptable weight or stress concentration. Automotive OEMs in Michigan and Tennessee specify reactive adhesives for aluminum-steel mixed-material joining under EPA NESHAP compliance pressure.
- Coating:Protective and functional layers providing chemical resistance, abrasion protection, or thermal management. Industrial maintenance applications across petrochemical facilities favor 100% solid polyurethane coatings for tank and pipeline rehabilitation.
- Sealing:Gap-filling and environmental barrier functions accommodating joint movement. European construction specifications under EN 15651 mandate elastic sealant performance across facade and interior applications.
- Potting:Complete encapsulation of electronic assemblies for moisture, thermal, and mechanical protection. EV battery module-to-pack assembly in China's Shanghai-Shenzhen corridor consumes thermally conductive, flame-retardant epoxy potting compounds with dielectric stability requirements.
Bonding holds the largest share; potting is climbing the fastest through electrification buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream isocyanate and epoxy resin production clusters in Germany, China, and the United States shape regional supply availability. Formulation asset location decisions follow automotive OEM technical centers and EV battery manufacturing corridors.
United States
EPA National Emission Standards for Hazardous Air Pollutants drive solvent-free system conversions at automotive assembly plants in Michigan and Tennessee. OSHA workplace exposure limits accelerate reactive hot melt investments. The Southeast manufacturing corridor hosts tier-one seating and electronics module suppliers requiring localized application engineering support.
Germany
KBA crashworthiness standards specify crash-resistant structural bonding for aluminum-intensive vehicle platforms. REACH substance restrictions and EU Green Deal chemical sustainability criteria reshape raw material qualification. Bavaria and Baden-Württemberg concentrate OEM design centers and adhesive formulation R&D.
China
MIIT domestic semiconductor initiatives and EV production scaling consume premium reactive adhesive grades. MEE environmental enforcement tightens VOC emissions at manufacturing facilities. The Shanghai-Shenzhen corridor dominates electronics assembly and battery pack production volumes.
Japan
METI fuel efficiency regulations accelerate lightweighting specifications in body-in-white assembly. JIS standards govern construction and industrial adhesive performance. The Nagoya and Tokyo metropolitan areas anchor automotive OEM technical centers demanding multi-continent supplier capability.
India
PLI scheme incentives for semiconductor and mobile device assembly create technical service localization requirements. BIS standards adoption accelerates as domestic electronics manufacturing scales. Gujarat and Tamil Nadu emerge as contract manufacturing clusters for global device brands.
Reactive Adhesives Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across specification-grade and commodity tiers. The market structure concentrates among integrated material science platforms with captive precursor supply and standalone formulation specialists dependent on merchant feedstock. Three archetypes dominate: diversified chemical conglomerates with upstream integration, adhesive-focused specialists with deep OEM relationships, and regional converters serving construction maintenance channels. Competitive moves center on qualification timeline acceleration and reactive hot melt capacity expansion for automated assembly lines.
Among integrated material science platforms, Dow and BASF exemplify upstream control over acrylic and polyurethane precursor chemistry. Henkel AG & Co. KGaA occupies a position within the specification-grade tier through automotive OEM technical partnerships. These three anchors represent divergent strategic positions: feedstock security versus formulation expertise versus customer integration depth.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Arkema Group |
| Dow |
| BASF |
| Illinois Tool Works |
| Wacker Chemie AG |
| Others |
Value Chain & Pricing Dynamics
Solvent-free formulation substitutions for legacy VOC-containing systems simultaneously relocate production asset investments toward REACH-compliant European facilities and compress margin structures for merchant-feedstock-dependent converters. This chemistry transition rewards integrated material science platforms with captive epoxy resin and isocyanate precursor supply while squeezing standalone formulation specialists exposed to petrochemical derivative volatility.
Pricing Analysis
REACH substance restrictions and EPA VOC regulations dictate the pricing tier structure across specification-grade and commodity reactive adhesive segments. Three-tier pricing separates aerospace-qualified grades with FAA outgassing certification from automotive OEM-approved tiers and undifferentiated industrial maintenance products. Price differentiation rests on qualification timeline investment and thermal performance certification, with automotive tier-one suppliers exhibiting highest price sensitivity due to buyer consolidation and electronics potting applications showing lowest sensitivity given dielectric stability requirements. Cost compression in commodity polyurethane segments is intensifying because of MDI and TDI feedstock volatility concentrated among Asian petrochemical complexes.
Supply Chain Analysis
Germany, China, and the United States anchor upstream epoxy resin and isocyanate production capacity serving global formulation networks. Raw material flows draw from bisphenol-A and novolac feedstocks for thermoset systems, polyol blends for polyurethane flexibility grades, and silane coupling agents for hybrid moisture-cure technologies. Single-source vulnerability concentrates in MDI and TDI supply among Asian petrochemical maintenance cycles, exposing European and North American converters to allocation risk. Distribution runs through direct technical service partnerships with automotive OEM design centers and construction specification channels, with automated dispensing equipment integration increasingly determining supplier selection at tier-one electronics module producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive adhesive market fragmentation creates opportunity across specialized qualification tiers, as EV battery bonding specifications and semiconductor reshoring incentives multiply addressable niches beyond incumbent-dominated automotive structural applications.
For Market Incumbents: Shield specification-grade revenue pools by accelerating reactive hot melt capacity expansion in Germany and Japan where automotive OEM technical partnerships concentrate. Deepen backward integration into acrylic and polyurethane precursor chemistry to defend margin position against merchant-feedstock-dependent challengers facing petrochemical derivative volatility. Prioritize FAA outgassing certification maintenance for aerospace adhesive portfolios where limited qualified supplier lists sustain pricing premiums.
For New Entrants and Emerging Players: Application engineering service gaps at Indian electronics manufacturing clusters under-served by incumbents with Asia-Pacific technical staff concentration in China offer white-space entry. Target semiconductor packaging and mobile device assembly specifications under India's PLI scheme where localized technical service requirements create qualification barriers for distant suppliers. Pursue joint development agreements with contract manufacturers in Gujarat and Tamil Nadu to establish reference installations before incumbents redirect regional resources.
For Investors and Strategic Acquirers: EU Green Deal chemical sustainability criteria reshapes the acquisition landscape toward formulation assets with bio-based hardener capabilities and low-isocyanate polyurethane development pipelines. Mid-cap specialists with captive epoxy resin supply and established automotive OEM qualification timelines present strongest long-term viability through the electrification buildout window. Monitor ECHA authorization list expansions as inflection signal for stranded asset risk in legacy solvent-containing formulation portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Hot Melt Capacity Expansion | Eliminates clamping time for German and Japanese automotive seating suppliers automating assembly lines. |
| Backward Integration into Isocyanate Precursors | Secures MDI and TDI supply stability for polyurethane adhesive producers facing Asian petrochemical allocation risk. |
| FAA Outgassing Certification Investment | Qualifies epoxy systems for satellite and crewed vehicle bonding where limited supplier pools command premium positioning. |
| Localized Technical Service in India | Supports PLI scheme semiconductor and mobile device assembly with application engineering presence in Gujarat and Tamil Nadu. |
| Bio-Based Hardener Development Partnership | Aligns formulation portfolios with EU Green Deal chemical sustainability criteria reshaping European raw material qualification. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and EPA regulatory dockets. Primary interviews engaged adhesive formulation R&D directors, automotive tier-one supplier procurement leads, plant managers at European and Asian production facilities, and distribution channel partners serving construction specification markets. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators ensures volume and value consistency across regional production clusters and end-use applications.
Segmentation dimensions modeled include product chemistry tier, formulation architecture, end-use industry concentration, and regional regulatory compliance pathway across the projection horizon. CAGRs derive from elasticity-adjusted demand projections incorporating EV production scaling, semiconductor reshoring incentive uptake, and construction activity indices. Industry-specific forecast inputs capture OEM qualification timeline distributions and reactive hot melt automation retrofit cycles at automotive seating and electronics module suppliers.
Forecasts assume regulatory continuity in REACH authorization procedures and EPA National Emission Standards for Hazardous Air Pollutants enforcement; material policy shifts would require re-modeling of solvent-free system adoption trajectories and formulation asset relocation patterns. Recalibration cycles align with material shifts in isocyanate feedstock allocation events, automotive OEM platform standardization decisions, and ECHA substance restriction list expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Anaerobic Adhesives Market