
 Global Medical Terminology Software Market | 2026-2036
Global Medical Terminology Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Terminology Software Market Foresight
Platform bundling is pivoting toward integrated terminology modules that embed directly within EHR workflows rather than standalone dictionaries. Wolters Kluwer leverages its clinical decision support ecosystem to cross-sell terminology services into existing hospital contracts. 3M anchors its position through deep integration with coding and reimbursement software used by health systems. Intelligent Medical Objects competes by maintaining one of the largest mapped clinical terminology libraries for semantic interoperability.
Medical terminology software comprises structured vocabularies, ontologies, and mapping engines that translate clinical concepts into standardized codes such as SNOMED CT, ICD-10, and LOINC for interoperable data exchange. These systems normalize free-text clinical documentation into machine-readable formats to support analytics, billing accuracy, and care coordination. Cloud-based deployments are capturing the fastest growth as health systems migrate away from capital-intensive on-premise infrastructure. Medical coding applications concentrate margin pools due to direct linkage to revenue cycle operations and compliance auditing. Hybrid architectures are gaining traction among mid-tier hospitals balancing latency-sensitive workflows with remote accessibility requirements.
FDA oversight of clinical trial data standards and ONC's interoperability certification criteria shape product roadmaps by mandating standardized terminology exchange. EMA's IDMP implementation and Japan's PMDA data submission requirements create parallel compliance obligations for multinational pharma companies deploying terminology platforms across jurisdictions. Stakeholders must monitor evolving national e-health strategies to anticipate where terminology standardization becomes a prerequisite for market participation or reimbursement eligibility.
Market Dynamics
Interoperability mandates from the FDA and ONC are compressing procurement cycles as hospitals accelerate enterprise terminology platform upgrades to meet certification deadlines.
Growth Catalysts
- FDA interoperability mandates:The FDA's clinical trial data standards require standardized terminology exchange, forcing pharmaceutical sponsors to deploy mapping engines for regulatory submissions.
- Cloud migration:Health systems are abandoning capital-intensive on-premise infrastructure for SaaS terminology platforms that reduce IT overhead and accelerate deployment timelines.
- Revenue cycle integration:Medical coding applications concentrate procurement attention because terminology accuracy directly impacts billing precision and audit compliance.
Market Restraints
- SNOMED CT licensing costs:The International Health Terminology Standards Development Organisation's membership fees and per-user licensing create persistent cost pressure for mid-tier hospitals.
- Implementation complexity:Legacy EHR architectures require extensive API customization to embed terminology modules, extending deployment timelines and professional services spend.
- Specialist talent scarcity:Health informaticists with cross-training in clinical workflows and ontology engineering command premium compensation, constraining vendor scaling.
Strategic Opportunities
- EMA IDMP compliance:The European Medicines Agency's Identification of Medicinal Products implementation creates parallel terminology obligations for multinational pharma deploying across EU member states.
- Japan PMDA data standards:Japan's Pharmaceuticals and Medical Devices Agency submission requirements open specialized localization contracts for terminology vendors with Japanese clinical concept libraries.
- Real-world evidence platforms:Convergence of terminology engines with AI-powered analytics is automating cohort identification for post-market surveillance and label expansion studies.
Industry Challenges
- Semantic drift maintenance:Clinical concept libraries require continuous curation as medical knowledge evolves, demanding dedicated editorial operations that scale with library breadth.
- Cross-vendor map reconciliation:Health systems operating multiple EHR instances struggle to harmonize terminology mappings across vendor-specific implementations, fragmenting data quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Terminology Software Market |
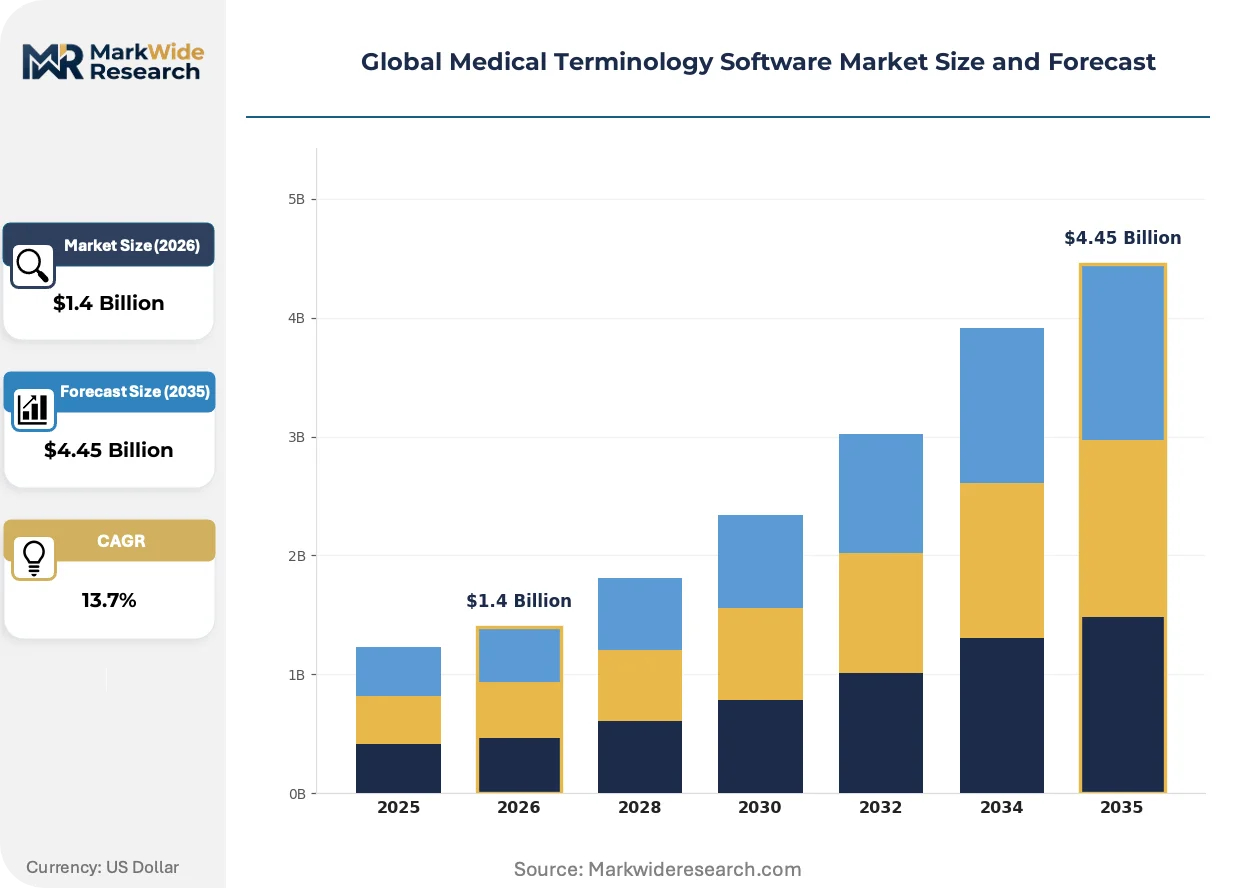
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Applications Application: Electronic Health Records, Clinical Documentation, Medical Coding, Research Analysis, Education End User: Hospitals, Diagnostic Centers, Research Institutions, Medical Universities, Pharma Companies Deployment: Enterprise, Small & Medium Businesses, Government Agencies, Non-Profit Organizations |
| Companies Covered | Wolters Kluwer, 3M, Intelligent Medical Objects, Apelon, Clinical Architecture, CareCom, BT Clinical Computing, BiTAC, B2i Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Terminology Software Market Shifts & Advancements
Natural language processing engines are embedding directly into clinical documentation workflows, compressing the latency between physician narrative entry and coded data availability.
Large language models fine-tuned on clinical corpora are automating the extraction of structured codes from unstructured physician notes. Academic medical centers in the United States are piloting these systems for emergency department documentation. This compression of coding labor is reallocating health information management staff toward exception handling and quality assurance.
EMA's IDMP implementation timeline is forcing pharmaceutical manufacturers to restructure product master data with standardized substance, product, and organization identifiers. Companies with existing terminology investments are extending those platforms to cover IDMP compliance, while laggards face parallel system builds. The compliance burden falls heaviest on generics manufacturers with limited data governance infrastructure.
Subscription pricing for terminology platforms is displacing perpetual license models as health systems prioritize operational expenditure predictability. Procurement teams are bundling terminology modules with broader clinical decision support contracts, eroding standalone dictionary margins. This shift is most pronounced among integrated delivery networks consolidating vendor relationships across multiple facilities.
Global Medical Terminology Software Market Segmentation
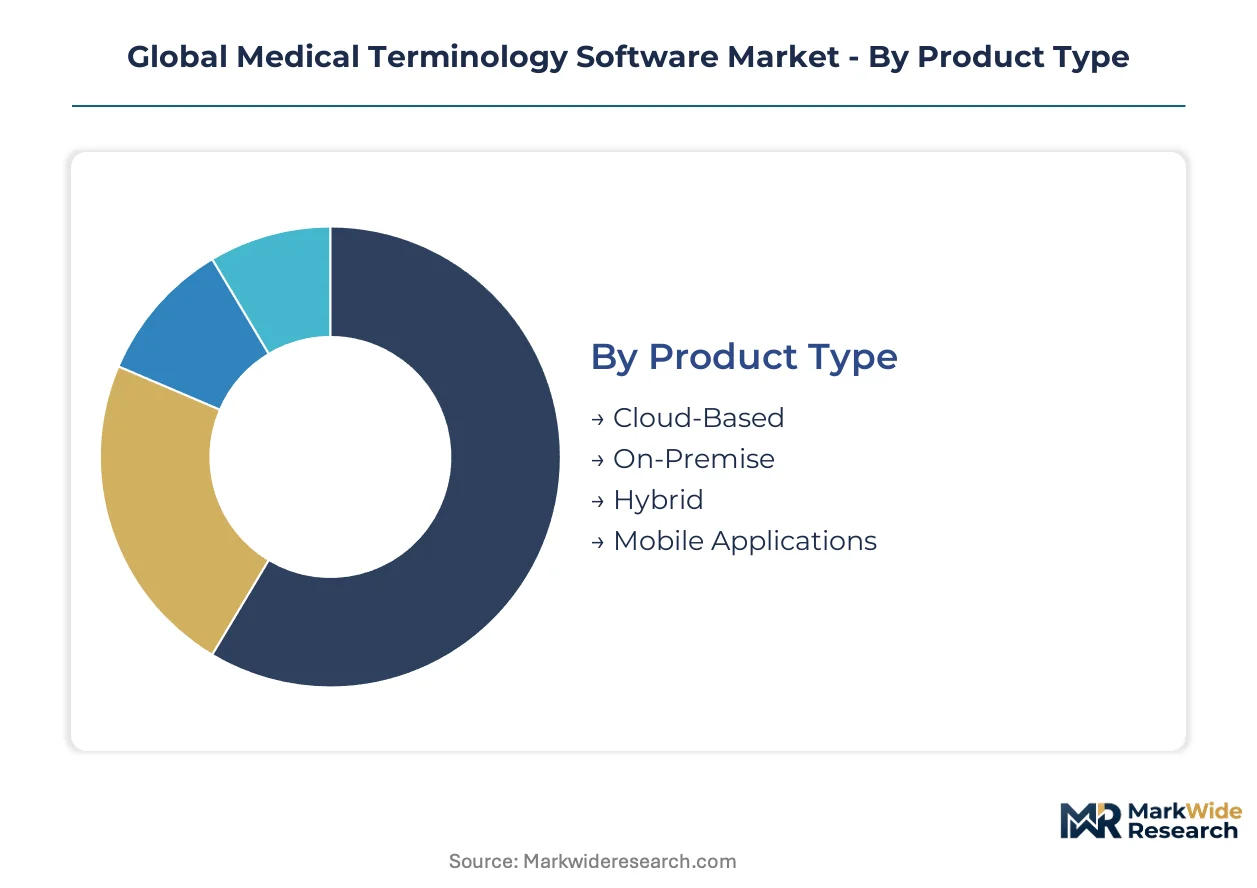
Medical terminology software vendors configure product architectures around distinct operational constraints. Deployment models, clinical workflows, and organizational scale each demand specialized interface designs, security protocols, and integration patterns.
Product Type:
Customization requirements diminish as infrastructure control shifts from client data centers to vendor-managed environments.
- Cloud-Based:Multi-tenant SaaS architectures deliver terminology services through browser-based interfaces with automatic version updates. United States health systems migrating from capital expenditure models are consolidating procurement around these platforms to eliminate server maintenance overhead.
- On-Premise:Licensed software installed within client firewall boundaries maintains data sovereignty for institutions with restrictive security policies. German university hospitals and Japanese academic medical centers continue specifying these deployments for genomic research data.
- Hybrid:Split architectures process latency-sensitive coding workflows locally while synchronizing terminology libraries to cloud repositories. Mid-tier United States hospitals balancing legacy EHR constraints with remote access requirements are driving adoption.
- Mobile Applications:Smartphone-optimized interfaces for bedside documentation and point-of-care code lookup. Physician practices in India and Brazil deploy these for rural outreach programs with intermittent connectivity.
Most installed capacity flows through Cloud-Based platforms. Expansion is steepest in Hybrid configurations as transition-bound health systems seek intermediate architectures.
Application:
Revenue concentration tracks proximity to billing operations and regulatory submission requirements.
- Medical Coding:Terminology engines mapping clinical documentation to ICD-10, CPT, and HCPCS codes for reimbursement claims. United States hospital revenue cycle departments prioritize these modules for audit defense and denial reduction.
- Electronic Health Records:Embedded terminology services normalizing structured data entry across clinical modules. Epic and Cerner implementations in academic medical centers consume substantial mapping engine licenses.
- Clinical Documentation:Natural language processing pipelines extracting coded concepts from physician narrative. Emergency departments in Australia and Canada pilot these for real-time quality reporting.
- Research Analysis:Cohort identification and phenotyping tools for clinical trial recruitment and observational studies. Pharmaceutical sponsors in Switzerland and the United Kingdom deploy these for real-world evidence generation.
- Education:Training platforms for health informatics students and clinical terminology certification programs. Medical universities in South Korea and Saudi Arabia license these for curriculum integration.
Coding applications dominate current procurement volumes. Documentation automation is climbing fastest as NLP accuracy crosses clinical adoption thresholds.
End User:
Procurement sophistication varies with organizational data governance maturity and regulatory exposure.
- Hospitals:Integrated delivery networks operating multiple facilities standardize terminology across EHR instances to enable enterprise analytics. United States health systems with Medicare accountable care contracts lead enterprise platform deployments.
- Pharma Companies:Multinational manufacturers require harmonized substance and product identifiers for regulatory submissions across FDA, EMA, and PMDA jurisdictions. These organizations invest heavily in IDMP-compliant terminology infrastructure.
- Research Institutions:Academic medical centers and government laboratories conducting multi-site studies need semantic interoperability for federated querying. The United Kingdom's NHS Digital and France's INSERM coordinate terminology standards for cross-border research.
- Diagnostic Centers:Imaging and laboratory networks integrating results into EHR workflows through standardized code mapping. Independent pathology groups in Germany and the Netherlands license terminology modules for lab information system connectivity.
- Medical Universities:Educational institutions training health information management professionals on standardized classification systems. Curriculum requirements in India and China drive institutional subscriptions to terminology databases.
Hospital procurement represents the largest addressable base. Pharmaceutical investment is expanding most quickly under regulatory deadline pressure.
Deployment:
Contract structures and pricing models align with budget predictability requirements and compliance oversight intensity.
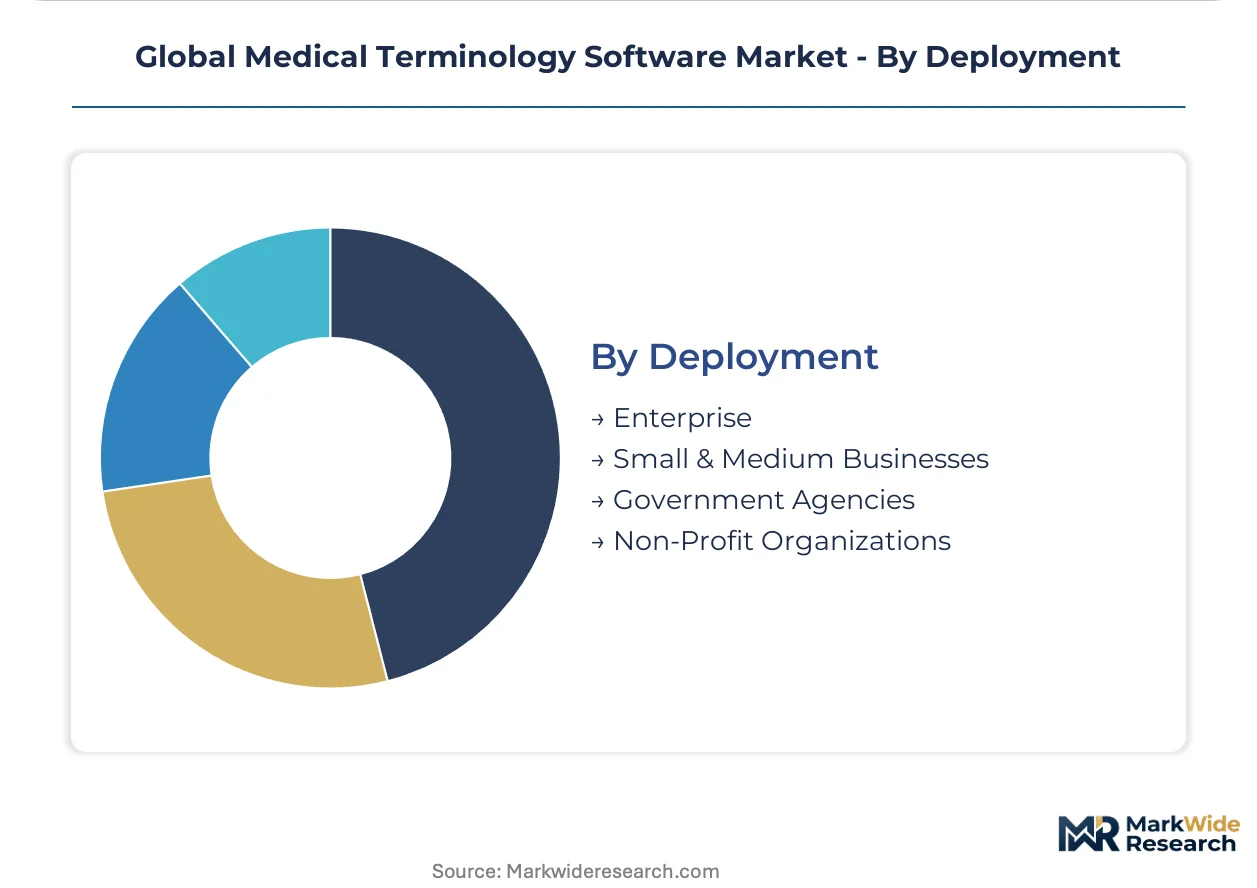
- Enterprise:Multi-year agreements covering thousands of users across integrated health systems with dedicated implementation support. United States-based IDNs negotiate these for standardization across acquired facilities.
- Government Agencies:National e-health programs and military health systems procuring terminology infrastructure for population-scale deployment. Canada's Infoway and Australia's Digital Health Agency operate at this tier.
- Small & Medium Businesses:Subscription packages sized for independent physician practices and regional clinics with limited IT staff. Community health centers in Spain and Italy select these for Meaningful Use compliance.
- Non-Profit Organizations:Discounted licensing for humanitarian health information initiatives and global health research consortia. WHO-affiliated programs in sub-Saharan Africa access terminology resources through these channels.
Enterprise deployments absorb the majority of vendor professional services capacity. Government agency contracts are scaling fastest under national digital health mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered large-scale medical terminology standardization through federal EHR incentive programs, establishing the regulatory template that Germany, Japan, and Australia later adapted for their national digital health infrastructures.
United States
Hospital revenue cycle departments and accountable care organizations drive enterprise terminology platform procurement to unify documentation across acquired facilities. ONC certification requirements and FDA clinical trial data standards compress implementation timelines for vendors serving pharmaceutical sponsors. The Boston-Cambridge corridor hosts concentrated health informatics R&D activity alongside major EHR vendor headquarters.
Germany
University hospitals and genomic research institutes specify on-premise deployments to maintain data sovereignty over sensitive patient information. The national electronic health card initiative and forthcoming hospital digitalization mandates accelerate terminology standardization across Länder health systems. Berlin and Munich anchor competing clusters of health IT vendors and academic medical centers piloting semantic interoperability protocols.
Japan
Academic medical centers and pharmaceutical manufacturers invest in localized terminology libraries to meet PMDA data submission requirements for new drug applications. The Ministry of Health, Labour and Welfare's promotion of standardized medical information exchange creates procurement pressure on regional hospital networks. Osaka and Tokyo metropolitan areas concentrate health IT vendor development facilities alongside major pharmaceutical company headquarters.
Australia
Digital Health Agency national programs and state-based hospital networks deploy terminology infrastructure for population-scale analytics and care coordination. The Therapeutic Goods Administration's alignment with international data standards influences vendor product roadmaps for regulatory submission tools. Melbourne and Sydney host the primary health informatics research institutions driving clinical NLP pilot programs.
Switzerland
Pharmaceutical headquarters and contract research organizations require harmonized terminology platforms for multinational regulatory submissions across FDA, EMA, and PMDA jurisdictions. Swissmedic's implementation of IDMP-aligned standards shapes vendor investment in substance and product identifier mapping engines. Basel and Zurich concentrate pharmaceutical data governance operations alongside specialized health IT consultancies.
Global Medical Terminology Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth, with those embedding terminology engines directly within EHR workflows commanding superior pricing power. The vendor base organizes into three tiers: diversified information services conglomerates, specialized health IT pure-plays, and regional compliance-focused boutiques. Strategic moves concentrate on API-first architecture investments and professional services capacity expansion to compress client implementation timelines.
Within the diversified information services tier, Wolters Kluwer and 3M occupy positions anchored by cross-selling leverage into existing hospital contracts and coding software relationships respectively. Intelligent Medical Objects exemplifies the specialized pure-play archetype through its focus on maintaining expansive mapped terminology libraries for semantic interoperability use cases.
| Leading Market Players |
|---|
| Wolters Kluwer |
| 3M |
| Intelligent Medical Objects |
| Apelon |
| Clinical Architecture |
| CareCom |
| BT Clinical Computing |
| BiTAC |
| B2i Healthcare |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ONC-certified enterprise platforms and uncertified modular tools creates bifurcated pricing power that tracks directly to supply chain complexity. Premium vendors command annual subscription premiums by embedding terminology engines within FDA-validated clinical decision support workflows, while commodity providers compete on per-seat licensing for standalone dictionary access.
Pricing Analysis
Subscription-based SaaS tiers dominate procurement contracts, with pricing stratifying across premium, standard, and economy levels based on SNOMED CT licensing scope and API call volume entitlements. Price differentiation hinges on ONC certification status and embedded NLP processing capabilities. Cost compression in the mid-market intensifies as Epic and Cerner bundle terminology modules into base EHR contracts, eroding standalone vendor margins. Independent physician practices exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over per-seat rates.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor cloud infrastructure deployment for terminology platform delivery. Software development draws from specialized health informatics talent pools concentrated in Boston-Cambridge, Berlin, and Tokyo metropolitan clusters. Supply chain risk centers on single-source vulnerability for SNOMED CT editorial content licensed exclusively through the International Health Terminology Standards Development Organisation. Distribution runs through direct enterprise sales teams for hospital systems and specialized pharma-facing consultancies for regulatory compliance deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cloud-native architectures that eliminate on-premise infrastructure overhead while capturing premium pricing for real-time NLP capabilities. The shift from perpetual licenses to predictable subscription revenue streams reinforces vendor valuation multiples.
For Market Incumbents: Hedge against EHR vendor bundling by deepening API-first architecture investments that enable interoperability across heterogeneous hospital IT environments. Acquire specialized NLP engineering teams to compress coding automation latency below competitor thresholds. Prioritize ONC certification maintenance as defensive moat against modular entrants. For New Entrants and Emerging Players: Enter via IDMP compliance services for mid-tier European generics manufacturers lacking in-house data governance infrastructure. Target Japanese pharmaceutical sponsors requiring PMDA-aligned terminology localization as most penetrable regulatory vertical. Pursue channel partnerships with specialized health IT consultancies rather than direct enterprise sales builds. For Investors and Strategic Acquirers: Consolidation pressure builds where semantic interoperability capabilities become table stakes for hospital system procurement. Long-term viability favors vendors with captive terminology library editorial operations rather than licensed content aggregators. Acquisition target archetype: specialized health informatics firms with FDA submission experience and existing pharma sponsor relationships. Signal to monitor: EMA IDMP enforcement actions creating compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding terminology engines within Epic and Cerner workflows captures procurement decision authority from hospital IT committees. |
| Acquisition of Specialist Firm | Buying clinical NLP startups accelerates real-time documentation automation capabilities beyond organic R&D timelines. |
| Regulatory Approval Pathway | ONC certification investment opens federal EHR incentive program eligibility for vendor solutions. |
| Strategic Partnership | Alliances with GPOs channel terminology modules into hospital purchasing contracts at enterprise scale. |
| Geographic Expansion | Japanese and EU commercial offices localize IDMP and PMDA compliance offerings for pharma sponsor procurement. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined through structured interviews with health informatics officers, hospital procurement directors, pharmaceutical regulatory affairs leads, and terminology platform product managers. Secondary validation drew from FDA 510(k) filings, ONC certification databases, EMA IDMP implementation guidance, hospital GPO contract disclosures, and vendor SEC financial statements. Bottom-up deployment counts triangulated against top-down health IT spending estimates.
Rate-of-change decomposition segmented growth across cloud versus on-premise deployment models, hospital versus pharmaceutical end-user categories, and medical coding versus clinical documentation application types. CAGRs were derived from fitted adoption curves weighted by regulatory deadline proximity. Forecast inputs incorporated EHR vendor bundling trajectory, SNOMED CT licensing fee schedules, and NLP accuracy improvement curves from academic medical center pilot programs across the analysis window.
Inputs from hospital procurement databases and pharmaceutical sponsor regulatory filings were available through the study window; gaps in private mid-tier hospital IT spending introduce uncertainty bands in the on-premise to cloud transition timing. Forecasts reflect documented assumptions regarding interoperability mandate enforcement intensity and EHR vendor competitive dynamics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
AI Medical Service Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
US Healthcare ERP Market