
 Europe Dog Dewormers Market | 2026-2036
Europe Dog Dewormers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dog Dewormers Market Intelligence
Subscription-based preventive care plans is shifting how dog dewormers reach end users across Europe, bundling recurring treatments with wellness monitoring. Zoetis leverages its direct-to-veterinary channel infrastructure to anchor recurring revenue streams in core EU markets. Boehringer Ingelheim competes through specialized parasiticide R&D pipelines targeting emerging resistance profiles. Dechra Pharmaceuticals differentiates via narrow therapeutic focus on companion animal anthelmintics.
Dog dewormers comprise pharmaceutical formulations—typically containing benzimidazoles, macrocyclic lactones, or praziquantel complexes—administered orally or parenterally to eliminate nematode, cestode, and trematode infections in canines, with tablet and chewable presentations dominating outpatient dispensing due to owner compliance advantages. The application landscape shows veterinary clinics capturing the highest-margin transactions through prescription authority, while online retailers represent the fastest-expanding channel as tele-veterinary consultations normalize post-pandemic. Distribution through veterinary distributors sustains bulk procurement efficiencies for multi-practice operators, though e-commerce penetration is fragmenting traditional wholesaler concentration.
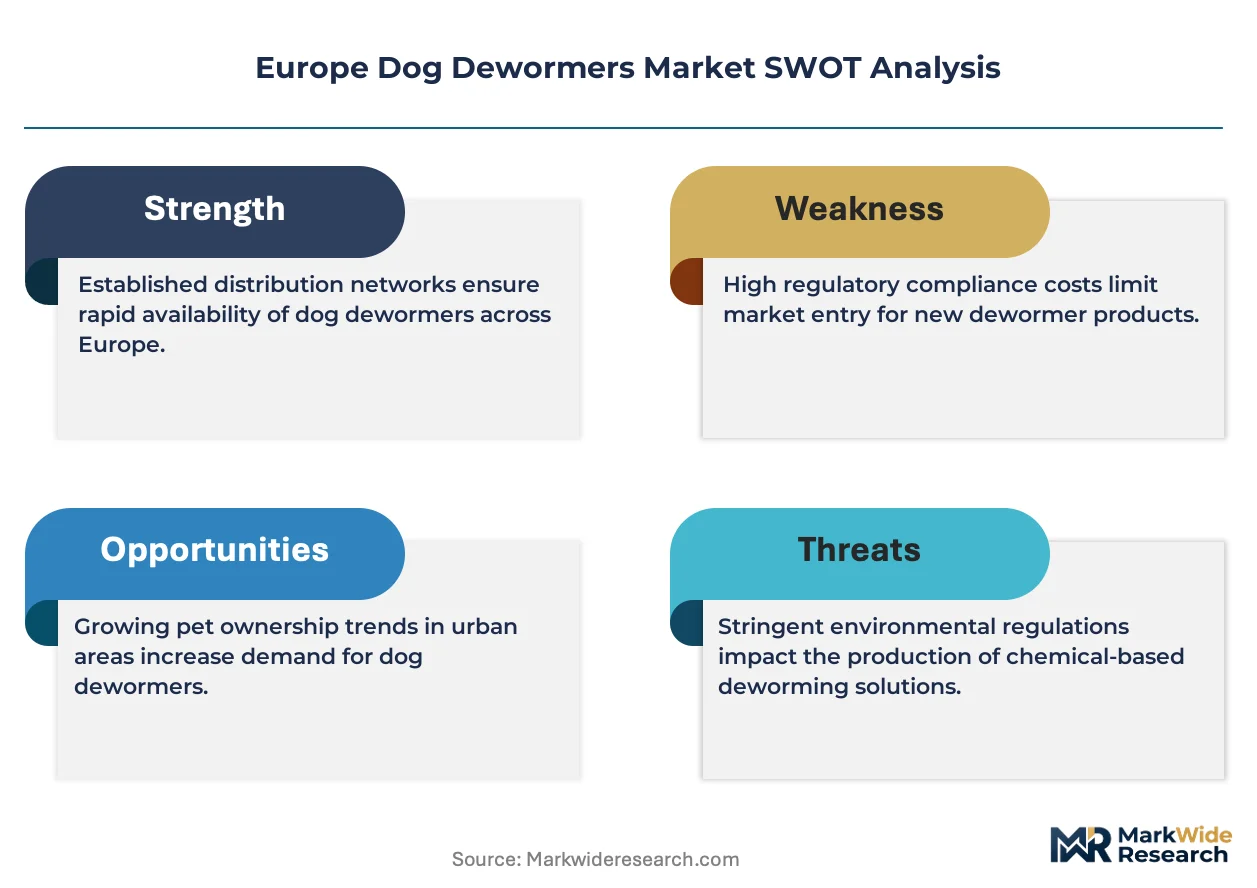
EMA's veterinary pharmacovigilance framework and REACH chemical safety standards constrain active ingredient sourcing and formulation stability requirements across EU member states. National regulators in Germany, France, and Italy enforce MDR-aligned traceability mandates that elevate compliance costs for imported generics. Stakeholders must monitor evolving resistance surveillance data from European parasitology networks to align R&D portfolios with shifting therapeutic protocols.
Market Dynamics
EMA's tightened residue monitoring standards are compressing formulation approval timelines and elevating compliance costs across European veterinary pharmaceutical supply chains, forcing manufacturers toward prescription-grade production systems.
Growth Catalysts
- REACH chemical safety standards:These ECHA mandates elevate barrier-to-entry for imported generics, protecting domestic formulation margins and incentivizing localized manufacturing investment.
- Pet insurance penetration:Western European markets with mature reimbursement infrastructure normalize routine preventive deworming, converting episodic purchases into recurring revenue streams.
- Tele-veterinary consultations:Post-pandemic normalization of remote diagnostics expands prescription authority beyond physical clinic walls, accelerating online channel growth.
Market Restraints
- Active ingredient sourcing concentration:Benzimidazole and macrocyclic lactone precursors concentrate among Asian chemical manufacturers, exposing European formulators to supply disruption and currency volatility.
- MDR-aligned traceability mandates:German, French, and Italian national regulators impose serialization and batch-tracking requirements that inflate packaging and IT infrastructure costs for multi-market operators.
- Anthelmintic resistance surveillance:European parasitology networks document emerging nematode resistance profiles, compressing product lifecycles and forcing accelerated R&D reinvestment.
Strategic Opportunities
- Central and Eastern European underpenetration:Poland, Romania, and Czech Republic markets exhibit lower veterinary expenditure per capita but rising companion animal ownership, creating whitespace for preventive care plan rollout.
- Subscription-based preventive care plans:Bundled wellness monitoring with recurring deworming treatments locks in customer lifetime value and reduces price sensitivity.
- EU Green Deal chemistry incentives:Sustainable manufacturing certifications and reduced-carbon formulation processes attract ESG-mandated institutional procurement from veterinary group purchasing organizations.
Industry Challenges
- Veterinary parasitology expertise scarcity:Diagnostic interpretation and resistance monitoring require specialized training that outpaces European veterinary school output, constraining clinic-level protocol implementation.
- Legacy ERP integration with traceability systems:MDR-compliant serialization demands real-time data exchange that fragments across incompatible practice management software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dog Dewormers Market |
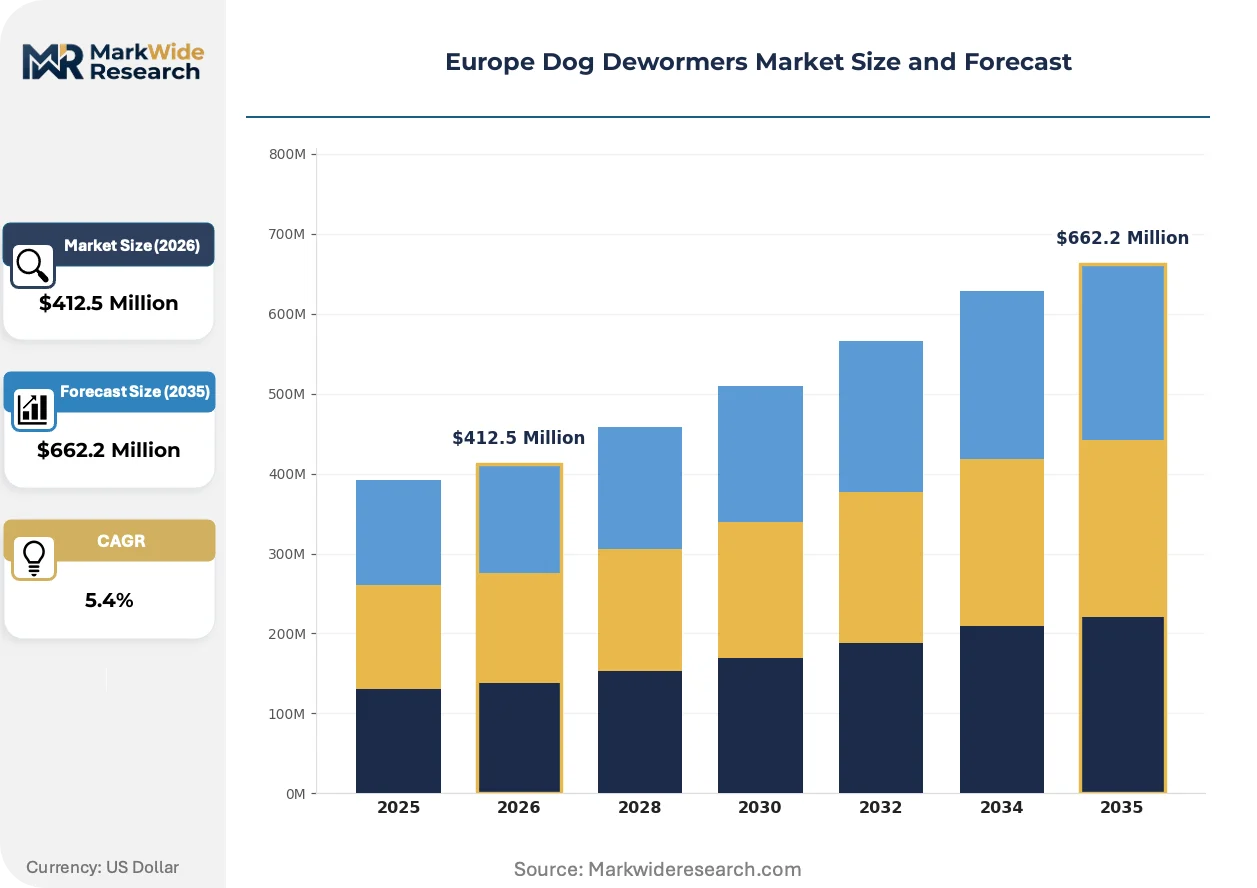
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Liquid, Chewable, Injectable Application: Veterinary Clinics, Pet Shops, Online Retailers, Animal Hospitals Distribution Channel: Direct Sales, Wholesalers, E-Commerce, Veterinary Distributors Customer Type: Pet Owners, Breeders, Shelters, Kennels |
| Companies Covered | Zoetis, Boehringer Ingelheim, Merck & Co., Dechra Pharmaceuticals, Elanco Animal Health, Ceva Sante Animale, Virbac, Vetoquinol, Bioveta, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dog Dewormers Market Strategic Shifts & Innovations
Digitalization of veterinary workflows and chemistry platform advances are compressing product development cycles while reshaping how deworming protocols reach end users across European markets.
Combination chewable formulations integrating benzimidazoles with macrocyclic lactones are automating compliance monitoring through palatability-engineered dosing that reduces owner administration failure rates. German and UK veterinary clinics deploy these platforms to minimize retreatment visits and improve protocol adherence. The technology is automating outcome tracking by embedding treatment timestamps into practice management databases for resistance surveillance.
EMA's veterinary pharmacovigilance framework now mandates real-time adverse event reporting across all member states, compressing post-market surveillance timelines from quarterly to continuous. Formulation stability requirements under REACH constrain excipient sourcing to EU-approved chemical suppliers. Small and mid-sized generic manufacturers in Italy and Spain face disproportionate compliance cost burdens, accelerating consolidation toward scaled quality management systems.
Pet owner purchasing behavior is fragmenting across channel types as tele-veterinary platforms normalize prescription fulfillment through direct-to-consumer shipping. Traditional veterinary distributors in France and Belgium lose volume to specialized e-commerce operators offering subscription scheduling and automated refill triggers. This pattern concentrates most visibly in urban UK markets where digital-native millennial pet owners dominate demographic composition.
Europe Dog Dewormers Market Segmentation
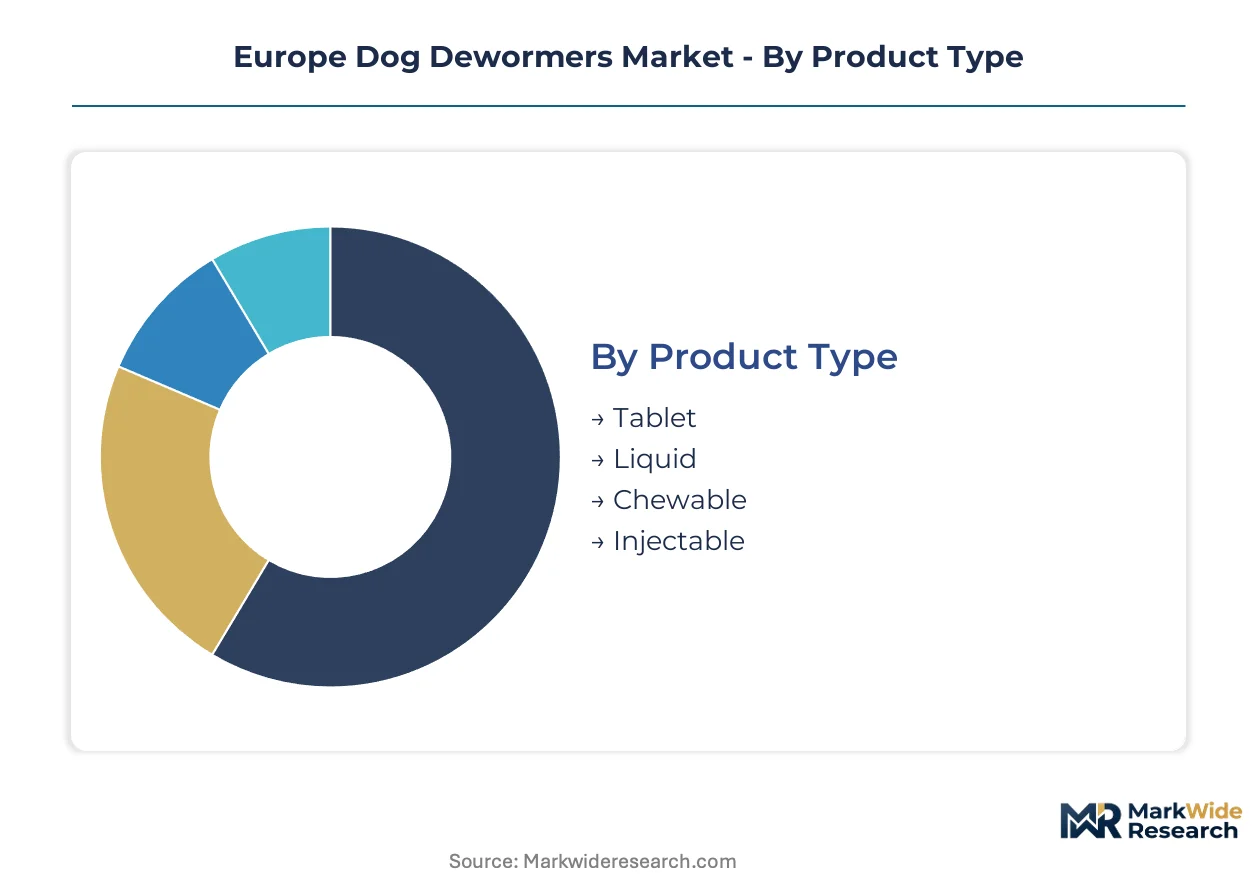
Product form, purchase setting, and buyer sophistication create distinct commercial segments across European dog dewormers. Each dimension shapes pricing power, channel strategy, and regulatory compliance requirements differently.
Product Type:
Palatability and administration convenience separate casual pet owners from professional breeders and institutional buyers.
- Tablet:Compressed benzimidazole and praziquantel formulations deliver precise dosing with extended shelf stability. German veterinary clinics prescribe tablets for multi-dog households where cost-per-treatment matters, though owner compliance lags chewable alternatives.
- Chewable:Palatability-engineered macrocyclic lactone complexes mask active ingredients in meat-flavored matrices that reduce administration failure. UK pet insurance reimbursement protocols increasingly favor chewable prescriptions for improved protocol adherence metrics.
- Liquid:Suspension formulations enable weight-adjusted dosing for puppies and small breeds where tablet fractioning introduces error. French breeders favor liquid presentations for litters requiring synchronized treatment schedules.
- Injectable:Parenteral macrocyclic lactone depots provide sustained-release protection in kennel and shelter environments where oral administration is impractical.
Tablets lead volumes today; chewables are gaining share fastest.
Application:
Prescription authority and reimbursement infrastructure determine margin capture across treatment settings.
- Veterinary Clinics:Physical practice environments anchor prescription-grade revenue through diagnostic confirmation and protocol customization. EMA pharmacovigilance mandates concentrate adverse event reporting through this channel, elevating compliance costs but protecting margin structures.
- Animal Hospitals:Emergency and referral centers handle complex parasitic co-infections requiring combination therapies unavailable through retail channels. Italian university hospitals generate resistance surveillance data that shapes national treatment guidelines.
- Pet Shops:Over-the-counter benzimidazole generics serve price-sensitive owners in markets with limited veterinary access, particularly rural Spain and Portugal.
- Online Retailers:Tele-veterinary prescription fulfillment fragments traditional channel concentration, with UK and Dutch platforms capturing urban millennial demand through subscription scheduling.
Veterinary clinics capture the highest margins; online retailers show the steepest expansion trajectory.
Distribution Channel:
Batch traceability requirements and order scale differentiate procurement pathways.
- Veterinary Distributors:Specialized wholesalers maintain cold-chain integrity for temperature-sensitive formulations while managing MDR-aligned serialization for multi-practice operators. Belgian and Dutch distributors consolidate procurement for Benelux clinic networks.
- E-Commerce:Direct-to-consumer platforms leverage automated refill triggers and wellness bundling to reduce price sensitivity. German pet owners increasingly purchase through specialized veterinary e-commerce operators rather than generalist marketplaces.
- Direct Sales:Manufacturer-to-clinic relationships sustain bulk pricing for large veterinary groups and corporate chains.
- Wholesalers:General pharmaceutical distributors serve fragmented rural practices where specialized veterinary inventory is uneconomical.
Veterinary distributors handle the largest transaction volumes; e-commerce is climbing the fastest.
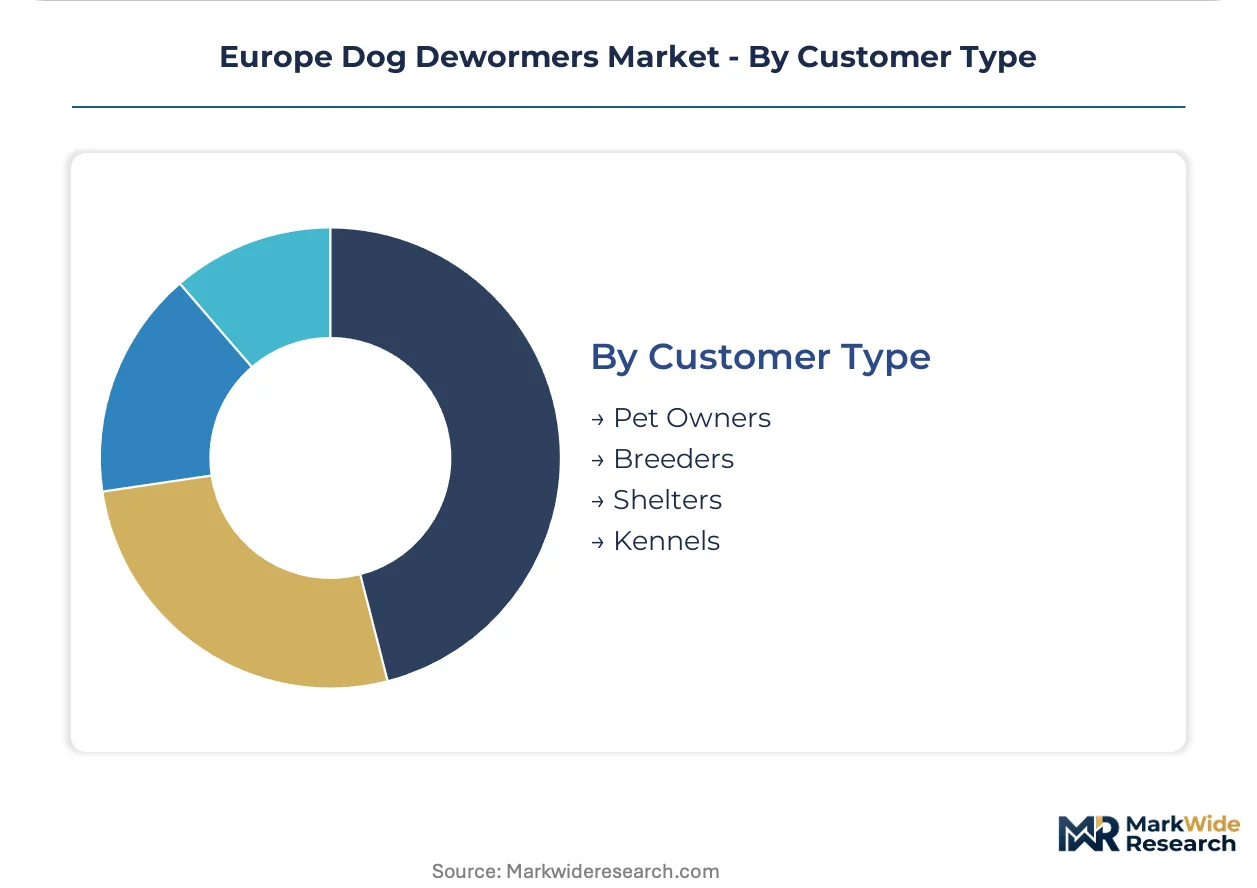
Customer Type:
Buying sophistication and treatment protocol rigor shape product selection and channel preference.
- Pet Owners:Individual companion animal households prioritize administration convenience and palatability over unit cost, driving chewable premiumization in UK and Scandinavian markets.
- Breeders:Commercial kennel operations demand bulk formulations with batch documentation for pedigree registration requirements. French and German breeding associations negotiate direct procurement contracts.
- Shelters:Non-profit animal welfare organizations balance treatment efficacy against constrained budgets, favoring generic tablet presentations with donated or subsidized supply.
- Kennels:Boarding and training facilities require prophylactic protocols that minimize disease transmission liability, often selecting sustained-release injectables for operational efficiency.
Pet owners generate the largest revenue pool; breeders show the most concentrated per-capita expenditure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's veterinary expenditure per capita exceeds Poland's by a factor of four, yet both markets exhibit accelerating companion animal ownership trajectories that reshape dewormer procurement patterns.
Germany
Pet insurance penetration reaches maturity levels that normalize quarterly preventive deworming across multi-dog households. The Federal Office for Consumer Protection and Food Safety enforces stringent batch documentation requirements that elevate compliance costs for imported formulations. Munich and Stuttgart veterinary clinic networks anchor prescription-grade revenue through corporate consolidation and standardized treatment protocols.
United Kingdom
Tele-veterinary platforms capture urban millennial demand through subscription-based wellness bundling that converts episodic purchases into recurring revenue streams. The Veterinary Medicines Directorate aligns pharmacovigilance reporting with EMA continuous surveillance mandates. London and Manchester metropolitan areas concentrate online retailer fulfillment infrastructure specialized in direct-to-consumer veterinary pharmaceutical distribution.
France
Commercial breeding associations in Normandy and Brittany negotiate direct procurement contracts for bulk tablet formulations with pedigree documentation requirements. ANSM maintains national residue monitoring protocols that exceed baseline EMA standards for macrocyclic lactone formulations. Lyon veterinary university hospitals generate resistance surveillance data that shapes national nematode treatment guidelines.
Italy
Regional disparities in veterinary access fragment demand between northern clinic networks and southern pet shop over-the-counter channels. The Italian Medicines Agency imposes MDR-aligned serialization requirements that accelerate consolidation among mid-sized generic manufacturers. Bologna's university veterinary faculty anchors parasitology research clusters documenting emerging anthelmintic resistance profiles.
Poland
Rising companion animal ownership in Warsaw and Kraków metropolitan areas creates whitespace for preventive care plan rollout among digitally native pet owners. The Chief Veterinary Officer coordinates with EMA frameworks while maintaining national import licensing for temperature-sensitive formulations. Poznań veterinary distributors consolidate procurement for emerging multi-practice operators expanding across Central European markets.
Europe Dog Dewormers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with prescription-grade formulations concentrating around veterinary-anchored players while generic tablet production fragments among regional formulators. The vendor base organizes into three tiers: multinational pharmaceutical conglomerates with direct-to-veterinary infrastructure, mid-cap specialists focused on narrow therapeutic categories, and regional generic manufacturers serving price-sensitive over-the-counter channels. Consolidation pressures intensify as MDR compliance costs and EMA pharmacovigilance mandates favor scaled quality management systems over fragmented operations.
Among the multinational tier, Zoetis and Boehringer Ingelheim occupy positions exemplifying divergent strategic archetypes—one leveraging channel infrastructure for recurring revenue capture, the other emphasizing specialized parasiticide research pipelines. Dechra Pharmaceuticals represents the mid-cap specialist model with concentrated focus on companion animal anthelmintics. These three entities anchor competitive dynamics across Western European markets where prescription authority and reimbursement infrastructure determine margin capture.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Merck & Co. |
| Dechra Pharmaceuticals |
| Elanco Animal Health |
| Ceva Sante Animale |
| Virbac |
| Vetoquinol |
| Bioveta |
| Others |
Cost & Logistics Intelligence
Prescription-grade certification divergence between EMA-compliant formulations and over-the-counter generics manifests in parallel supply chain configurations—branded manufacturers anchor production in EU GMP-certified facilities while commodity tablet suppliers route through lower-cost Asian chemical intermediaries.
Pricing Analysis
Capacity additions in Central and Eastern European manufacturing are reshaping price floors for generic benzimidazole tablets. Three-tier pricing structure across premium, standard, and economy levels separates chewable macrocyclic lactone complexes from praziquantel tablets from unbranded liquid suspensions. Pricing pressure stems from REACH compliance costs elevating excipient sourcing expenses. Breeders and kennel operators show highest price sensitivity; insured pet owners in Germany and UK exhibit lowest.
Supply Chain Analysis
EMA veterinary GMP certification gates upstream active ingredient procurement, forcing European formulators toward audited Indian and Chinese API manufacturers with documented pharmacovigilance systems. Benzimidazole precursors, macrocyclic lactone fermentation stocks, and praziquantel chemical intermediates constitute critical input dependencies. Single-source vulnerability concentrates in pyrantel pamoate supply from select Asian chemical parks. Distribution runs through veterinary distributors maintaining cold-chain integrity for temperature-sensitive formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pet insurance normalization shifts demand toward prescription-grade chewables with documented efficacy profiles and adverse event traceability.
For Market Incumbents: Deploy subscription-based preventive care platforms to lock recurring revenue against generic tablet erosion. Consolidate manufacturing footprints in EU GMP-certified facilities to absorb REACH compliance costs at scale. Channel control through direct-to-veterinary relationships protects margin structures from tele-veterinary platform disintermediation. For New Entrants and Emerging Players: Capture whitespace in Polish and Romanian metropolitan markets where companion animal ownership accelerates ahead of veterinary infrastructure maturity. Target digitally native millennial pet owners through specialized e-commerce operators offering automated refill triggers. Position via tele-veterinary partnerships that bypass traditional distributor concentration. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR serialization mandates and EMA pharmacovigilance costs disproportionately burden mid-sized Italian and Spanish generic manufacturers. Acquisition candidates with scaled quality management systems and veterinary clinic network relationships offer durable positioning. Watch resistance surveillance data from European parasitology networks as inflection indicator for product lifecycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GMP Certification Investment | Unlocks prescription-grade revenue pools in German and UK clinic networks. |
| Tele-Veterinary Platform Partnership | Captures urban millennial demand through direct-to-consumer fulfillment infrastructure. |
| Subscription-Based Preventive Care Launch | Converts episodic purchases into recurring revenue with reduced price sensitivity. |
| Central European Manufacturing Expansion | Reduces logistics costs for Polish and Romanian market penetration. |
| Resistance Surveillance Data Integration | Aligns R&D pipelines with evolving nematode treatment protocols from Lyon and Bologna. |
Research Approach
Bottom-up veterinary clinic and pet owner modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core of this study. Primary interviews with veterinary procurement officers, clinic network managers, pharmaceutical regulatory affairs leads, and pet insurance reimbursement specialists combined with secondary validation from EMA pharmacovigilance databases, national veterinary medicine agency filings, and European pet ownership surveys. Trade flow analysis of benzimidazole and macrocyclic lactone API shipments anchored supply-side calibration.
Input-output matrices map product form, application setting, and distribution channel dimensions across the projection horizon. Segmentation modeling incorporates formulation type, purchase setting, buyer sophistication tier, and regional regulatory cluster. CAGRs derive from weighted average of historical trajectory and forward-looking protocol adoption curves. Forecast inputs include pet insurance penetration rates and tele-veterinary consultation normalization patterns.
Anthelmintic resistance emergence, EMA regulatory tightening, and API supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about treatment protocol standardization and reimbursement infrastructure expansion. A model refresh is warranted upon material change in European parasitology network resistance surveillance findings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
OTC Cat Medicines Market
Veterinary
Animal Antibiotics Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Supplements Market
Veterinary
Global Animal Vaccine Market
Veterinary
Bovine Mastitis Market
Veterinary
India Veterinary Healthcare Market
Veterinary
Spay and Neuter Market
Veterinary
Veterinary Software Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Global Canine Atopic Dermatitis Market