
 South Africa Veterinary Medicine Market | 2026-2036
South Africa Veterinary Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Veterinary Medicine Market Intelligence
Recombinant DNA vaccines are displacing conventional attenuated formulations and is realigning unit economics across the South Africa Veterinary Medicine Market. Zoetis leverages its transgenic platform development to sustain premium positioning in ruminant biologicals. Biovac anchors domestic manufacturing capacity through its Onderstepoort-based facility, while Afrivet competes aggressively on channel reach into emerging farmer cooperatives.
South Africa veterinary medicine comprises biologically active preparations—vaccines containing attenuated or inactivated pathogens, antimicrobial formulations with specified withdrawal periods, and parasiticidal agents dosed by body weight—developed for disease prevention, treatment, and productivity maintenance in food-producing and companion animals. Vaccines command the largest revenue share among product types due to mandatory brucellosis and lumpy skin disease programs, while parasiticides exhibit the fastest growth trajectory as tick-borne resistance spreads across Limpopo and KwaZulu-Natal cattle herds. Distribution through veterinary clinics retains the dominant channel position for prescription therapeutics, though e-commerce is capturing share in companion animal parasiticides where pet owners seek convenience.
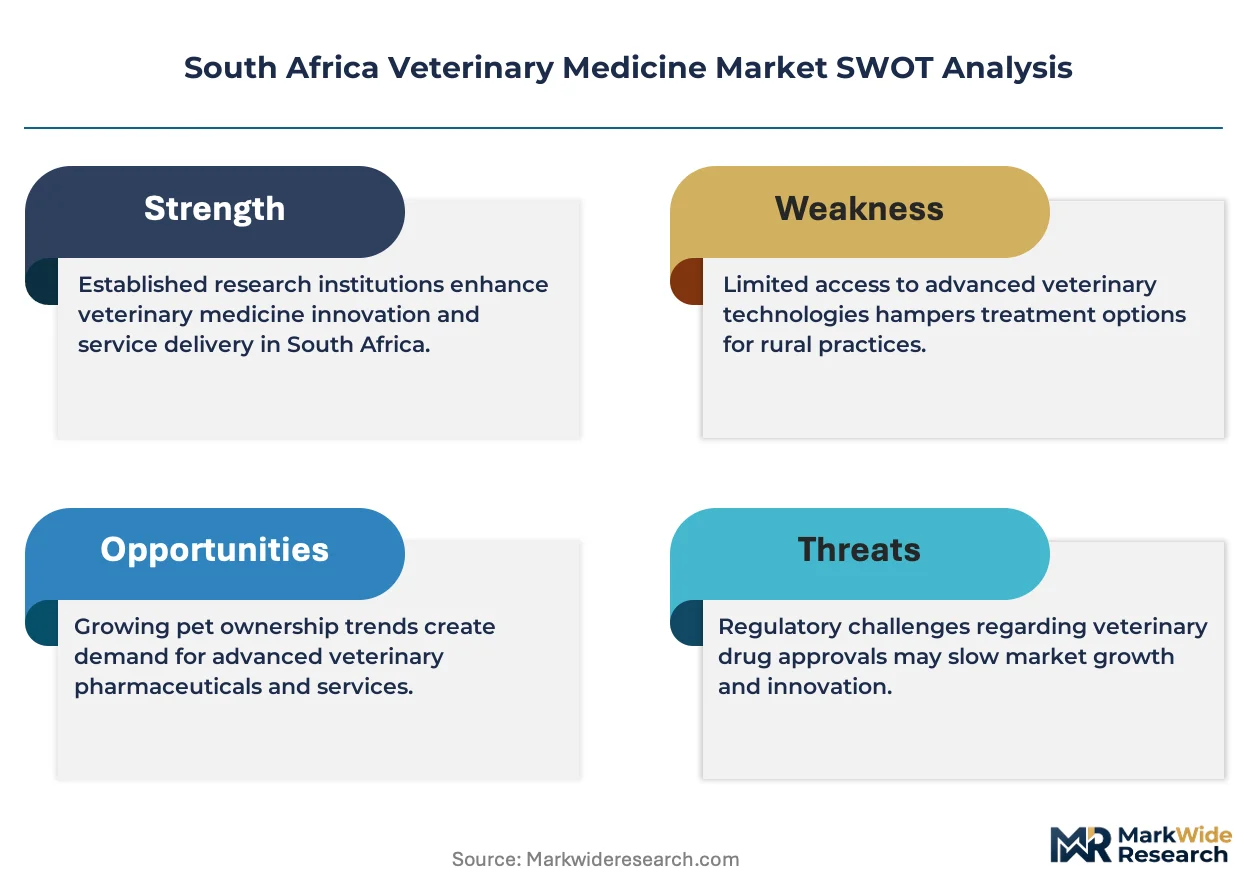
The South African Health Products Regulatory Authority governs veterinary medicine registration, while the Department of Agriculture enforces the Medicines and Related Substances Control Act and Fertilizers, Farm Feeds, Seeds and Remedies Act compliance. These frameworks elevate barriers for imported generics and mandate local stability testing, which shapes product portfolios and timeline planning for multinational entrants. Stakeholders must monitor regulatory harmonization progress with the Southern African Development Community, as mutual recognition agreements could reshape competitive access across neighboring markets.
Market Dynamics
Recombinant DNA platforms are compressing development timelines for veterinary biologics while the Fertilizers, Farm Feeds, Seeds and Remedies Act tightens residue surveillance across commercial feedlots. This dual pressure is restructuring competitive economics between domestic manufacturers and import-dependent distributors.
Growth Catalysts
- Lumpy Skin Disease Mandates:The Department of Agriculture's compulsory vaccination programs for cattle herds in Limpopo and KwaZulu-Natal are generating recurring demand for attenuated viral vaccines. Commercial producers must maintain compliance to access export certification.
- Tick-Borne Resistance Spread:Acaricide failure rates in communal grazing areas are accelerating rotation protocols and combination therapy adoption. Parasiticide procurement volumes are rising fastest among emerging farmer cooperatives.
- Onderstepoort Manufacturing Cluster:Concentrated biological production capacity near Pretoria reduces cold-chain logistics costs for domestic distributors serving the Gauteng-Johannesburg corridor.
Market Restraints
- Import Dependency for API Supply:Active pharmaceutical ingredient sourcing concentrates among Indian and Chinese manufacturers, exposing formulators to currency volatility and shipping delays.
- Local Stability Testing Mandates:The South African Health Products Regulatory Authority requires climate-specific shelf-life validation that extends registration timelines by 12-18 months for multinational entrants.
- Antimicrobial Withdrawal Complexity:Extended residue clearance periods for macrolide and tetracycline formulations limit treatment flexibility in intensive poultry operations facing disease pressure.
Strategic Opportunities
- Eastern Cape Emerging Farmer Segment:Underpenetrated communal livestock areas present channel expansion potential for parasiticide distributors willing to build veterinary extension networks.
- Companion Animal E-Commerce:Online prescription fulfillment for chronic condition management in urban pet populations is capturing share from traditional clinic dispensing.
- Southern African Development Community Harmonization:Pending mutual recognition agreements for veterinary product registration could unlock export pathways into Botswana, Namibia, and Zimbabwe.
Industry Challenges
- Veterinary Epidemiologist Shortage:Public sector compensation gaps are draining diagnostic capacity from the Onderstepoort Veterinary Institute, delaying outbreak response and vaccine strain updates.
- Cold-Chain Infrastructure Gaps:Temperature-controlled distribution to deep rural areas requires capital investment in solar-powered refrigeration that exceeds distributor return thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Veterinary Medicine Market |
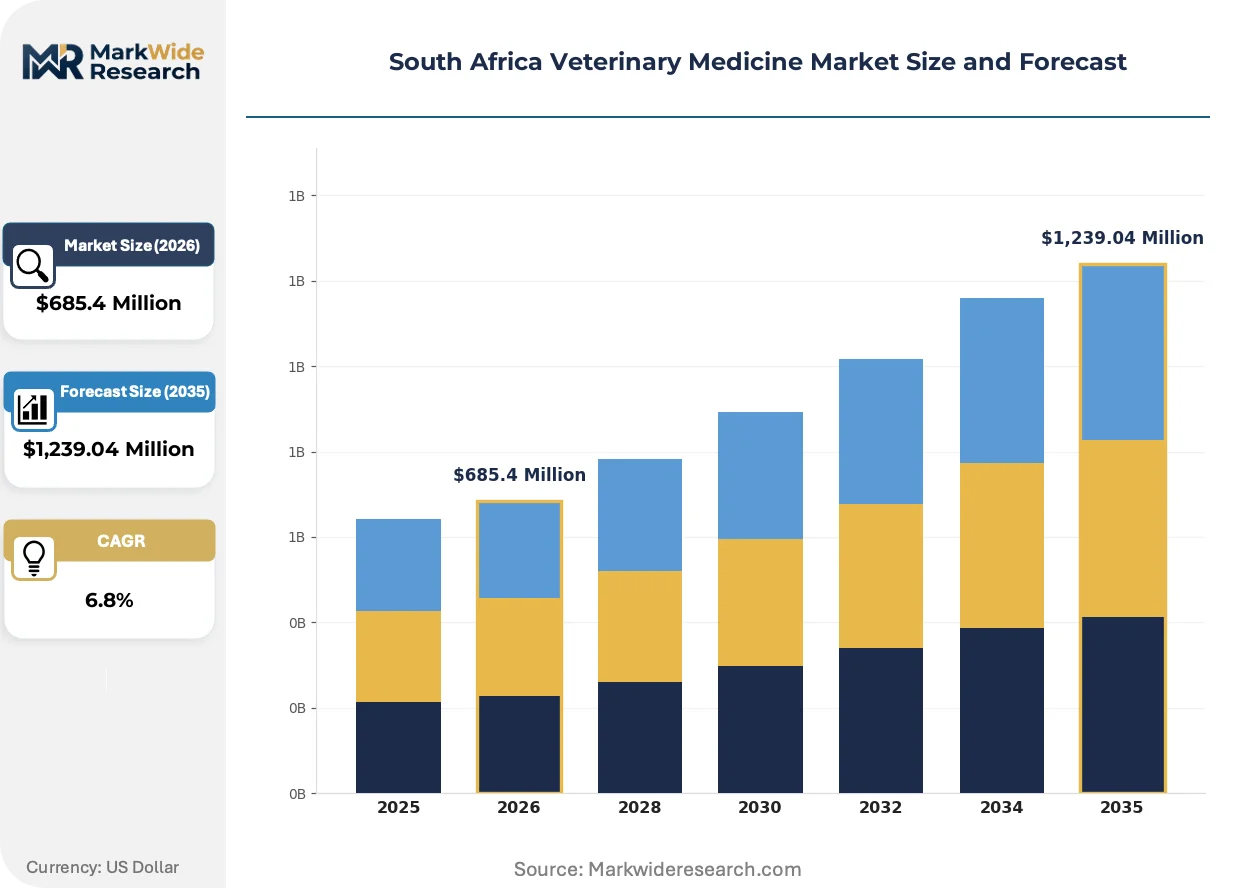
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antimicrobials, Anti-inflammatories, Parasiticides Application: Livestock, Companion Animals, Aquaculture, Equine Distribution Channel: Veterinary Clinics, E-Commerce, Pharmacies, Distributors Customer Type: Pet Owners, Farmers, Veterinary Practices, Research Institutions |
| Companies Covered | Biovac, Elanco Animal Health, Afrivet, Virbac South Africa, Boehringer Ingelheim, Zoetis, Ceva Santé Animale, Onderstepoort Biological Products, MSD Animal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Veterinary Medicine Market Strategic Shifts & Innovations
Biological manufacturing platforms and distribution digitization are restructuring how veterinary products reach food-producing and companion animal segments. These shifts are compressing traditional value chain margins while opening new service revenue streams.
mRNA vaccine development is consolidating around platform approaches that reduce antigen production costs for viral diseases affecting ruminants. Large-scale feedlot operators in the North West province are piloting these formulations for respiratory disease complexes. The technology is consolidating supplier relationships toward integrated platform licensors capable of rapid strain adaptation.
The Medicines and Related Substances Control Act amendments are tightening pharmacovigilance reporting requirements for all registered veterinary products. Distributors must now maintain adverse event databases accessible to the South African Health Products Regulatory Authority. Small generic importers face compliance cost burdens that favor established domestic manufacturers with dedicated regulatory affairs capacity.
Subscription-based preventive health packages are displacing transactional product sales in companion animal channels. Urban veterinary clinics in Cape Town and Johannesburg are bundling parasiticide prophylaxis with wellness examinations. Pet owner purchasing is consolidating toward practices offering integrated digital health records and automated refill scheduling.
South Africa Veterinary Medicine Market Segmentation
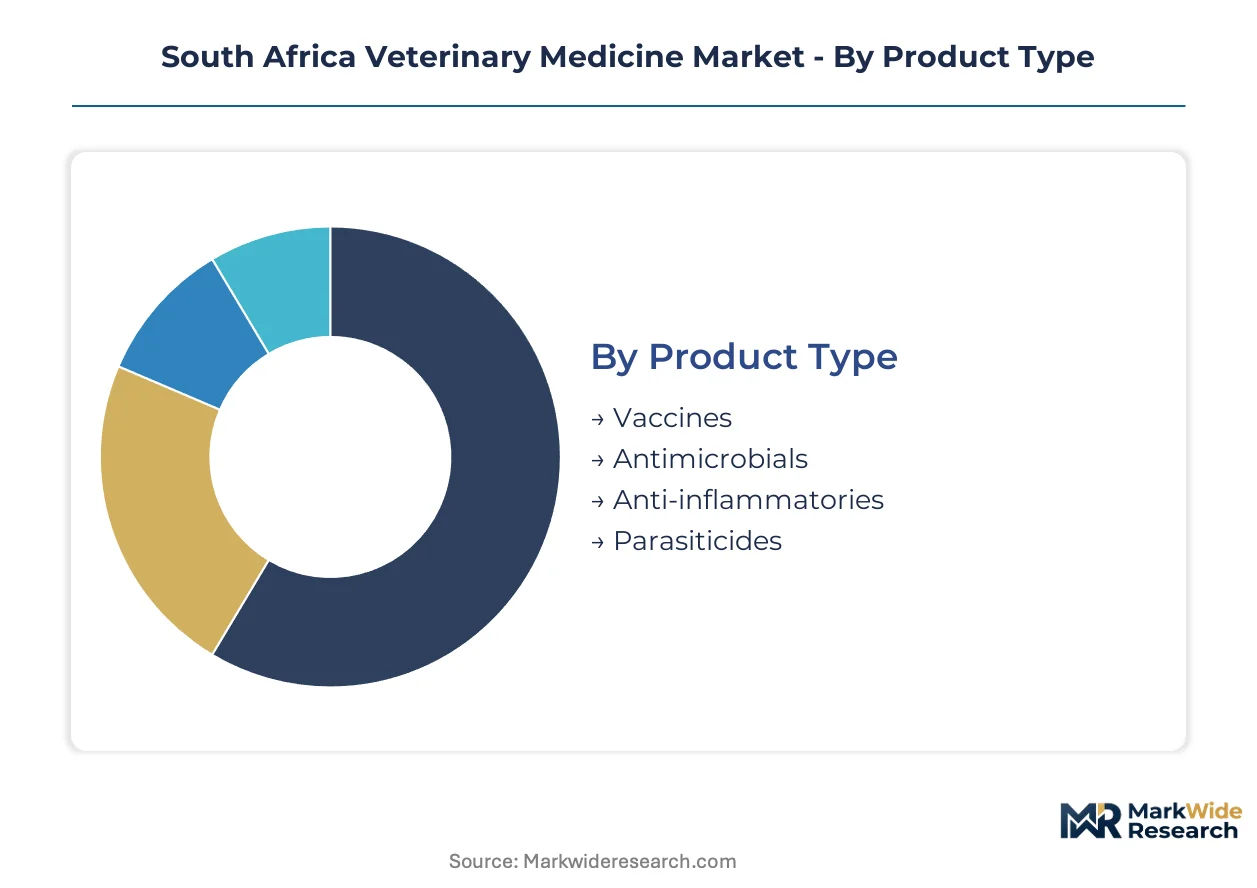
South Africa's veterinary medicine market segments along four critical dimensions that determine procurement patterns, regulatory exposure, and margin structures. Understanding these divisions reveals where biological innovation concentrates and which channels are capturing emerging farmer and urban pet owner demand.
Product Type:
Upgrade cycles vary sharply across biological and chemical formulations, with recombinant platforms displacing legacy attenuated vaccines faster than antimicrobial portfolios refresh.
- Vaccines:Attenuated and inactivated viral formulations dominate ruminant disease prevention, with compulsory brucellosis and lumpy skin disease programs in Limpopo and KwaZulu-Natal generating recurring procurement volumes. The Department of Agriculture's export certification requirements lock commercial feedlots into compliance-driven purchasing cycles that resist generic substitution.
- Parasiticides:Acaricides, endectocides, and anthelmintics address escalating tick-borne resistance across communal grazing areas. Emerging farmer cooperatives in the Eastern Cape are accelerating rotation protocols as single-active failures spread, driving combination therapy adoption faster than any other product category.
- Antimicrobials:Macrolide and tetracycline formulations face tightening residue surveillance under the Fertilizers, Farm Feeds, Seeds and Remedies Act, constraining treatment flexibility in intensive poultry operations.
- Anti-inflammatories:NSAID and corticosteroid products support post-surgical recovery and metabolic disorder management in dairy herds, with demand tracking mastitis incidence patterns in the Free State.
Volume placements concentrate in vaccines; the faster expansion belongs to parasiticides.
Application:
Cost tier differentiation separates intensive commercial operations from communal and companion animal segments, with biosecurity investment levels determining product sophistication.
- Livestock:Cattle, sheep, and poultry operations consume the bulk of biological and antimicrobial volumes, with feedlot density in the Gauteng-Johannesburg corridor creating procurement gravity for pharmaceutical distributors serving high-throughput facilities.
- Companion Animals:Dogs and cats drive parasiticide and vaccine demand through urban veterinary clinics in Cape Town and Johannesburg, where subscription preventive packages are displacing transactional sales.
- Equine:Racing and breeding stables in the Western Cape require specialized biologics and anti-inflammatory protocols, though this segment remains smaller than ruminant applications.
- Aquaculture:Marine and freshwater farm operations along the Eastern Cape coast generate niche demand for antimicrobial and parasiticidal treatments, constrained by limited veterinary service penetration.
Revenue concentrates in livestock; companion animals are climbing the fastest.
Distribution Channel:
Customer type determines channel selection, with prescription requirements and convenience preferences splitting procurement between professional and direct-to-consumer pathways.
- Veterinary Clinics:Licensed practices retain dominant share for prescription therapeutics and biologicals, particularly in urban centers where the South African Health Products Regulatory Authority mandates professional administration for controlled substances.
- E-Commerce:Online platforms capture growing share in companion animal parasiticides and chronic condition refills, with automated scheduling appealing to time-constrained pet owners in metropolitan areas.
- Distributors:Wholesale networks serve commercial livestock producers and emerging farmer cooperatives with cold-chain logistics for temperature-sensitive biologicals, anchored by the Onderstepoort manufacturing cluster near Pretoria.
- Pharmacies:Retail drug outlets handle limited over-the-counter companion animal products, constrained by veterinary prescription requirements for most therapeutics.
Procurement gravity centers on veterinary clinics; e-commerce shows the steepest expansion trajectory.
Customer Type:
Geographic concentration of customer bases shapes service requirements, with dense urban pet populations demanding different support models than dispersed rural livestock holdings.
- Farmers:Commercial livestock producers and emerging cooperatives generate bulk biological and parasiticide demand, with the former prioritizing export compliance and the latter seeking cost-optimized rotation protocols.
- Pet Owners:Urban households in Johannesburg, Cape Town, and Durban drive companion animal pharmaceutical consumption, increasingly purchasing through subscription wellness packages bundled with veterinary services.
- Veterinary Practices:Clinics and hospitals act as both customers and intermediaries, stocking inventory for immediate dispensing while influencing producer and pet owner product selection.
- Research Institutions:Onderstepoort Veterinary Institute and university laboratories procure specialized biologics for diagnostic and vaccine development work, representing a small but technically influential segment.
Transaction volume concentrates among farmers; pet owners are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial feedlot density in Gauteng-Johannesburg generates procurement gravity for pharmaceutical distributors serving high-throughput livestock operations. Provincial regulatory frameworks and veterinary service clusters shape demand concentration across South Africa's agricultural heartland.
Gauteng-Johannesburg Corridor
Dense feedlot operations and veterinary service clusters create concentrated demand for biologicals and parasiticides. The Department of Agriculture enforces Fertilizers, Farm Feeds, Seeds and Remedies Act compliance for residue monitoring. Johannesburg-based pharmaceutical distributors anchor cold-chain logistics networks serving commercial cattle producers.
KwaZulu-Natal
Tick-borne resistance spread accelerates acaricide rotation protocols among communal grazing cooperatives. Compulsory lumpy skin disease vaccination programs mandate recurring attenuated viral vaccine procurement. The Pietermaritzburg veterinary corridor supports biological distribution to coastal and midlands cattle herds.
Limpopo
Brucellosis eradication programs drive sustained demand for inactivated bacterial vaccines among commercial and emerging producers. The South African Health Products Regulatory Authority mandates local stability testing for all registered products. The Polokwane agricultural hub concentrates veterinary pharmaceutical procurement for northern border zone livestock.
Eastern Cape
Underpenetrated communal livestock areas present channel expansion potential for parasiticide distributors. Emerging farmer cooperatives seek cost-optimized rotation protocols as single-active acaricide failures spread. The Makhanda-Grahamstown corridor anchors veterinary extension networks reaching deep rural cattle holdings.
Western Cape
Racing and breeding stables generate specialized biologics demand for equine health management. Urban pet populations in Cape Town drive companion animal pharmaceutical consumption through subscription wellness packages. The Stellenbosch veterinary cluster supports diagnostic capacity for export certification requirements.
South Africa Veterinary Medicine Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with biological innovation consolidating around platform licensors while generic formulators compete on channel reach. Domestic manufacturing capacity concentrates near Pretoria, reducing cold-chain logistics costs for temperature-sensitive products. Three archetypes dominate: multinational platform developers, regional manufacturing specialists, and distribution-focused channel players. Competitive moves center on regulatory affairs capacity building and veterinary extension network expansion into emerging farmer cooperatives.
Among platform-development multinationals, Zoetis occupies a position exemplifying transgenic biological innovation, while Biovac anchors domestic manufacturing capacity through its Onderstepoort-based facility. Afrivet represents the channel-archetype, competing aggressively on reach into emerging farmer cooperatives. These three players illustrate how competitive positioning fragments across technology licensing, captive production, and distribution density vectors.
| Leading Market Players |
|---|
| Biovac |
| Elanco Animal Health |
| Afrivet |
| Virbac South Africa |
| Boehringer Ingelheim |
| Zoetis |
| Ceva Santé Animale |
| Onderstepoort Biological Products |
| MSD Animal Health |
| Others |
Cost & Logistics Intelligence
Compulsory vaccination programs for lumpy skin disease and brucellosis lock commercial feedlots into recurring procurement cycles that resist generic substitution, forcing supply chains to prioritize cold-chain reliability over cost minimization and sustaining premium pricing for attenuated viral vaccines.
Pricing Analysis
Volume placements concentrate in vaccines while margins concentrate in recombinant platforms. Three-tier pricing structure across platform-licensed premium, domestically manufactured standard, and import-generic economy levels separates Zoetis transgenic products from Biovac Onderstepoort formulations. Cost compression in economy-tier parasiticides is intensifying because emerging farmer cooperatives rotate acaricides aggressively. Commercial livestock producers show lowest price sensitivity due to export certification requirements, while communal grazing cooperatives exhibit highest sensitivity to per-dose costs.
Supply Chain Analysis
South African Health Products Regulatory Authority climate-specific stability testing requirements gate entry for multinational formulators, extending registration timelines and concentrating active pharmaceutical ingredient sourcing on Indian and Chinese manufacturers. Formulation depends on imported macrolide and tetracycline precursors, transgenic antigen substrates, and cold-chain packaging materials. Single-source vulnerability runs through concentrated API supply from Asian manufacturers exposed to currency volatility. Distribution runs through Johannesburg-based pharmaceutical distributors anchoring cold-chain networks for temperature-sensitive biologicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over Onderstepoort manufacturing capacity and regulatory affairs capability determines competitive survival. Players are pursuing backward integration into biological production to defend margin position.
For Market Incumbents: To counter import-dependent API exposure, secure captive supply arrangements with Indian pharmaceutical chemical manufacturers or accelerate transgenic platform licensing to reduce formulation cost exposure. Invest in dedicated regulatory affairs capacity to navigate South African Health Products Regulatory Authority stability testing mandates faster than multinational entrants.
For New Entrants and Emerging Players: Capture underpenetrated Eastern Cape communal livestock areas by building veterinary extension networks that demonstrate cost-optimized parasiticide rotation protocols to emerging farmer cooperatives. Prioritize e-commerce fulfillment capabilities for companion animal chronic condition refills in Johannesburg and Cape Town metropolitan markets.
For Investors and Strategic Acquirers: The window for entry favors domestic manufacturing specialists with Onderstepoort facility access and established regulatory affairs infrastructure. Long-term viability hinges on positioning for Southern African Development Community mutual recognition agreement expansion. Watch regulatory harmonization progress with Botswana, Namibia, and Zimbabwe as inflection indicator for export pathway unlocking.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Buildout | Accelerates South African Health Products Regulatory Authority registration timelines for biological formulations. |
| Veterinary Extension Network Expansion | Captures emerging farmer cooperative demand in underpenetrated Eastern Cape communal grazing areas. |
| Cold-Chain Infrastructure Investment | Enables temperature-controlled distribution to deep rural Limpopo and KwaZulu-Natal cattle herds. |
| mRNA Platform Licensing Agreement | Consolidates supplier relationships for rapid strain adaptation in North West feedlot respiratory disease programs. |
| E-Commerce Prescription Fulfillment | Displaces transactional clinic dispensing for urban Johannesburg and Cape Town companion animal parasiticides. |
Research Approach
Document review covered veterinary pharmaceutical registration databases, Department of Agriculture compulsory program mandates, and Southern African Development Community trade harmonization protocols, complemented by interviews with feedlot operations managers, veterinary clinic proprietors, pharmaceutical distribution channel heads, and regulatory affairs specialists at domestic manufacturers. Secondary validation drew from South African Health Products Regulatory Authority filing records, customs import data for active pharmaceutical ingredients, and Onderstepoort Biological Products production disclosures. Bottom-up procurement volume estimates from commercial livestock producers and top-down market sizing from distributor revenue aggregates underwent cross-reference triangulation.
Historical growth trajectories for vaccines, parasiticides, antimicrobials, and anti-inflammatories were cross-referenced against panel input from pharmaceutical procurement managers across Gauteng-Johannesburg corridor feedlots. The analytical framework modeled product type, application, distribution channel, and customer type dimensions across the projection horizon. CAGRs were derived from segment-level volume projections and price trajectory assumptions. Forecast inputs incorporated tick-borne resistance spread rates in Limpopo and KwaZulu-Natal, mRNA platform adoption curves in North West province feedlots, and e-commerce penetration rates in metropolitan companion animal channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Southern African Development Community regulatory harmonization timelines and veterinary epidemiologist capacity at Onderstepoort Veterinary Institute. Forecasts reflect documented assumptions regarding compulsory vaccination program continuity and API import channel stability. A model refresh is warranted upon material change in mutual recognition agreement ratification or significant currency volatility affecting Indian and Chinese pharmaceutical chemical sourcing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Anesthesia Machines Market