
 Veterinary Lasers Market | 2026-2036
Veterinary Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Lasers Market Intelligence
Class IV therapeutic laser certification is unwinding price compression across the veterinary equipment channel. BIOLASE, Inc. dominates dental-specialized laser platforms through direct veterinary education programs. SpectraVET leverages modular diode architectures to serve mixed-animal practices across North America. Omega Laser Systems Ltd anchors the European market with portable low-level laser therapy units designed for equine rehabilitation centers.
Veterinary lasers are coherent light sources operating at specific wavelengths between 600 nm and 10,600 nm, delivered via fiber optic or articulated arm systems to achieve tissue ablation, photobiomodulation, or diagnostic imaging in animal patients. Diode lasers lead product type volumes due to compact form factors and reduced cooling requirements, while CO2 laser systems command premium placement in surgical suites where soft-tissue precision limits collateral thermal damage. Surgical laser systems within the technology dimension capture the dominant installed base, though low-level laser therapy represents the fastest-expanding segment as rehabilitation protocols displace pharmaceutical pain management in post-operative care.
The FDA Center for Veterinary Medicine and the EU Medical Device Regulation frame device safety and clinical efficacy requirements, with CE marking and 510(k) pathways determining market access timelines for manufacturers. ISO 13485 quality management certification and IEC 60601-1 electrical safety standards further constrain supplier qualification, filtering smaller entrants from institutional procurement channels. Stakeholders must monitor evolving reimbursement codes for laser-assisted procedures across national veterinary insurance frameworks to anticipate capital equipment refresh cycles.
Market Dynamics
Photobiomodulation protocols are compressing pharmaceutical pain management expenditure across companion animal practices, redirecting capital toward laser therapy suites as first-line post-operative care. This substitution dynamic is restructuring equipment procurement priorities and vendor qualification criteria.
Growth Catalysts
- EU Medical Device Regulation streamlining:CE marking pathways for Class II and Class IIIb veterinary lasers are accelerating product entry timelines for European manufacturers.
- Pet insurance penetration:Reimbursement frameworks in Germany and Japan are covering laser-assisted procedures, enabling premium device adoption in urban specialty clinics.
- Diode laser miniaturization:Reduced cooling requirements and compact form factors are expanding portable unit deployment in ambulatory equine practices.
Market Restraints
- Input cost volatility:Rare earth element pricing for solid-state laser crystals creates margin pressure on diode system manufacturers.
- Technical limitation:Wavelength specificity constraints restrict single-device efficacy across heterogeneous tissue types in mixed-animal settings.
- Regulatory friction:FDA 510(k) clearance timelines for Class IV surgical lasers extend capital recovery periods for North American distributors.
Strategic Opportunities
- Underpenetrated geography:Brazil's expanding small animal specialist network presents untapped demand for rehabilitation-focused low-level laser therapy units.
- Technology convergence:Integration of laser therapy with diagnostic imaging platforms is creating bundled procedure offerings in Japanese university hospitals.
- Regulatory tailwind:India's PLI scheme for medical device manufacturing is attracting diode laser assembly investment for domestic veterinary supply.
Industry Challenges
- Certification timeline compression:ISO 13485 quality management audits are extending supplier qualification cycles for institutional procurement channels.
- Talent scarcity:Certified laser therapy technician training programs are failing to match installation growth in United States metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Lasers Market |
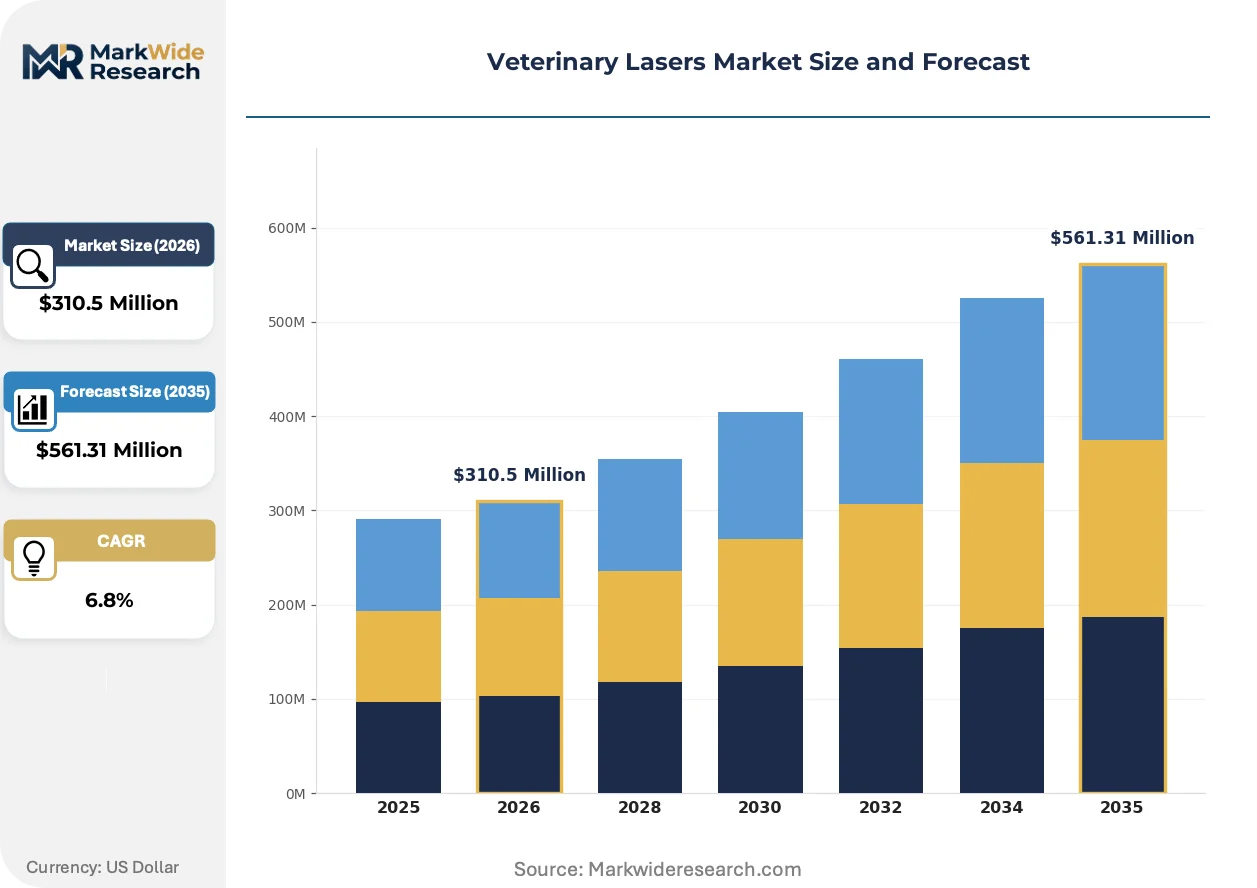
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $561.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, CO2 Lasers, Nd:YAG Lasers, Ruby Lasers Application: Veterinary Surgery, Pain Management, Dermatology, Dentistry End User: Animal Clinics, Research Institutions, Veterinary Hospitals, Mobile Veterinary Services Technology: Low-Level Laser Therapy, Surgical Laser Systems, Laser Imaging, Laser Diagnostics |
| Companies Covered | SpectraVET, VBS Direct Limited, Omega Laser Systems Ltd, Excel Lasers Limited, BIOLASE, Inc., Cutting Edge Laser Technologies, Summus Medical Laser, LLC, Aesculight, Aspen Laser Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Lasers Market Strategic Shifts & Innovations
Wavelength-tunable diode architectures are fragmenting the traditional fixed-wavelength equipment installed base. Vendors are repositioning around procedure-specific protocol libraries rather than hardware specifications.
Multi-wavelength diode platforms are displacing single-wavelength legacy systems in rehabilitation applications. Mixed-animal practices in Texas and Florida are adopting these units to sequence treatments across canine orthopedic and equine soft-tissue cases. The technology is displacing pharmaceutical dependency in post-surgical pain protocols, compressing recurring drug revenue for incumbent veterinary pharmaceutical distributors.
CE marking requirements under the EU Medical Device Regulation are tightening clinical evidence standards for therapeutic laser claims. Manufacturers must now submit species-specific efficacy data for soft-tissue and photobiomodulation indications. German and French veterinary teaching hospitals are accelerating collaborative trials to satisfy notified body expectations, shifting competitive advantage toward research-integrated suppliers.
Leasing arrangements with bundled maintenance and protocol training are replacing outright equipment purchases in United States companion animal clinics. Corporate practice groups like Banfield and VCA are standardizing on single-vendor fleet agreements with quarterly technology refresh options. This model is most visible in California and New York metro markets where capital efficiency metrics dominate procurement committee decisions.
Veterinary Lasers Market Segmentation
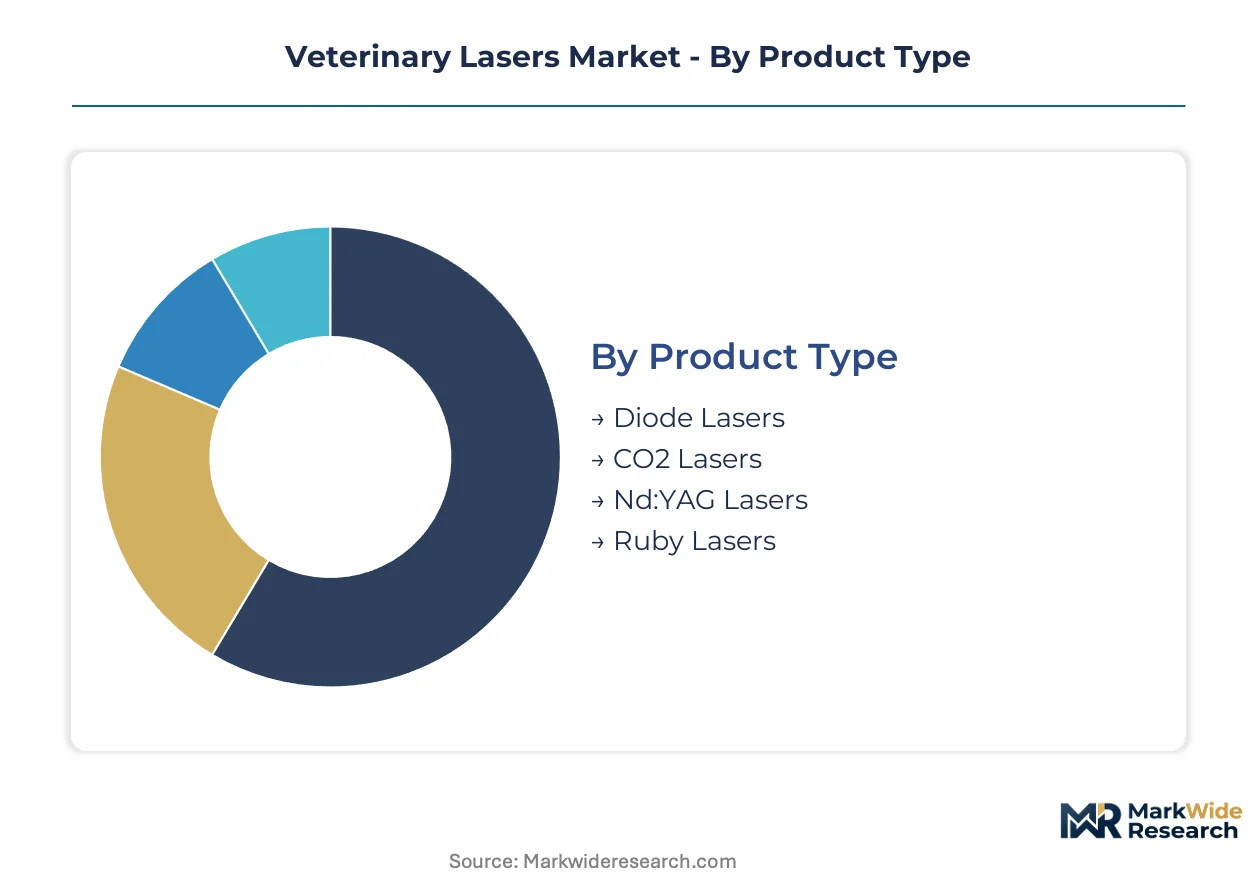
Veterinary laser segmentation reveals divergent equipment preferences across practice types and regulatory environments. Product architecture and wavelength specifications determine reimbursement eligibility and capital allocation priorities in institutional procurement.
Product Type:
Diode and CO2 laser platforms dominate domestic manufacturing footprints in the United States and Germany, while solid-state alternatives rely on rare earth supply chains concentrated in China.
- Diode Lasers:Compact semiconductor devices operating at 600-1000 nm wavelengths with thermoelectric cooling systems. Demand concentrates in United States companion animal clinics where portable units enable ambulatory house-call services; miniaturization trends are accelerating replacement cycles.
- CO2 Lasers:Gas discharge systems at 10,600 nm delivering precise soft-tissue ablation with minimal collateral thermal damage. German veterinary teaching hospitals prioritize these units for oncological resections; premium pricing reflects articulated arm precision engineering.
- Nd:YAG Lasers:Solid-state platforms utilizing neodymium-doped yttrium aluminum garnet crystals for deep tissue penetration.
- Ruby Lasers:Chromium-doped aluminum oxide systems historically deployed for dermatological pigment targeting.
Diode lasers hold the largest share; momentum sits with CO2 systems in academic medical centers.
Application:
Procedure reimbursement codes in Japan and Germany are redirecting capital toward pain management suites while surgical applications retain volume leadership in corporate practice groups.
- Veterinary Surgery:Tissue ablation, incision, and excision procedures across soft-tissue and oncological interventions. United States specialty referral hospitals anchor demand; FDA 510(k) clearance timelines favor established vendors with predicate device portfolios.
- Pain Management:Photobiomodulation protocols reducing pharmaceutical dependency in post-operative and chronic conditions. Japanese pet insurance frameworks now reimburse laser-assisted rehabilitation; Tokyo metropolitan clinics are expanding dedicated therapy suites.
- Dermatology:Targeted treatment of cutaneous lesions and inflammatory conditions in companion animals.
- Dentistry:Hard and soft-tissue oral procedures including gingivectomy and periodontal therapy.
Surgical applications retain installed base dominance; pain management represents the steepest expansion trajectory.
End User:
Capital intensity and technician certification requirements create distinct procurement patterns across facility types, with mobile services driving portable unit innovation.
- Animal Clinics:Private companion animal practices representing the primary volume channel. Corporate consolidation in the United States is standardizing fleet agreements with single-vendor maintenance bundles.
- Veterinary Hospitals:Multi-specialty referral centers with dedicated surgical and rehabilitation departments. German university hospitals are accelerating collaborative efficacy trials to satisfy EU MDR clinical evidence requirements.
- Research Institutions:Academic and pharmaceutical facilities conducting species-specific therapeutic studies.
- Mobile Veterinary Services:Ambulatory practices serving equine and rural companion animal populations. Texas and Florida operations are adopting multi-wavelength diode platforms to sequence treatments across species.
Animal clinics command the greatest unit volume; veterinary hospitals drive premium specification adoption.
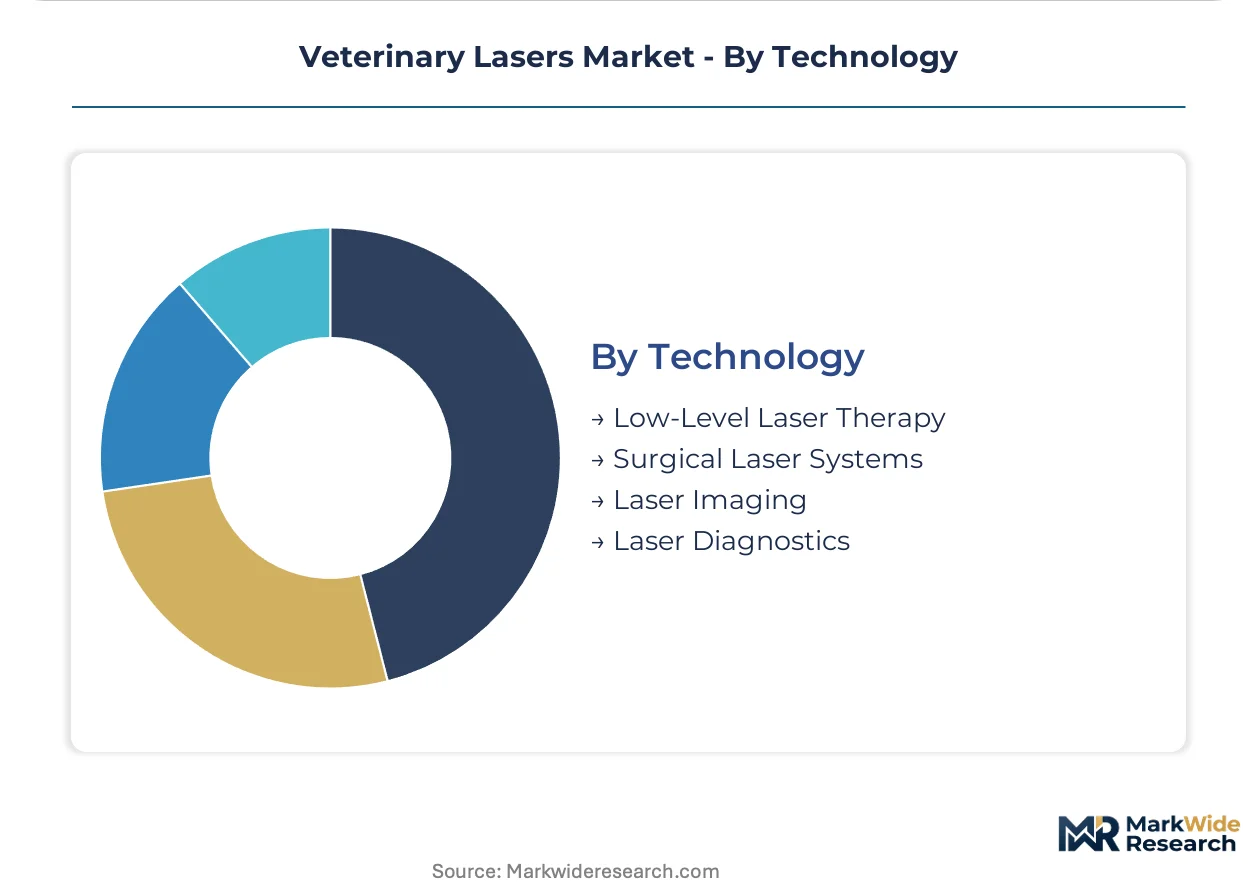
Technology:
Regulatory classification under FDA Center for Veterinary Medicine and EU MDR frameworks determines market access complexity and capital recovery timelines.
- Surgical Laser Systems:Class IV devices delivering ablative energy densities for incision and excision. FDA 510(k) clearance pathways extend distribution timelines; North American distributors face compressed margin structures during extended approval periods.
- Low-Level Laser Therapy:Class II and Class IIIb photobiomodulation systems stimulating cellular metabolism without thermal damage. CE marking streamlining under EU MDR is accelerating European manufacturer entry; rehabilitation protocols are displacing pharmaceutical pain management.
- Laser Imaging:Diagnostic platforms utilizing coherent light for tissue visualization and pathology detection.
- Laser Diagnostics:Analytical systems supporting point-of-care disease identification and treatment monitoring.
Surgical systems retain the dominant installed base; low-level laser therapy is gaining share fastest in post-operative care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diode laser manufacturing clusters in the United States and Germany supply the majority of installed veterinary laser systems worldwide, while demand expansion concentrates in markets with mature pet insurance frameworks and rising specialist clinic density.
United States
Corporate practice consolidation at Banfield and VCA is standardizing fleet procurement around single-vendor maintenance bundles. FDA 510(k) clearance pathways for Class IV surgical lasers extend distribution timelines, compressing distributor margins during extended approval periods. California and New York metro markets lead capital efficiency metrics in leasing arrangements with bundled protocol training.
Germany
EU Medical Device Regulation streamlining is accelerating CE marking timelines for Class II and Class IIIb therapeutic lasers. German university hospitals are conducting collaborative species-specific efficacy trials to satisfy notified body expectations for photobiomodulation claims. Bavaria's veterinary teaching hospital network anchors European clinical evidence generation for soft-tissue ablation protocols.
Japan
Pet insurance reimbursement frameworks now cover laser-assisted rehabilitation procedures, enabling premium device adoption in Tokyo metropolitan specialty clinics. METI standards for medical device electrical safety align with IEC 60601-1 certification requirements. Osaka and Nagoya university hospitals are pioneering integrated diagnostic imaging and laser therapy platforms for bundled procedure offerings.
Brazil
Expanding small animal specialist networks in São Paulo and Rio de Janeiro present untapped demand for rehabilitation-focused low-level laser therapy units. ANVISA regulatory pathways for imported medical devices create entry friction for foreign manufacturers. The Southeast region's veterinary referral center concentration is attracting distributor investment in technician certification programs.
India
The PLI scheme for medical device manufacturing is attracting diode laser assembly investment for domestic veterinary supply. CDSCO medical device rules classify therapeutic lasers based on risk stratification, determining registration pathway complexity. Maharashtra's Pune-Ahmednagar veterinary corridor is emerging as a hub for ambulatory equine laser therapy service deployment.
Veterinary Lasers Market Key Industry Players
Concentration sits with specialized veterinary laser manufacturers rather than diversified medical device conglomerates, creating a fragmented vendor base where technical certification and direct education programs determine account penetration. Two strategic archetypes dominate: dental-specialized platform developers leveraging veterinary education investments, and modular diode architects serving mixed-animal practices with portable configurations. Competitive moves center on M&A for protocol library expansion and strategic partnerships with corporate practice groups for fleet standardization.
Within the dental-specialized tier, BIOLASE, Inc. exemplifies education-anchored market development, while SpectraVET occupies a position among modular diode architects addressing ambulatory service requirements. Omega Laser Systems Ltd represents the European portable low-level laser therapy segment with equine rehabilitation center focus. These three manufacturers illustrate the geographic and application specialization vectors shaping procurement committee qualification criteria.
| Leading Market Players |
|---|
| SpectraVET |
| VBS Direct Limited |
| Omega Laser Systems Ltd |
| Excel Lasers Limited |
| BIOLASE, Inc. |
| Cutting Edge Laser Technologies |
| Summus Medical Laser, LLC |
| Aesculight |
| Aspen Laser Systems |
| Others |
Cost & Logistics Intelligence
Capacity utilization at diode laser foundries in the United States and Germany shapes both supply concentration and price floors for veterinary laser systems, with Class IV surgical platforms commanding premium positioning against portable Class II units.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across veterinary laser equipment, separating premium Class IV surgical systems from standard Class IIIb therapeutic units and economy-level portable diode devices. Price differentiation rests on ISO 13485 certification status and bundled protocol training rather than hardware specifications alone. Cost compression in economy-tier portable units is intensifying because rare earth element volatility squeezes solid-state crystal margins. Corporate practice groups like Banfield and VCA exhibit the least price sensitivity due to fleet standardization agreements, while independent mixed-animal practices in Texas and Florida remain most sensitive to upfront capital outlays.
Supply Chain Analysis
Strategic stockpiling of neodymium-doped yttrium aluminum garnet crystals and gallium arsenide substrates characterizes procurement behavior among tier-one veterinary laser manufacturers facing rare earth supply uncertainty. Manufacturing concentrates in the United States, Germany, and China, with final assembly drawing from Chinese rare earth processing and German precision optics engineering. Single-source vulnerability in neodymium supply from Chinese refiners creates exposure to export restriction shocks. Distribution runs through specialized veterinary equipment distributors with direct field service capabilities rather than general medical device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical pain management substitution threatens equipment-dependent revenue streams, requiring incumbents to reposition laser therapy as indispensable rather than discretionary within post-operative protocols.
For Market Incumbents: Fortify installed base retention through backward integration into technician certification programs and captive maintenance service networks. Deepen vertical control over protocol library intellectual property to lock out modular competitors. Counter SpectraVET-style portable architectures by embedding proprietary treatment sequencing software that resists interoperability. For New Entrants and Emerging Players: Differentiate on wavelength-tunable diode platforms targeting Brazil's underpenetrated specialist clinic network in São Paulo and Rio de Janeiro. Penetrate the rehabilitation-focused low-level laser therapy segment where ANVISA regulatory friction has slowed established foreign vendors. Pursue white-label manufacturing partnerships with India's PLI scheme beneficiaries to bypass import duty structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors research-integrated suppliers with collaborative trial relationships at German and Japanese university hospitals. Five-to-ten year viability concentrates in vendors capable of satisfying evolving EU MDR species-specific efficacy requirements. Monitor FDA 510(k) clearance velocity for Class IV surgical lasers as an inflection indicator for distributor margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR streamlining at notified bodies compresses European market entry timelines for therapeutic laser manufacturers. |
| Protocol Library Expansion | Species-specific treatment databases differentiate vendors in procurement evaluations at German veterinary teaching hospitals. |
| Technician Certification Investment | Training program scarcity in United States metropolitan markets creates captive channel control for equipment suppliers. |
| Reimbursement Strategy Development | Pet insurance framework alignment in Japan and Germany enables premium procedure adoption in urban specialty clinics. |
| Diagnostic Imaging Integration | Platform convergence at Osaka university hospitals creates bundled procedure offerings with higher capital efficiency metrics. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body documentation, and veterinary equipment procurement records preceded structured interviews with veterinary practice owners, biomedical equipment procurement managers, and laser therapy technician training program directors. Primary fieldwork across United States corporate practice groups, German university hospital networks, and Japanese specialty clinics combined with secondary validation against ISO 13485 audit registries and IEC 60601-1 certification listings. Bottom-up unit shipment estimates triangulated against top-down capital expenditure patterns at institutional veterinary facilities.
Variance decomposition across product type, application, end user, and technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from segmented growth rate reconciliation against macroeconomic veterinary services expenditure trends. Modeled inputs included pet insurance penetration trajectories, regulatory clearance velocity assumptions, and rare earth element price sensitivity coefficients affecting solid-state laser manufacturing costs.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement code expansion or rare earth supply stability would require recalibration. Forecasts reflect documented assumptions regarding technician certification pipeline growth and corporate practice consolidation velocity. Revision becomes warranted when FDA 510(k) timeline compression or EU MDR clinical evidence requirement relaxation crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Animal Intestinal Health Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Veterinary Tables Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Canine Parvovirus Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Pet Cremation Market
Veterinary
CBD Pet Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Canine Arthritis Market
Veterinary
Global Animal Model Market