
 Medication Management System Market | 2026-2036
Medication Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Medication Management System Market Outlook
Cloud-native architecture certification is reorganizing competitive tiers in medication management, as hospitals prioritize interoperability with existing electronic health records. Cerner Corporation leverages its embedded position in health system IT stacks to sustain recurring revenue from integrated medication modules. Epic Systems Corporation anchors enterprise-wide deployments through its tightly coupled EHR-native workflow design. Baxter International Inc. differentiates through specialized infusion pump connectivity that closes the loop between ordering and administration.
A medication management system comprises software and hardware platforms that orchestrate prescribing, dispensing, administering, and monitoring of pharmaceutical therapies, typically integrating barcode verification, clinical decision algorithms, and real-time inventory tracking to prevent adverse drug events. The primary purpose is eliminating human error across the medication use process while maintaining regulatory audit trails. Automated dispensing systems dominate capital expenditure budgets due to their tangible impact on nursing workflow efficiency and controlled substance security. Cloud-based delivery mode represents the fastest-expanding structural category, as smaller hospitals and long-term care facilities outsource infrastructure maintenance to specialized vendors. Compliance monitoring applications command premium pricing because they directly address Joint Commission survey requirements and malpractice liability exposure.
FDA barcode medication administration mandates and HIPAA security rule enforcement shape product development roadmaps, forcing vendors to embed audit logging and access controls at the architecture level. The Drug Enforcement Administration's electronic prescribing requirements for controlled substances further constrain market entry by imposing cryptographic authentication standards. Stakeholders must monitor evolving state-level e-prescribing mandates and interoperability rulemaking from the Office of the National Coordinator for Health IT to anticipate procurement cycle timing and certification requirements.
Market Dynamics
Cloud-native architecture certification is reorganizing competitive tiers in medication management, as hospitals prioritize interoperability with existing electronic health records and regulatory audit requirements intensify.
Growth Catalysts
- FDA barcode medication administration mandates:Healthcare facilities must upgrade legacy infrastructure to comply with enforcement standards, creating replacement demand across installed bases.
- Joint Commission survey requirements:Compliance monitoring applications command premium pricing as hospitals seek to reduce malpractice liability exposure and satisfy accreditation protocols.
- Integrated health networks:Multi-site hospital systems in the United States are consolidating procurement across facilities, favoring vendors with enterprise-scale deployment capabilities.
Market Restraints
- DEA cryptographic authentication standards:Electronic prescribing requirements for controlled substances impose technical barriers that constrain market entry for smaller vendors lacking certification expertise.
- Capital intensity of automated dispensing systems:Hardware platforms require substantial upfront investment, limiting adoption pace among independent community hospitals and long-term care facilities.
- Legacy infrastructure lock-in:Proprietary EHR architectures create switching costs that slow migration to cloud-native alternatives despite superior interoperability.
Strategic Opportunities
- Long-term care facility outsourcing:Smaller post-acute care providers represent an underpenetrated segment seeking to offload infrastructure maintenance to specialized cloud vendors.
- ONC Health IT interoperability rulemaking:Evolving certification requirements create timing windows for vendors that achieve early compliance with information blocking provisions.
- Infusion pump connectivity convergence:Integration between smart pump networks and medication ordering systems closes safety loops that standalone dispensing cabinets cannot address.
Industry Challenges
- Interoperability certification timelines:Vendors face extended development cycles to achieve cloud-native architecture validation against multiple EHR platform specifications simultaneously.
- Clinical informatics talent scarcity:Health systems struggle to recruit pharmacy informaticists capable of configuring clinical decision algorithms and maintaining real-time inventory tracking workflows.
- Multi-site integration complexity:Consolidated health networks demand synchronized deployment across heterogeneous legacy environments with varying technical debt levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medication Management System Market |
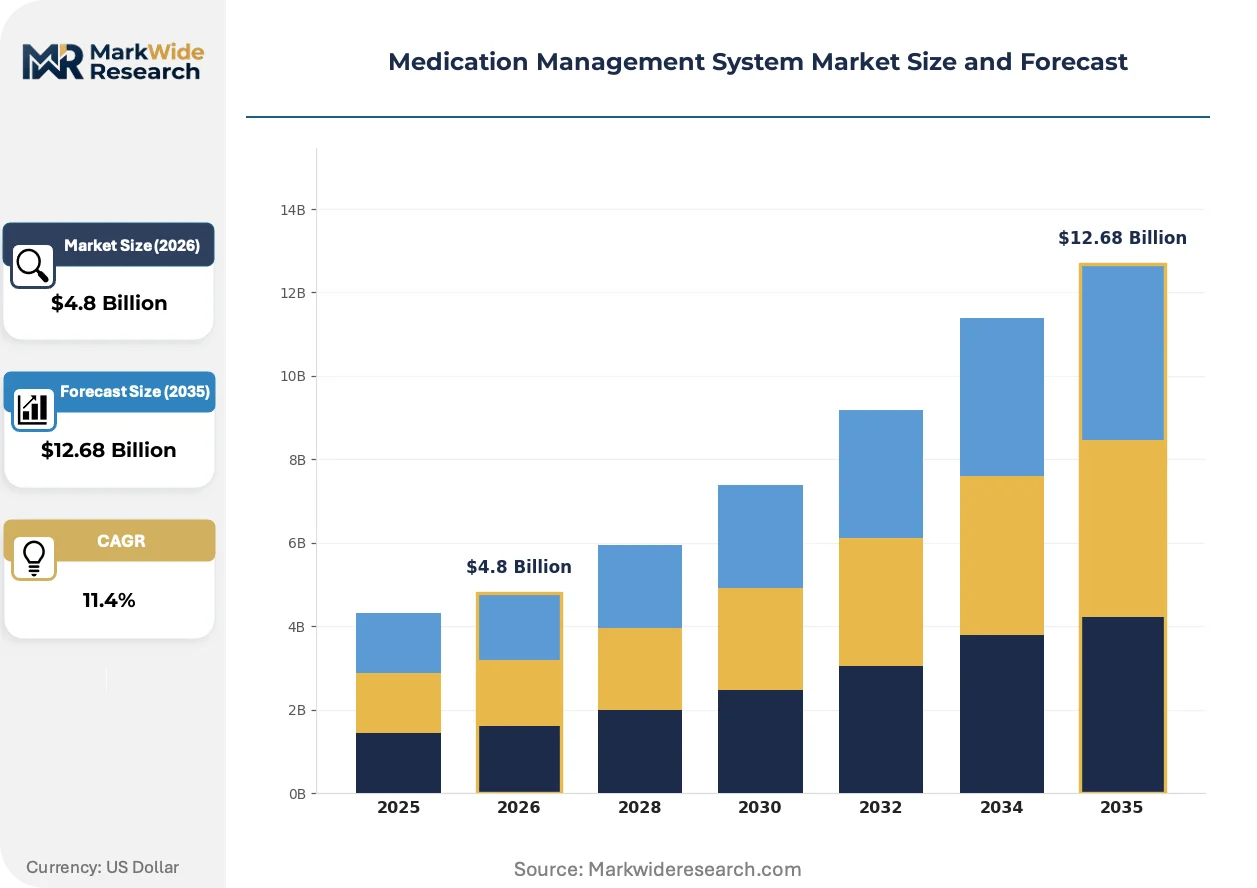
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computerized Provider Order Entry, Electronic Medication Administration Record, Clinical Decision Support System, Automated Dispensing System End User: Hospitals, Long-term Care Facilities, Home Healthcare, Pharmacies Delivery Mode: Cloud-based, On-premises, Hybrid, Mobile Application: Patient Safety, Compliance Monitoring, Drug Interaction Management, Inventory Control |
| Companies Covered | BD, Omnicell, Inc., Cerner Corporation, Epic Systems Corporation, Swisslog Healthcare, GE Healthcare, McKesson Corporation, Allscripts Healthcare Solutions, Inc., Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medication Management System Market Strategic Shifts
Artificial intelligence integration and edge computing deployment are actively reshaping how medication management systems process clinical data and execute safety verifications at the point of care.
Machine learning algorithms embedded in clinical decision support modules is bifurcating vendor capabilities between those offering predictive adverse event detection and those limited to rule-based alerts. Academic medical centers and large integrated delivery networks are adopting these tools fastest, driven by quality metric reporting requirements. The technology is compressing competitive differentiation around data training set scale and algorithmic transparency rather than hardware reliability alone.
REACH chemical safety registration and EU MDR cybersecurity annexes are forcing European vendors to embed lifecycle security documentation into product design files. Manufacturers must now demonstrate post-market surveillance capabilities for software updates and vulnerability patching. Class IIa medication management devices face heightened notified body scrutiny, compressing time-to-market for new feature releases.
Subscription-based service models are displacing perpetual license arrangements as hospital capital budgets tighten and IT departments prioritize operational expenditure predictability. Vendor financing arrangements and managed service partnerships are capturing preference among mid-size health systems lacking dedicated infrastructure teams. This shift is most visible in Germany and France, where hospital consolidation has centralized procurement authority and standardized vendor evaluation frameworks.
Medication Management System Market Segmentation
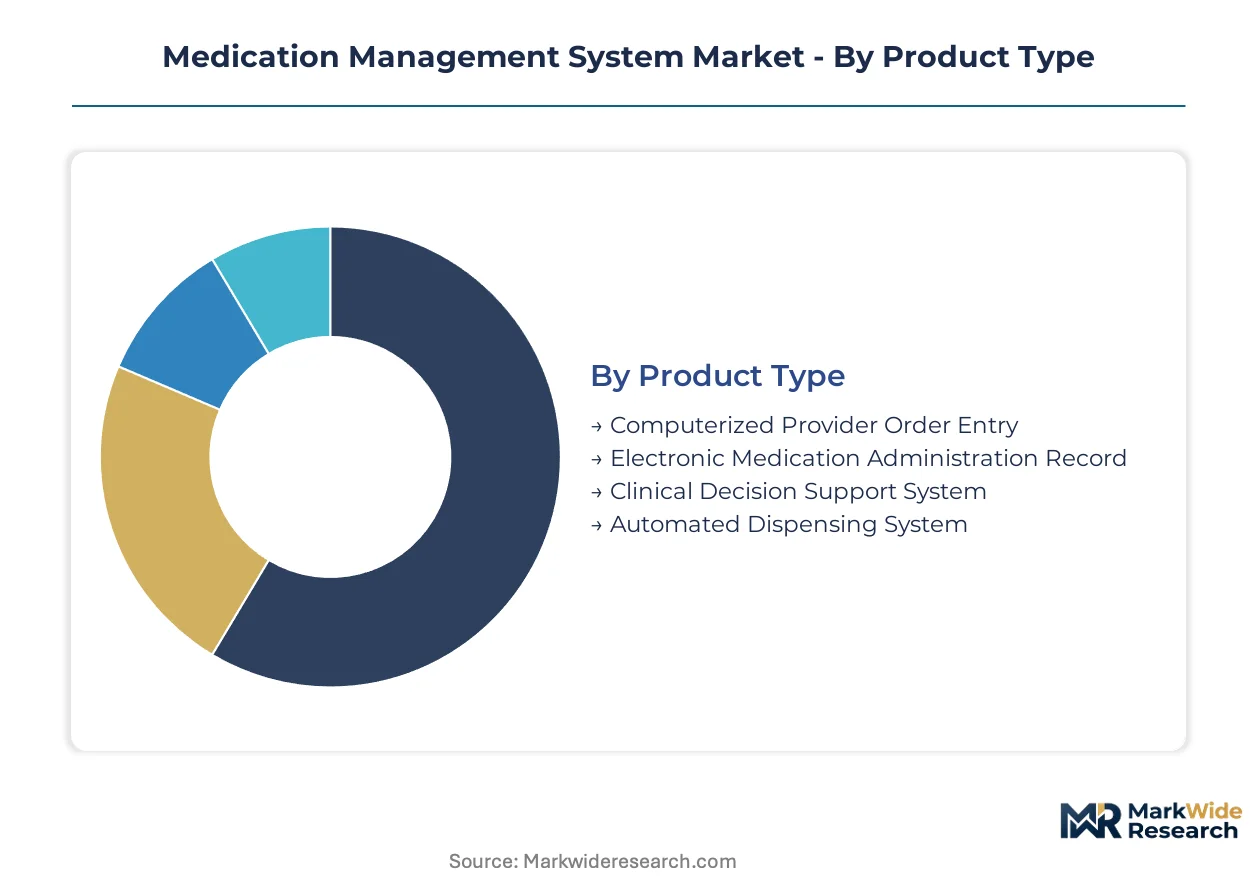
Medication management systems fragment across four distinct axes, each shaped by divergent regulatory pressure, infrastructure maturity, and care delivery economics. Procurement decisions increasingly hinge on how segment-specific capabilities align with Joint Commission mandates, DEA authentication requirements, and cloud interoperability certifications.
Product Type:
FDA barcode medication administration enforcement and DEA electronic prescribing standards create divergent compliance burdens across hardware-intensive versus software-native platforms.
- Automated Dispensing System:Hardware platforms integrating barcode verification, biometric access controls, and real-time inventory tracking for controlled substance security. Hospital pharmacy departments in the United States concentrate procurement here to satisfy Joint Commission survey requirements and reduce nursing workflow friction.
- Clinical Decision Support System:Algorithmic modules embedding drug interaction databases, dosing calculators, and allergy cross-referencing within EHR workflows. Academic medical centers prioritize these tools to address quality metric reporting and malpractice liability exposure.
- Computerized Provider Order Entry:Physician-facing interfaces for electronic prescription generation with embedded formulary checking.
- Electronic Medication Administration Record:Point-of-care documentation systems capturing nurse verification timestamps and patient identification events.
Established volume favors Automated Dispensing System; emerging adoption favors Clinical Decision Support System.
End User:
Capital intensity and informatics staffing requirements segment demand between integrated delivery networks and resource-constrained independent operators.
- Hospitals:Multi-site health systems consolidating procurement across emergency departments, operating suites, and inpatient wards. United States integrated networks drive enterprise-scale deployments favoring vendors with synchronized rollout capabilities across heterogeneous legacy environments.
- Long-term Care Facilities:Post-acute providers managing polypharmacy for elderly populations with limited on-site pharmacy infrastructure. Cloud-based outsourcing models are gaining traction fastest here as administrators seek to offload server maintenance and cybersecurity patching.
- Home Healthcare:Mobile-enabled medication adherence monitoring for discharged patients with complex chronic conditions.
- Pharmacies:Retail and specialty pharmacy chains requiring inventory synchronization with prescriber networks.
Procurement consolidation elevates Hospitals; infrastructure outsourcing elevates Long-term Care Facilities.
Delivery Mode:
Total cost of ownership calculations and HIPAA security rule enforcement reshape preferences between capital expenditure and operational expenditure models.
- Cloud-based:Vendor-hosted architectures with subscription pricing, automatic security patching, and API-driven EHR interoperability. Smaller hospitals and long-term care facilities in Germany and France are migrating fastest as hospital consolidation centralizes IT governance and standardizes vendor evaluation frameworks.
- On-premises:Client-managed server infrastructure retaining direct control over patient data residency and audit logging. Large United States health systems with dedicated security operations centers maintain preference here despite higher total cost of ownership.
- Hybrid:Mixed deployments isolating controlled substance data on local servers while outsourcing non-critical modules.
- Mobile:Smartphone and tablet applications for bedside medication verification and remote order authorization.
Operational expenditure predictability favors Cloud-based; data sovereignty requirements favor On-premises.
Application:
Malpractice liability exposure and accreditation survey timing concentrate investment in modules with direct regulatory audit trail value.
- Compliance Monitoring:Automated documentation generators for Joint Commission readiness, FDA adverse event reporting, and state pharmacy board inspections. These applications command premium pricing because they directly reduce survey deficiency risk and legal discovery exposure.
- Patient Safety:Barcode verification, allergy alerting, and high-risk medication double-check protocols at the point of administration. Nursing leadership prioritizes these capabilities to reduce preventable adverse drug events and associated quality metric penalties.
- Drug Interaction Management:Real-time screening against polypharmacy risks for elderly and complex chronic populations.
- Inventory Control:Automated reorder triggers, lot tracking, and waste reduction analytics for pharmacy supply chains.
Premium pricing power favors Compliance Monitoring; workflow integration urgency favors Patient Safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters in the United States, Germany, and Japan, where hospital consolidation and regulatory mandates are accelerating procurement of certified medication management platforms.
United States
Integrated health networks spanning multiple states are consolidating procurement decisions at the corporate level, favoring vendors with enterprise-scale deployment capabilities. FDA enforcement of barcode medication administration standards and DEA electronic prescribing requirements for controlled substances are compelling infrastructure upgrades across legacy installations. The Boston-Cambridge corridor anchors significant health system IT innovation, with academic medical centers piloting AI-enabled clinical decision support modules.
Germany
Hospital consolidation under regional purchasing cooperatives is standardizing vendor evaluation frameworks and favoring subscription-based service models over perpetual licenses. EU MDR cybersecurity annexes and REACH chemical safety documentation requirements are extending product development timelines for device manufacturers. The Rhine-Ruhr metropolitan region concentrates health IT procurement authority, with university hospitals driving early adoption of cloud-native interoperability certifications.
Japan
Aging demographics and polypharmacy management needs are expanding demand for automated dispensing systems in acute care and long-term care facilities. METI digital health initiatives and PMDA software-as-a-medical-device guidance are shaping vendor certification requirements for algorithmic clinical decision tools. The Tokyo-Osaka corridor dominates procurement volume, with large integrated delivery networks prioritizing EHR-native workflow designs.
United Kingdom
NHS England's medication safety improvement programs are mandating barcode administration verification across hospital trusts, creating replacement demand for outdated infrastructure. MHRA recognition of FDA-authorized devices is streamlining market access for US-based vendors with established interoperability certifications. The Greater Manchester and London health systems are consolidating pharmacy informatics procurement, favoring vendors with managed service partnership capabilities.
France
Regional hospital agencies are centralizing IT governance and shifting capital expenditure toward operational expenditure models for medication management infrastructure. ANSM post-market surveillance requirements and CNIL data protection mandates are embedding audit logging and access controls into product architectures from design phase. The Paris-Île-de-France region concentrates procurement authority, with university hospital centers driving adoption of compliance monitoring applications for Joint Commission-equivalent accreditation.
Medication Management System Market Competitive Environment
Concentration sits with EHR-embedded platforms and specialized hardware manufacturers, creating a tiered structure where enterprise health IT vendors and medical device specialists occupy distinct competitive positions. The market organizes around three strategic archetypes: integrated health IT stacks with native medication modules, standalone automated dispensing hardware specialists, and infusion therapy connectivity platforms. Dominant competitive moves include cloud-native architecture certification to satisfy interoperability mandates and strategic partnerships with regional purchasing cooperatives to secure multi-site deployment contracts.
Within the EHR-native tier, Cerner Corporation and Epic Systems Corporation exemplify vendors leveraging embedded health system relationships to sustain recurring revenue from integrated medication workflows. Baxter International Inc. occupies a specialized position among infusion pump connectivity providers, representing the convergence archetype that closes safety loops between ordering and administration systems. These three companies anchor the competitive structure, with their respective positions reflecting divergent strategic bets on software depth versus hardware specialization versus therapy-specific integration.
| Leading Market Players |
|---|
| BD |
| Omnicell, Inc. |
| Cerner Corporation |
| Epic Systems Corporation |
| Swisslog Healthcare |
| GE Healthcare |
| McKesson Corporation |
| Allscripts Healthcare Solutions, Inc. |
| Baxter International Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA barcode medication administration certification gates both vendor qualification and price differentiation simultaneously, compressing margins for uncertified hardware suppliers while enabling premium capture by cloud-native platform providers with embedded EHR interoperability.
Pricing Analysis
Joint Commission survey requirements dictate the pricing tier structure across medication management platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-scale cloud deployments from mid-tier hybrid installations and basic on-premises configurations. Cost compression in the standard tier is intensifying because long-term care facilities are consolidating procurement under regional purchasing cooperatives. Independent community hospitals exhibit the highest price sensitivity due to capital budget constraints, while integrated delivery networks prioritize total cost of ownership over upfront licensing fees.
Supply Chain Analysis
Semiconductor fabrication capacity for embedded medication dispensing controllers represents a critical chokepoint constraining hardware platform delivery timelines. Manufacturing concentrates in the United States, Germany, and Japan for automated dispensing cabinets, while cloud software development draws from India and Ireland for clinical informatics engineering. Supply chains rest on stainless steel pharmaceutical-grade enclosures, barcode scanner modules, and biometric authentication sensors. Single-source vulnerability persists in specialized pump connectivity chipsets. Distribution runs through regional healthcare group purchasing organizations with multi-site deployment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medication management system market is entering a cyclical recovery phase as hospital capital expenditure budgets rebound from pandemic-era deferrals and FDA enforcement timelines accelerate replacement demand across aging installed bases.
For Market Incumbents: Secure cloud-native architecture certification ahead of ONC Health IT interoperability rulemaking deadlines to defend enterprise contract renewals against emerging SaaS-native competitors. Deepen backward integration into clinical decision algorithm development to reduce dependency on third-party drug interaction database licensing. Prioritize managed service partnerships with regional purchasing cooperatives to lock in multi-site deployment schedules.
For New Entrants and Emerging Players: Lead with specialized infusion pump connectivity modules that close safety loops between ordering and administration systems, a segment where EHR-native incumbents lack hardware depth. Target long-term care facilities in Germany and France seeking to outsource infrastructure maintenance to cloud vendors with subscription pricing. Pursue white-label partnerships with established medical device distributors to bypass direct hospital procurement committee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based delivery segments as vendor-hosted architectures displace client-managed server infrastructure. Position acquisition screening around clinical informatics talent density and existing EHR integration certification portfolios rather than hardware manufacturing scale. Monitor DEA electronic prescribing mandate enforcement timelines as the primary signal for replacement demand inflection in the automated dispensing hardware segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Certification | ONC interoperability rulemaking rewards early compliance with information blocking provisions. |
| Hospital System Partnership | Multi-site deployment contracts with integrated networks anchor recurring revenue streams. |
| Infusion Pump Connectivity Convergence | Baxter International's specialized positioning demonstrates therapy-specific integration value. |
| Managed Service Partnership | Regional purchasing cooperatives in Germany favor subscription models over capital expenditure. |
| Clinical Decision Algorithm Development | Academic medical centers prioritize predictive adverse event detection capabilities. |
Study Parameters
Desk research of FDA enforcement documentation, hospital procurement databases, and GPO contract filings preceded structured interviews with pharmacy informaticists, biomedical engineers, hospital purchasing committee chairs, and cloud vendor product managers. Primary fieldwork captured deployment timeline data, certification cost structures, and interoperability testing protocols. Secondary validation drew from CMS Medicare reimbursement data, Joint Commission survey deficiency reports, and SEC filings of publicly traded health IT vendors. Bottom-up facility-level adoption modeling triangulated against top-down health system IT budget projections.
Variance decomposition across product type, delivery mode, end-user segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented adoption curves weighted by Joint Commission survey timing and DEA mandate enforcement schedules. Modeled inputs included EHR platform market share trajectories, cloud infrastructure cost decline curves, and clinical informatics staffing availability by metropolitan region.
Forecasts assume regulatory continuity in FDA barcode medication administration enforcement and ONC Health IT certification programs; material policy shifts would require re-modeling adoption timelines and vendor competitive positioning. Practitioners should keep alternative scenarios live as hospital consolidation patterns and interoperability rulemaking evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
PDA Closure Devices Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Germany Ophthalmic Devices Market