
 Veterinary Anesthesia Drugs Market | 2026-2036
Veterinary Anesthesia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Anesthesia Drugs Market Analytics
Veterinary anesthesiologist shortages across tertiary care institutions are redrawing competitive dynamics in the companion animal surgery segment. Zoetis leverages its integrated anesthesia and analgesia portfolio to sustain loyalty among large veterinary hospital groups. Dechra Pharmaceuticals specializes in injectable sedative-anesthetic combinations for equine and exotic species, occupying a defensible niche outside the canine-feline mainstream. Merck Animal Health controls distribution density in North American academic veterinary medical centers through exclusive supply agreements.
Veterinary anesthesia drugs comprise pharmacological agents—including isoflurane, sevoflurane, propofol, ketamine, and medetomidine—formulated to induce reversible loss of consciousness and analgesia in non-human species, with dosing calibrated by metabolic weight and species-specific receptor pharmacology. Injectable anesthetics dominate procedural volume in general practice settings where gas anesthesia infrastructure remains limited, while inhalation anesthetics command premium positioning at referral hospitals performing prolonged orthopedic and soft-tissue surgeries. The adjuvant segment, encompassing local anesthetics and analgesic synergists, represents the fastest-expanding margin pool as multimodal anesthesia protocols gain veterinary adoption.
The FDA's Center for Veterinary Medicine and the EMA's Committee for Medicinal Products for Veterinary Use enforce batch consistency, residue limit, and target animal safety standards that shape product development timelines and market access pathways. ISO 10993 biocompatibility frameworks and species-specific pharmacovigilance requirements add compliance layers for manufacturers seeking multi-jurisdiction registration. Stakeholders must monitor evolving controlled substance scheduling for ketamine and tiletamine across national drug enforcement agencies, as regulatory reclassification would disrupt formulation strategies and distribution security obligations.
Market Dynamics
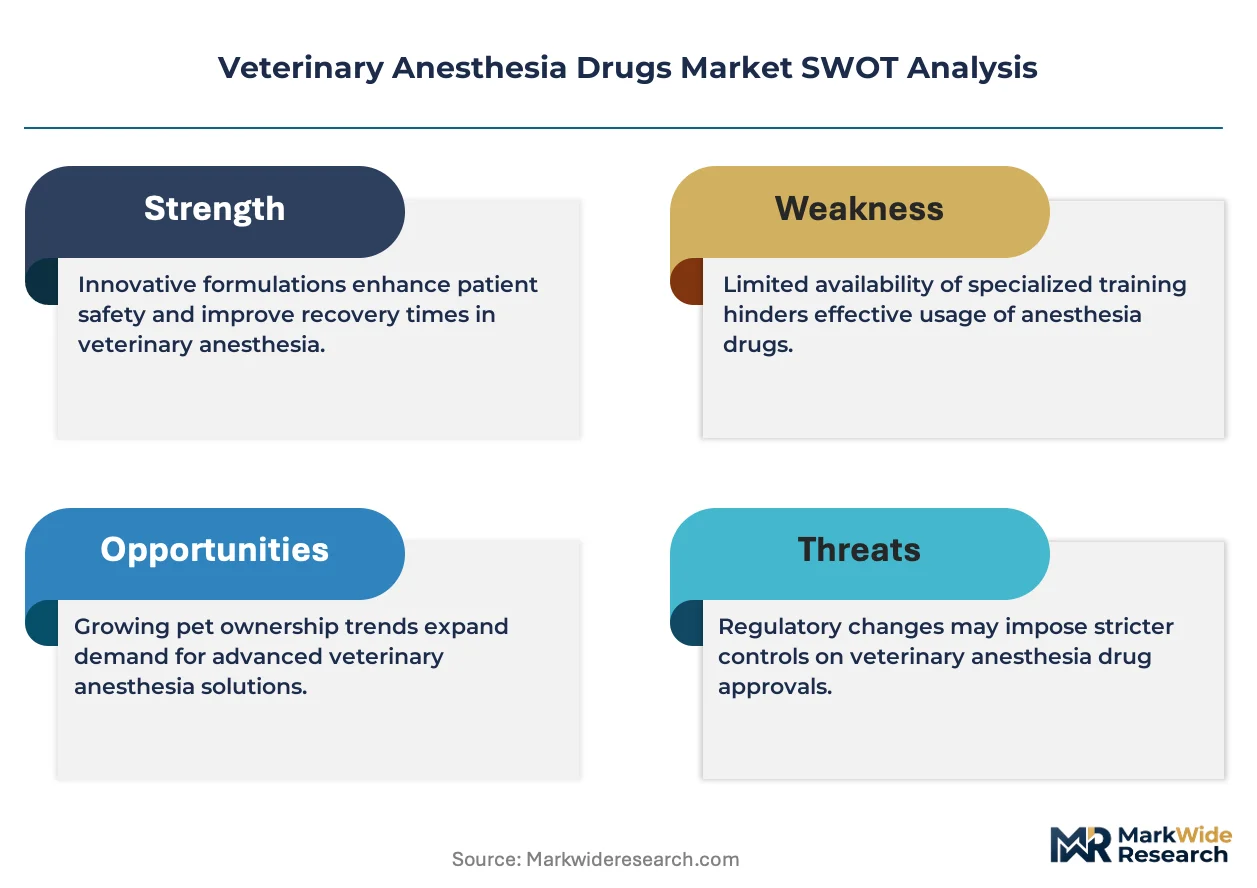
Veterinary anesthesia drug markets are being restructured by the acute shortage of board-certified veterinary anesthesiologists, which concentrates purchasing power in a shrinking pool of referral institutions capable of supporting complex multimodal protocols.
Growth Catalysts
- Specialty surgical volume expansion:Orthopedic and soft-tissue procedure growth at North American and Western European referral hospitals is pulling demand for inhalation anesthesia infrastructure and advanced monitoring.
- EMA CVMP regulatory harmonization:Streamlined centralized marketing authorization procedures are reducing time-to-market for novel anesthetic formulations across EU member states.
- Multimodal protocol adoption:Integration of local anesthetics and analgesic synergists into standard practice is expanding the adjuvant product margin pool beyond core induction agents.
Market Restraints
- Controlled substance scheduling volatility:National drug enforcement agencies in multiple jurisdictions are reviewing ketamine and tiletamine classifications, creating formulation strategy uncertainty and distribution security cost escalation.
- Gas anesthesia infrastructure capex barriers:General practice settings face prohibitive capital requirements for waste gas scavenging systems and calibrated vaporizers, limiting inhalation agent penetration.
- Species-specific pharmacovigilance complexity:ISO 10993 biocompatibility frameworks and target animal safety studies multiply compliance layers, extending development timelines for multi-species indications.
Strategic Opportunities
- Japan's underpenetrated exotic species segment:Zoological and aquaculture anesthesia applications remain underserved by incumbent canine-feline focused portfolios, creating white space for specialized formulations.
- Telemedicine-integrated anesthesia consultation:Remote perioperative monitoring support is enabling general practitioners to adopt intermediate-complexity protocols previously restricted to referral settings.
- FDA CVM incentive pathways:Minor use and minor species (MUMS) designation programs are accelerating approval timelines for anesthetics targeting equine and exotic veterinary applications.
Industry Challenges
- Veterinary anesthesiologist training pipeline constraints:Residency program capacity limitations at American College of Veterinary Anesthesia and Analgesia-accredited institutions are failing to match referral hospital demand growth.
- Legacy equipment interoperability:Digital anesthesia record systems face integration friction with existing practice management software, delaying real-time pharmacokinetic monitoring adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Anesthesia Drugs Market |
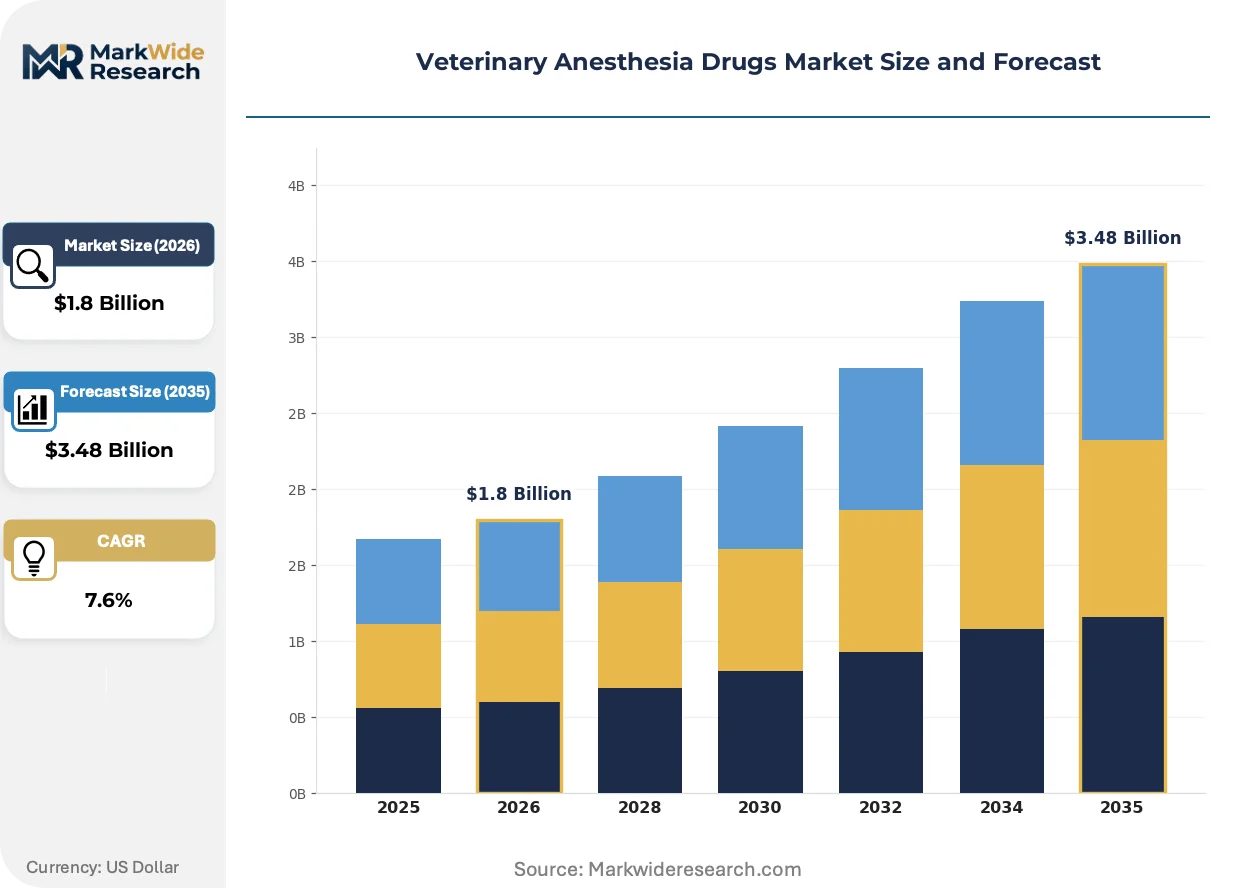
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Anesthetics, Inhalation Anesthetics, Sedatives, Adjuvants Animal Type: Dogs, Cats, Horses, Exotic Animals Route of Administration: Intravenous, Intramuscular, Inhalation, Subcutaneous End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Rescue Organizations |
| Companies Covered | Bayer Animal Health, Dechra Pharmaceuticals, Zoetis, Ceva Santé Animale, Virbac, Merck Animal Health, Vetoquinol, Norbrook Laboratories, Elanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Anesthesia Drugs Market Evolving Landscape
Pharmaceutical formulation science and digital perioperative monitoring are converging to reshape how anesthesia depth is managed across species, with particular emphasis on reducing recovery variability and improving analgesic precision.
Target-controlled infusion (TCI) systems calibrated for veterinary species are fragmenting the traditional bolus-dominant administration paradigm. Large veterinary hospital groups in Germany and the United States are piloting propofol and alfentanil TCI protocols adapted from human anesthesia. This technology is fragmenting competitive positioning between practices capable of precision pharmacokinetic delivery and those reliant on conventional weight-based dosing.
REACH authorization requirements for fluorinated greenhouse gases are tightening sevoflurane manufacturing and import protocols across the European Union. The F-Gas Regulation phasedown schedule is forcing reformulation investments and alternative carrier gas exploration. German and French veterinary distributors are responding by diversifying supplier relationships and building strategic inventories of non-fluorinated alternatives.
Consolidation among corporate veterinary groups is compressing vendor selection cycles and standardizing formularies across multi-site networks. Independent specialty practices face exclusion from preferred pricing tiers as purchasing committees centralize anesthesia drug procurement at the corporate level. This pattern is most visible in the United States, where Mars Veterinary Health and Vetcor networks now control substantial referral hospital anesthesia volume.
Veterinary Anesthesia Drugs Market Segmentation
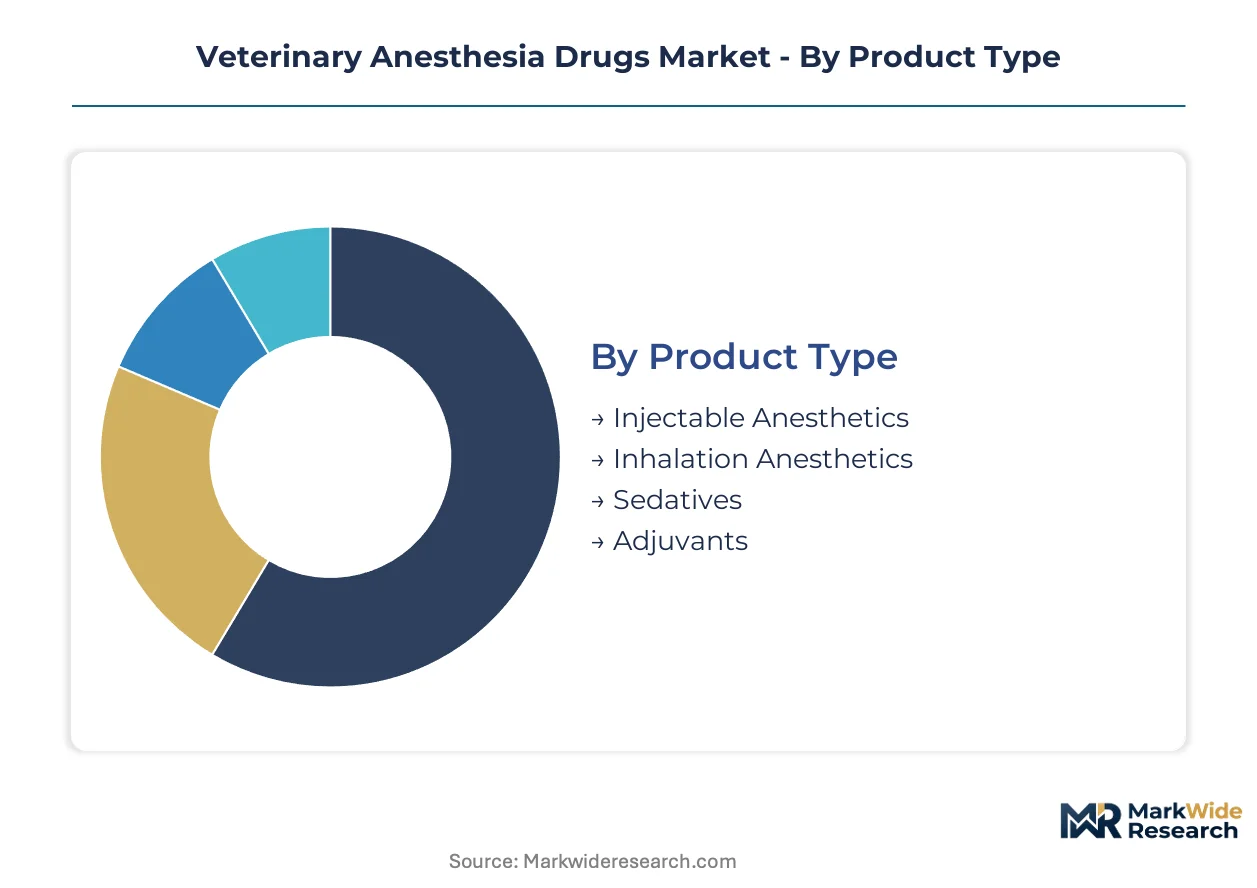
Segmentation in veterinary anesthesia drugs reflects divergent clinical workflows across practice settings and species metabolic complexity. Product formulations, administration routes, and end-user capabilities determine pricing architecture and regulatory pathway selection.
Product Type:
Injectable anesthetics dominate domestic procurement across general practices lacking gas infrastructure, while inhalation agents concentrate in export-led supply chains serving tertiary referral networks.
- Injectable Anesthetics:Propofol, ketamine, and medetomidine formulations enable rapid induction without vaporizer capital expenditure. Demand concentrates in United States general practices performing routine dental and soft-tissue procedures where multimodal injectable protocols substitute for inhalation infrastructure. Controlled substance scheduling volatility for ketamine disrupts formulation stability.
- Inhalation Anesthetics:Isoflurane and sevoflurane require calibrated vaporizers and active waste gas scavenging systems. Germany's REACH F-Gas Regulation compliance costs are compressing sevoflurane manufacturing margins and accelerating alternative carrier gas exploration.
- Sedatives:Alpha-2 agonists and benzodiazepines provide pre-anesthetic calming and muscle relaxation.
- Adjuvants:Local anesthetics and analgesic synergists expand multimodal protocol adoption.
Injectable anesthetics command the established base. The steepest expansion runs through adjuvants as multimodal pain management protocols gain veterinary adoption.
Animal Type:
Canine-feline applications generate volume scale, while exotic species segments reward specialized pharmacology expertise with premium pricing tiers.
- Dogs:Largest procedural volume drives standardized dosing tables and automated infusion pump compatibility. United States specialty hospitals are piloting target-controlled propofol protocols adapted from human anesthesia, fragmenting competitive positioning between precision-capable and conventional practices.
- Cats:Unique hepatic glucuronidation limitations necessitate species-specific formulation adjustments. Japan's aging feline population is expanding chronic pain management demand beyond acute surgical applications.
- Horses:Field anesthesia requirements favor injectable induction and recovery management.
- Exotic Animals:Zoological and aquaculture applications remain underserved by mainstream portfolios.
Dogs anchor volume concentration. Exotic animals present the steepest margin expansion opportunity through FDA CVM MUMS pathway acceleration.
Route of Administration:
Intravenous delivery commands referral hospital premium positioning, while intramuscular and subcutaneous routes sustain field veterinary accessibility.
- Intravenous:Enables precise titration and rapid redistribution termination. Germany's large veterinary hospital groups are integrating TCI systems for propofol and alfentanil delivery, displacing weight-based bolus conventions.
- Intramuscular:Tiletamine-zolazepam combinations serve remote equine and wildlife immobilization where vascular access is impractical.
- Inhalation:Waste gas scavenging mandates under OSHA and national occupational health regulations limit general practice penetration.
- Subcutaneous:Reserved for small-volume pre-anesthetic medications and local anesthetic infiltration.
Intravenous administration dominates revenue capture. Inhalation routes face infrastructure cost barriers despite superior control characteristics.
End User:
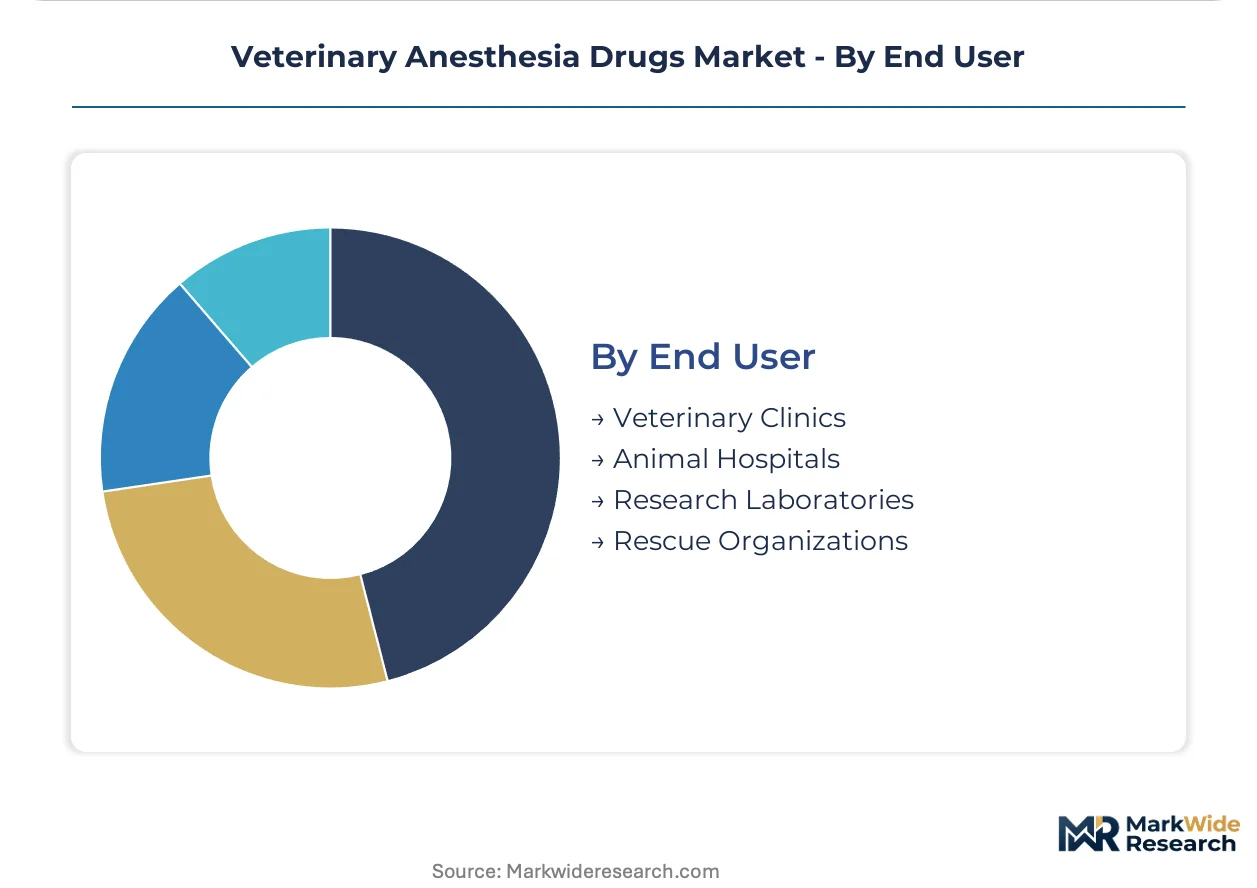
Animal hospitals consolidate purchasing power through corporate formulary standardization, while research laboratories sustain specialized compound demand.
- Veterinary Clinics:General practice settings favor injectable protocols and limited monitoring equipment. United States independent clinics face exclusion from preferred pricing tiers as Mars Veterinary Health and Vetcor networks centralize procurement.
- Animal Hospitals:Tertiary referral institutions perform complex orthopedic and soft-tissue surgeries requiring inhalation anesthesia infrastructure and board-certified anesthesiologist staffing.
- Research Laboratories:GLP-compliant pharmacokinetic studies and toxicology protocols demand batch-certified compounds with documented purity specifications.
- Rescue Organizations:Field sterilization campaigns prioritize cost-minimized ketamine-xylazine combinations.
Animal hospitals concentrate premium product demand. Research laboratories sustain the most specialized formulation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine guidelines anchor the United States as the dominant geography, while EMA CVMP harmonization and Japan's PMDA frameworks shape parallel development corridors across Western Europe and East Asia.
United States
Referral-grade veterinary hospitals in metropolitan corridors drive inhalation anesthesia infrastructure investment. FDA CVM incentive pathways for minor use and minor species accelerate equine and exotic drug approvals. The Greater Boston and Research Triangle clusters concentrate academic veterinary medical centers where Merck Animal Health maintains exclusive supply agreements.
Germany
Large veterinary hospital groups pilot target-controlled infusion systems for propofol delivery. REACH F-Gas Regulation compliance costs compress sevoflurane manufacturing margins and force alternative carrier gas exploration. The Munich and Hanover veterinary clusters standardize multimodal protocols across corporate practice networks.
Japan
Aging feline populations expand chronic pain management demand beyond acute surgical applications. PMDA species-specific pharmacovigilance requirements extend development timelines for multi-species indications. Tokyo and Osaka metropolitan veterinary hospitals concentrate premium adjuvant product procurement.
United Kingdom
Specialty surgical volume expansion at referral institutions pulls demand for advanced monitoring equipment. EMA CVMP centralized marketing authorization procedures reduce time-to-market for novel formulations. The London and Liverpool veterinary corridors consolidate purchasing through corporate formulary standardization.
France
Equine field anesthesia requirements sustain demand for injectable sedative-anesthetic combinations. ANSM batch consistency enforcement shapes product development timelines for manufacturers seeking multi-jurisdiction registration. The Lyon and Normandy veterinary clusters specialize in large-animal anesthesia applications.
Veterinary Anesthesia Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the veterinary anesthesia drugs market. The structure concentrates around integrated pharmaceutical portfolios and specialized niche formulations rather than fragmented commodity supply. Three archetypes dominate: diversified animal health conglomerates with full anesthesia-analgesia portfolios, mid-cap specialists in exotic or equine species segments, and regional distributors with exclusive academic medical center relationships. Competitive moves center on corporate formulary standardization through multi-site network contracts and regulatory pathway acceleration for minor species designations.
Among the diversified conglomerates, Zoetis and Merck Animal Health exemplify scale-driven positioning through integrated portfolio breadth and academic distribution density. Dechra Pharmaceuticals occupies a specialist tier focused on injectable combinations outside the canine-feline mainstream. These three anchors represent divergent strategic bets: full-service loyalty programs versus defensible species niches versus exclusive institutional supply relationships.
| Leading Market Players |
|---|
| Bayer Animal Health |
| Dechra Pharmaceuticals |
| Zoetis |
| Ceva Santé Animale |
| Virbac |
| Merck Animal Health |
| Vetoquinol |
| Norbrook Laboratories |
| Elanco |
| Others |
Value Network & Pricing Analysis
Multi-year corporate formulary agreements lock in supply access and price visibility for veterinary anesthesia drugs across Mars Veterinary Health and Vetcor network hospitals. These contracts bundle inhalation agents, injectable induction drugs, and adjuvant synergists under tiered volume commitments that compress procurement cycles and standardize cost baselines across metropolitan referral clusters in the United States and Germany.
Pricing Analysis
Geographic price spreads of 15-25% separate United States metropolitan referral hospitals from rural general practices purchasing identical propofol and isoflurane formulations. Three-tier pricing structure across premium, standard, and economy levels segments by anesthesia infrastructure investment and board-certified staffing density. Cost compression in the economy tier is intensifying because ketamine scheduling volatility disrupts formulation stability and forces security compliance cost pass-through. Corporate hospital groups exhibit lowest price sensitivity due to centralized procurement leverage, while independent rescue organizations face acute budget constraints on ketamine-xylazine combinations.
Supply Chain Analysis
Strategic inventory buffers of 90-120 days now cover sevoflurane and propofol active pharmaceutical ingredients across German and French veterinary distributors responding to REACH F-Gas Regulation phasedown uncertainty. Manufacturing concentration in the United States, Germany, and India supplies isoflurane, propofol, and ketamine base materials. Raw material dependencies on fluorinated ether intermediates, soybean oil emulsion carriers, and alpha-2 agonist precursors create formulation vulnerability. Single-source vulnerability in fluorinated greenhouse gas manufacturing threatens sevoflurane continuity. Distribution runs through exclusive academic medical center agreements and corporate network direct contracts, bypassing traditional wholesale channels for premium product tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary anesthesia drug markets reward service-attach revenue models where remote perioperative monitoring subscriptions and TCI system calibration contracts expand faster than core pharmaceutical sales. Anesthesia consultation telemedicine layers generate recurring income streams that compound customer lifetime value beyond transactional drug procurement.
For Market Incumbents: Compound formulary stickiness through integrated anesthesia-analgesia-adjuvant bundles that raise switching costs for corporate veterinary groups. Defend against Dechra Pharmaceuticals' equine-exotic niche expansion by accelerating FDA CVM MUMS pathway investments for minor species indications. Prioritize backward integration into propofol emulsion manufacturing to capture margin compression from soybean oil carrier volatility. For New Entrants and Emerging Players: Lead with Japan's underpenetrated exotic species segment where zoological and aquaculture applications lack specialized formulations from canine-feline focused incumbents. Target telemedicine-integrated anesthesia consultation platforms that enable general practitioners to adopt intermediate-complexity protocols. Pursue regulatory-first positioning through PMDA species-specific pharmacovigilance pre-submission meetings. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with defensible exotic species pharmacology expertise and established FDA CVM MUMS designation track records. Long-term viability hinges on regulatory pathway acceleration capabilities rather than commodity scale. Watch for ketamine scheduling reclassification announcements across national drug enforcement agencies as inflection indicators for formulation strategy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pathway Acceleration | FDA CVM MUMS designations compress approval timelines for equine and exotic anesthetic formulations. |
| Target-Controlled Infusion Integration | TCI system partnerships with German hospital groups displace conventional weight-based bolus conventions. |
| Telemedicine Platform Development | Remote perioperative monitoring subscriptions expand addressable market into general practice settings. |
| Alternative Carrier Gas Exploration | Non-fluorinated sevoflurane substitutes respond to REACH F-Gas Regulation manufacturing constraints. |
| Corporate Formulary Standardization | Multi-site network contracts with Mars Veterinary Health consolidate procurement at premium pricing tiers. |
Research Methodology
A spread of perspectives from veterinary anesthesiologists, pharmaceutical regulatory affairs directors, corporate veterinary group procurement officers, and academic medical center supply chain managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with anesthesia drug formulary committees and secondary validation against FDA CVM approval databases, EMA CVMP centralized marketing authorization records, and ISO 10993 biocompatibility framework documentation. Bottom-up procedure volume modeling across companion animal surgical categories triangulated with top-down pharmaceutical manufacturer revenue attribution.
Segmentation dimensions modeled span product type, animal species, route of administration, and end-user facility tier across the projection horizon. Injectable versus inhalation anesthesia infrastructure penetration, multimodal protocol adoption rates, and controlled substance scheduling volatility informed CAGR derivation through scenario-weighted probability analysis. Species-specific pharmacokinetic parameters and referral hospital staffing density served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained specialty surgical volume expansion or abrupt ketamine regulatory reclassification would require recalibration. Forecasts reflect documented assumptions regarding EMA CVMP harmonization progress and corporate veterinary consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Europe Dog Dewormers Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Mastitis Market
Veterinary
Clonorchiasis Market
Veterinary
Veterinary Excipients Market
Veterinary
Global Dog Vaccines Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Companion Animal Drugs Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Milking Salve Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Europe Veterinarians Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Compression Veterinary Bandages Market