
 Veterinary Software Market | 2026-2036
Veterinary Software Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Software Market Intelligence
The consolidation of independent veterinary clinics into large corporate hospital groups is recalibrating the procurement process for software solutions. This structural shift favors enterprise-grade platforms that offer multi-location management and standardized reporting. IDEXX Laboratories leverages its diagnostic leadership to offer deeply integrated software and hardware systems. Covetrus specializes in comprehensive supply chain and practice management platforms for these expanding networks. Meanwhile, ezyVet differentiates with its focus on cloud-native, user-friendly interfaces for specialized and emergency hospitals.
Veterinary software encompasses a suite of specialized applications designed to manage clinical and administrative functions within animal healthcare environments. These systems must support integration with diagnostic equipment, such as Picture Archiving and Communication Systems (PACS), for managing medical images. The primary purpose is to centralize patient data, streamline appointment scheduling, and automate billing and inventory. Cloud-based SaaS platforms are rapidly displacing traditional on-premise deployments due to superior accessibility and scalability. Within product types, telemedicine solutions represent the fastest-growing category, addressing client demand for remote consultations and follow-up care.
Regulatory frameworks significantly shape software design and data handling protocols. In the United States, while not directly governed by HIPAA, best practices for protecting pet owner data often mirror its stringent privacy and security rules. Across Europe, GDPR compliance is mandatory, dictating how client information is collected, stored, and processed by software vendors. The FDA's regulations on veterinary pharmaceuticals also influence the design of e-prescribing and inventory management modules. Navigating these varied international data security and prescription management standards is critical for vendors seeking to expand their footprint.
Market Dynamics
The structural consolidation of veterinary services into corporate hospital groups is the central force altering the market. This shift moves purchasing decisions from individual practitioners to centralized corporate procurement, creating demand for enterprise-grade software capable of standardizing operations across multiple locations.
Growth Catalysts
- AI-Powered Diagnostics:The integration of artificial intelligence into diagnostic workflows, particularly for analyzing medical images from PACS systems, is driving adoption of advanced software in specialty and emergency animal hospitals seeking improved clinical accuracy and efficiency.
- Pet Humanization Trend:A societal shift toward viewing pets as family members increases owner willingness to spend on advanced healthcare, which in turn necessitates more sophisticated software for managing complex treatments, detailed medical records, and multi-faceted billing.
- Data Security Mandates:Adherence to data protection regulations, such as GDPR in Europe, and the adoption of HIPAA-like best practices for client data in the United States compel clinics to upgrade from insecure legacy systems to modern, compliant software platforms.
Market Restraints
- High Subscription Costs:The total cost of ownership for premium, cloud-based SaaS platforms, including subscription fees and implementation services, remains a significant financial barrier for small, independent, or rural veterinary practices with limited operating budgets.
- Legacy Hardware Integration:Significant friction exists in integrating modern software with older, often proprietary, diagnostic equipment from a multitude of manufacturers, leading to data silos and workflow inefficiencies that deter upgrades.
- Practitioner Resistance to Change:A segment of long-standing veterinary professionals exhibits resistance to abandoning familiar paper-based or simple spreadsheet systems, slowing technology penetration in established, smaller-scale clinics.
Strategic Opportunities
- Niche Practice Specialization:Developing software modules tailored for underserved veterinary specialties, such as equine, avian, or zoological medicine, offers a significant opportunity to capture markets with unique workflow and data management requirements.
- Emerging Market Expansion:Geographic expansion into regions like Brazil and Southeast Asia, where a growing middle class is driving a surge in pet ownership, presents a major opportunity for first-mover advantage with localized and accessibly priced software.
- Insurance and Wellness Integration:There is a clear opportunity in building direct API integrations between practice management software and the ecosystems of pet insurance providers and consumer wellness apps, streamlining claims processing and enhancing client engagement.
Industry Challenges
- Data Migration Complexity:The process of migrating historical patient and financial data from disparate legacy systems into a new, unified cloud platform is a complex, costly, and operationally risky challenge for veterinary practices of all sizes.
- Interoperability Standards Gap:The absence of universally adopted data interoperability standards across veterinary software, laboratory systems, and diagnostic imaging equipment creates persistent data-sharing hurdles between different clinics and referral partners.
- Shortage of Tech-Savvy Staff:A widespread talent gap exists within veterinary clinics, with a shortage of administrative and clinical staff possessing the necessary IT skills to fully leverage the advanced features of modern practice management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Software Market |
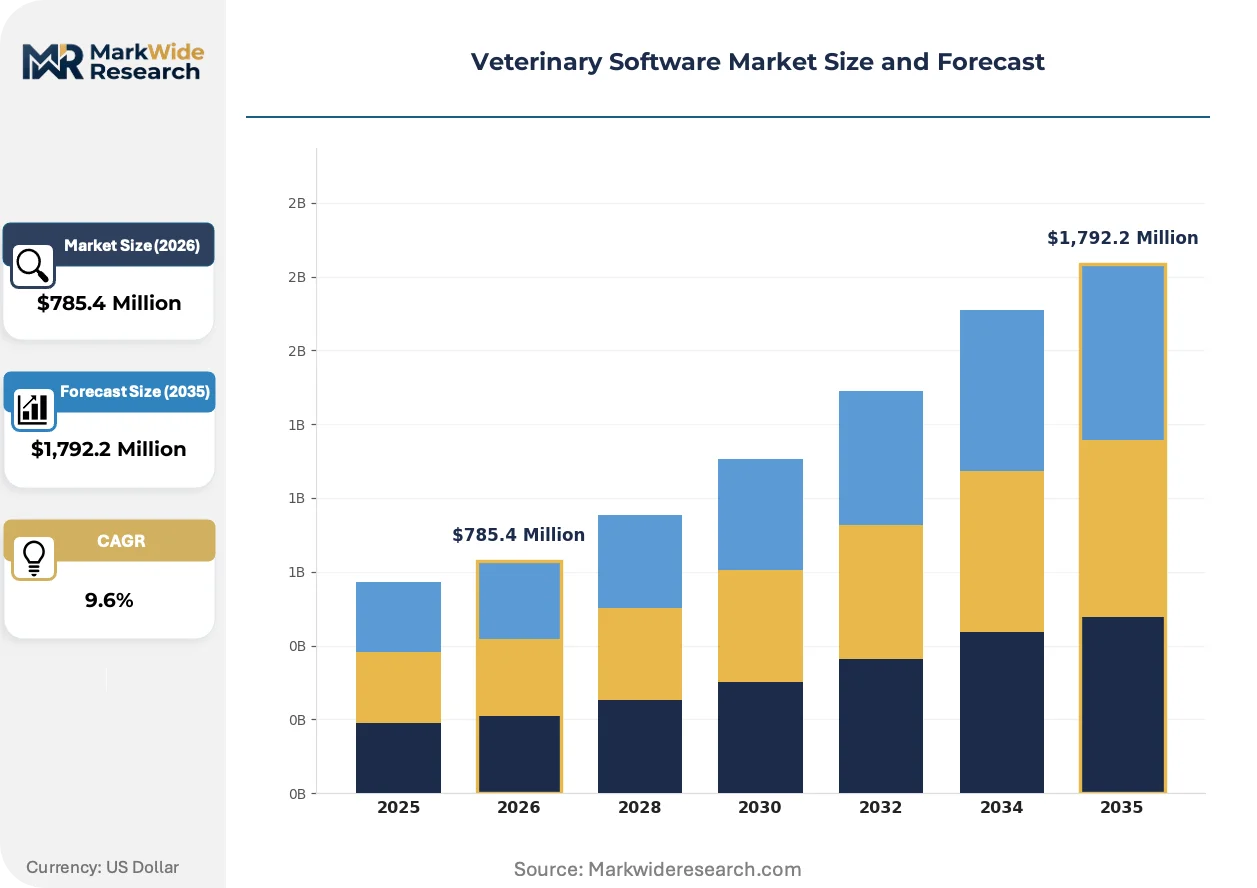
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,792.2 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Practice Management, Telemedicine Solutions, Diagnostic Software, Inventory Management, Billing Systems Application: Pet Health Records, Appointment Scheduling, Treatment Planning, Client Communication, Prescription Management End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Pet Insurance Providers, Zoos Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Applications, SaaS Platforms |
| Companies Covered | Nordhealth, DaySmart Software, IDEXX Laboratories, Provet Cloud, ezyVet, Covetrus, Patterson Companies, Animal Intelligence Software, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Software Market Strategic Shifts & Innovations
The evolution from simple digital appointment books to integrated business intelligence platforms defines the current market trajectory. This transformation is driven by the need for data-driven decision-making in an increasingly competitive veterinary landscape and by client expectations for seamless digital services.
Artificial intelligence is being embedded directly into practice management systems to provide predictive analytics. Large, multi-location hospital groups are the primary adopters, seeking to standardize care protocols and optimize financial performance across their networks. This advanced analytical capability is unifying clinical, operational, and financial data streams into cohesive dashboards that support strategic decision-making on everything from inventory management to staffing levels.
Europe's General Data Protection Regulation (GDPR) has profoundly influenced software design. The regulation mandates strict controls over how personal data of pet owners is collected, stored, and managed. Consequently, SaaS vendors are compelled to engineer features for explicit consent management, data portability, and client data deletion, with non-compliance carrying significant financial penalties.
Client demand for consumer-grade digital convenience is altering clinic operations. This behavioral shift is steadily replacing traditional phone calls for appointments and inquiries with self-service online portals and dedicated mobile applications. Through these platforms, clients can book visits, approve treatment estimates, access their pet's medical records, and order prescription refills, a trend most visible in urban and suburban practices in North America.
Veterinary Software Market Segmentation
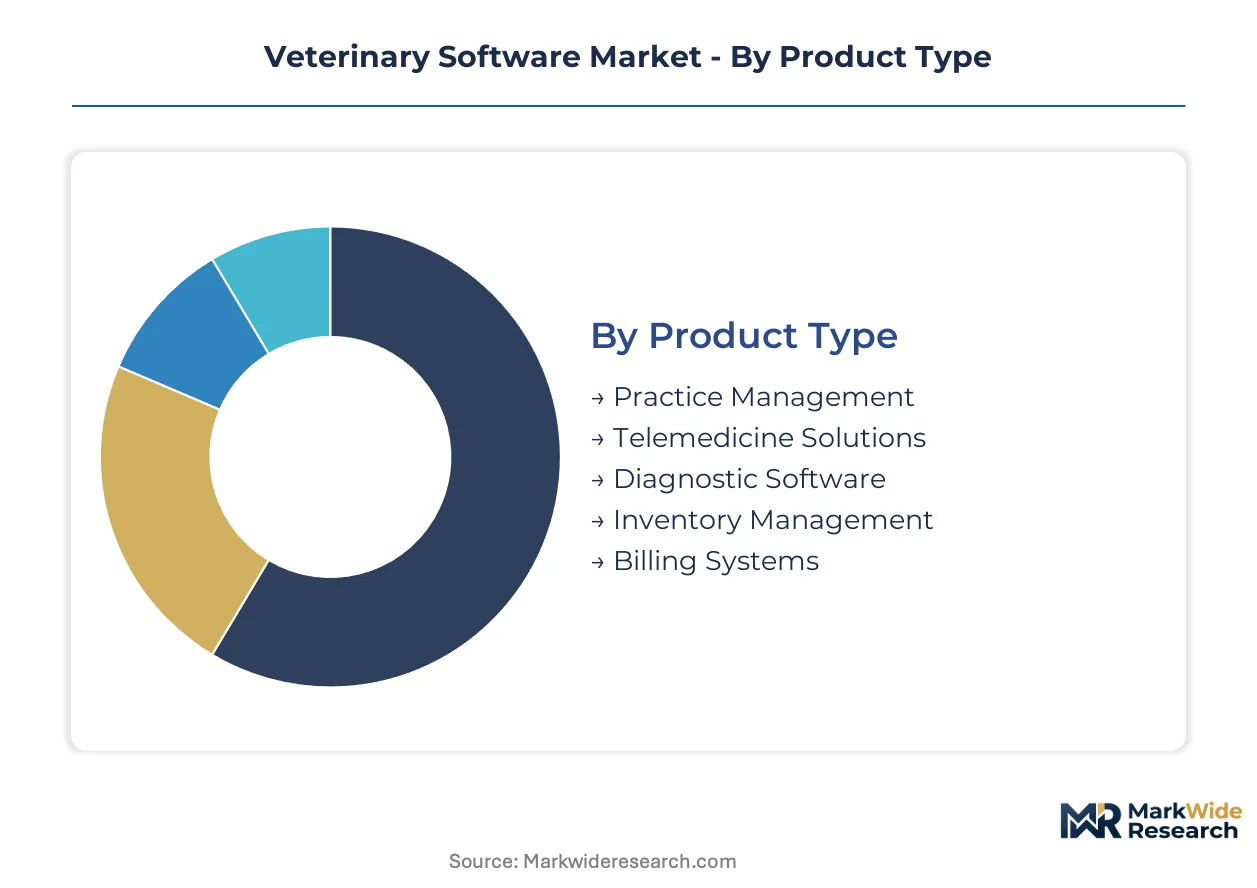
The Veterinary Software Market segmentation reflects the diverse operational needs and technological preferences across animal healthcare environments. Understanding these distinct segments is crucial for vendors to tailor solutions addressing specific clinical workflows and administrative challenges. This granular view highlights areas of concentrated demand and emerging innovation within the sector.
Product Type:
Buyers differentiate based on core functionality, from comprehensive management platforms to specialized diagnostic tools.
- Practice Management:These systems form the operational backbone for practices, integrating patient data, appointments, and billing. Demand concentrates in corporate hospital groups standardizing operations across locations.
- Telemedicine Solutions:These platforms facilitate remote consultations and digital client communication, addressing demand for convenient pet care. This segment represents the fastest-growing category.
- Diagnostic Software:Specialized applications process and analyze medical images and lab results, integrating with PACS systems.
- Inventory Management:Modules track pharmaceutical supplies, consumables, and equipment, optimizing stock levels.
- Billing Systems:Dedicated software or integrated modules manage invoicing, payment processing, and financial reporting.
Volume sits with Practice Management; growth tilts toward Telemedicine Solutions.
Application:
The specific operational tasks software automates significantly influence its utility and adoption within veterinary practices.
- Pet Health Records:These applications centralize and manage comprehensive medical histories, diagnostic results, and treatment plans. Demand is high across all practice types.
- Treatment Planning:Software modules assist veterinarians in developing, tracking, and adjusting therapeutic interventions, integrating with diagnostic data. This is critical for complex cases in specialty hospitals.
- Appointment Scheduling:Digital tools manage client appointments, staff calendars, and resource allocation, often featuring online booking.
- Client Communication:Platforms enable automated reminders, secure messaging, and educational content delivery to pet owners.
- Prescription Management:Systems generate, track, and dispense veterinary pharmaceuticals, ensuring compliance with regulatory frameworks.
The most critical operational efficiency gains stem from Pet Health Records, while Client Communication enhances client convenience.
End User:
The scale and operational complexity of the user organization dictate software solutions required for effective management.
- Animal Hospitals:These large facilities, often part of corporate groups, require enterprise-grade platforms for multi-location management and standardized reporting.
- Veterinary Clinics:Independent or smaller group practices focus on software that streamlines daily operations, manages patient data, and offers user-friendly interfaces.
- Research Institutes:Specialized software supports data collection, analysis, and management for animal studies.
- Pet Insurance Providers:Integration with practice management software streamlines claims processing and data exchange.
- Zoos:Unique software modules manage exotic animal health records, specialized diets, and breeding programs.
Large-scale operations prioritize solutions for Animal Hospitals, whereas individual practitioners benefit most from Veterinary Clinics focused software.
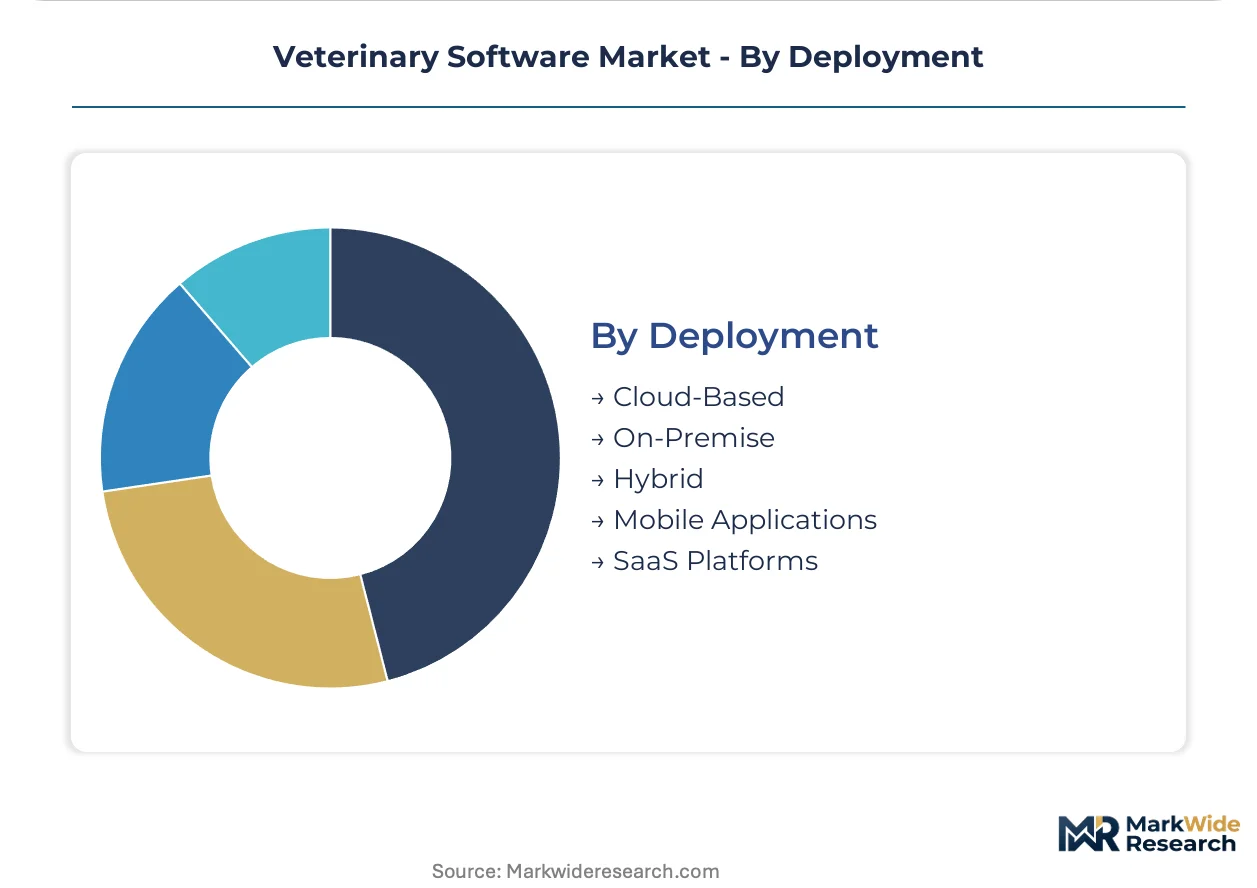
Deployment:
Software delivery models are evolving, offering varying levels of accessibility, infrastructure burden, and data security.
- Cloud-Based:These platforms deliver software as a service over the internet, providing superior accessibility, scalability, and automatic updates. Demand concentrates in practices seeking reduced IT overhead.
- SaaS Platforms:A specific type of cloud-based deployment where software is licensed on a subscription basis, managed by a third-party vendor. This model rapidly displaces traditional on-premise solutions.
- On-Premise:Traditional software installed and maintained on local servers, offering full control but higher initial investment.
- Hybrid:A combination of cloud-based and on-premise components, allowing practices to leverage benefits of both models.
- Mobile Applications:Companion apps for smartphones and tablets extending core software functionality, enabling remote access and client self-service.
Modern practices increasingly favor Cloud-Based solutions for their flexibility, moving away from On-Premise deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration for veterinary software solutions is most pronounced in the United States, reflecting a highly consolidated veterinary services industry. This market structure accelerates technology adoption, particularly for enterprise-grade platforms. Other regions also exhibit unique drivers and regulatory landscapes influencing software uptake.
United States
The United States market exhibits significant demand for advanced veterinary software, driven by the consolidation of independent clinics into large corporate groups. Best practices for protecting pet owner data often mirror HIPAA's stringent privacy and security rules. Silicon Valley in California, along with other tech hubs, drives innovation in specialized veterinary software development.
Germany
German veterinary practices increasingly seek sophisticated software to manage complex treatments and comply with strict data protection regulations. GDPR compliance is mandatory, dictating how client information is collected, stored, and processed by software vendors. Munich's vibrant tech ecosystem fosters innovation in digital health solutions tailored for animal care.
United Kingdom
Pet humanization trends in the United Kingdom fuel demand for advanced software capable of managing detailed medical records and client communication. UK GDPR and other data protection laws influence software design, ensuring secure handling of client data. London's dynamic tech sector supports the development of specialized veterinary platforms and telemedicine solutions.
Australia
Australia's veterinary software market benefits from high pet ownership rates and a focus on integrating advanced diagnostic tools. Australian Privacy Principles guide data handling protocols, compelling clinics to upgrade to compliant software platforms. Sydney's growing health tech community supports local software development for animal care, including cloud-based solutions.
Brazil
Expansion into Brazil presents a significant opportunity, driven by a growing middle class and a surge in pet ownership across major urban centers. Brazil's General Data Protection Law (LGPD) mandates client data protection, influencing localization requirements for software vendors. São Paulo's expanding tech scene attracts investment in localized veterinary software solutions, catering to this emerging market.
Veterinary Software Market Key Industry Players
United States producers anchor one tier of the veterinary software market; European specialists hold another significant position. The market structure exhibits a blend of consolidated enterprise platforms and niche solution providers. Strategic archetypes include comprehensive practice management suites, diagnostic integration experts, and cloud-native innovators. Competitive moves focus on strategic partnerships and portfolio diversification to capture market share.
Specialists in comprehensive veterinary solutions include IDEXX Laboratories, which leverages its diagnostic leadership to offer deeply integrated software and hardware systems. Covetrus focuses on providing comprehensive supply chain and practice management platforms, particularly for expanding corporate networks. ezyVet differentiates with its focus on cloud-native, user-friendly interfaces, especially for specialized and emergency hospitals.
| Leading Market Players |
|---|
| Nordhealth |
| DaySmart Software |
| IDEXX Laboratories |
| Provet Cloud |
| ezyVet |
| Covetrus |
| Patterson Companies |
| Animal Intelligence Software |
| Carestream Health |
| Others |
Cost & Logistics Intelligence
A clear performance gap exists between enterprise-grade and basic software solutions, directly influencing both pricing models and the distribution strategies of vendors.
Pricing Analysis
Volume discounts significantly reduce per-unit costs for large corporate groups, while smaller practices often face higher subscription fees. The dominant pricing model is SaaS-tiered subscription, with differentiation based on customization level and comprehensive after-sales service. Pricing softness reflects increased competition among cloud-based SaaS providers, especially for entry-level offerings. Small, independent veterinary practices are most price-sensitive, whereas large hospital groups prioritize feature sets, multi-location capabilities, and robust data integration.
Supply Chain Analysis
Regional distribution centers are critical for deploying on-premise hardware components, supporting localized implementation teams for veterinary software installations. Geographic supply for core software development concentrates in the United States, Germany, and the United Kingdom. Key dependencies include cloud infrastructure services from major providers and specialized diagnostic hardware components for integration. A structural risk involves single-source vulnerability for proprietary diagnostic equipment interfaces. Distribution runs through direct sales teams for enterprise clients and a network of value-added resellers for smaller practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Veterinary Software Market is witnessing a vertical-integration race, with players pursuing deeper integration of AI-powered diagnostic tools as a core upstream lever.
For Market Incumbents:Deploy strategic acquisitions to expand geographic reach into emerging markets like Brazil, countering the threat of localized, accessibly priced software solutions. Incumbents must invest heavily in robust data security features to comply with evolving GDPR and HIPAA-like mandates. Continued R&D in AI diagnostics integration provides a critical lever against new clinical technology entrants.
For New Entrants and Emerging Players:Veterinary associations and professional networks represent a key channel partner type for new entrants to gain credibility and market access. White-space targets include software modules for underserved specialties such as equine or zoological medicine. Cloud-native telemedicine solutions for independent clinics in Southeast Asia offer a penetrable market segment. A strong go-to-market angle involves offering user-friendly, modular solutions with flexible subscription tiers.
For Investors and Strategic Acquirers:Re-rating potential sits with companies offering comprehensive supply chain and practice management platforms, given the ongoing corporate consolidation catalyst. Long-term viability favors platforms capable of handling multi-location enterprise needs across diverse regulatory environments. Acquisition targets should include cloud-native innovators with strong API integration capabilities and a focus on specialized veterinary niches. Increased M&A activity for AI-powered diagnostic startups serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered predictive analytics module | Enhances clinical accuracy and operational efficiency for large animal hospitals. |
| Platform Integration: Seamless integration with pet insurance providers | Streamlines claims processing and improves client engagement for veterinary clinics. |
| Strategic Partnership: Collaboration with diagnostic equipment manufacturers | Ensures data interoperability and reduces legacy hardware integration friction. |
| Acquisition of Specialist Firm: Purchase of niche software for equine medicine | Captures underserved market segments with unique workflow requirements. |
| Geographic Expansion: Entry into Brazil and Southeast Asian markets | Leverages growing pet ownership and middle-class spending in emerging economies. |
Research Approach
Document review covered SEC filings, industry association reports, and academic journals, complemented by interviews with CTOs, veterinary practice managers, regulatory affairs specialists, and IT procurement officers. This approach combined primary insights from industry stakeholders with secondary validation from diverse data sources. Bottom-up data aggregation and top-down market sizing techniques were applied to ensure comprehensive coverage.
Market volume and value projections were generated using a robust analytical framework, incorporating historical trends and forward-looking indicators across the analysis window. Segmentation dimensions modeled include product type, application, end-user, deployment model, and regional adoption patterns. Compound Annual Growth Rates were calculated based on a regression analysis of market drivers and restraints, with pet ownership rates and veterinary services expenditure as key inputs.
Caveats apply where unforeseen technological breakthroughs or significant shifts in global economic conditions could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research, acknowledging potential revisions from rapid regulatory changes or unexpected shifts in pet humanization trends. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Point of Care Market
Veterinary
Mastitis Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Europe Veterinarians Market
Veterinary
Pet Cremation Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Animal Antibiotics Market
Veterinary
Veterinary Tables Market
Veterinary
Veterinary Scales Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Veterinary Excipients Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Spay and Neuter Market
Veterinary
Global Animal Intestinal Health Market