
 Europe General Aviation Market | 2026-2036
Europe General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe General Aviation Market Foresight
A capital-intensity divergence between full-airframe manufacturers and component specialists is reorganizing competitive tiers across European general aviation. Airbus SE leverages its composite-wing expertise to dominate high-end business jet platforms, while Leonardo S.p.A. anchors rotorcraft supply through its vertically integrated AgustaWestland production network. Textron Inc. competes in the light-aircraft segment with cost-efficient piston and turboprop models that sustain aftermarket revenue through proprietary parts channels.
General aviation encompasses all civil aircraft operations excluding scheduled commercial air transport, ranging from single-engine pistons with maximum takeoff weights below 5,700 kg to long-range business jets capable of transatlantic flight at Mach 0.85. These aircraft serve commercial functions including corporate transport, flight training, and emergency medical evacuation where flexibility outweighs airline economies of scale. Business jets command the dominant margin pool within the aircraft type dimension, while rotorcraft generates disproportionate aftermarket value through intensive maintenance cycles driven by component-limited time between overhauls. Air taxi services represent the fastest-expanding end user category as urban air mobility frameworks mature across regulatory jurisdictions.
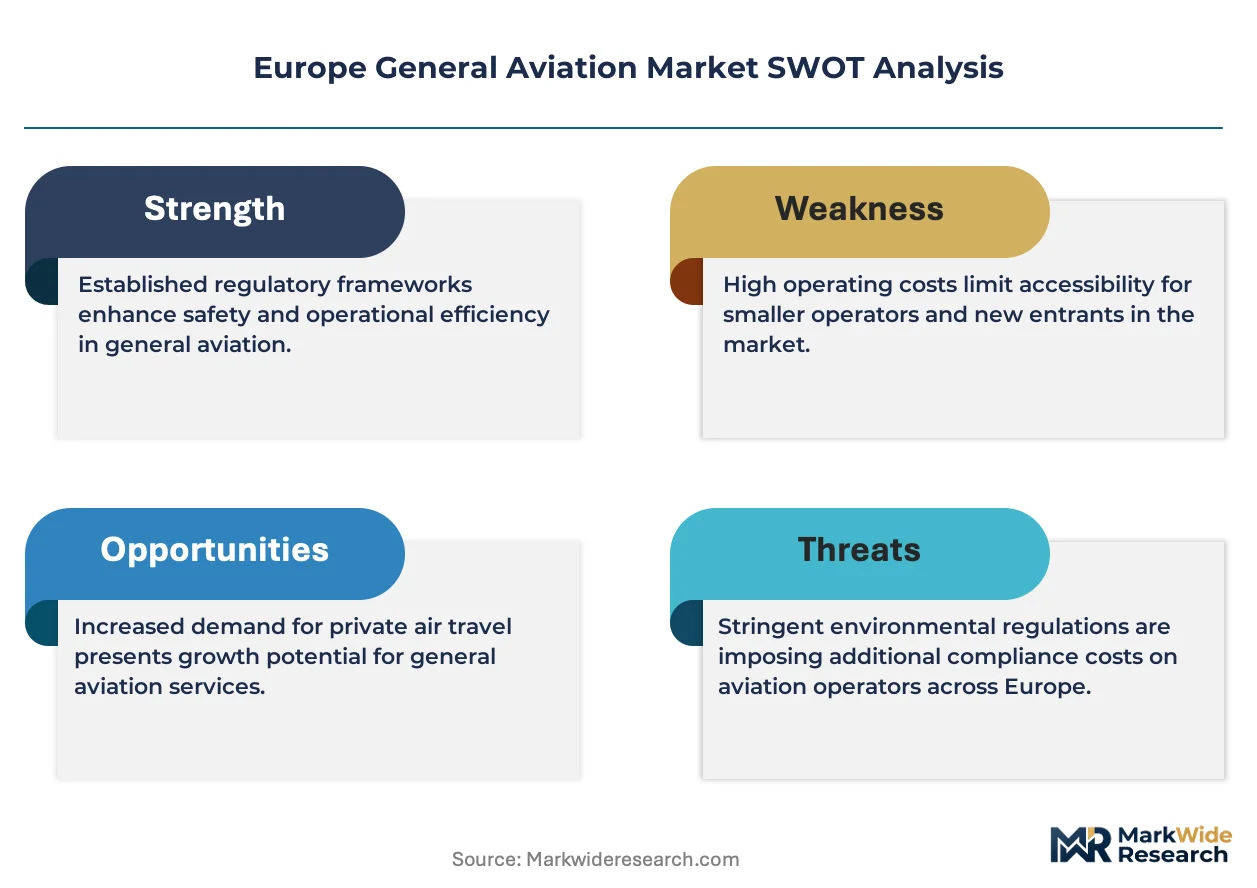
EASA's CS-23 certification standards and the EU Green Deal's SAF blending mandates shape product development trajectories, forcing airframers to redesign fuel systems for hydrotreated esters or face market access restrictions in member states. France's DGAC and Germany's LBA enforce national operating rules that layer compliance complexity onto cross-border charter operations. Stakeholders must monitor whether EASA finalizes single-pilot business jet operational credits, as this regulatory decision would reshape crew-cost economics and aircraft specification demand across European fleet renewal cycles.
Market Dynamics
EASA's CS-23 certification overhaul and the EU Green Deal's SAF mandates are forcing airframers to reengineer fuel systems and propulsion architectures, compressing development timelines while opening retrofit revenue streams for compliant platforms.
Growth Catalysts
- Urban air mobility frameworks:Regulatory pilots in Germany and France are validating eVTOL operational concepts, pulling demand toward next-generation air taxi platforms.
- EASA SAF compatibility mandates:The EU Green Deal's blending requirements are redirecting OEM engineering resources toward hydrotreated ester propulsion retrofits.
- Light-aircraft manufacturing corridor:Switzerland's Stans region anchors Pilatus-centered supply chains that concentrate specialized aerostructures talent and composite fabrication capacity.
Market Restraints
- SAF feedstock cost volatility:Hydrotreated vegetable oil and Fischer-Tropsch synthetic paraffin prices fluctuate with agricultural commodity markets, squeezing operator fuel budgets.
- Powertrain supplier concentration:Turboprop engine production concentrates among three Western manufacturers, creating single-source vulnerability for European airframers.
- Single-pilot operational credit delays:EASA's pending certification decision on reduced-crew business jet operations extends fleet renewal uncertainty for charter operators.
Strategic Opportunities
- Eastern European charter underpenetration:Poland and Romania show minimal business jet density relative to GDP, presenting greenfield demand for fractional ownership models.
- Electrified propulsion convergence:Hybrid-electric architectures combining turbine generators with distributed electric motors are opening new airframe design space for sub-19 seat platforms.
- Direct airframe procurement channels:Digital sales platforms are disintermediating traditional broker networks, compressing transaction costs for light-aircraft buyers.
Industry Challenges
- Composite repair technician scarcity:Carbon fiber airframe maintenance requires specialized certification that outpaces vocational training pipeline output.
- CS-23 amendment compliance timelines:Recertification of existing type certificates for crashworthiness and icing protection standards demands multi-year engineering commitments.
- Legacy avionics integration friction:New digital flight decks must interface with analog-era sensor architectures, complicating retrofit certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe General Aviation Market |
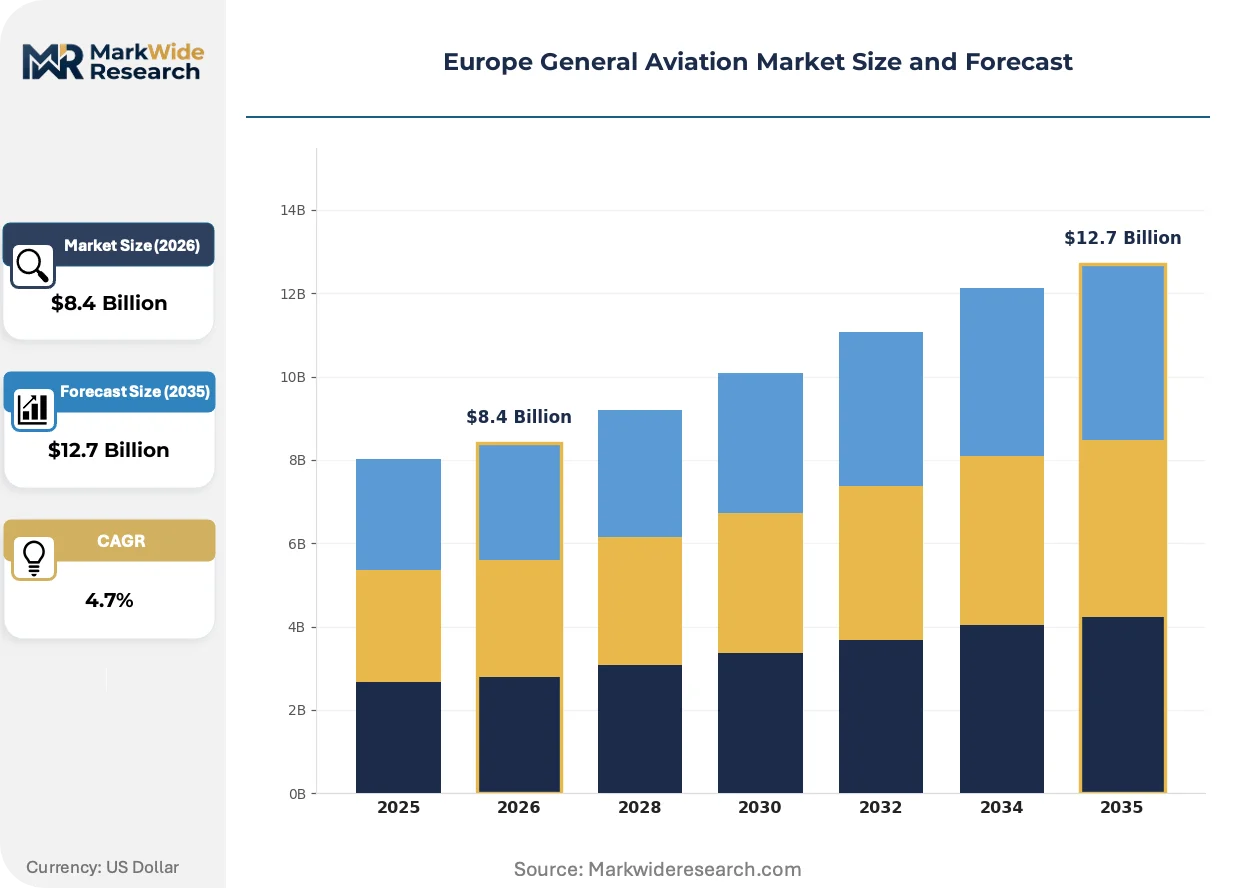
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fixed-Wing, Rotorcraft, Business Jets, Light Aircraft End User: Private Operators, Flight Schools, Air Taxi Services, Government Agencies Application: Aerial Surveying, Personal Travel, Emergency Services, Charters Service Type: Maintenance, Pilot Training, Charter Services, Aircraft Management |
| Companies Covered | Airbus SE, Leonardo S.p.A., Bombardier Inc., General Dynamics Corporation, Embraer, Dassault Aviation, Pilatus Aircraft Ltd., Saab AB, Textron Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe General Aviation Market Shifts & Advancements
Propulsion electrification and digital flight control architectures are displacing mechanical systems across the European general aviation value chain, while regulatory pressure on emissions accelerates technology substitution cycles.
Hybrid-electric propulsion is displacing conventional turboprop configurations in the 9-19 seat segment. Regional air taxi operators in Germany are flight-testing battery-assisted turbine systems for 2025 service entry. This displacement is compressing the addressable market for pure piston and turboprop powertrains below 1,500 shaft horsepower.
The EU Green Deal's SAF blending mandates are forcing fuel system redesigns across all new type certifications. Airframers must demonstrate compatibility with hydrotreated esters and synthetic paraffinic kerosene blends up to 50% by volume. Business jet platforms with legacy fuel tank sealants face accelerated obsolescence unless retrofit programs reach completion before 2030 enforcement windows.
Charter procurement is fragmenting toward on-demand digital marketplaces that bypass traditional fixed-base operator relationships. Corporate flight departments in France and Switzerland are adopting app-based booking platforms that aggregate fractional fleet availability. This channel shift concentrates purchasing power among platform operators while squeezing independent FBO margins across Alpine corridor hubs.
Europe General Aviation Market Segmentation
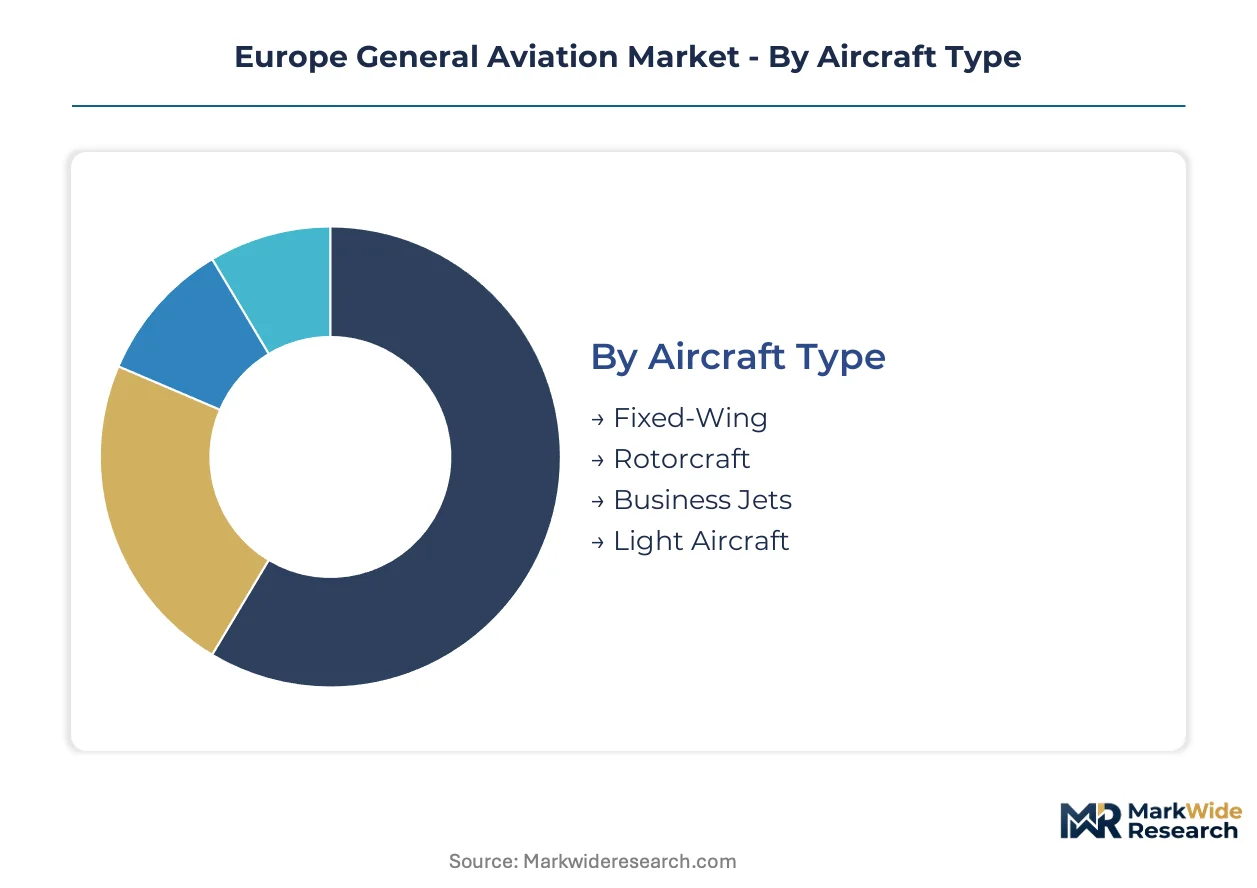
Segmentation in European general aviation reveals how regulatory boundaries reshape competitive boundaries across aircraft categories and service tiers. EASA certification classes and national operating rules fragment addressable markets, forcing suppliers to build distinct compliance capabilities for each segment cluster.
Aircraft Type:
EASA's CS-23 and CS-25 certification partitions create divergent engineering cost structures across airframe categories, with crashworthiness and icing protection standards tightening fastest for higher-weight platforms.
- Business Jets:Twin-turbine platforms certified under CS-25 standards dominate transcontinental corporate transport. Demand concentrates in Germany's Rhine-Main corridor and Paris-Le Bourget axis where fractional ownership programs expand fleet access without full capital commitment.
- Light Aircraft:Single-engine pistons and light turboprops below 5,700 kg MTOW serve flight training and personal mobility under streamlined CS-23 rules. Switzerland's Stans manufacturing cluster anchors European supply for Pilatus and composite aerostructure subcontractors.
- Fixed-Wing:Encompasses both certified and permit-to-fly categories spanning ultralights through utility turboprops. French DGAC maintains distinct national microlight regulations that layer complexity onto cross-border operations.
- Rotorcraft:Helicopter platforms face component-limited time-between-overhaul cycles that intensify aftermarket revenue capture. Leonardo's AgustaWestland network dominates European production for emergency medical and offshore transport missions.
Business Jets handles the majority of throughput; Light Aircraft is gaining share fastest as training demand rebounds post-pandemic.
End User:
Customer procurement sophistication varies sharply across operator types, with institutional buyers leveraging fleet-scale maintenance contracts while individual owners prioritize capital efficiency.
- Air Taxi Services:Urban air mobility operators in Germany and France are flight-testing eVTOL platforms for regulatory pilot programs. Berlin and Paris regulatory sandboxes validate operational concepts that pull demand toward next-generation distributed electric propulsion.
- Private Operators:High-net-worth individuals and family offices acquire aircraft through management companies that bundle crew, maintenance, and hangar services. Charter revenue offsets fixed costs for underutilized assets across Alpine corridor hubs.
- Flight Schools:Ab-initio training demand concentrates in Spain and Poland where operating costs undercut Northern European competitors. EASA's standardized licensing framework enables cross-border student mobility.
- Government Agencies:State flight departments and police aviation units procure through national tender frameworks. Italian Guardia di Finanza and French Gendarmerie operate specialized surveillance-configured fleets.
Private Operators commands the largest installed base; Air Taxi Services is expanding most quickly as regulatory frameworks mature.
Application:
Mission profiles determine equipment specifications and operating cost structures, with commercial applications demanding higher dispatch reliability than personal use cases.
- Charters:On-demand corporate transport generates premium yields through broker networks and emerging digital marketplaces. French and Swiss flight departments aggregate fractional fleet availability through app-based booking platforms.
- Emergency Services:Air ambulance and search-rescue operations require all-weather capability and rapid dispatch windows. Mountain rescue services across the Alps maintain dedicated helicopter fleets for high-altitude extraction.
- Aerial Surveying:LiDAR and multispectral imaging missions demand stable flight envelopes at low speeds. Geospatial contractors in Scandinavia operate specialized high-wing platforms with camera belly pods.
- Personal Travel:Owner-flown piston singles serve point-to-point mobility for time-flexible travelers. German private pilot license holders access dense airfield infrastructure across federal states.
Charters generates the dominant revenue pool; Emergency Services shows the steepest equipment upgrade cycle as night-vision and hoist capabilities standardize.
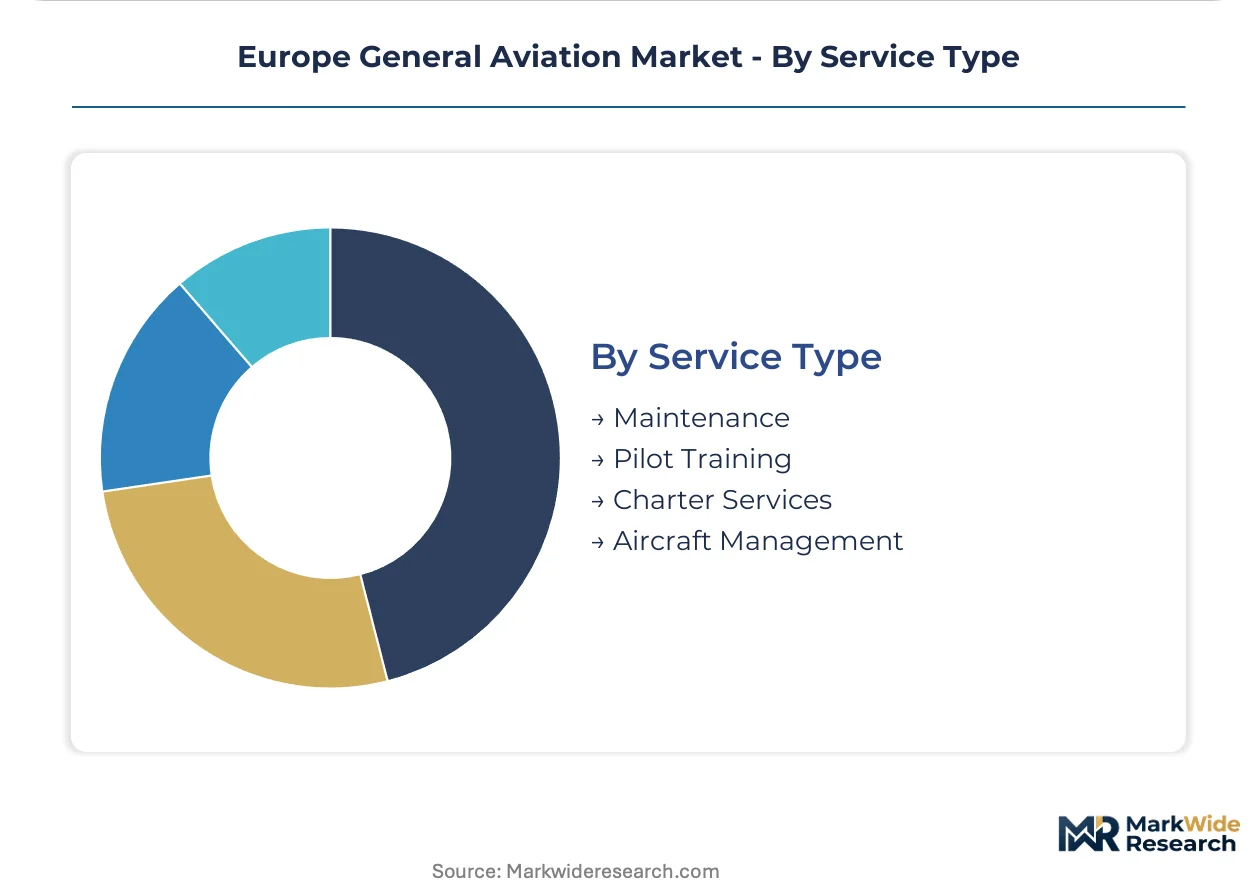
Service Type:
Aftermarket value capture concentrates in recurring revenue streams where regulatory mandates create captive demand for approved maintenance organizations.
- Maintenance:Continuing airworthiness management requires EASA Part-145 certification for structural and engine work. Composite repair technician scarcity in France and Germany extends turnaround times for carbon fiber airframe damage.
- Charter Services:Aircraft management companies bundle crew provision, flight planning, and regulatory compliance for owner-flown assets. Revenue splits between fixed monthly fees and hourly utilization charges.
- Pilot Training:Type rating instruction and recurrent simulator sessions concentrate at dedicated training centers. Lufthansa Aviation Training and CAE operate full-flight simulators for business jet platforms at European hubs.
- Aircraft Management:Technical administration of maintenance programs, registration, and resale preparation. Swiss fiduciary structures attract international owners seeking neutral-flag registry advantages.
Maintenance absorbs the largest share of lifecycle spend; Pilot Training is climbing the fastest as simulator-based instruction displaces airborne hours for currency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Switzerland's Stans manufacturing corridor, while cost-sensitive charter demand migrates toward Eastern European operating bases. Germany and France capture premium business jet utilization through Rhine-Main and Paris-Le Bourget infrastructure. Regulatory divergence between EASA harmonization and national operating rules fragments cross-border fleet deployment.
Germany
Business jet charter demand from private operators expands through the Rhine-Main corridor, with Frankfurt-Egelsbach serving as the dominant fractional ownership hub. Germany's LBA enforces national operating rules that layer compliance complexity onto cross-border operations. The Bavarian aerospace cluster around Munich anchors maintenance, repair, and overhaul capacity for CS-25 certified platforms.
France
Corporate flight departments concentrate around Paris-Le Bourget, generating premium yields through broker networks and emerging digital marketplaces. France's DGAC maintains distinct national microlight regulations that complicate cross-border ultralight operations. The Provence-Alpes-Côte d'Azur corridor sustains Mediterranean charter demand through seasonal private aviation traffic.
Switzerland
Light-aircraft manufacturing concentrates in the Stans corridor, where Pilatus anchors regional supply chains and specialized aerostructures talent pools. Swissmedic and BAZL coordinate airworthiness certification with EU mutual recognition agreements. The Alpine region's fiduciary structures attract international owners seeking neutral-flag registry advantages for aircraft management.
United Kingdom
Business aviation demand concentrates in London/Southeast flight departments, with Biggin Hill and Farnborough serving corporate transport missions. The UK CAA operates independently from EASA post-Brexit, creating dual certification requirements for fleet operators. Scotland maintains specialized helicopter capacity for offshore energy transport in the North Sea basin.
Poland
Minimal business jet density relative to GDP presents greenfield demand for fractional ownership models and cost-efficient charter entry points. Poland's national aviation authority aligns with EASA regulatory frameworks while maintaining sovereign enforcement discretion. The Warsaw-Łódź corridor develops MRO capacity to capture eastward fleet migration from Western European operating bases.
Europe General Aviation Market Competitive Landscape
Concentration sits with full-airframe manufacturers possessing composite-wing expertise and vertically integrated rotorcraft networks. The market structures around three tiers: diversified aerospace conglomerates with defense crossover, specialized business jet and light-aircraft pure-plays, and component specialists feeding upstream assembly. Dominant competitive moves include propulsion retrofit programs for SAF compliance and digital sales platform deployment to disintermediate traditional broker networks.
Among diversified European aerospace conglomerates, Airbus SE exemplifies the composite-intensive platform tier, while Leonardo S.p.A. represents vertically integrated rotorcraft production. Pilatus Aircraft Ltd. occupies the specialized light-aircraft manufacturer position, anchoring Switzerland's Stans manufacturing corridor. These three entities collectively illustrate how engineering depth and regulatory compliance capabilities determine competitive positioning across EASA certification classes.
| Leading Market Players |
|---|
| Airbus SE |
| Leonardo S.p.A. |
| Bombardier Inc. |
| General Dynamics Corporation |
| Embraer |
| Dassault Aviation |
| Pilatus Aircraft Ltd. |
| Saab AB |
| Textron Inc. |
| Others |
Supply & Pricing Matrix
Sustainable aviation fuel substitution for conventional Jet-A is redrawing procurement geography across European general aviation, compressing margins for operators while elevating pricing power for hydrotreated ester suppliers in Northwestern Europe. This feedstock transition simultaneously concentrates supply around Rotterdam-Amsterdam refining corridors and forces airframers to absorb retrofit certification costs that propagate through configured-to-order pricing.
Pricing Analysis
The customization-premium spread between configured-to-order business jets and standard light-aircraft platforms spans approximately three performance tiers. Price differentiation rests on CS-25 certification grade and composite airframe complexity, with EASA-mandated SAF compatibility upgrades adding engineering surcharges to new type certificates. Pricing pressure stems from SAF feedstock cost volatility that squeezes operator fuel budgets and compresses aftermarket service margins. Fractional ownership programs show highest price sensitivity due to utilization-based cost allocation, while government flight departments demonstrate lowest sensitivity given sovereign procurement frameworks.
Supply Chain Analysis
Inbound logistics costs for carbon fiber prepreg and titanium forgings have intensified through Rotterdam port congestion and constrained air freight capacity on Asia-Europe trade lanes. Manufacturing concentration centers on Switzerland, Germany, and France, with the Stans corridor anchoring specialized aerostructures talent and composite fabrication capacity. Raw material dependencies include aerospace-grade carbon fiber from Japan and the United States, plus turbine engine castings from the United Kingdom and Italy. Single-source vulnerability concentrates in turboprop powertrain supply among three Western manufacturers. Distribution runs through authorized service centers and Part-145 maintenance organizations that capture recurring aftermarket revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European general aviation rewards engineering depth over scale, with composite repair technician shortages and EASA certification expertise gaps creating durable competitive moats for incumbent specialists. Market participants must align capability investments with regulatory trajectory rather than volume expansion.
For Market Incumbents: Consolidate composite airframe repair capacity in France and Germany to capture aftermarket value from SAF-mandated fleet retrofits. Deepen captive supply of hydrotreated ester-compatible fuel system components to offset powertrain supplier concentration risk. Prioritize CS-23 amendment compliance engineering to defend type certificate validity against crashworthiness recertification deadlines.
For New Entrants and Emerging Players: Lead with digital sales platforms targeting Poland and Romania's greenfield fractional ownership demand, bypassing legacy broker networks that dominate Western European charter procurement. Position hybrid-electric propulsion architectures for sub-19 seat platforms where EASA regulatory pilots are validating operational concepts. Partner with Swiss fiduciary structures to access neutral-flag aircraft management demand from international owners.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed component specialists feeding Pilatus-centered supply chains in the Stans corridor. Long-term viability hinges on SAF retrofit program completion before enforcement windows close and single-pilot operational credit decisions reshape crew-cost economics. Watch EASA's reduced-crew certification timeline as the critical inflection signal for business jet specification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Fuel System Retrofit Program | EASA compliance mandates force engineering resource reallocation toward hydrotreated ester compatibility across CS-25 platforms. |
| Single-Pilot Operational Credit Pursuit | EASA certification decision would reshape crew-cost economics and aircraft specification demand for charter operators. |
| Digital Sales Platform Deployment | App-based booking aggregates fractional fleet availability while compressing independent FBO margins across Alpine hubs. |
| Composite Repair Technician Pipeline | Specialized certification scarcity in France and Germany extends turnaround times for carbon fiber airframe damage. |
| Hybrid-Electric Propulsion Development | Battery-assisted turbine systems for 9-19 seat segment compress addressable market for pure piston and turboprop powertrains. |
Research Methodology
Operator-level perspectives from fractional ownership fleet managers, Part-145 maintenance organization technical directors, EASA certification engineers, and flight school operations heads anchored the qualitative base. Primary interview data combined with secondary validation from EASA regulatory filings, EU Green Deal policy documentation, Lufthansa Aviation Training and CAE simulator utilization disclosures, and customs trade data for aerospace component flows. Bottom-up triangulation across aircraft type and end-user segments intersected with top-down macroeconomic modeling to produce volume and value estimates.
Sensitivity analysis tested forecast robustness against SAF blending mandate acceleration, single-pilot operational credit approval timing, and Eastern European charter market penetration rates. Segmentation dimensions modeled include aircraft certification class, propulsion architecture, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fleet replacement cycle analysis and retrofit program adoption curves, incorporating EASA Part-21 design organization output data and OEM engineering resource allocation patterns.
Forecasts assume regulatory continuity in EASA harmonization and EU Green Deal enforcement; material policy shifts would require re-modeling. Specific risks include SAF feedstock price spikes, CS-23 amendment compliance deadline extensions, and Brexit-related UK CAA-EASA divergence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Transparencies Market
Aircraft
America Freighter Aircraft Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Aircraft Galley Systems Market
Aircraft
North America Business Jet Market
Aircraft
Aircraft Manufacturing Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Supersonic Jet Market
Aircraft
Global Helicopter Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aircraft Exterior Mounts Market