
 Middle East and Africa Military Helicopters Market | 2026-2036
Middle East and Africa Military Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Military Helicopters Market Foresight
The gap between premium attack platforms and commodity utility rotorcraft is expanding across Middle East and Africa defense budgets. Airbus SE leverages its Tiger and H225M families to anchor high-end contracts in the Gulf, while Russian Helicopters competes on cost-engineered Mi-17 variants for African militaries with constrained spending. Turkish Aerospace Industries differentiates through indigenous T-70 Black Hawk derivatives tailored to regional offset requirements.
Military helicopters are rotary-wing aircraft engineered for armed forces operations, typically powered by turbine engines generating shaft horsepower to main and tail rotor systems, with airframes designed to withstand combat stress and integrate weapons stations, sensor suites, and troop transport modules. Their primary purpose spans tactical assault, logistics lift, battlefield surveillance, and search-and-rescue in contested environments. Attack helicopters command the largest share of regional procurement value due to asymmetric warfare requirements, while reconnaissance platforms represent the fastest-growing segment as sensor miniaturization and unmanned teaming architectures mature. Utility helicopters retain stable demand across peacekeeping and humanitarian missions where multirole flexibility outweighs specialized performance.
Saudi Arabia's General Authority of Civil Aviation and the UAE's General Civil Aviation Authority impose airworthiness and certification standards that filter non-compliant suppliers from national tenders, while South Africa's Civil Aviation Authority maintains technical benchmarks affecting sub-Saharan import pathways. The EU Green Deal's extraterritorial F-Gas Regulation and emerging sustainable aviation fuel mandates are beginning to shape Middle Eastern procurement specifications as Gulf states align with carbon-neutral defense pledges. Stakeholders must weigh indigenous assembly incentives against OEM direct sales models as offset thresholds tighten from Riyadh to Cairo.
Market Dynamics
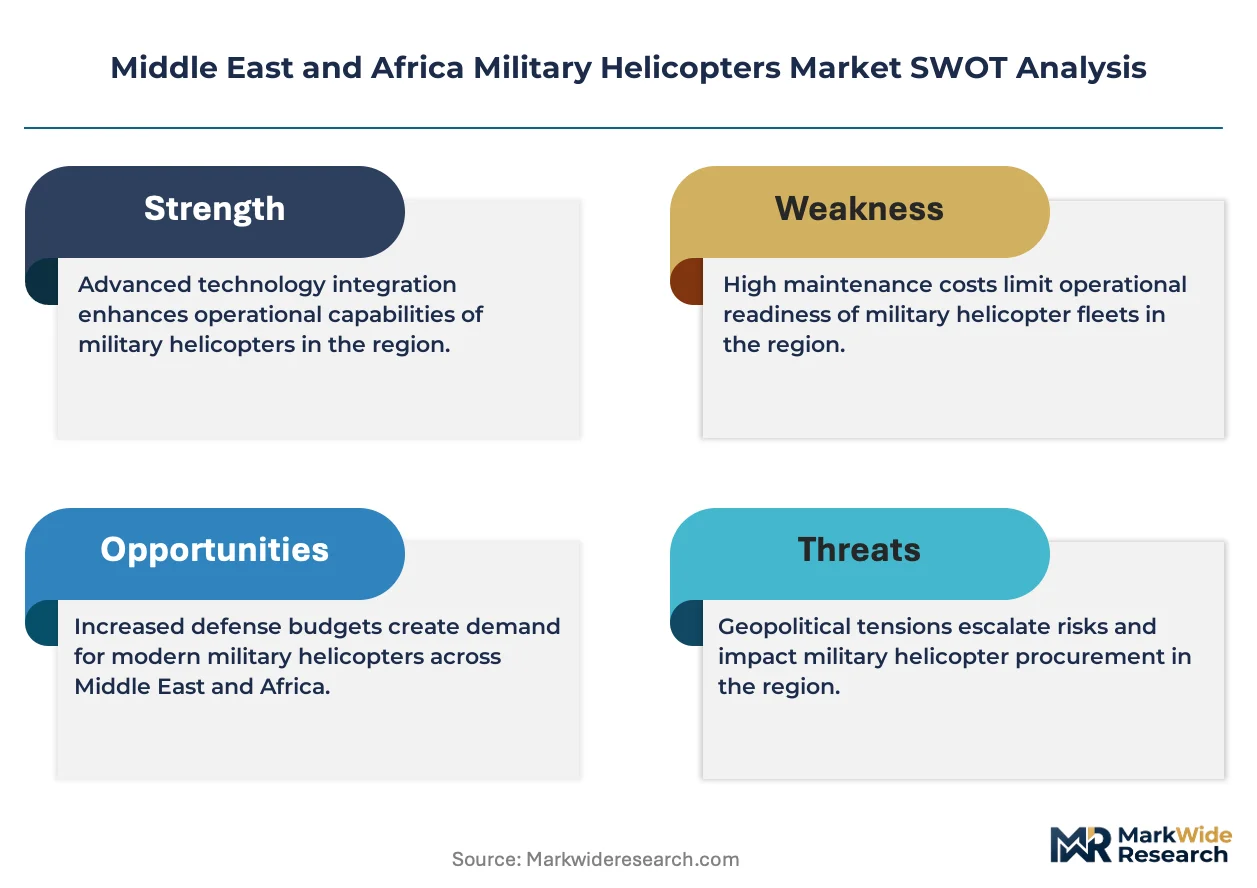
Airworthiness mandates from Saudi Arabia's GACA and the UAE's GCAA are compressing supplier eligibility, forcing OEMs to restructure certification pathways and localize maintenance capabilities before contract award.
Growth Catalysts
- Counter-insurgency doctrine:Asymmetric warfare requirements in the Sahel and Horn of Africa sustain demand for armed reconnaissance platforms with integrated sensor-to-shooter loops.
- SFDA airworthiness harmonization:Saudi Arabia's alignment with EASA technical standards accelerates European OEM access while filtering non-compliant suppliers from national tenders.
- Carbon-neutral defense pledges:Sustainable aviation fuel mandates and F-Gas Regulation compliance are reshaping procurement specifications across Gulf state fleets.
Market Restraints
- Turboshaft engine supply concentration:Dependency on single-source powerplant manufacturers creates vulnerability in long-lead component availability for attack helicopter programs.
- MOHAP certification friction:The UAE's medical-equipment-grade documentation requirements for avionics subsystems extend qualification timelines by 18-24 months.
- Unmanned rotorcraft substitution:Tactical UAS platforms below 150kg are displacing manned reconnaissance missions in low-threat environments.
Strategic Opportunities
- Ethiopian-Djibouti corridor:Underpenetrated peacekeeping logistics markets offer entry points for medium-lift utility platforms with austere-field operating envelopes.
- Indigenous assembly incentives:Egyptian offset thresholds now mandate 35% local content, creating joint-venture openings for airframe component manufacturing.
- Manned-unmanned teaming architectures:Sensor fusion between attack helicopters and loitering munitions is expanding mission sets for combined-arms battlegroups.
Industry Challenges
- Airframe fatigue-life extension engineering:Extending service intervals for legacy Mi-8/17 fleets demands metallurgical expertise scarce across North African maintenance depots.
- Avionics software airworthiness certification:DO-178C compliance for mission-computer upgrades consumes 40% of modernization program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Military Helicopters Market |
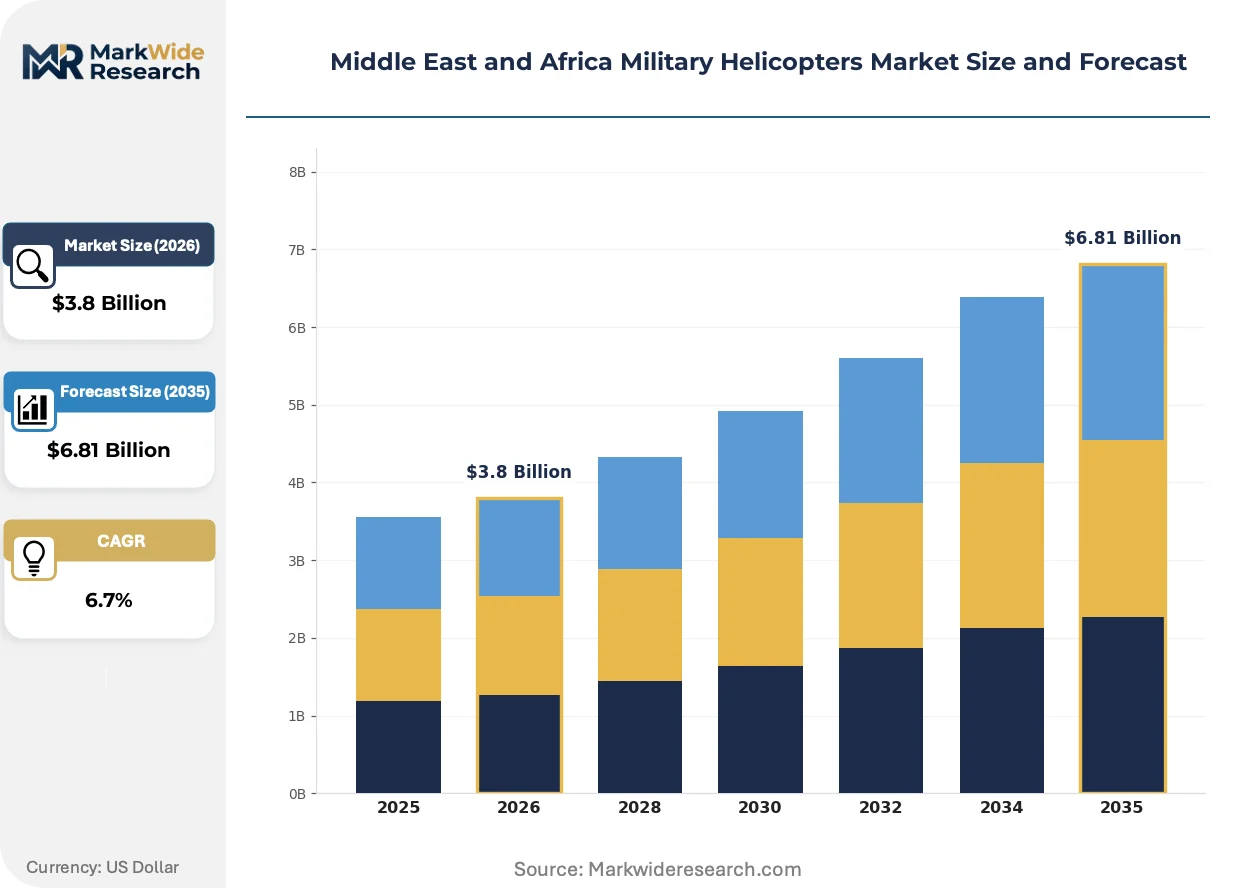
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Helicopters, Transport Helicopters, Reconnaissance Helicopters, Utility Helicopters End User: Government, Defense Contractors, Law Enforcement, Private Security Technology: Fly-by-Wire, Avionics, Turbine Engines, Rotor Systems Deployment: Onshore, Offshore, Transport Support, Recon Missions |
| Companies Covered | Airbus SE, Leonardo S.p.A, Russian Helicopters, Textron Inc., The Boeing Company, Lockheed Martin Corporation, Rostec State Corporation, Turkish Aerospace Industries, Bell Textron Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Military Helicopters Market Shifts & Advancements
Active electronically scanned array radar miniaturization and open-architecture mission computers are compressing platform refresh cycles while enabling capability insertion without full airframe replacement.
AESA radar pods weighing under 85kg are expanding into attack helicopter nose-mounted configurations, enabling fire-control quality targeting in degraded visual environments. Saudi Arabian Aviation Command requirements now specify this capability for all new attack platform acquisitions. The technology is compressing the sensor-to-weapon timeline from detection to engagement.
The EU Green Deal's F-Gas Regulation extraterritorial application is mandating refrigerant-phaseout timelines for environmental control systems in platforms operated by Gulf states with carbon-neutral pledges. OEMs must redesign thermal management architectures to maintain export eligibility. Attack helicopter variants with updated ECS architectures are capturing preference in UAE technical evaluations.
Performance-based logistics contracts are displacing traditional spares-provisioning agreements across Saudi fleet modernization programs. Contractors now guarantee availability rates rather than delivering discrete components, transferring inventory risk to OEMs. This model concentrates with European suppliers possessing regional depot infrastructure.
Middle East and Africa Military Helicopters Market Segmentation
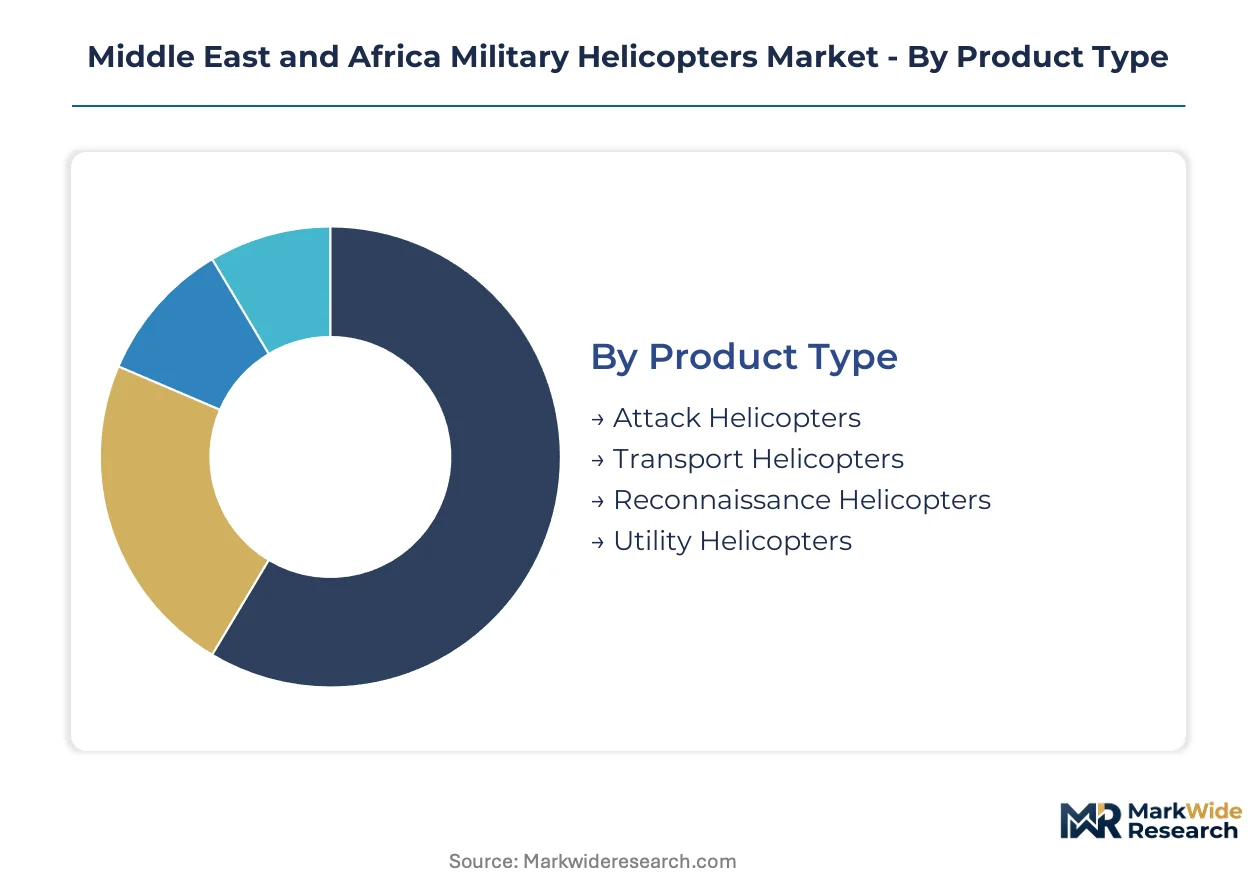
Military helicopter procurement across the Middle East and Africa fragments across mission profiles, buyer sophistication tiers, and operational environments. Each segmentation axis reveals distinct capability requirements and contracting patterns that reshape supplier positioning.
Product Type:
Attack platforms command premium pricing through integrated weapons and sensor architectures, while transport and utility variants compete on fleet economics and multirole flexibility.
- Attack Helicopters:Armed platforms integrate chain guns, anti-tank missiles, and helmet-mounted cueing systems for direct fire support. Saudi Arabian Aviation Command specifications now mandate AESA radar compatibility for all new attack acquisitions, filtering suppliers without nose-mounted sensor integration capabilities.
- Transport Helicopters:Heavy-lift airframes with rear-loading ramps and internal cargo hooks move battalion-scale forces across the Horn of Africa. Ethiopian and Djiboutian peacekeeping logistics contracts favor platforms with hot-and-high performance above 6,000 feet mean sea level.
- Reconnaissance Helicopters:Light scout platforms with mast-mounted sightlines and low acoustic signatures conduct route clearance and target acquisition. Expanding most quickly across Sahel counter-insurgency operations where sensor-to-shooter loops compress engagement timelines.
- Utility Helicopters:Multirole airframes configurable for troop transport, medical evacuation, or external sling loads dominate North African fleet modernization programs. Mi-17 variants retain cost advantages for budget-constrained militaries.
Volume sits with Utility Helicopters; growth tilts toward Reconnaissance Helicopters.
End User:
Procurement authority concentrates with state actors possessing sovereign certification pathways, while private and para-state buyers operate through import licensing frameworks.
- Government:National defense ministries and aviation commands issue platform requirements aligned with GACA, GCAA, or EASA technical standards. Saudi Arabia's Vision 2030 localization mandates now require 35% domestic content for government contracts above threshold values.
- Defense Contractors:Private military service providers lease rotary-wing assets for site protection and personnel transport in conflict zones. UAE-based contractors face MOHAP medical-equipment-grade documentation requirements extending qualification timelines.
- Law Enforcement:Border patrol and coast guard agencies acquire light utility platforms for surveillance and interdiction. Nigerian and Kenyan agencies prioritize night-vision-compatible cockpits for transnational crime suppression.
- Private Security:Corporate protection details and resource extraction operators contract wet-lease helicopter services. Demand clusters around Iraqi and Libyan oilfield corridors where sovereign airspace access remains contested.
Government buyers anchor procurement value; Defense Contractors show the steepest expansion trajectory.
Technology:
Subsystem differentiation now exceeds airframe performance in contract evaluations, with digital flight controls and modular avionics determining platform longevity.
- Fly-by-Wire:Digital flight control systems replace mechanical linkages with triple-redundant electrical signaling. European attack helicopter platforms leverage this architecture for automatic terrain following and degraded-mode recovery.
- Avionics:Open-architecture mission computers enable software-defined capability insertion without hardware replacement. DO-178C certification requirements consume substantial program schedules for North African upgrade contracts.
- Turbine Engines:Turboshaft powerplants from concentrated single-source manufacturers drive long-lead vulnerability for attack helicopter production. Hot-climate sand ingestion specifications filter engine options for Gulf state acquisitions.
- Rotor Systems:Bearingless hub designs and composite blade construction reduce maintenance intervals and acoustic signatures. South African technical benchmarks influence sub-Saharan import acceptance criteria for dynamic component lifing.
Avionics captures modernization investment; Fly-by-Wire gains share fastest in new-build programs.
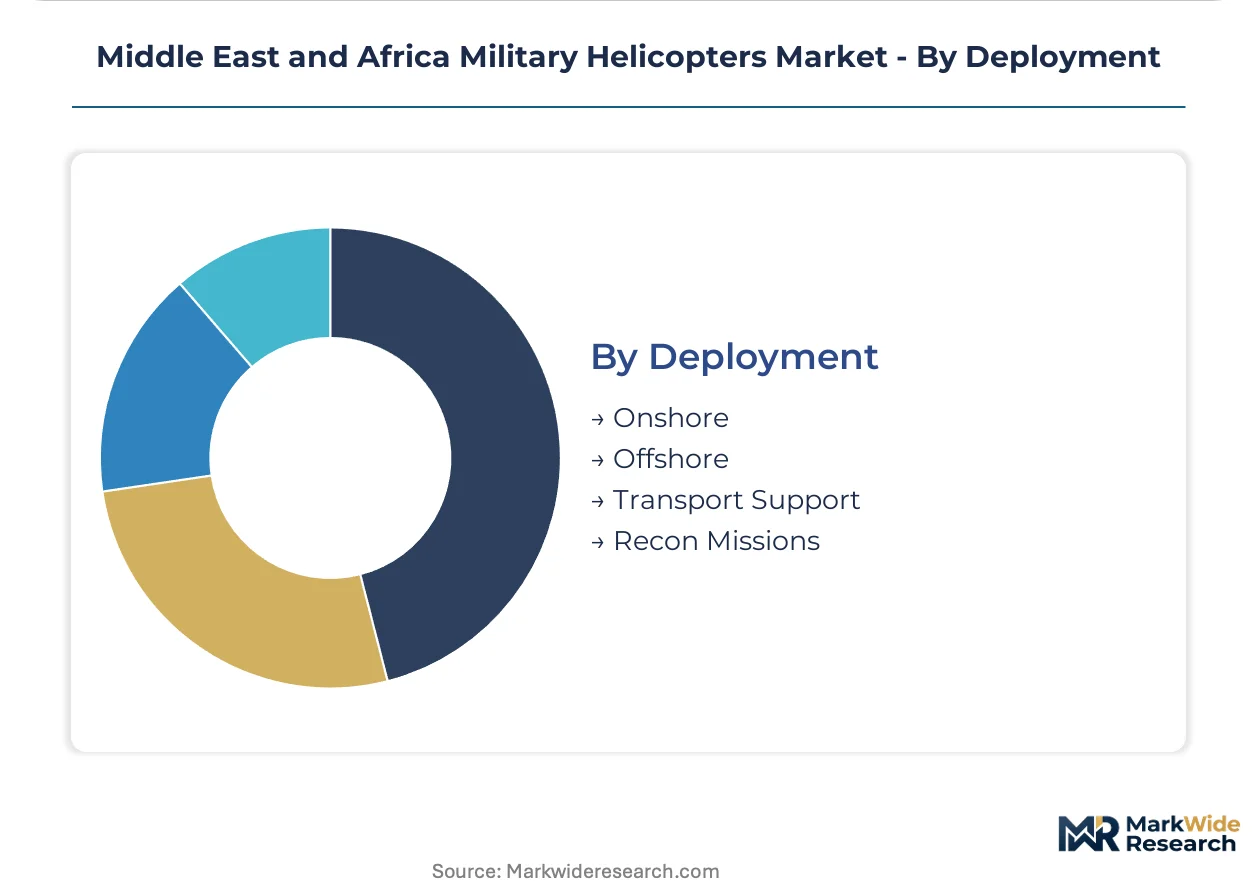
Deployment:
Operating environment dictates platform configuration more than mission type, with austere-field requirements separating premium from commodity procurement tiers.
- Onshore:Land-based operations from prepared airfields or forward arming and refueling points. Saudi Arabian border security commands dominate regional onshore fleet requirements.
- Offshore:Maritime rotary-wing operations from naval vessels or oil platforms demand corrosion-resistant coatings and folding rotor systems. UAE naval aviation expansion drives Gulf offshore platform acquisitions.
- Transport Support:Logistics missions connecting forward operating bases with supply depots prioritize payload-range tradeoffs. Ethiopian-Djibouti corridor contracts favor platforms with self-deploying ferry range.
- Recon Missions:Intelligence-gathering sorties requiring low-probability-of-intercept sensors and standoff optics. Climbing the fastest across Sahel and Horn of Africa theaters where manned-unmanned teaming architectures mature.
Onshore deployments hold fleet mass; Recon Missions attract capability investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors Middle East and Africa military helicopter procurement volume through Saudi Vision 2030 localization mandates. The Eastern Province hosts airframe assembly partnerships absorbing European OEM technology transfer.
Saudi Arabia
Attack helicopter modernization and border security expansion drive fleet replacement programs. The General Authority of Civil Aviation enforces SFDA airworthiness harmonization aligned with EASA technical standards. Riyadh-based Aviation Command headquarters concentrates attack platform requirements and offset negotiation authority.
United Arab Emirates
Naval aviation expansion and offshore platform protection sustain rotary-wing acquisitions. The General Civil Aviation Authority imposes MOHAP medical-equipment-grade documentation for avionics subsystems. Abu Dhabi hosts performance-based logistics contracting that transfers inventory risk to OEMs.
Egypt
Counter-insurgency operations in the Sinai Peninsula demand armed reconnaissance capabilities. Offset thresholds now mandate 35% local content for contracts above threshold values. Cairo-Alexandria corridor maintenance depots struggle with airframe fatigue-life extension engineering for legacy Soviet-era fleets.
South Africa
Sub-Saharan import pathway influence and technical benchmarking shape regional acceptance criteria. The Civil Aviation Authority maintains dynamic component lifing standards affecting bearingless hub designs. Johannesburg-Pretoria industrial corridor hosts metallurgical expertise scarce across North African maintenance networks.
Ethiopia
Peacekeeping logistics in the Horn of Africa and Djibouti corridor operations sustain medium-lift demand. Self-deploying ferry range specifications filter platform options for forward operating base connectivity. Addis Ababa anchors underpenetrated utility helicopter markets with austere-field operating requirements.
Middle East and Africa Military Helicopters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification pathway complexity and airworthiness compliance depth. European OEMs capture high-end attack contracts through EASA-aligned standards, while Russian and Turkish suppliers compete on cost-engineered platforms with localized assembly incentives. Three archetypes dominate: full-system integrators with nose-mounted AESA radar capabilities, regional offset specialists leveraging indigenous assembly mandates, and commodity utility providers serving budget-constrained African militaries. Competitive moves concentrate on joint-venture localization and performance-based logistics contracting that guarantees availability rates.
Within the full-system integrator tier, Airbus SE and Leonardo S.p.A exemplify premium-positioned European OEMs navigating Gulf state carbon-neutral procurement specifications. Turkish Aerospace Industries occupies a position as the regional offset specialist archetype, with T-70 Black Hawk derivatives tailored to Egyptian and Saudi localization thresholds. Russian Helicopters anchors the commodity utility segment, with Mi-17 variants penetrating African markets where cost-engineered platforms outweigh sensor integration requirements.
| Leading Market Players |
|---|
| Airbus SE |
| Leonardo S.p.A |
| Russian Helicopters |
| Textron Inc. |
| The Boeing Company |
| Lockheed Martin Corporation |
| Rostec State Corporation |
| Turkish Aerospace Industries |
| Bell Textron Inc. |
| Others |
Supply & Pricing Matrix
Captive maintenance networks in Saudi Arabia and the UAE anchor both supply positioning and pricing power for European OEMs, forcing competitors without regional depot infrastructure into steep discounting to compensate for availability risk transfer.
Pricing Analysis
Availability-rate guarantees now anchor contract valuations across Saudi fleet modernization programs, displacing discrete spares-provisioning models. Price differentiation separates EASA-aligned platforms with AESA radar integration from cost-engineered Mi-17 variants serving budget-constrained African militaries. Pricing pressure stems from performance-based logistics contracting that transfers inventory risk to OEMs, compressing margins for suppliers without regional depot infrastructure. Government buyers in Riyadh and Abu Dhabi show lowest price sensitivity due to offset mandates and sovereign certification requirements, while private security operators in Iraqi and Libyan oilfield corridors exhibit highest sensitivity.
Supply Chain Analysis
Turboshaft engine supply rests on concentrated single-source manufacturers in France, the United States, and Ukraine, creating long-lead vulnerability for attack helicopter production programs. Critical inputs include nickel-based superalloys for hot-section components, composite prepregs for rotor blades, and gallium arsenide substrates for AESA radar modules. Supply chain risk centers on single-source powerplant dependency that disrupts production schedules when geopolitical friction interrupts component flows. Distribution runs through sovereign aviation authority certification pathways, with GACA and GCAA compliance filtering non-qualified suppliers from national tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around airworthiness compliance depth, with SFDA harmonization to EASA standards and carbon-neutral procurement pledges forcing weaker players without certification investment capacity toward exit.
For Market Incumbents: Lock in performance-based logistics contracts with Saudi Aviation Command before offset thresholds tighten further, while deepening captive maintenance networks in the Eastern Province to defend against Turkish Aerospace Industries' localization bids. Threat substitution from tactical UAS platforms below 150kg demands accelerated manned-unmanned teaming architecture investment as the priority R&D lever. For New Entrants and Emerging Players: The mid-tier pricing gap between Airbus H225M configurations and Russian Mi-17 variants offers entry points for indigenous assembly specialists. White-space targets cluster in Ethiopian-Djibouti corridor peacekeeping logistics and Egyptian offset-compliant component manufacturing. The most penetrable segment is austere-field utility platforms for sub-Saharan peacekeeping missions, best approached through joint-venture structures with Cairo-based maintenance depots. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-system integrators seeking regional depot infrastructure and EASA-aligned certification pathways. Long-term viability favors suppliers with nose-mounted AESA radar capabilities and established GACA/GCAA compliance records. The signal to watch is UAE MOHAP documentation requirement expansion beyond medical-equipment-grade avionics into additional subsystem categories, which would accelerate supplier filtration.| Strategic Initiative | Industry Significance |
|---|---|
| Joint-Venture Localization | Egyptian 35% offset thresholds create captive assembly partnerships with technology transfer from European OEMs. |
| Performance-Based Logistics Contracting | Saudi fleet modernization programs now guarantee availability rates, transferring inventory risk to suppliers with regional depots. |
| AESA Radar Integration | Saudi Aviation Command mandates nose-mounted configurations, filtering suppliers without fire-control quality targeting capabilities. |
| Carbon-Neutral Fleet Transition | F-Gas Regulation compliance and sustainable aviation fuel mandates reshape Gulf state procurement specifications. |
| Manned-Unmanned Teaming Architectures | Sensor fusion between attack helicopters and loitering munitions expands mission sets for combined-arms battlegroups. |
Research Methodology
Multi-period observation of fleet modernization contract awards, certification pathway restructuring, and localization threshold evolution anchored the trend analysis, supplemented by interviews with Saudi Aviation Command procurement officers, UAE GCAA certification engineers, Egyptian offset negotiation leads, and European OEM regional directors. Secondary validation drew from GACA airworthiness directives, EASA technical standard harmonization documents, SFDA regulatory filings, and customs trade data for turboshaft engine imports. Bottom-up platform-level demand modeling triangulated against top-down defense budget allocation analysis.
Input-output matrices mapped attack helicopter, transport helicopter, reconnaissance helicopter, and utility helicopter segments against government, defense contractor, law enforcement, and private security end users. Deployment configurations across onshore, offshore, transport support, and recon missions were modeled throughout the forecast period. CAGRs were derived from contract award velocity analysis and fleet replacement cycle assessment, with hot-climate sand ingestion specifications and DO-178C avionics certification timelines incorporated as industry-specific demand modifiers.
Inputs from GACA directive releases and Saudi Vision 2030 localization mandate updates were available through the study window; gaps in classified attack platform technical specifications introduce uncertainty bands around sensor integration adoption curves. Forecasts reflect documented assumptions regarding EASA-SFDA harmonization pace and carbon-neutral pledge implementation timelines. Geopolitical disruption to Ukrainian engine component flows and UAE MOHAP requirement expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Wheels Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Docking System Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Utility Aircraft Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Military Trainer Aircraft Market
Aircraft
Europe Military Helicopters Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Air Speed Indicator Market