
 Asia-Pacific Commercial Aircraft Market | 2026-2036
Asia-Pacific Commercial Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Aircraft Market Outlook
Multi-source supplier networks is repositioning how Asia-Pacific carriers procure airframes and subsystems. Airbus leverages its Tianjin final assembly line to anchor regional delivery timelines for narrow-body programs. Boeing competes through expanded partnerships with Japanese and Australian aerostructures firms. Embraer specializes in the sub-150-seat segment, occupying a niche that larger OEMs have ceded to regional operators.
Commercial aircraft are fixed-wing, turbine-powered vehicles certified for passenger or cargo transport under maximum takeoff weights exceeding several thousand kilograms, with aluminum-lithium alloys and carbon-fiber reinforced polymers now constituting primary structural elements. Narrow-body configurations lead order backlogs across Asia-Pacific due to route density economics and slot constraints at congested hubs like Manila and Jakarta. Composite materials technology is expanding fastest as airframers replace metallurgical assemblies to reduce operating empty weight and improve fuel burn metrics. Direct purchase delivery mode still dominates fleet planning for state-affiliated carriers, though leasing companies are capturing share among privately funded startups.
CAAC airworthiness directives and EASA-equivalent standards adopted by Australia's Civil Aviation Safety Authority shape certification pathways for imported equipment. India's DGCA mandates localized maintenance infrastructure as a condition of operator certificates, redirecting aftermarket investment toward Mumbai and Bangalore. Stakeholders must weigh exposure to currency-denominated purchase agreements against the long-dated revenue profiles that leasing structures offer across this expansion cycle.
Market Dynamics
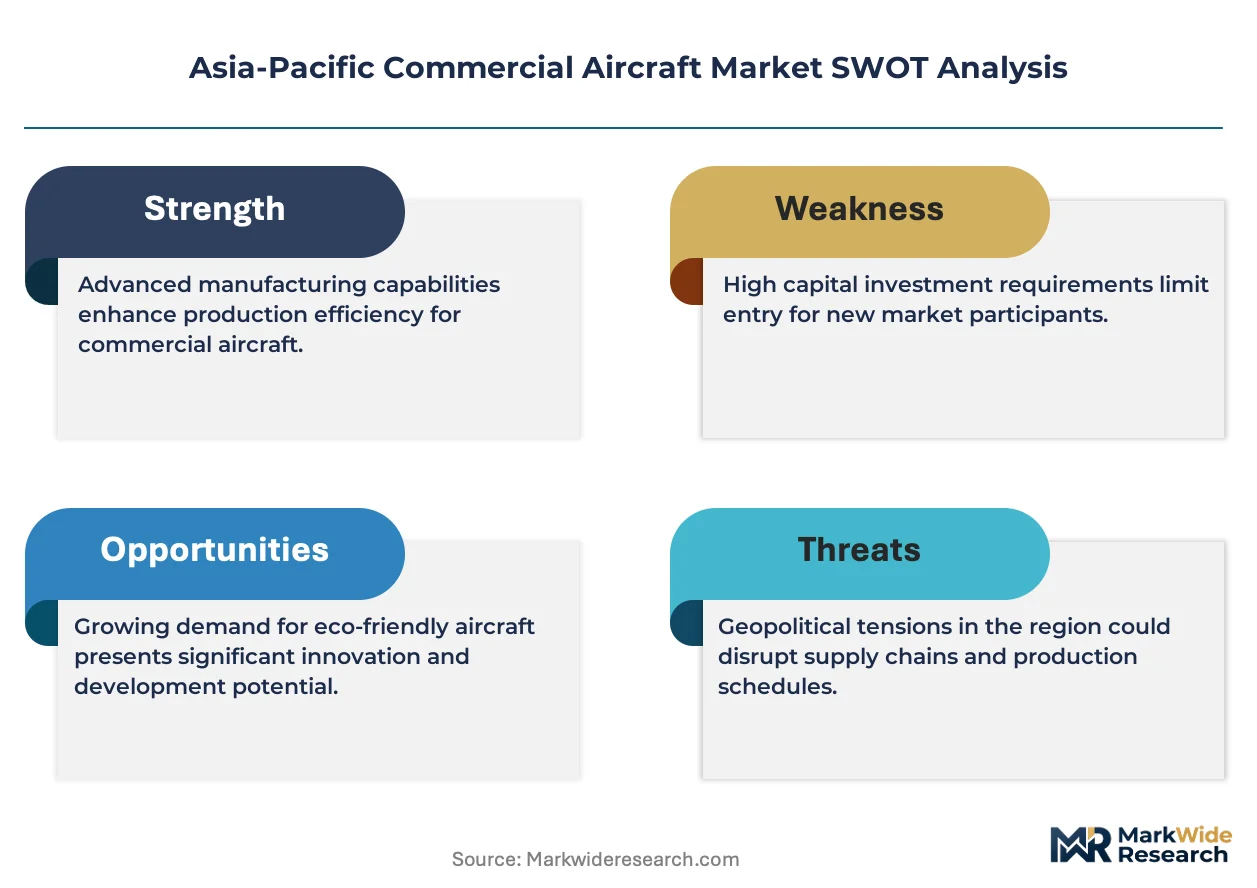
Carbon-emission benchmarks from the International Civil Aviation Organization are forcing Asia-Pacific carriers to accelerate fleet renewal cycles, compressing delivery timelines and redirecting procurement toward fuel-efficient narrow-body platforms.
Growth Catalysts
- ICAO Carbon Offsetting and Reduction Scheme:Binding emission thresholds are mandating fleet modernization across Southeast Asian low-cost carriers, triggering concentrated order flows for next-generation narrow-body aircraft.
- Secondary city route proliferation:India's regional connectivity schemes are stimulating demand for sub-180-seat configurations capable of operating from constrained airfields.
- Aluminum-lithium alloy adoption:Advanced metallurgy is reducing operating empty weight by substantial margins, improving payload-range economics for high-frequency domestic operators.
Market Restraints
- US dollar-denominated purchase agreements:Currency mismatch between revenue streams and capital commitments exposes Asia-Pacific operators to exchange rate volatility on long-dated delivery schedules.
- Final assembly line concentration:Tianjin and Mobile facilities control narrow-body delivery pacing, creating queue risk for carriers outside priority allocation tiers.
- Composite repair infrastructure scarcity:Carbon-fiber reinforced polymer damage assessment requires specialized tooling that remains concentrated in Singapore and Sydney maintenance clusters.
Strategic Opportunities
- Vietnam and Philippines greenfield airports:New secondary hubs lack incumbent carrier dominance, creating first-mover positioning for lessors deploying mid-life narrow-body assets.
- Hybrid-electric propulsion integration:Turbogenerator-battery architectures are approaching commercial viability for sub-100-seat segments, opening technology partnership pathways between regional operators and powertrain specialists.
- India's DGCA maintenance localization mandate:Required domestic MRO infrastructure is redirecting aftermarket investment toward Mumbai and Bangalore, creating captive service revenue pools.
Industry Challenges
- Composite technician certification pipelines:CAAC and Australia's Civil Aviation Safety Authority have divergent qualification frameworks, fragmenting workforce mobility across the region.
- Airworthiness directive harmonization gaps:EASA-equivalent standards adopted by Australian regulators misalign with India's DGCA implementation timelines, delaying cross-border aircraft transfers.
- Legacy avionics integration complexity:New flight management systems require substantial cockpit modification to interface with existing fleet configurations, extending downtime during retrofit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Aircraft Market |
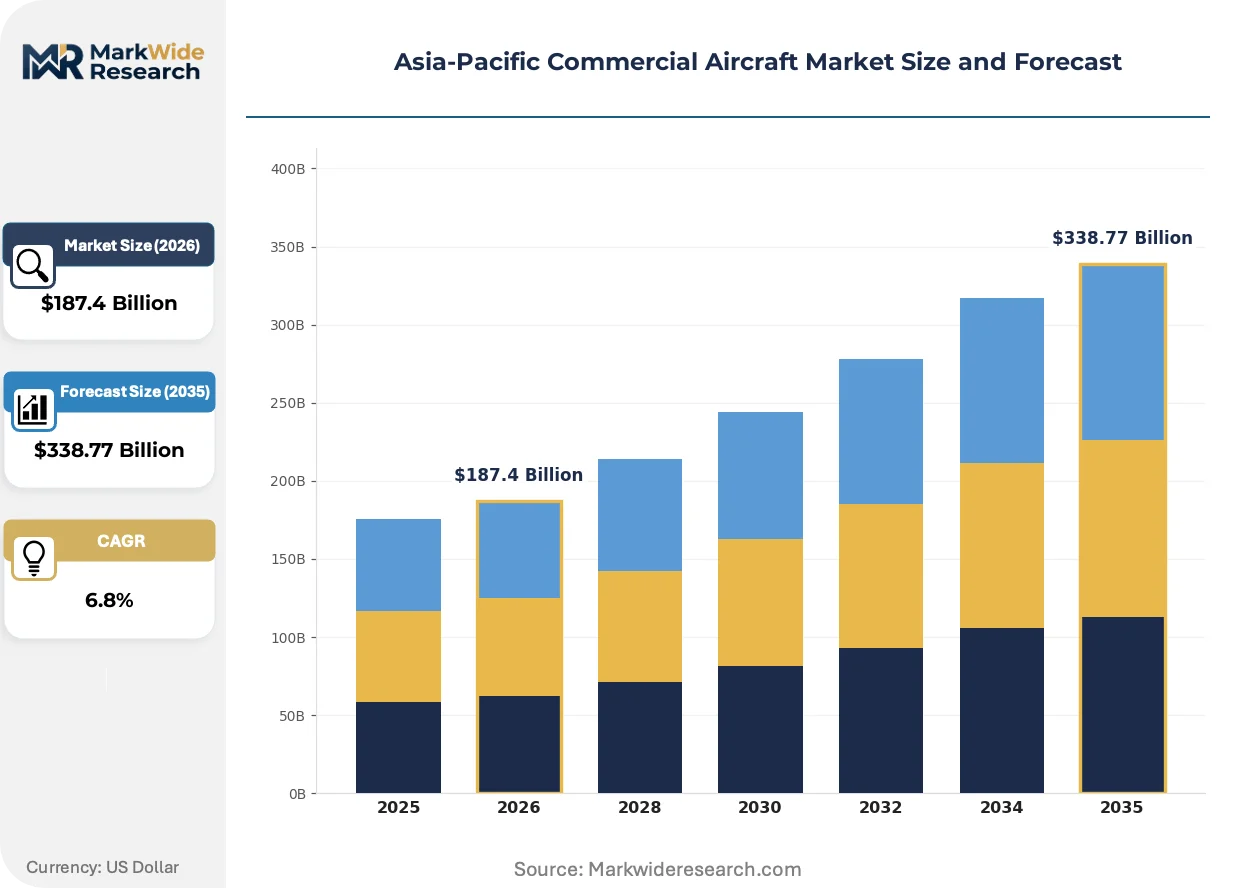
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Narrow-Body, Wide-Body, Regional, Business Jets Technology: Conventional, Composite Materials, Fly-by-Wire, Hybrid Systems End User: Airlines, Cargo Operators, Leasing Companies, Government Agencies Delivery Mode: Direct Purchase, Leasing, Frame Agreements, Others |
| Companies Covered | Bombardier, Gulfstream Aerospace, Airbus, Joby Aviation, De Havilland Canada, Boeing, Dassault Aviation, Airbus Helicopters, Embraer, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Aircraft Market Strategic Shifts
Material substitution and regulatory harmonization pressures are compressing traditional aircraft development cycles, while procurement models fragment between direct purchase and operating lease structures.
Carbon-fiber reinforced polymers are overtaking aluminum-lithium assemblies in wingbox and fuselage barrel construction. Asia-Pacific carriers operating high-cycle domestic routes are specifying full-composite wings on new narrow-body deliveries. This material transition is overtaking metallurgical supply chains and forcing tier-one aerostructures firms to retool fabrication facilities.
EASA-equivalent standards adopted by Australia's Civil Aviation Safety Authority are tightening noise and emission certification thresholds for imported equipment. These requirements are extending type certificate validation timelines for non-European manufacturers. Southeast Asian operators are responding by consolidating fleet standardization around platforms already holding dual CAAC-EASA certification.
Operating lease penetration is accelerating among privately funded startup carriers lacking sovereign credit backing. Lessors are capturing share from direct purchase structures by offering maintenance-reserve packages and flexible return conditions. This financing rotation is most visible in Indonesia and Vietnam, where new market entrants lack balance-sheet capacity for capital-intensive asset ownership.
Asia-Pacific Commercial Aircraft Market Segmentation
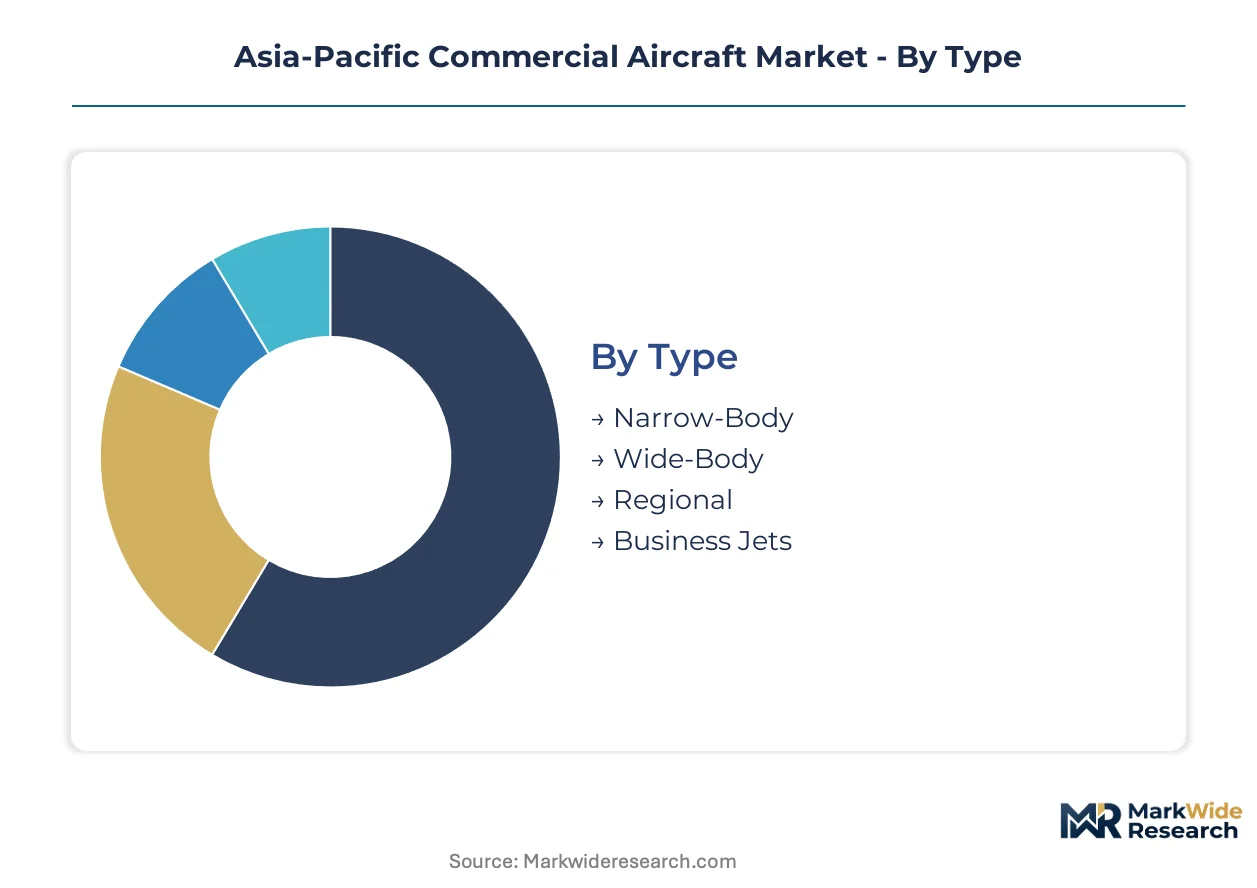
Segmentation in Asia-Pacific commercial aircraft procurement reveals how fleet planners balance route economics against capital structure constraints. Each dimension—airframe type, materials technology, customer category, and acquisition method—channels investment toward distinct operational profiles across the region's heterogeneous aviation markets.
Type:
Final assembly line concentration for single-aisle programs anchors supply availability for Asia-Pacific carriers.
- Narrow-Body:Single-aisle configurations with 150-200 seat capacity dominate order backlogs. IndiGo and Air India in India concentrate procurement here to serve secondary city routes under regional connectivity mandates, compressing delivery timelines at Airbus Tianjin and Boeing facilities.
- Wide-Body:Twin-aisle aircraft certified for long-haul operations above 250 seats address hub-to-hub trunk routes. Singapore Airlines and Cathay Pacific prioritize these for trans-Pacific services, though order volumes lag narrow-body programs due to higher capital intensity and longer replacement cycles.
- Regional:Turboprop and small jet platforms below 100 seats serve thin routes from constrained airfields. Garuda Indonesia and Philippine Airlines deploy these for island-hopping networks where runway length limits narrow-body operations.
- Business Jets:Corporate-configured aircraft under 50 seats support executive transport and high-net-worth mobility. Australia's mining sector and Singapore's wealth management cluster generate concentrated demand for long-range models.
Narrow-body platforms absorb the bulk of installed capacity; regional aircraft are expanding most quickly across secondary city networks.
Technology:
Material substitution trajectories differentiate cost tiers across the technology stack, with composite adoption commanding premium positioning.
- Conventional:Aluminum-alloy primary structures with hydromechanical flight controls persist in mid-life fleet segments. Southeast Asian low-cost carriers operating high-cycle domestic routes specify these for acquisition cost advantages despite fuel burn penalties.
- Composite Materials:Carbon-fiber reinforced polymers in wingbox and fuselage construction reduce operating empty weight substantially. CAAC airworthiness directives and Australia's Civil Aviation Safety Authority certification requirements concentrate demand among flag carriers with dedicated MRO infrastructure in Singapore and Sydney.
- Fly-by-Wire:Digital flight control architectures replace mechanical linkages with electronic signaling. Indian operators under DGCA oversight specify these for precision approach capabilities at challenging Himalayan airfields.
- Hybrid Systems:Turbogenerator-battery electric architectures approach commercial viability for sub-100-seat segments. Japanese METI technology partnerships and Australian sustainable aviation fuel mandates accelerate demonstration programs.
Conventional technology retains the largest active fleet footprint; composite materials are climbing the fastest as fuel efficiency mandates tighten.
End User:
Customer type segmentation tracks capital access differentiation, separating sovereign-backed operators from privately funded market entrants.
- Airlines:Scheduled passenger carriers operating under national air operator certificates. India's IndiGo and Vietnam's VietJet drive narrow-body demand through fleet renewal programs responding to ICAO carbon emission benchmarks.
- Cargo Operators:Dedicated freighter fleets and converted passenger-to-cargo platforms. Cathay Pacific Cargo and Singapore Airlines Cargo prioritize wide-body conversions for e-commerce trunk routes between China and Southeast Asia.
- Leasing Companies:Aircraft lessors acquiring speculative positions for onward operating lease placement. Air Lease Corporation and BOC Aviation capture share among Indonesian and Vietnamese startups lacking balance-sheet capacity for direct purchase.
- Government Agencies:State aviation units including VIP transport and maritime patrol derivatives. Royal Australian Air Force and Japan Air Self-Defense Force procure modified commercial platforms for multi-mission requirements.
Airlines command the dominant share of forward orders; leasing companies are gaining share fastest among privately funded startup carriers.
Delivery Mode:
Acquisition structure segmentation reflects financing rotation toward flexible capital deployment mechanisms.
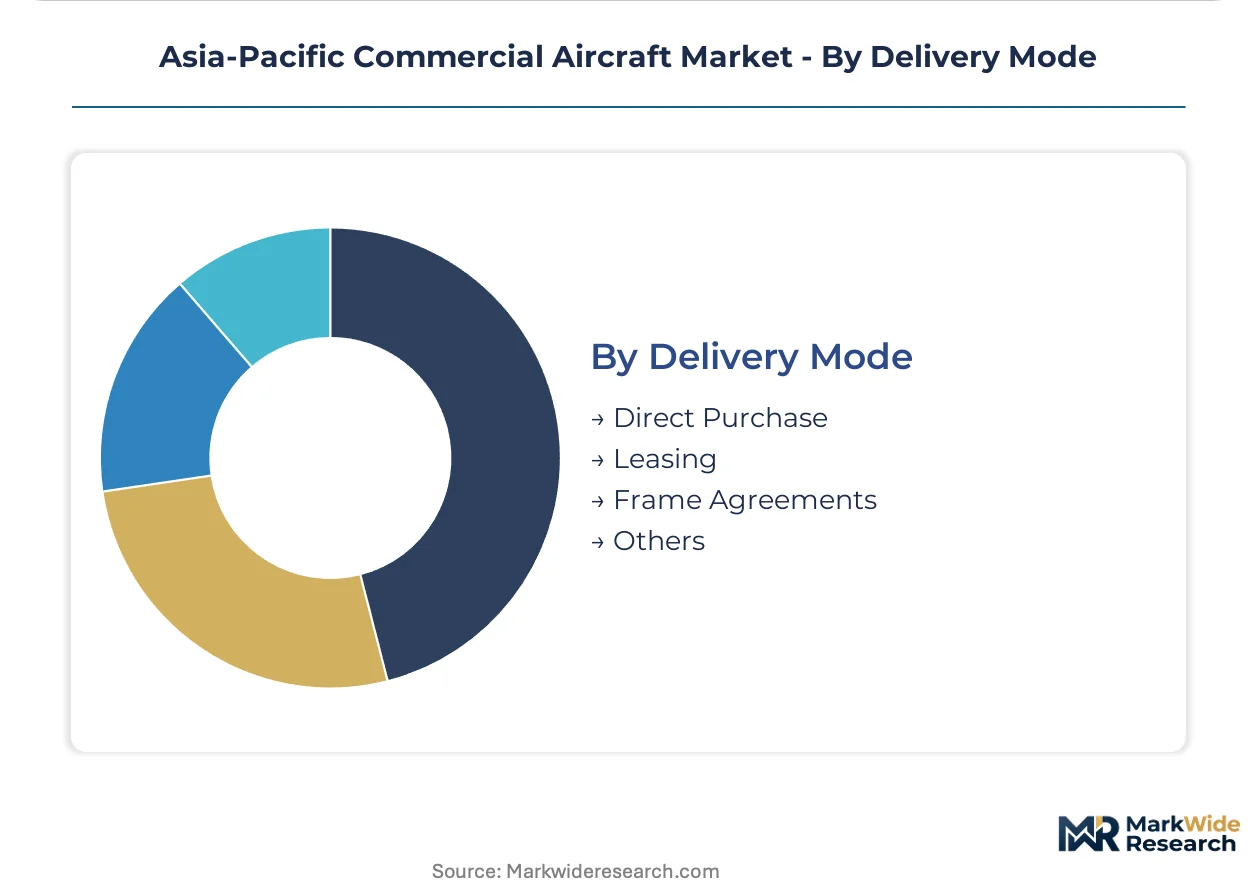
- Direct Purchase:Outright acquisition with manufacturer warranty and aftermarket support packages. State-affiliated carriers including Air India and China Southern Airlines favor this for fleet standardization and residual value control.
- Leasing:Operating lease structures with maintenance reserve provisions and return condition flexibility. Indonesia's Lion Air and Vietnam's Bamboo Airways access newer narrow-body equipment through lessor relationships despite currency-constrained balance sheets.
- Frame Agreements:Multi-year procurement commitments with variable delivery scheduling and pricing terms. Singapore Airlines and Qantas negotiate these for fleet commonality across group subsidiaries.
- Others:Sale-leaseback arrangements and manufacturer-supported financing for specific transaction structures. Secondary market entrants in Philippines and Thailand utilize these for mid-life asset access.
Direct purchase structures retain the largest historical transaction volume; leasing is expanding most quickly among new market entrants lacking sovereign credit backing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum-bauxite deposits in Australia's Queensland and Western Australia anchor the Asia-Pacific aerospace materials supply chain, feeding Tianjin's final assembly lines and Japan's precision forging clusters.
China
CAAC airworthiness directives are tightening composite certification standards for imported equipment. The Tianjin final assembly line anchors Airbus narrow-body delivery timelines for Southeast Asian carriers. Shanghai and Xi'an host concentrated MRO infrastructure serving domestic operators under dual carbon mandates from MEE.
India
IndiGo and Air India have placed record orders for narrow-body jets to serve secondary city routes under UDAN regional connectivity schemes. DGCA mandates localized maintenance infrastructure as a condition of operator certificates. Mumbai and Bangalore are redirecting aftermarket investment toward captive service revenue pools.
Japan
METI technology partnerships are accelerating hybrid-electric propulsion demonstration programs for sub-100-seat segments. JIS standards govern precision component supply to Boeing's expanded aerostructures partnerships. Nagoya's Chubu region concentrates composite wingbox fabrication for next-generation platforms.
Australia
Civil Aviation Safety Authority adoption of EASA-equivalent standards is tightening noise and emission certification thresholds for imported equipment. Queensland's bauxite deposits feed aluminum-lithium alloy supply chains. Sydney maintenance clusters retain specialized carbon-fiber reinforced polymer damage assessment tooling.
Singapore
Seletar Aerospace Park hosts concentrated composite repair infrastructure serving regional carriers lacking in-house capability. The city-state's lessor community captures share among Indonesian and Vietnamese startups through operating lease structures with flexible return conditions.
Asia-Pacific Commercial Aircraft Market Competitive Environment
Global majors compete with regional champions across final assembly capacity and materials technology tiers. The market structures around three concentrated OEMs controlling narrow-body and wide-body certification pathways, with specialist players occupying sub-150-seat niches. Strategic archetypes include: full-range platform developers with Tianjin anchoring; regional jet specialists ceding upper segments; and emerging urban air mobility entrants. Dominant competitive moves center on multi-source supplier network expansion and hybrid-electric propulsion technology partnerships.
Within the full-range platform tier, Airbus and Boeing exemplify divergent regional anchoring strategies. Airbus leverages its Tianjin final assembly line to compress delivery timelines for Asia-Pacific narrow-body operators. Boeing competes through expanded partnerships with Japanese and Australian aerostructures firms. Embraer occupies a specialist position in the sub-150-seat segment, representing the regional jet archetype that larger OEMs have ceded to thin-route operators.
| Leading Market Players |
|---|
| Bombardier |
| Gulfstream Aerospace |
| Airbus |
| Joby Aviation |
| De Havilland Canada |
| Boeing |
| Dassault Aviation |
| Airbus Helicopters |
| Embraer |
| Others |
Value Chain & Pricing Dynamics
State-affiliated carriers with sovereign credit backing anchor procurement volumes and favor direct purchase structures bundled with long-term manufacturer warranties. This buyer concentration compresses price transparency and shifts negotiation leverage toward airframers with final assembly line priority allocation.
Pricing Analysis
Manufacturer warranty and aftermarket support packages remain bundled for flag carriers, while lessors unbundle maintenance reserves into separate contractual structures. Three-tier pricing structure across premium composite configurations, standard aluminum-lithium platforms, and conventional alloy variants reflects certification grade and MRO infrastructure requirements. Cost compression in narrow-body segments is intensifying because low-cost carriers consolidate fleet standardization around high-volume programs. Privately funded startups lacking sovereign backing exhibit highest price sensitivity; state-affiliated operators with direct purchase capacity show lowest.
Supply Chain Analysis
Freight costs for titanium sponge and carbon fiber prepreg from Japan and the United States feed into Tianjin and Nagoya fabrication clusters. Australia, China, and Japan anchor aluminum-bauxite and precision component supply. Raw material dependencies center on aluminum-lithium master alloys, carbon-fiber reinforced polymer tow, and high-temperature engine alloys. Single-source vulnerability concentrates in Tianjin final assembly line capacity for narrow-body delivery pacing. Distribution runs through lessor inventory positions and manufacturer direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific commercial aircraft market sits in a material-transition phase as carbon-fiber reinforced polymers displace aluminum-lithium alloys in primary structures. This technology shift compresses development cycles and redirects supply chain investment toward composite fabrication infrastructure.
For Market Incumbents: Cement composite repair certification pipelines by partnering with CAAC and Australia's Civil Aviation Safety Authority to harmonize technician qualification frameworks. Expand Tianjin final assembly line throughput commitments to defend queue priority against emerging hybrid-electric entrants. Composite technician mobility fragmentation across regulatory jurisdictions represents the core threat to aftermarket service capture.
For New Entrants and Emerging Players: Regional operators in Vietnam and Philippines lacking incumbent carrier dominance at greenfield secondary airports represent the most penetrable buyer archetype. Hybrid-electric propulsion integration for sub-100-seat segments opens technology partnership pathways with Japanese METI demonstration programs. Position through operating lease structures with flexible return conditions to bypass balance-sheet constraints.
For Investors and Strategic Acquirers: The window for entry favors lessors with maintenance-reserve packaging capabilities and composite MRO infrastructure positions. Long-term viability hinges on exposure to India's DGCA-mandated localization requirements and secondary city route proliferation. Watch ICAO carbon offsetting scheme enforcement stringency as the inflection signal for fleet renewal acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Materials Certification Investment | CAAC and EASA-equivalent standards adoption accelerates airworthiness validation timelines for carbon-fiber primary structures. |
| Final Assembly Line Capacity Expansion | Tianjin and Mobile facility throughput increases compress delivery queues for Southeast Asian low-cost carrier order backlogs. |
| Hybrid-Electric Propulsion Partnership | METI technology collaborations advance turbogenerator-battery architectures toward commercial viability in sub-100-seat segments. |
| Maintenance Localization Infrastructure | DGCA-mandated MRO requirements in Mumbai and Bangalore redirect aftermarket investment toward captive service revenue pools. |
| Operating Lease Structure Innovation | Flexible return condition packaging captures share among Indonesian and Vietnamese startups lacking direct purchase capacity. |
Study Parameters
Airworthiness directive filings, customs trade data for aerospace components, and OEM delivery disclosure reports formed the secondary backbone of this analysis. Primary interviews with fleet planning executives at Asia-Pacific carriers, procurement leads at tier-one aerostructures firms, MRO operations directors, and lessor portfolio managers combined with secondary validation. Bottom-up and top-down triangulation cross-checked order backlog data against installed fleet projections and retirement schedules.
Bottom-up modeling aggregated individual carrier procurement plans across narrow-body, wide-body, and regional segments, while top-down analysis calibrated against ICAO emission benchmark compliance timelines. Segmentation dimensions included airframe type, materials technology tier, end-user capital structure, and delivery mode. CAGRs were derived from delivery schedule pacing and fleet replacement cycle compression. Fuel burn improvement trajectories and carbon offsetting cost assumptions fed composite adoption forecasts.
Revisions become necessary when ICAO enforcement timelines accelerate, currency volatility disrupts dollar-denominated purchase agreements, or composite repair infrastructure deployment lags fleet in-service dates. Forecasts reflect documented assumptions about regulatory harmonization progress and manufacturer delivery capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Door Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Water Bomber Market
Aircraft
Maritime Patrol Aircraft Market
Aircraft
Turboprop Aircraft Market
Aircraft
Military Rotorcraft Market
Aircraft
Special Mission Aircraft Market
Aircraft
Evtol Aircraft Market
Aircraft
Military Transport Aircraft Market
Aircraft
Europe Business Jet Market
Aircraft
Electric Aircraft Market