
 Middle-East and Africa Business Jet Market | 2026-2036
Middle-East and Africa Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Business Jet Market Foresight
Aircraft maintenance technician pipelines across the Middle-East and Africa region are collapsing, creating acute bottlenecks for scheduled inspections and avionics retrofits that operators must resolve to sustain fleet readiness. Gulfstream Aerospace Corporation dominates the ultra-long-range segment through its in-house completion centers and direct sales presence in Dubai. Bombardier Inc. leverages its Challenger and Global platforms to anchor corporate fleet renewals across Riyadh and Jeddah. Dassault Aviation SA differentiates through Falcon trijet fuel efficiency, a decisive factor for operators navigating Europe-bound routes from African departure points.
Business jets comprise turbine-powered aircraft configured for private or corporate transport, typically featuring pressurized cabins, integrated avionics suites, and range capabilities spanning 1,500 to 7,500 nautical miles depending on airframe class. These assets serve time-sensitive executive mobility, medical evacuation, and government transport missions where schedule control outweighs commercial airline constraints. Large jets and ultra-long-range jets command the dominant share of regional order backlogs, reflecting Gulf-based buyer preference for intercontinental nonstop capability. Light jets sustain faster growth trajectories in secondary African markets where runway limitations and lower utilization rates favor smaller acquisition footprints and reduced operating economics.
The General Civil Aviation Authority of the UAE enforces stringent operational specifications for business aviation within Dubai and Abu Dhabi airspace, while Saudi Arabia's General Authority of Civil Aviation mandates localization requirements for maintenance providers that reshape vendor selection criteria. EASA-aligned airworthiness standards from Europe influence import certification pathways for new deliveries entering North African registers. Operators and lessors must monitor evolving carbon-offset mandates and sustainable aviation fuel blending requirements across Gulf jurisdictions, as these frameworks will determine aircraft residual values and operating permissions through the forecast horizon.
Market Dynamics
The Middle-East and Africa business jet market faces acute pressure from collapsing aircraft maintenance technician pipelines, a structural force that threatens fleet readiness across Gulf Cooperation Council registers while sovereign wealth offices accelerate discretionary travel demand.
Growth Catalysts
- Ultra-long-range fleet renewal:High-net-worth individuals across the United Arab Emirates and Saudi Arabia prioritize intercontinental nonstop capability for diplomatic missions and executive mobility.
- GCAA emissions protocols:The General Civil Aviation Authority of the UAE has tightened noise-abatement standards around Dubai and Abu Dhabi airports, compelling operators toward newer-generation airframes with reduced acoustic footprints.
- FBO infrastructure expansion:Dedicated business aviation terminals in Riyadh and Jeddah now outpace competing regional hubs, anchoring corporate fleet consolidation decisions.
Market Restraints
- Maintenance technician scarcity:Pipeline collapse for airframe and powerplant certificated mechanics extends scheduled inspection turnaround times across the Gulf Cooperation Council.
- Import certification friction:EASA-aligned airworthiness standards from Europe create documentation bottlenecks for new deliveries entering North African registers.
- Carbon-offset compliance costs:Evolving sustainable aviation fuel blending requirements across Gulf jurisdictions compress operating margins for legacy fleet operators.
Strategic Opportunities
- Secondary African market penetration:Light jets address runway limitations and lower utilization rates in markets where acquisition footprints must shrink.
- Avionics retrofit demand:Next-generation integrated suites enable compliance with GCAA operational specifications while extending residual values for mid-life airframes.
- Localization mandates:Saudi Arabia's General Authority of Civil Aviation maintenance provider requirements reshape vendor selection criteria toward domestic joint ventures.
Industry Challenges
- Certified mechanic attrition:Gulf-based completion centers and MRO facilities compete for scarce airframe specialists against commercial airline recruitment.
- Residual value uncertainty:Carbon-offset frameworks and sustainable aviation fuel mandates through the forecast horizon complicate lease-end valuation models for lessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Business Jet Market |
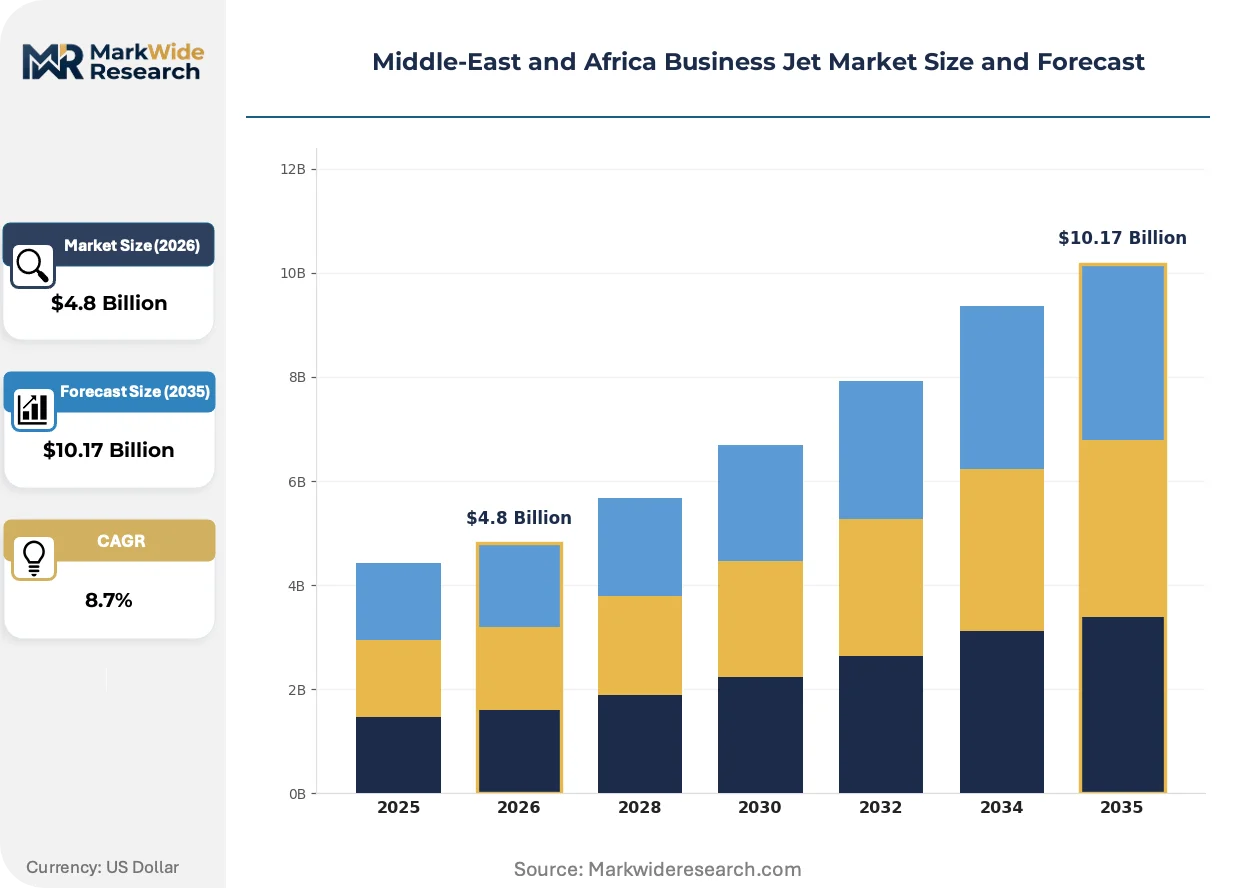
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jet, Midsize Jet, Large Jet, Ultra Long Range Jet End User: Corporate, Individual Owners, Aircraft Charter, Government Operating Model: Fractional Ownership, Full Ownership, Leasing, Charter Services Market Segment: Commercial Aviation, Private Aviation, Military Aviation, Offshore Operations |
| Companies Covered | Airbus SE, Embraer SA, Gulfstream Aerospace Corporation, ExecuJet, Empire Aviation Group, Bombardier Inc., Textron Inc., Qatar Executive, Dassault Aviation SA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Business Jet Market Shifts & Advancements
Propulsion efficiency mandates and sovereign buyer preferences for intercontinental range are compressing the competitive window for legacy airframe architectures across Middle-East and Africa registers.
Next-generation turbofan architectures with reduced specific fuel consumption are supplanting earlier powerplant designs in Gulf-based fleet planning. Sovereign wealth offices and corporate flight departments now specify these engines as baseline requirements for new acquisitions. The shift is compressing demand for pre-owned large-cabin aircraft equipped with legacy propulsion systems.
The General Civil Aviation Authority of the UAE has implemented stringent operational specifications for business aviation within Dubai and Abu Dhabi airspace. These protocols mandate advanced navigation performance and emissions monitoring capabilities for slot allocation priority. Operators are responding by accelerating avionics retrofit schedules and prioritizing airframes with factory-installed compliant systems.
Fractional ownership models are displacing traditional whole-aircraft acquisition among mid-tier corporate users across Saudi Arabia and the United Arab Emirates. Flight departments now favor access programs that reduce capital commitment while preserving schedule control. This behavioral shift is most visible in Riyadh and Jeddah, where corporate users previously dominated direct purchase backlogs.
Middle-East and Africa Business Jet Market Segmentation
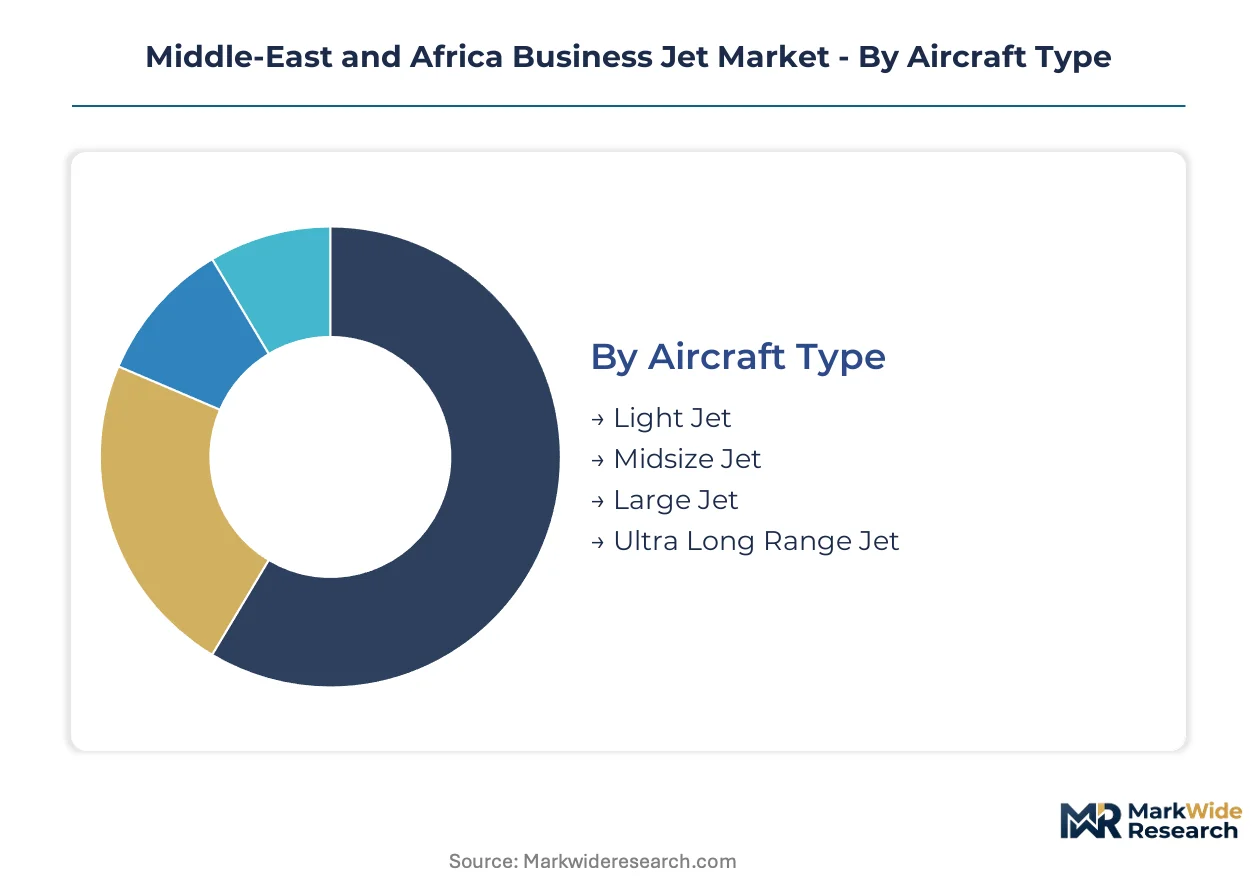
Segmentation in the Middle-East and Africa business jet market reveals divergent margin profiles across aircraft classes and operating models. Gulf-based sovereign buyers and African corporate operators prioritize different capability bundles, reshaping vendor pricing power and aftermarket revenue streams.
Aircraft Type:
Margin pools concentrate in the upper cabin tiers where completion customization and long-range performance command premium positioning.
- Light Jet:These aircraft typically accommodate 4-7 passengers with range capabilities of 1,500-2,500 nautical miles and operate from shorter runways. Demand concentrates in secondary African markets including Lagos and Nairobi where infrastructure constraints limit larger aircraft access and lower utilization rates favor reduced operating economics.
- Midsize Jet:Configured for 7-9 passengers with transcontinental range spanning 2,500-3,500 nautical miles and stand-up cabins. Charter operators across Dubai and Riyadh favor this class for regional missions where payload flexibility and operating cost discipline outweigh intercontinental requirements.
- Large Jet:Deliver 12-16 passenger capacity with 4,000-5,500 nautical mile range and full-service galleys.
- Ultra Long Range Jet:Enable 6,000-7,500 nautical mile nonstop missions with sleeping configurations for 12-19 passengers.
Ultra Long Range Jet holds installed capacity across Gulf Cooperation Council registers. Light Jet is rotating up the share rankings in African markets with runway-constrained infrastructure.
End User:
Volume concentration sits with institutional buyers whose procurement cycles drive fleet renewal waves and residual value benchmarks.
- Corporate:Flight departments of multinational energy, finance, and construction conglomerates operating 2-12 aircraft fleets. Saudi Aramco and Emirates Group aviation divisions anchor demand in the United Arab Emirates and Saudi Arabia where schedule control for executive mobility justifies dedicated lift.
- Individual Owners:High-net-worth families and private offices acquiring single aircraft for personal transport and asset diversification. Dubai-based family offices increasingly specify ultra-long-range platforms for European and Asian destination access without commercial airline constraints.
- Aircraft Charter:Commercial operators selling per-flight access to non-owners through on-demand or membership programs.
- Government:State flight units transporting heads of state, diplomatic delegations, and military leadership.
Corporate holds installed capacity across established Gulf fleet bases. Individual Owners is climbing the fastest as fractional and jet card programs lower capital barriers.
Operating Model:
Revenue stability varies sharply across ownership structures, with asset-light models capturing growth in capital-constrained segments.
- Fractional Ownership:Programs providing 50-400 annual flight hour access to a shared aircraft pool without full acquisition burden. Mid-tier corporate users across Riyadh and Jeddah favor this structure for preserving balance sheet capacity while maintaining schedule priority over commercial charter.
- Full Ownership:Direct aircraft acquisition with dedicated crew and hangar infrastructure. Sovereign wealth offices and ruling family offices in Abu Dhabi and Doha dominate this segment, specifying bespoke completion and dedicated maintenance programs.
- Leasing:Operating lease structures transferring residual value risk to lessors while preserving operational flexibility.
- Charter Services:Ad-hoc per-flight procurement without ongoing capital commitment or hour purchase obligations.
Full Ownership holds installed capacity among established Gulf operators. Fractional Ownership is gaining share fastest as corporate finance teams scrutinize capital efficiency metrics.
Market Segment:
Application context determines regulatory pathway and operational specification intensity, with military and offshore carrying distinct certification burdens.
- Commercial Aviation:Revenue-generating operations subject to air operator certificate requirements and scheduled service regulations. Charter and fractional providers across the United Arab Emirates fall under GCAA operational specifications with stringent crew training and maintenance oversight protocols.
- Private Aviation:Non-commercial transport for corporate or personal purposes with reduced regulatory burden. Individual owners and corporate flight departments in Saudi Arabia operate under GACA private aircraft rules with simplified dispatch requirements.
- Military Aviation:Government flight units with defense-specific communications and defensive systems.
- Offshore Operations:Personnel transport to oil and gas installations with specialized equipment and training mandates.
Private Aviation holds installed capacity across the regional fleet register. Commercial Aviation is expanding most quickly as charter platforms professionalize and scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
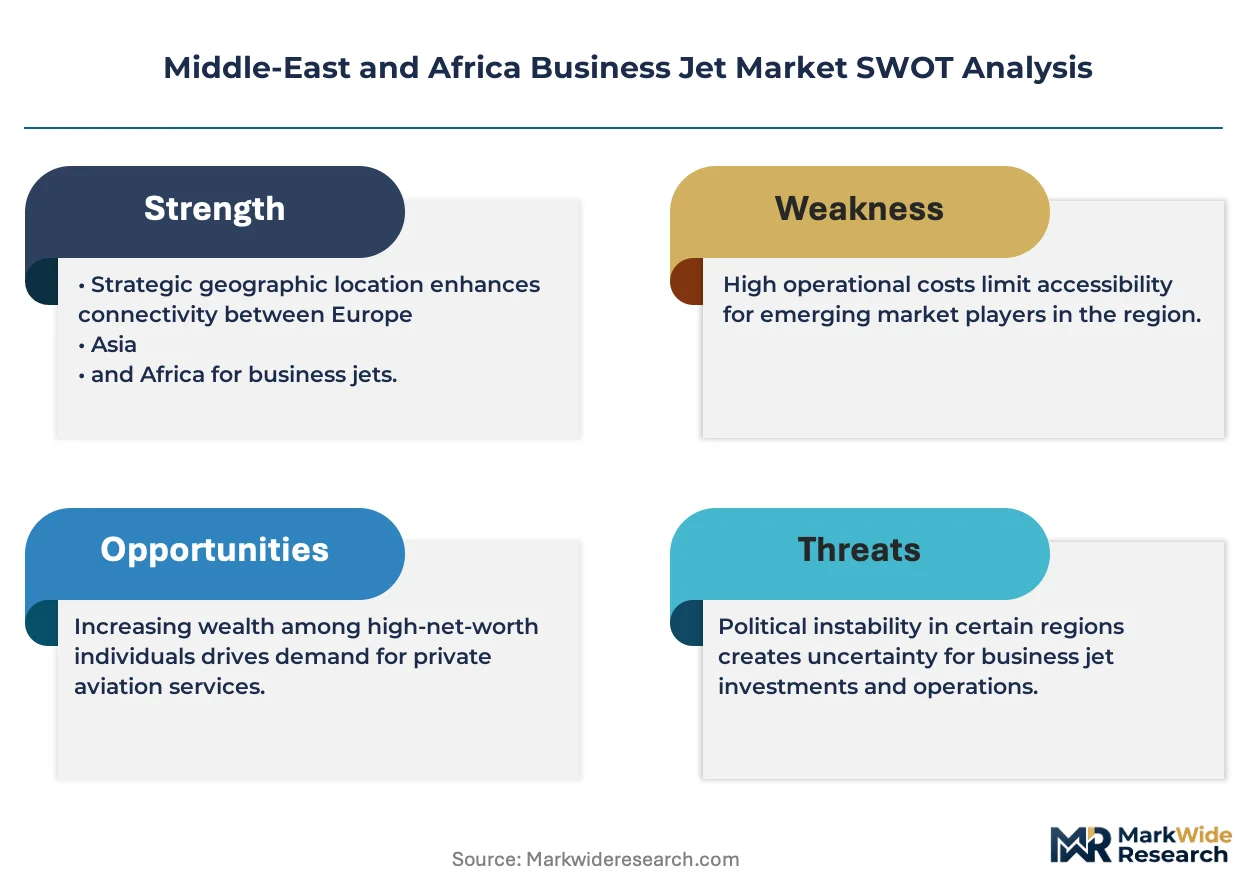
The General Civil Aviation Authority of the UAE anchors regulatory frameworks that cascade across Gulf Cooperation Council jurisdictions, establishing airworthiness and emissions benchmarks that operators throughout the region must satisfy.
United Arab Emirates
Sovereign wealth offices and ruling family offices in Dubai and Abu Dhabi drive ultra-long-range fleet acquisitions for intercontinental diplomatic missions. The General Civil Aviation Authority enforces noise-abatement protocols that compel operators toward newer-generation airframes. Dubai's dedicated business aviation terminals and FBO infrastructure outpace competing regional hubs, consolidating corporate flight department activity in the emirate.
Saudi Arabia
Corporate flight departments of Saudi Aramco and multinational energy conglomerates anchor large-cabin fleet demand for executive mobility across Riyadh and Jeddah. The General Authority of Civil Aviation mandates localization requirements for maintenance providers that reshape vendor selection toward domestic joint ventures. Riyadh's expanding dedicated business aviation terminals now rival Dubai for corporate fleet consolidation decisions.
Qatar
State flight units and diplomatic delegations sustain government transport demand for heads of state missions requiring intercontinental nonstop capability. The Qatar Civil Aviation Authority aligns operational specifications with GCAA frameworks while maintaining distinct slot allocation protocols for Doha airspace. State-backed aviation services in Doha concentrate completion and maintenance activity for Gulf-based sovereign buyers.
South Africa
Corporate mining houses and resource extraction conglomerates in Johannesburg and Cape Town sustain midsize jet demand for regional executive mobility across sub-Saharan Africa. The South African Civil Aviation Authority applies EASA-aligned airworthiness standards that create documentation friction for new deliveries entering the register. Johannesburg's business aviation infrastructure serves as the southern African hub for charter operators addressing runway-constrained secondary markets.
Nigeria
Energy sector executives and banking conglomerates in Lagos drive light jet demand where infrastructure constraints limit larger aircraft access and lower utilization rates favor reduced operating economics. The Nigerian Civil Aviation Authority enforces operational specifications that lag GCC stringency, extending residual value lifecycles for mid-life airframes. Lagos and Abuja concentrate fractional ownership program growth as capital-constrained corporate users seek schedule control without full acquisition burden.
Middle-East and Africa Business Jet Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa business jet market. The vendor base concentrates around airframe OEMs with direct sales presence in Dubai and Riyadh, completion centers with captive customization capabilities, and regional operators with fleet scale advantages. Three strategic archetypes dominate: ultra-long-range specialists with factory-installed compliant systems, midsize platform providers serving charter consolidation demand, and integrated aviation services groups bundling management with access programs. Competitive moves center on avionics retrofit partnerships for GCAA compliance and localization joint ventures satisfying Saudi maintenance mandates.
Among airframe OEMs with Gulf-based direct sales presence, Gulfstream Aerospace Corporation, Bombardier Inc., and Dassault Aviation SA exemplify the ultra-long-range specialist archetype. Gulfstream occupies a position anchored by in-house completion centers in Dubai serving sovereign buyer customization requirements. Bombardier represents the platform breadth approach spanning Challenger regional missions through Global intercontinental capability. Dassault exemplifies fuel efficiency differentiation through trijet architectures that operators prioritize for Europe-bound routes from African departure points.
| Leading Market Players |
|---|
| Airbus SE |
| Embraer SA |
| Gulfstream Aerospace Corporation |
| ExecuJet |
| Empire Aviation Group |
| Bombardier Inc. |
| Textron Inc. |
| Qatar Executive |
| Dassault Aviation SA |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Gulf-based sovereign buyers and airframe OEMs lock in delivery slots and price visibility across multi-year fleet renewal cycles. These contracts insulate operators from spot-market volatility while committing capital to specific completion specifications and maintenance bundling terms.
Pricing Analysis
Price spreads between Dubai and Lagos exceed thirty percent for equivalent light-jet configurations, reflecting import certification friction and logistics premiums for African delivery. Three-tier pricing structure across premium, standard, and economy levels separates factory-new Gulfstream G700 deliveries from mid-life Challenger retrofits and pre-owned Citation airframes. Pricing pressure stems from collapsing technician pipelines that extend MRO turnaround times and compress residual values for legacy fleet operators. Corporate flight departments in Riyadh exhibit lowest price sensitivity due to balance-sheet capacity, while Nigerian fractional users face acute capital constraints.
Supply Chain Analysis
Inbound logistics costs through Jebel Ali port congestion and container availability constraints on Asia-Gulf trade lanes inflate avionics component lead times. Manufacturing concentration rests on the United States, France, and Canada for airframe assembly, with engine production anchored in the United States and United Kingdom. Supply chains draw from titanium forgings, composite prepregs, and semiconductor-grade navigation chips as critical inputs. Single-source vulnerability concentrates in engine OEM proprietary maintenance protocols. Distribution runs through Dubai-based completion centers and Riyadh MRO joint ventures for regional fleet support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business aviation incumbents must defend against fractional ownership platforms and premium commercial airline cabin products that substitute for whole-aircraft acquisition among capital-constrained corporate users.
For Market Incumbents: Shield installed base relationships through captive maintenance contracts that lock in airframe and powerplant work amid technician scarcity. Deepen backward integration into avionics retrofit capabilities to capture GCAA compliance mandates. Prioritize completion center capacity in Dubai to preserve sovereign buyer access against Bombardier and Dassault direct sales presence.
For New Entrants and Emerging Players: Avionics retrofit service gaps in secondary African markets present white-space entry points where OEM-authorized networks under-serve mid-life airframe operators. Target Lagos and Nairobi charter bases with portable compliance solutions for EASA-aligned import certification. Deploy mobile maintenance units as go-to-market angle to bypass fixed infrastructure requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated aviation services groups with fleet management and fractional access program bundling. Long-term viability hinges on residual value capture through lease-end remarketing capabilities. Monitor sustainable aviation fuel blending mandate announcements across Gulf jurisdictions as inflection indicator for legacy fleet write-down risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Localization Joint Venture | Satisfies GACA maintenance provider mandates while securing sovereign buyer relationships in Riyadh. |
| Avionics Retrofit Partnership | Enables GCAA operational specification compliance for mid-life airframes across Dubai registers. |
| Fractional Platform Launch | Captures capital-constrained corporate demand in Jeddah without whole-aircraft balance-sheet burden. |
| Completion Center Expansion | Preserves customization revenue from ultra-long-range orders by Abu Dhabi ruling family offices. |
| Sustainable Aviation Fuel Certification | Positions fleet operators for carbon-offset compliance across evolving UAE emissions frameworks. |
Research Methodology
Operator-level perspectives from flight department directors, MRO facility managers, FBO operators, and GCAA regulatory affairs leads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through GCAA operational bulletins, GACA localization directives, EASA airworthiness standards, and customs import records for business jet registrations. Bottom-up fleet counts triangulated against top-down OEM delivery disclosures to reconcile volume estimates.
Sensitivity analysis tested forecast outputs against variable assumptions for technician pipeline recovery rates and sustainable aviation fuel mandate implementation timing across the projection horizon. Segmentation dimensions modeled include aircraft type, end-user archetype, operating model structure, and market segment classification. CAGRs were derived from regression analysis of historical delivery patterns and projected replacement demand. Forecast inputs incorporated sovereign wealth office capital allocation disclosures and corporate flight department fleet planning cycles.
Underlying assumptions cover stable diplomatic travel demand and gradual technician training program expansion, with deviation risk concentrated in accelerated carbon-offset enforcement or regional conflict disruption to airspace access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Cables Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Commercial Helicopter Market
Aircraft
Attack Helicopter Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Water Bomber Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Airship Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Airplane Landing Gear Market
Aircraft
Latin America Business Jet Market
Aircraft
Japan Aviation Market