
 Aircraft Strut Market | 2026-2036
Aircraft Strut Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Strut Market Outlook
Buyer concentration among aerospace OEMs is recalibrating procurement leverage across the aircraft strut supply base. Safran Landing Systems leverages integrated landing gear platforms to sustain long-term contracts with Airbus and Boeing. Liebherr-Aerospace anchors European supply through specialized hydraulic and electromechanical actuation systems. Parker-Hannifin Corporation competes on fluid power integration, extending its position across multiple aircraft platforms.
An aircraft strut is a structural compression member engineered to absorb landing impact loads and support airframe weight during ground operations, typically manufactured from high-strength aluminum alloys or titanium through precision forging and CNC machining to meet strict fatigue-life specifications. Titanium struts now lead military aviation applications where strength-to-weight ratios justify premium material costs, while composite-reinforced designs represent the fastest-growing material segment driven by next-generation narrow-body programs. Fixed installation types remain the mature volume base, though modular installation architectures are capturing margin pools through reduced MRO turnaround times.
FAA airworthiness standards, EASA CS-25 certification requirements, and ISO 9001/AS9100 quality frameworks collectively govern material traceability, fatigue testing protocols, and supplier qualification pathways for aircraft strut manufacturers. These regulatory layers elevate barriers for new entrants while compelling incumbents to maintain redundant testing infrastructure across multiple jurisdictions. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and emerging FAA initiatives targeting reduced-carbon manufacturing processes as these will reshape material selection and supplier qualification criteria.
Market Dynamics
Narrow-body fleet renewal cycles are compressing supplier qualification timelines while simultaneously elevating fatigue-test standards, forcing strut manufacturers to absorb dual pressures of accelerated delivery and enhanced certification rigor.
Growth Catalysts
- FAA Airworthiness Directives:Updated landing gear assembly mandates are expanding testing infrastructure investment across domestic supplier networks, elevating certified capacity.
- Titanium adoption:Military aviation programs are prioritizing strength-to-weight performance in next-generation fighter platforms, sustaining premium material demand.
- United States MRO concentration:Boeing's domestic maintenance networks are anchoring component sourcing volumes, reinforcing regional procurement gravity.
Market Restraints
- Titanium price volatility:Sponge and mill product cost swings compress margin predictability for alloy-dependent manufacturers.
- Supplier concentration in Wichita-Kansas aerospace cluster:Single-region forging capacity creates geographic vulnerability to weather or labor disruptions.
- Fatigue-test duration:Extended certification cycles for new alloy formulations delay revenue recognition on developmental contracts.
Strategic Opportunities
- Composite-reinforced architectures:Next-generation narrow-body programs are qualifying hybrid material struts, opening design differentiation pathways.
- Modular installation systems:Line-replaceable unit formats are capturing aftermarket margin pools through reduced turnaround time value propositions.
- EU Green Deal manufacturing mandates:Reduced-carbon process certification is creating first-mover advantage for European suppliers with electrified forging operations.
Industry Challenges
- AS9100 auditor scarcity:Qualified third-party certification bodies face backlog, extending supplier qualification timelines.
- Legacy platform documentation:Aging airframe technical data packages complicate reverse-engineering for obsolescence management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Strut Market |
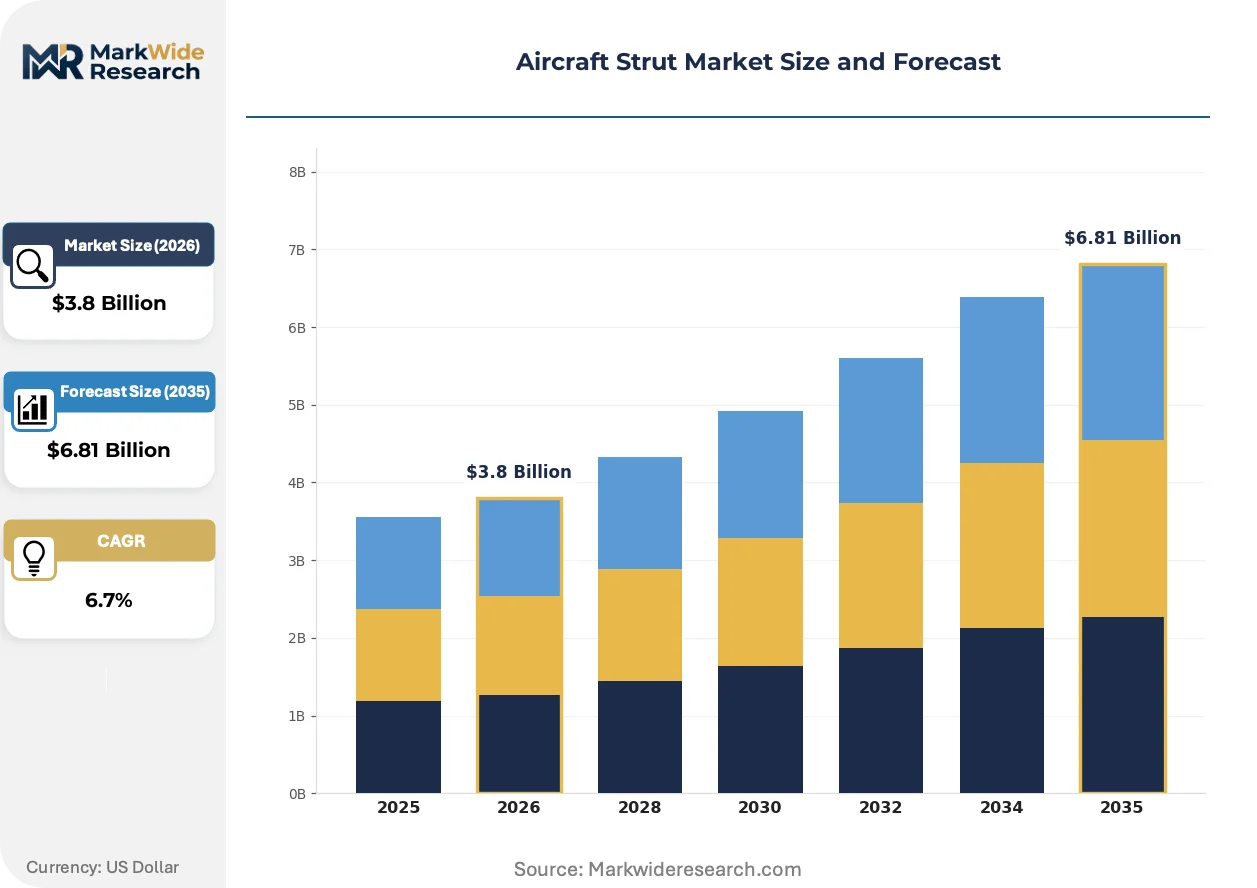
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Struts, Horizontal Struts, Angle Struts, Truss Struts Material: Aluminum, Steel, Titanium, Composite End User: Civil Aviation, Military Aviation, Aerospace OEMs, Aftermarket Providers Installation Type: Fixed Installation, Removable Installation, Modular Installation, Integrated Installation |
| Companies Covered | Safran Landing Systems, Collins Aerospace, Liebherr-Aerospace, Parker-Hannifin Corporation, Héroux-Devtek Inc., Triumph Group, CIRCOR International, Eaton Corporation, GKN Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Strut Market Strategic Shifts
Digital thread integration across design-for-manufacturing workflows is compressing iteration cycles while simultaneously enabling predictive fatigue modeling that reduces physical test iterations.
Additive manufacturing qualification for titanium strut brackets is automating topology optimization workflows that previously required manual finite-element refinement. Defense prime contractors are piloting these processes for low-volume military applications where lot sizes justify process development costs. The technology is automating geometric complexity realization that conventional subtractive methods cannot economically achieve.
EU Green Deal industrial emissions benchmarks are mandating furnace electrification and renewable energy sourcing for AS9100-certified suppliers serving Airbus platforms. Manufacturers in Germany and France are retrofitting forging operations to meet carbon-intensity thresholds. Narrow-body program suppliers face the steepest compliance curves given volume exposure and margin pressure.
Power-by-the-hour contracts are consolidating component procurement under airframe OEM direct sourcing, bypassing traditional tier-two distributor channels. Regional airline lessors are driving this consolidation to unify fleet configuration and simplify warranty administration. Latin American and Southeast Asian carrier fleets exhibit the fastest adoption of this consolidated sourcing model.
Aircraft Strut Market Segmentation
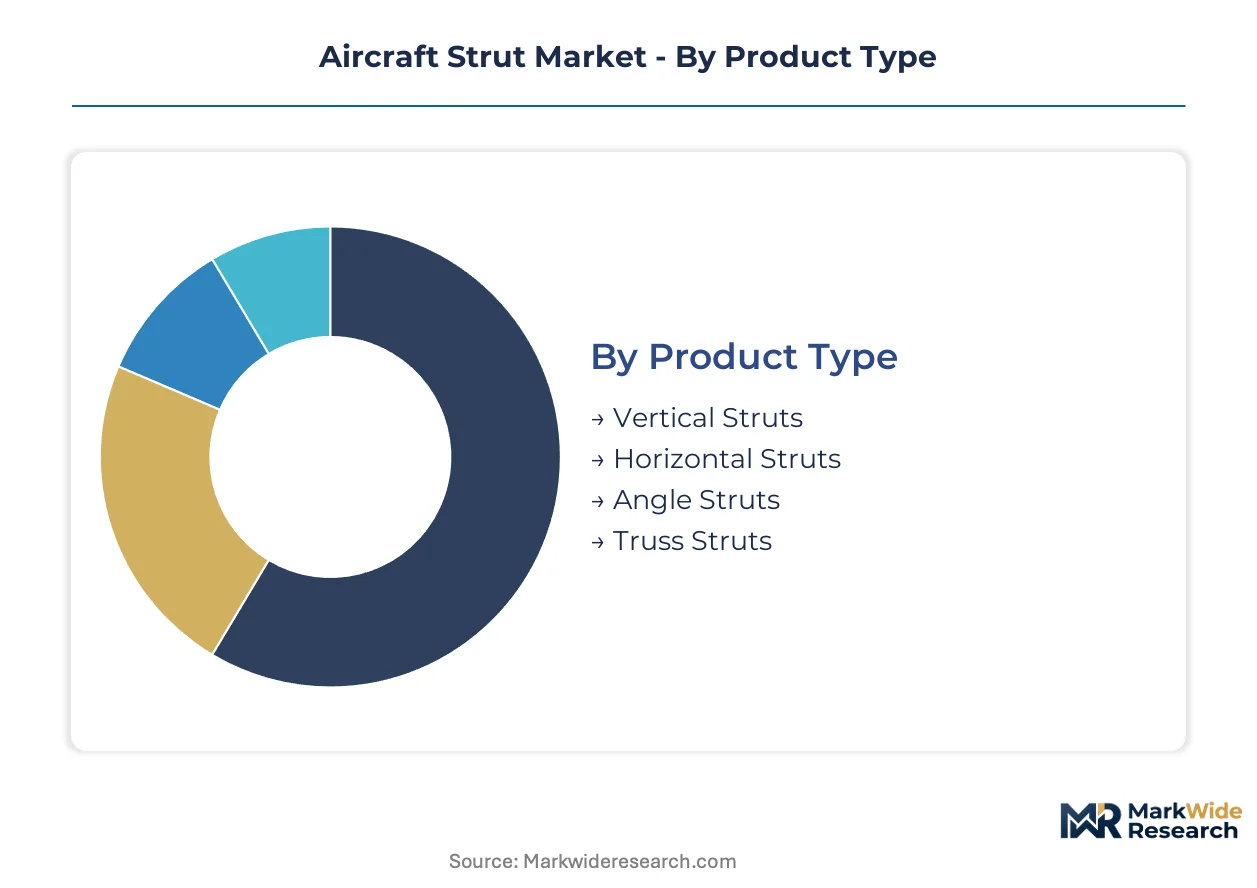
Aircraft strut segmentation reflects divergent certification burdens across product architectures and material grades. FAA and EASA fatigue-test protocols vary substantially by installation criticality and alloy composition, reshaping supplier qualification economics.
Product Type:
Certification intensity escalates with structural load-bearing responsibility, with primary compression members facing extended FAA airworthiness directive compliance cycles compared to secondary bracing elements.
- Vertical Struts:Primary compression members engineered to absorb vertical landing impact loads through precision-forged aluminum or titanium construction. Boeing's 737 MAX and Airbus A320neo programs anchor demand in the United States and France, where OEM direct sourcing consolidates procurement leverage.
- Horizontal Struts:Lateral bracing components stabilizing landing gear assemblies against side-loads during ground maneuvers, typically manufactured from high-strength aluminum alloys. Wichita-Kansas aerospace cluster suppliers dominate forging capacity for this mature volume base.
- Angle Struts:Diagonal reinforcement members bridging vertical and horizontal assemblies in complex landing gear geometries.
- Truss Struts:Lattice-structured bracing systems for legacy wide-body platforms with distributed load-path requirements.
Leading the category by volume: Horizontal Struts. Growing fastest: Vertical Struts.
Material:
Cost tier stratification separates premium titanium grades from commodity aluminum, with composite formulations commanding development premiums for next-generation narrow-body qualification.
- Titanium:Mill products deliver superior strength-to-weight ratios for fighter jet landing gear where performance justifies sponge price volatility. Military aviation programs in the United States sustain premium demand despite margin compression from raw material cost swings.
- Composite:Carbon-fiber-reinforced architectures are qualifying for hybrid strut designs on next-generation narrow-body programs, with Airbus suppliers in Germany and France retrofitting facilities for EU Green Deal compliance.
- Aluminum:High-strength alloys remain the commercial aviation workhorse for fatigue-life economics.
- Steel:Legacy wide-body and cargo applications where weight penalties are secondary to absolute load capacity.
Highest margin pool: Titanium. Steepest expansion trajectory: Composite.
End User:
Customer type determines contract structure, with aerospace OEMs demanding integrated landing gear platforms while aftermarket providers prioritize line-replaceable unit interchangeability.
- Aerospace OEMs:Boeing and Airbus anchor procurement volumes through multi-year landing gear platform contracts, with Safran Landing Systems and Liebherr-Aerospace competing on integrated system qualification. Direct sourcing bypasses traditional tier-two channels as power-by-the-hour contracts consolidate component procurement.
- Aftermarket Providers:MRO networks in the United States concentrate component demand through reduced turnaround time value propositions, with modular installation architectures capturing margin pools.
- Civil Aviation:Commercial airline fleet operators driving narrow-body renewal cycles.
- Military Aviation:Defense prime contractors prioritizing titanium performance for next-generation fighter platforms.
Contract concentration peaks with: Aerospace OEMs. Fastest channel shift: Aftermarket Providers.
Installation Type:
Supply concentration clusters around fixed installation maturity, while modular architectures require new forging investments for line-replaceable unit compatibility.
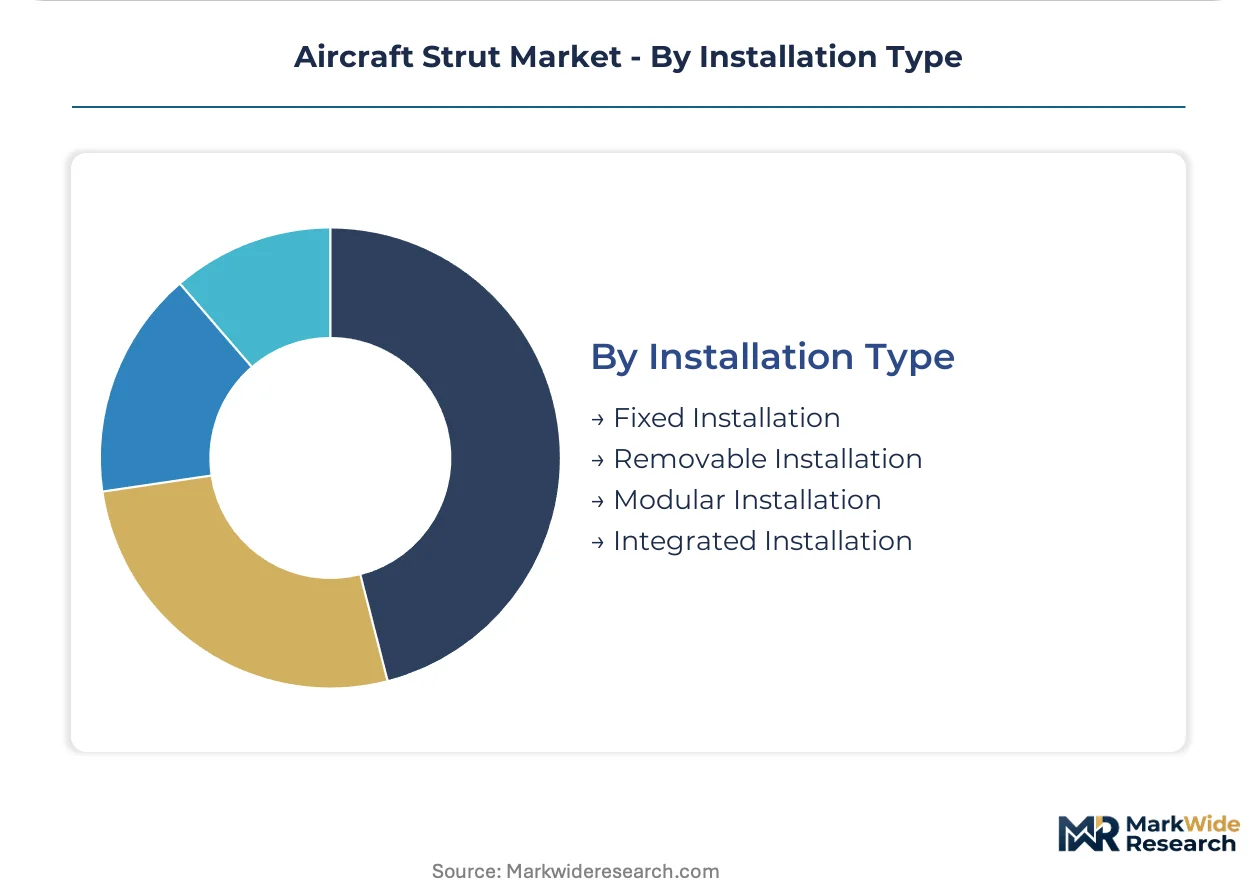
- Fixed Installation:Permanent structural integration dominates existing fleet configurations, with Wichita-Kansas forging capacity supporting high-volume commercial programs. Legacy airframe technical data packages complicate obsolescence management for aging platforms.
- Modular Installation:Line-replaceable unit formats reduce MRO turnaround times through standardized interface geometries, with regional airline lessors in Latin America and Southeast Asia driving fastest adoption.
- Removable Installation:Field-serviceable configurations for expeditionary military applications.
- Integrated Installation:Landing gear system-level packaging by tier-one suppliers.
Volume anchor: Fixed Installation. Margin expansion zone: Modular Installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement leverage from Boeing's supply chain anchors United States demand, while Airbus qualification pathways concentrate supplier investment in France and Germany. Regulatory divergence between FAA airworthiness standards and EASA certification protocols shapes regional qualification economics.
United States
Boeing's 737 MAX and 767 programs sustain landing gear platform procurement through Wichita-Kansas forging clusters. FAA airworthiness directives for landing gear assemblies mandate redundant fatigue-testing infrastructure across domestic supplier networks. The Wichita aerospace corridor concentrates titanium and aluminum forging capacity for commercial and military aviation strut production.
France
Airbus A320neo and A350 programs anchor integrated landing gear system demand through Toulouse-based supply chains. EASA CS-25 certification requirements govern material traceability and fatigue-test protocols for European-qualified suppliers. The Occitanie region hosts specialized forging operations retrofitting for EU Green Deal carbon-intensity thresholds.
Germany
Liebherr-Aerospace anchors hydraulic and electromechanical actuation supply for Airbus narrow-body platforms through Lindenberg and Toulouse facilities. EU Green Deal industrial emissions benchmarks mandate furnace electrification for AS9100-certified suppliers serving German aerospace primes. Bavaria and Baden-Württemberg concentrate precision machining capacity for titanium strut brackets.
United Kingdom
GKN Aerospace sustains structural component supply for legacy and next-generation platforms through western England manufacturing bases. The UK's national aerospace regulator enforces fatigue-life specifications aligned with EASA frameworks post-Brexit transition. The Midlands aerospace cluster maintains forging and CNC machining capacity for commercial aviation strut production.
Japan
Defense prime contractors prioritize titanium performance for next-generation fighter landing gear through domestic supply chains. METI industrial standards coordinate with JIS certification requirements for high-strength alloy procurement. The Chubu region around Nagoya concentrates precision forging capacity for aerospace structural components.
Aircraft Strut Market Competitive Environment
United States producers anchor one tier of the supply base; European specialists hold integrated system qualification pathways. The vendor base concentrates around landing gear platform providers with multi-year OEM contracts, creating tiered access to narrow-body program volumes. Three archetypes dominate: integrated landing gear system houses, precision forging specialists, and fluid power integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for next-generation narrow-body qualification.
Among integrated system providers, Safran Landing Systems and Liebherr-Aerospace occupy positions defined by long-term platform contracts with Airbus and Boeing. Parker-Hannifin Corporation sits within the fluid power integration tier, extending positioning across multiple aircraft programs. These three exemplify how geographic anchoring and certification breadth determine competitive access to OEM direct sourcing channels.
| Leading Market Players |
|---|
| Safran Landing Systems |
| Collins Aerospace |
| Liebherr-Aerospace |
| Parker-Hannifin Corporation |
| Héroux-Devtek Inc. |
| Triumph Group |
| CIRCOR International |
| Eaton Corporation |
| GKN Aerospace |
| Others |
Value Chain & Pricing Dynamics
Precision forging machinist concentrations in Wichita-Kansas and Occitanie-France create labor-cost differentials that widen pricing-tier spreads between AS9100-certified premium suppliers and commodity aluminum forging operations serving secondary bracing components.
Pricing Analysis
Volume-mature horizontal strut production anchors economy-tier pricing, while vertical strut qualification for Boeing 737 MAX and Airbus A320neo programs commands premium-mid-economy pricing differentiation based on fatigue-test certification depth and OEM direct-sourcing status. Price differentiation hinges on titanium grade certification and EASA CS-25 compliance tier, with EU Green Deal carbon-intensity thresholds adding compliance premiums for European suppliers. Pricing pressure stems from titanium sponge cost volatility compressing margin predictability for alloy-dependent manufacturers. Regional airline lessors in Latin America exhibit highest price sensitivity through power-by-the-hour contract consolidation, while military aviation programs demonstrate lowest sensitivity given performance-driven procurement mandates.
Supply Chain Analysis
Workforce availability constraints in Wichita-Kansas, Toulouse-France, and Nagoya-Japan concentrate precision forging capacity for aerospace-grade titanium and aluminum mill products. Raw material flows draw from titanium sponge producers, high-strength aluminum alloy mills, and carbon-fiber prepreg suppliers for composite-reinforced development programs. Single-region forging concentration in the Wichita aerospace corridor creates geographic vulnerability to weather disruptions and labor actions. Distribution runs through tier-one landing gear system houses with multi-year OEM platform contracts, bypassing traditional tier-two distributor channels as power-by-the-hour arrangements consolidate component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft strut market sits in a materials-transition phase, with composite-reinforced architectures displacing conventional aluminum forging in next-generation narrow-body qualification pathways.
For Market Incumbents: Hedge titanium price exposure through long-term mill product offtake agreements with sponge suppliers in the United States and Japan. Secure redundant AS9100 certification capacity across multiple jurisdictions to mitigate auditor backlog delays. Deepen backward integration into precision forging operations in the Wichita-Kansas corridor to defend margin position against modular installation competitors capturing aftermarket pools. For New Entrants and Emerging Players: Begin with composite-reinforced strut qualification for Airbus next-generation narrow-body programs in Germany and France, where EU Green Deal electrified forging mandates create first-mover advantage for low-carbon process certification. Target aftermarket modular installation architectures serving regional airline lessors in Southeast Asia, where power-by-the-hour contract adoption concentrates demand for line-replaceable unit interchangeability. Pursue joint development agreements with tier-one landing gear system houses rather than direct OEM qualification pathways. For Investors and Strategic Acquirers: Re-rating potential sits with precision forging specialists possessing EASA CS-25 and FAA dual-certification breadth given narrowing qualified supplier pools and extended qualification timelines. Long-term viability over the next decade favors operations with EU Green Deal compliance infrastructure already deployed. Monitor titanium sponge price inflection and AS9100 auditor capacity expansion as signals for margin recovery timing in the premium alloy segment.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification | Airbus A320neo suppliers in Germany retrofit facilities for hybrid strut certification under EU Green Deal mandates. |
| Modular Installation Architecture Development | Line-replaceable unit formats capture aftermarket margin pools through reduced MRO turnaround times for regional lessors. |
| Dual-Jurisdiction Certification Investment | Redundant FAA and EASA fatigue-testing infrastructure insulates against auditor scarcity extending qualification timelines. |
| Titanium Sponge Supply Agreement | Long-term offtake contracts with U.S. and Japanese mill product producers hedge raw material cost volatility exposure. |
| Electrified Forging Retrofit | Furnace electrification and renewable energy sourcing secure AS9100 certification for EU Green Deal carbon-intensity thresholds. |
Study Parameters
Multi-period observation of FAA airworthiness directive issuance patterns, EASA CS-25 certification timeline data, and titanium sponge price indices anchored the trend analysis, supplemented by interviews with landing gear platform engineers at Boeing and Airbus, procurement directors at Safran Landing Systems and Liebherr-Aerospace, MRO network managers in the United States, and precision forging plant managers in Wichita-Kansas and Occitanie-France. Secondary validation drew from FAA certification databases, EASA type certificate records, SEC 10-K filings from listed aerospace suppliers, and EU Green Deal industrial emissions benchmark disclosures. Bottom-up segment sizing triangulated against top-down OEM delivery forecasts across the analysis window.
Segment-weighting approaches modeled product type stratification across vertical, horizontal, angle, and truss strut architectures; material grade tiering across titanium, composite, aluminum, and steel formulations; end-user channel structure across aerospace OEM direct sourcing and aftermarket MRO networks; and installation type configuration across fixed and modular formats. CAGRs were derived from installed base renewal cycle analysis and narrow-body program delivery schedules. Industry-specific forecast inputs incorporated fatigue-test protocol evolution and EU Green Deal manufacturing mandate compliance curves.
Titanium price volatility, EASA-FAA regulatory divergence, and composite material qualification delays are the dominant revision risks that could compress or extend projected market trajectories. Forecasts reflect assumptions regarding OEM delivery schedules and supplier qualification timeline normalization. Material deviation in named triggers warrants pause and re-evaluation of segment-level growth assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aircraft Oxygen System Market
Aircraft
US Military Aviation Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Japan Aviation Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Evtol Aircraft Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Winglets Market
Aircraft
Aviation Market
Aircraft
Tilt Rotor Aircraft Market