
 Global Advanced Drug Delivery Systems Market | 2026-2036
Global Advanced Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Drug Delivery Systems Market Foresight
Capital-intensity divergence between platform developers and device manufacturers is bifurcating competitive returns in advanced drug delivery. Novartis leverages its integrated cell-and-gene therapy infrastructure to control end-to-end nanoparticle production. Baxter anchors its position through sterile manufacturing scale across parenteral delivery formats. Johnson & Johnson competes via diversified exposure spanning biologics, medical devices, and consumer health channels.
Advanced drug delivery systems encompass engineered platforms that modulate pharmacokinetic profiles through controlled release, targeted localization, or stimulus-responsive mechanisms, typically employing lipid, polymer, or inorganic matrices with dimensions from nanometers to micrometers. These systems serve to enhance bioavailability, reduce toxicity, and enable administration of biologics previously limited by instability or immunogenicity. Injectable delivery modes command premium pricing due to biologic compatibility and hospital-centric procurement, while nanoparticle formulations represent the fastest-growing product category as mRNA and gene therapy pipelines mature. Oral sustained-release technologies occupy a mature margin pool dominated by generic erosion, whereas smart delivery systems with sensor-integrated feedback loops concentrate R&D investment from venture-backed developers.
FDA, EMA, and Japan's PMDA collectively shape market access through divergent evidentiary requirements for combination product classification and real-world performance data. The FDA's Breakthrough Device designation and EMA's PRIME eligibility create accelerated pathways that reshape competitive timelines for novel delivery technologies. Stakeholders must monitor evolving biosimilar guidance from these regulators, as interchangeability determinations directly influence investment recoverability for next-generation delivery platforms.
Market Dynamics
Precision oncology pipelines are compressing clinical timelines for nanoparticle platforms, forcing device manufacturers and formulation specialists to synchronize development cycles around biologic launch windows rather than traditional hardware refresh schedules.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated review timelines for novel delivery platforms reduce capital lock-up periods and attract venture funding toward lipid nanoparticle programs.
- Cell therapy manufacturing expansion:Academic medical centers in the United States, Germany, and Japan are retrofitting cleanroom infrastructure to accommodate closed-system infusion devices.
- Biologic instability challenges:mRNA and gene therapy candidates require engineered stabilization matrices that oral and topical formats cannot provide, elevating demand for parenteral delivery innovation.
Market Restraints
- High-purity lipid sourcing concentration:Ionizable lipid production for nanoparticle assembly depends on a limited supplier base concentrated in Switzerland and specialized chemical clusters.
- EMA combination product classification complexity:Divergent evidentiary requirements for device-drug integration create regulatory friction that extends European market entry timelines.
- Sterile fill-finish capacity scarcity:Contract manufacturing organizations with isolator technology command premium pricing that compresses margins for mid-scale platform developers.
Strategic Opportunities
- India's CDSCO fast-track pathway:Streamlined approval for novel drug delivery systems targeting infectious disease applications creates first-mover positioning for parenteral antibiotic platforms.
- Wearable infusion convergence:Integration of continuous glucose monitoring algorithms with closed-loop insulin delivery opens ambulatory care channels previously restricted to hospital administration.
- Japan's PMDA Sakigake designation:Priority review incentives for regenerative medicine products accelerate commercial timelines for cell therapy-compatible delivery devices.
Industry Challenges
- Cross-functional talent scarcity:Formulation scientists with simultaneous expertise in polymer chemistry, biologic stability, and regulatory science command compensation premiums that strain R&D budgets.
- Legacy ERP integration friction:Smart delivery systems with sensor-integrated feedback loops require real-time data architecture that conflicts with validated manufacturing execution systems at established pharmaceutical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Drug Delivery Systems Market |
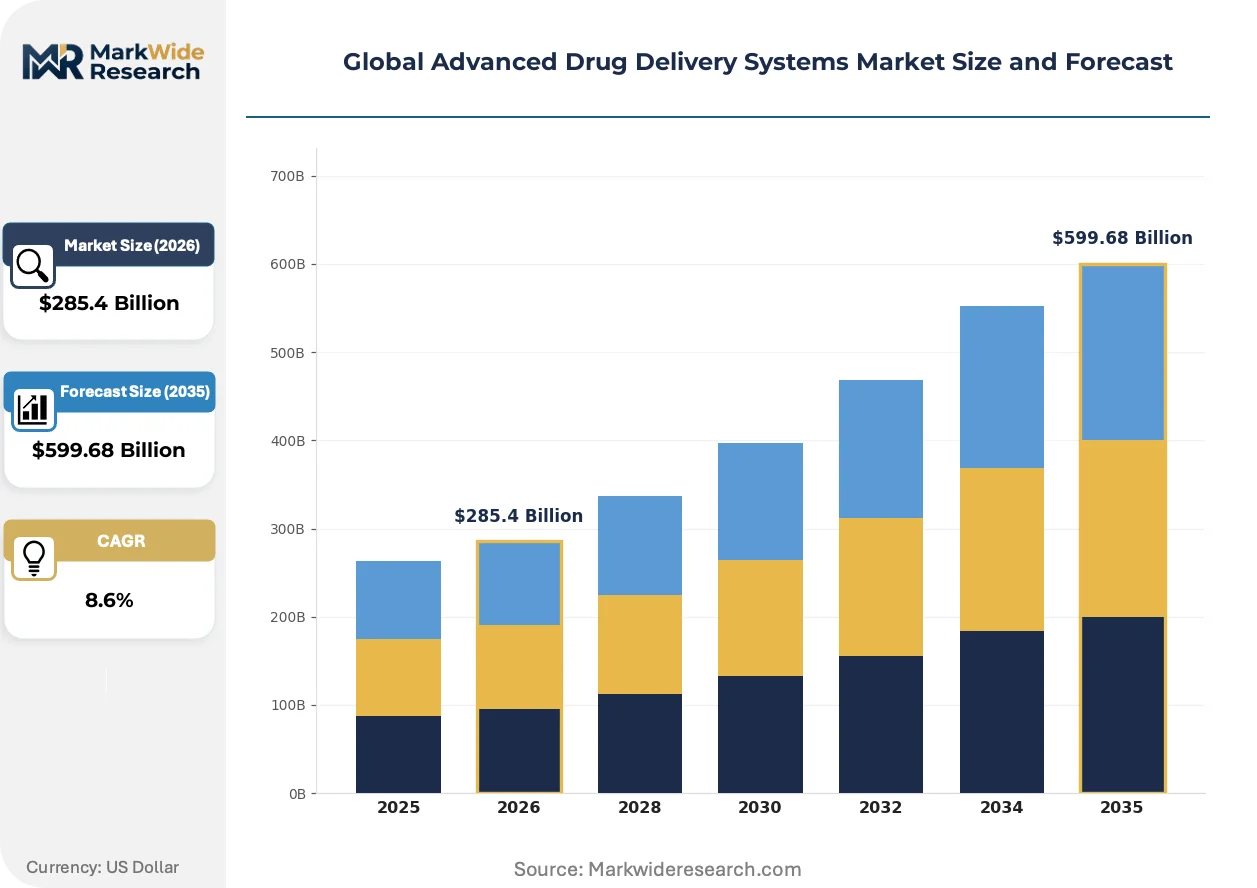
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $599.68 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microspheres, Liposomes, Nanoparticles, Hydrogels Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Research Institutions, Clinics, Homecare Technology: Targeted Delivery, Sustained Release, Smart Delivery, Bioadhesive |
| Companies Covered | Novartis, Abbott Laboratories, Becton Dickinson, Boston Scientific, Baxter, Johnson & Johnson, Medtronic, West Pharmaceutical Services, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Drug Delivery Systems Market Shifts & Advancements
Engineered particulate systems are converging with digital health infrastructure, creating closed-loop therapeutic platforms where pharmacokinetic modulation and physiological monitoring operate as unified interventions rather than sequential processes.
Microneedle array technology is miniaturizing transdermal delivery into painless, self-administered formats that bypass cold-chain requirements. Diabetes management programs in the Netherlands and primary care networks in Australia are piloting glucagon-compatible microneedle systems for emergency hypoglycemia rescue. This format is compressing the addressable market for traditional autoinjectors in conditions where patient adherence and portability outweigh dose precision requirements.
EMA's Medical Device Regulation (MDR) is reclassifying drug-device combination products based on intended therapeutic action rather than primary mode of action. Manufacturers of prefilled syringes with integrated safety mechanisms now face notified body scrutiny equivalent to active implantable devices. German and French notified bodies are extending review timelines for legacy product recertifications, forcing portfolio rationalization decisions ahead of certificate expiry deadlines.
Hospital procurement consortia in the United States are consolidating vendor panels for parenteral delivery devices around suppliers offering outcome guarantees on medication adherence metrics. Integrated delivery networks in Texas and Florida are replacing transactional purchasing with multi-year partnerships that bundle device supply with clinical training and wastage reduction commitments. This restructuring favors platform developers with field service infrastructure over pure-play device manufacturers.
Global Advanced Drug Delivery Systems Market Segmentation
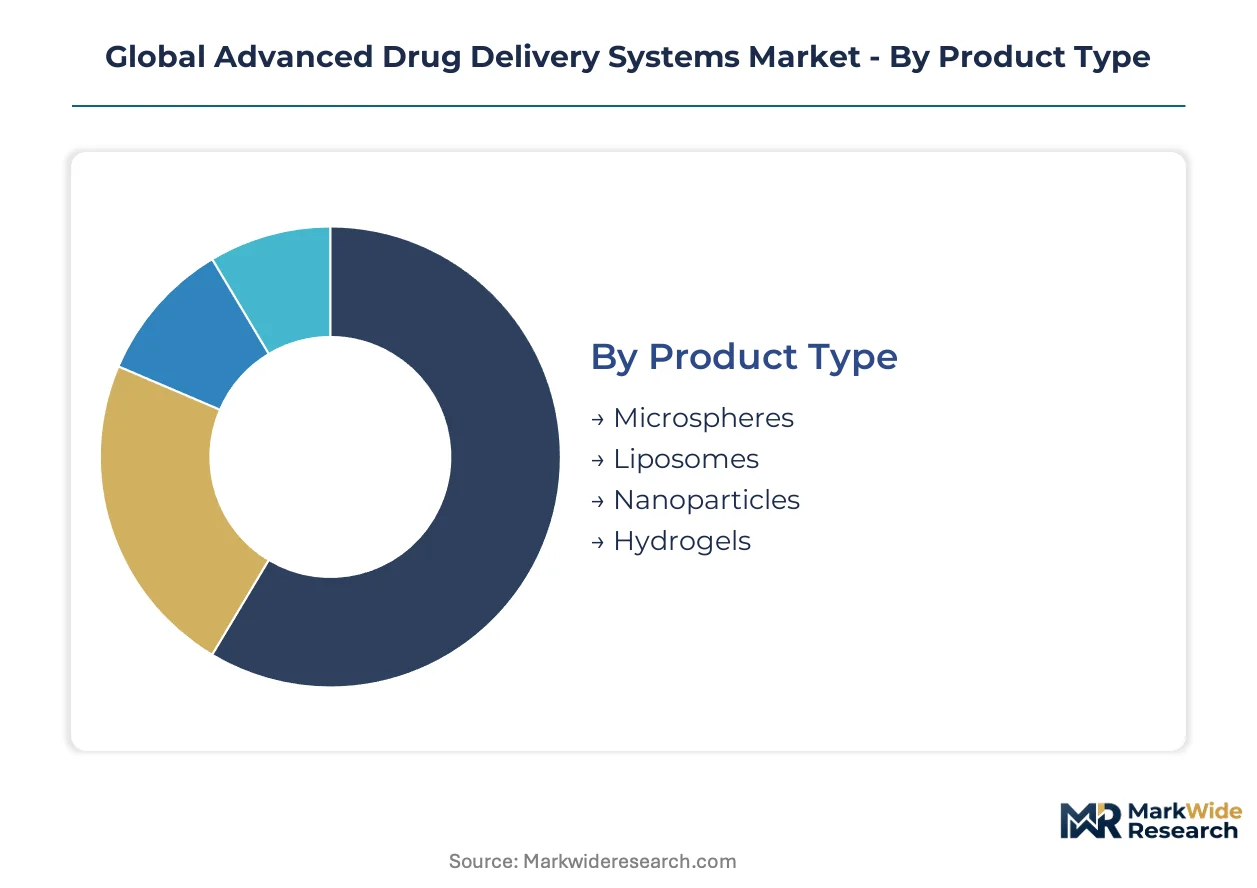
Segmentation in advanced drug delivery systems reveals how formulation chemistry, administration routes, and care settings create distinct competitive arenas with divergent margin profiles and regulatory pathways. Each dimension carries strategic implications for capital allocation, partnership structures, and geographic prioritization.
Product Type:
Domestic production dominates microspheres and hydrogels, while nanoparticles and liposomes depend heavily on export-oriented manufacturing clusters in Switzerland and specialized chemical corridors.
- Nanoparticles:Lipid and polymer matrices engineered at 1-100 nanometers enable mRNA encapsulation and tumor-targeted accumulation through enhanced permeability effects. Demand concentrates in United States oncology departments and German cell therapy manufacturing hubs where FDA Breakthrough Therapy and EMA PRIME designations accelerate commercial timelines. Ionizable lipid sourcing scarcity from Swiss suppliers constrains capacity expansion.
- Liposomes:Phospholipid bilayer structures deliver hydrophilic and hydrophobic payloads simultaneously, with established manufacturing protocols dating to early oncology applications. Japanese academic medical centers and United States hospital procurement consortia in Texas and Florida anchor demand for sterile, large-volume liposomal formulations.
- Microspheres:Biodegradable polymer matrices enable depot formulations with release profiles spanning weeks to months.
- Hydrogels:Cross-linked polymer networks provide localized, sustained release for ophthalmic and wound healing applications.
Nanoparticles hold the largest share; momentum sits with liposomes as gene therapy pipelines mature.
Delivery Mode:
Cost tiers separate hospital-administered formats from ambulatory and self-administered alternatives, with reimbursement frameworks in Germany and Japan favoring precision parenteral delivery over commodity oral formats.
- Injectable:Parenteral administration via prefilled syringes, autoinjectors, and infusion systems commands premium pricing due to biologic compatibility and cold-chain requirements. Baxter's sterile manufacturing scale and Johnson & Johnson's diversified channel access define competitive positioning in United States hospital-centric procurement.
- Transdermal:Microneedle arrays and patch technologies bypass first-pass metabolism while enabling patient self-administration. Pilot programs in Netherlands diabetes management and Australian primary care networks test glucagon-compatible microneedle systems for emergency hypoglycemia rescue.
- Oral:Sustained-release tablets and capsules face generic erosion pressure in mature markets.
- Inhalation:Pulmonary delivery targets local respiratory action or systemic absorption through alveolar interfaces.
Injectable formats hold the largest share; transdermal systems are expanding most quickly as wearable infusion technology converges with continuous monitoring.
End User:
Customer type determines regulatory complexity, with hospitals requiring combination product classification and homecare settings demanding simplified training protocols and adherence monitoring.
- Hospitals:Academic medical centers in the United States, Germany, and Japan drive adoption of nanoparticle-based therapies and closed-system infusion devices. Integrated delivery networks are consolidating vendor panels around suppliers offering outcome guarantees on medication adherence metrics and wastage reduction commitments.
- Homecare:Ambulatory settings require portable, patient-friendly formats with minimal cold-chain dependency. Wearable insulin pumps with closed-loop glucose control are opening channels previously restricted to hospital administration.
- Research Institutions:Academic and contract research organizations pilot novel delivery platforms prior to regulatory submission.
- Clinics:Outpatient facilities administer depot injections and sustained-release formulations with reduced monitoring infrastructure.
Hospitals hold the largest share; homecare is gaining share fastest as reimbursement shifts toward value-based ambulatory models.
Technology:
Maturity gradients separate established sustained-release platforms from emerging smart delivery systems requiring real-time data architecture and sensor integration.
- Targeted Delivery:Ligand-functionalized nanoparticles and antibody-drug conjugates achieve tissue-specific accumulation through receptor-mediated uptake. Novartis leverages integrated cell-and-gene therapy infrastructure to control end-to-end production of targeted oncology platforms.
- Smart Delivery:Stimulus-responsive systems with sensor-integrated feedback loops modulate release in response to physiological markers. Venture-backed developers concentrate R&D investment here, though legacy ERP integration friction at established pharmaceutical facilities constrains deployment.
- Sustained Release:Polymer matrix and reservoir technologies provide predictable pharmacokinetic profiles over extended durations.
- Bioadhesive:Mucoadhesive polymers prolong residence time at absorption sites for improved bioavailability.
Sustained release holds the largest share; smart delivery shows the steepest expansion trajectory as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by approximately 40% for parenteral delivery devices, while Japanese procurement consortia negotiate outcome-based contracts that compress margins for foreign entrants. Switzerland's ionizable lipid production clusters command supply-side leverage over nanoparticle formulation costs worldwide.
United States
Academic medical centers in Texas and Florida are consolidating vendor panels around suppliers offering medication adherence guarantees. FDA Breakthrough Therapy designation accelerates commercial timelines for lipid nanoparticle programs. The Boston-Cambridge corridor anchors cell therapy manufacturing expansion with retrofitted cleanroom infrastructure.
Germany
EMA Medical Device Regulation reclassification forces legacy product recertifications through German and French notified bodies. German hospital procurement consortia favor precision parenteral delivery over commodity oral formats. The Rhine-Main chemical corridor concentrates sterile fill-finish capacity for European nanoparticle assembly.
Japan
PMDA Sakigake designation prioritizes regenerative medicine products for accelerated review. Japanese academic medical centers retrofit infrastructure for closed-system infusion devices compatible with cell therapies. The Kansai region hosts specialized chemical clusters supplying high-purity lipids for nanoparticle production.
Switzerland
Ionizable lipid production for nanoparticle assembly depends on Swiss suppliers with limited global alternatives. Swissmedic maintains stringent evidentiary requirements for combination product classification that extend European market entry timelines. Basel anchors integrated pharmaceutical manufacturing with captive supply chains for biologic stabilization matrices.
India
CDSCO fast-track pathway streamlines approval for novel drug delivery systems targeting infectious disease applications. Parenteral antibiotic platforms gain first-mover positioning through regulatory prioritization. Maharashtra and Gujarat host contract manufacturing organizations expanding isolator technology for sterile fill-finish operations.
Global Advanced Drug Delivery Systems Market Competitive Landscape
Concentration sits with diversified healthcare conglomerates controlling end-to-end production infrastructure. The market structure tiers into three segments: integrated pharmaceutical-device hybrids, pure-play delivery specialists, and contract manufacturing organizations with sterile scale. Strategic archetypes include platform developers leveraging cell-and-gene therapy infrastructure, device manufacturers anchoring through sterile manufacturing scale, and formulation specialists synchronizing development cycles around biologic launch windows. Dominant competitive moves encompass backward integration into high-purity lipid sourcing and portfolio diversification across parenteral, transdermal, and smart delivery formats.
Among Swiss-integrated pharmaceutical conglomerates, Novartis occupies a position exemplifying platform developers with captive cell-and-gene therapy infrastructure. Baxter represents the device manufacturing archetype with sterile manufacturing scale across parenteral formats. Johnson & Johnson sits within the diversified healthcare hybrid tier, spanning biologics, medical devices, and channel access capabilities.
| Leading Market Players |
|---|
| Novartis |
| Abbott Laboratories |
| Becton Dickinson |
| Boston Scientific |
| Baxter |
| Johnson & Johnson |
| Medtronic |
| West Pharmaceutical Services |
| Pfizer |
| Others |
Supply & Pricing Matrix
Isolator technology capacity utilization at sterile fill-finish facilities shapes both supply concentration and price floors for parenteral delivery systems. Contract manufacturing organizations with validated isolator lines command premium pricing that propagates through nanoparticle formulation costs, while mid-scale platform developers absorb margin compression from limited qualified supplier alternatives.
Pricing Analysis
Configured-to-order pricing for patient-specific cell therapy delivery systems commands substantial premiums over standard prefilled syringe formats. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop infusion devices with integrated sensors from basic autoinjector platforms and commodity oral sustained-release tablets. Pricing pressure stems from hospital procurement consortia consolidating vendor panels around outcome guarantees, with integrated delivery networks in Texas and Florida demanding bundled pricing that compresses margins for pure-play device manufacturers. Generic erosion in oral formats exhibits highest buyer price sensitivity, while cell therapy-compatible closed-system devices show lowest sensitivity due to captive demand from academic medical center expansion.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for ionizable lipid shipments originating from Swiss chemical clusters. Nanoparticle formulation capacity draws from Switzerland for high-purity lipids, the United States for sterile fill-finish infrastructure, and India for contract manufacturing expansion with isolator technology. Raw material dependencies center on phospholipid precursors, medical-grade polymers, and sensor components for smart delivery platforms. Single-source vulnerability from concentrated Swiss lipid suppliers poses structural risk to global nanoparticle production. Distribution runs through hospital procurement consortia and integrated delivery networks rather than traditional pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market exhibits cyclical recovery characteristics as precision oncology pipeline maturation drives capital redeployment toward delivery infrastructure. FDA Breakthrough Therapy designation acceleration and EMA PRIME eligibility expansion constitute the named cyclical driver justifying this framing.
For Market Incumbents: Shield formulation expertise advantages through backward integration into ionizable lipid sourcing, capturing supply-side leverage from Swiss chemical cluster concentration. Expand sterile manufacturing capacity in the Rhine-Main corridor to preempt fill-finish bottlenecks that threaten biologic launch windows. Regulatory complexity from EMA Medical Device Regulation reclassification demands proactive notified body engagement ahead of certificate expiry deadlines.
For New Entrants and Emerging Players: CDSCO fast-track pathway certification acceleration enables first-mover positioning in India's parenteral antibiotic platform segment with streamlined approval timelines. Target microneedle array development for diabetes emergency rescue applications, where Netherlands and Australian pilot programs validate patient adherence advantages over traditional autoinjectors. Go-to-market execution should emphasize direct hospital procurement consortia engagement with outcome-guarantee contracting structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform developers with integrated cell-and-gene therapy infrastructure over pure-play device manufacturers facing margin compression. Long-term viability over the coming decade rests on convergence capabilities spanning nanoparticle formulation, digital health integration, and closed-loop therapeutic feedback. Acquisition screening should prioritize ventures with validated smart delivery sensor architectures. The inflection signal to watch is FDA interchangeability determination for biosimilar delivery platforms, which would reshape investment recoverability calculations for next-generation systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Scale-Up | Captive sterile fill-finish capacity secures biologic launch window synchronization for lipid nanoparticle programs. |
| CDSCO Fast-Track Registration | Regulatory prioritization unlocks first-mover positioning in India's parenteral infectious disease delivery segment. |
| Sensor-Integrated Platform Development | Closed-loop glucose control algorithms open ambulatory channels previously restricted to hospital administration settings. |
| Ionizable Lipid Backward Integration | Upstream control over Swiss chemical cluster supply reduces nanoparticle formulation cost volatility and capacity constraints. |
| Outcome-Guarantee Contracting | Texas and Florida integrated delivery network partnerships replace transactional purchasing with multi-year adherence commitments. |
Research Methodology
The analysis maps nanoparticle platforms, liposomal formulations, microneedle arrays, and smart delivery systems, each validated through formulation scientists, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary interviews with clinical investigators at academic medical centers and GPO contracts managers at integrated delivery networks combined with secondary validation from FDA Breakthrough Therapy designations, EMA PRIME eligibility records, ClinicalTrials.gov entries, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down pharmaceutical revenue allocation provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled delivery mode, product type, end-user setting, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from patent expiration timelines, biosimilar entry assumptions, and cell therapy manufacturing capacity expansion trajectories. Industry-specific inputs incorporated ionizable lipid sourcing constraints and EMA Medical Device Regulation recertification schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA Breakthrough Therapy pathway utilization and stable Swiss lipid supplier capacity; material deviation from these conditions would warrant model refresh. Forecasts reflect assumptions regarding reimbursement framework stability in the United States, Germany, and Japan alongside sterile manufacturing capacity expansion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
ADA Substitute Market
Medical Devices
Spinal Needles Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Recanalization System Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Microscope Market
Medical Devices
Spain Ultrasound Devices Market