
 Global Pessary Market | 2026-2036
Global Pessary Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pessary Market Foresight
Buyer concentration across outpatient gynecology networks is recalibrating procurement patterns for pessary devices. CooperSurgical Inc. leverages its broad women's health portfolio to sustain hospital system contracts across multiple geographies. Integra LifeSciences anchors its position through specialized silicone manufacturing capabilities that serve premium device segments. MedGyn Products, Inc. competes on cost-efficient latex and PVC alternatives for price-sensitive clinical settings.
A pessary is a removable prosthetic device inserted into the vagina to support pelvic organs or compress the urethra, typically manufactured from medical-grade silicone, latex, or thermoplastic elastomer through injection molding or compression forming processes. Its primary purpose is to provide non-surgical management of pelvic organ prolapse and stress urinary incontinence, particularly for patients who decline or are ineligible for operative intervention. Ring pessaries dominate clinical volume due to straightforward fitting protocols and broad applicability across prolapse stages, while silicone formulations command preference for biocompatibility and extended wear tolerance. Gellhorn and cube variants occupy niche positions in advanced prolapse cases where structural support demands exceed ring capacity.
The FDA's Class II medical device framework mandates 510(k) clearance for new pessary designs, compelling manufacturers to demonstrate substantial equivalence to predicate devices. EMA oversight through the Medical Device Regulation requires clinical evaluation reports and post-market surveillance systems for European market access. ISO 10993 biocompatibility testing standards govern material safety protocols across all major jurisdictions. Stakeholders must monitor evolving reimbursement criteria from CMS and national health technology assessment bodies, as coverage determinations increasingly tie device selection to documented patient-reported outcome measures.
Market Dynamics
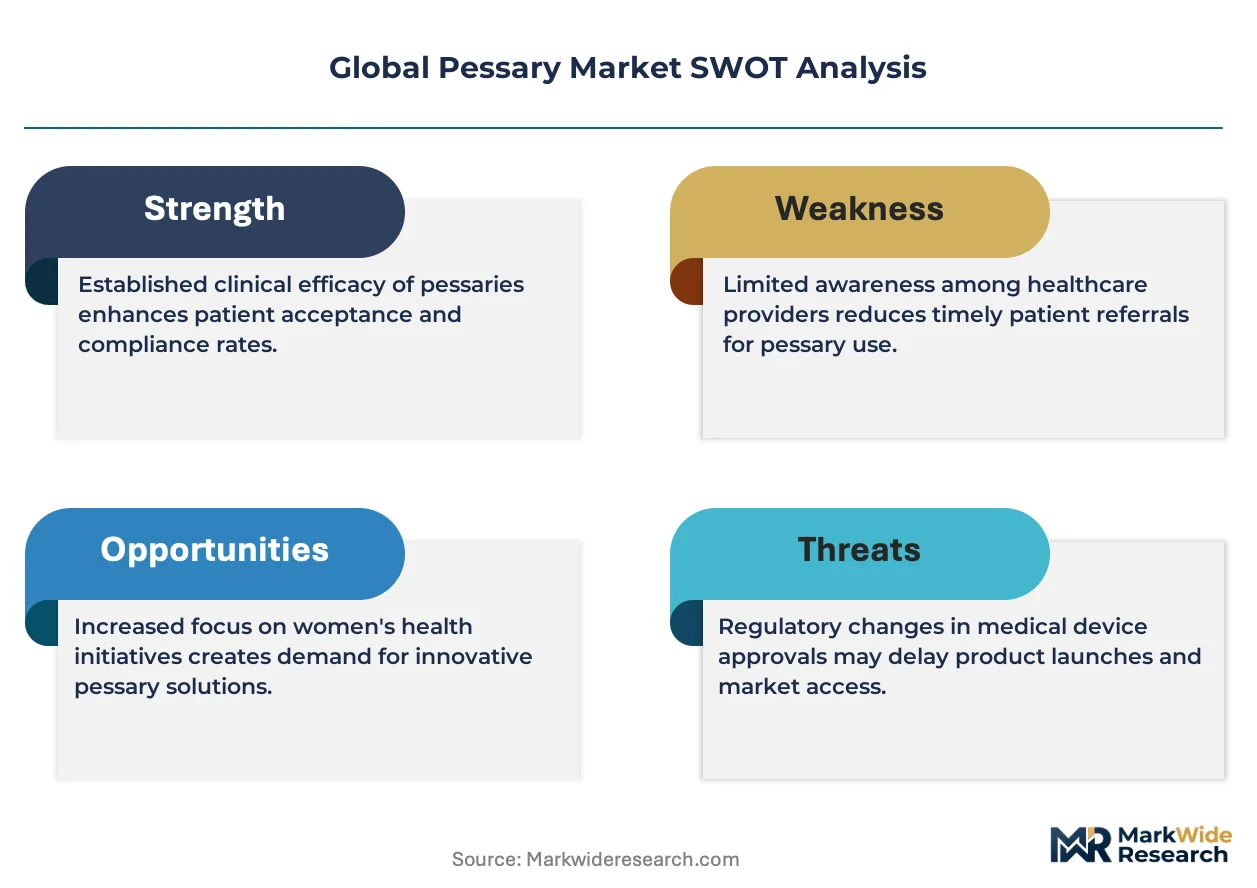
The FDA's Class II 510(k) pathway and EMA's MDR clinical evidence requirements are compressing product development timelines while elevating biocompatibility testing costs for silicone and thermoplastic elastomer formulations.
Growth Catalysts
- Japan's aging demographic profile:The country's super-aged population structure generates sustained clinical volume for conservative prolapse management as operative eligibility narrows.
- ISO 10993 biocompatibility frameworks:Standardized material safety protocols reduce regulatory friction for silicone device manufacturers seeking multi-jurisdiction approval.
- Outpatient gynecology network consolidation:Large clinic systems in the United States negotiate volume contracts that standardize ring pessary procurement across regional footprints.
Market Restraints
- Medical-grade silicone supply concentration:Specialty polymer production clusters in Germany and Japan create input cost volatility when capacity tightens.
- Latex allergy liability exposure:PVC and natural rubber alternatives face restricted hospital formulary placement due to hypersensitivity risk documentation requirements.
- EMA MDR technical documentation burdens:Clinical evaluation report preparation extends European market entry timelines by 18-24 months for novel geometries.
Strategic Opportunities
- India's underserved tier-2 cities:Gynecology clinic density in secondary urban centers remains below threshold for pessary fitting service availability.
- Digital fitting assistance platforms:Remote sizing algorithms paired with telehealth consultations expand access beyond metropolitan hospital networks.
- CMS value-based care pilots:Reimbursement bundling for pelvic floor disorder management creates incentive alignment for conservative therapy first-line protocols.
Industry Challenges
- Specialized pelvic floor physiotherapist scarcity:Proper pessary fitting requires trained clinical personnel that outpatient networks struggle to recruit and retain.
- Legacy electronic health record integration:Patient-reported outcome capture for reimbursement documentation demands custom API development with major hospital IT systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pessary Market |
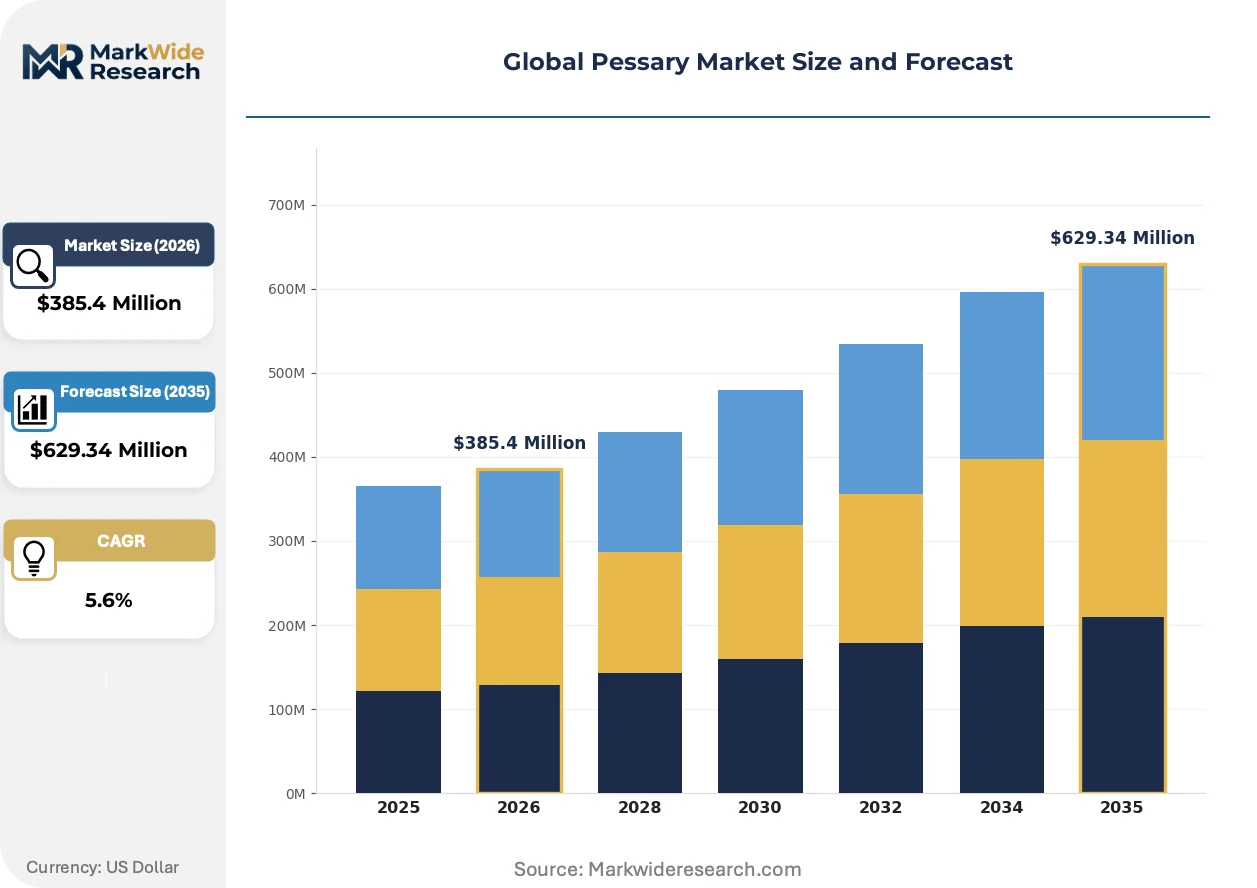
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $629.34 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ring, Gellhorn, Cube, Donut, Incontinence, Shaatz Material: Silicone, Latex, PVC, Thermoplastic Elastomer, Polyurethane Application: Pelvic Organ Prolapse, Stress Urinary Incontinence, Postpartum Support, Vaginal Support End User: Gynecology Clinics, Hospitals, Outpatient Centers, Homecare Providers |
| Companies Covered | CooperSurgical Inc., Integra LifeSciences, MedGyn Products, Inc., Panpac Medical Corp., Bioteque America, Inc., Dr. Arabin GmbH & Co. KG, Personal Medical Corp., Bliss GVS Pharma Limited, Coloplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pessary Market Shifts & Advancements
Silicone formulation chemistry and digital patient management platforms are converging to extend device wear intervals while compressing clinical follow-up requirements. Material biocompatibility and remote monitoring capabilities now determine competitive positioning.
Advanced platinum-cured silicone compounds with Shore A durometer optimization are unifying comfort and structural support properties previously split between soft ring and rigid Gellhorn designs. Academic medical centers in Germany and the United States adopt these hybrid formulations for same-day fitting protocols. The technology is unifying premium and standard device tiers into single-product solutions that reduce inventory complexity for outpatient clinics.
EMA's Medical Device Regulation post-market surveillance requirements are mandating systematic patient follow-up data collection across European implantable device categories. Manufacturers must establish quality management systems capable of tracing individual device lots to longitudinal outcome records. French and Italian hospital procurement consortia now prioritize suppliers with established vigilance infrastructure over lower-cost alternatives lacking documented traceability systems.
Hospital system buying committees are consolidating pessary procurement into women's health category contracts that span multiple device types. Integrated delivery networks in the United States negotiate two- to three-year sole-source agreements with manufacturers offering standardized silicone ring portfolios across all prolapse stages. This concentration is most visible in California and Texas, where large Catholic health systems have eliminated latex alternatives entirely from their formularies.
Global Pessary Market Segmentation
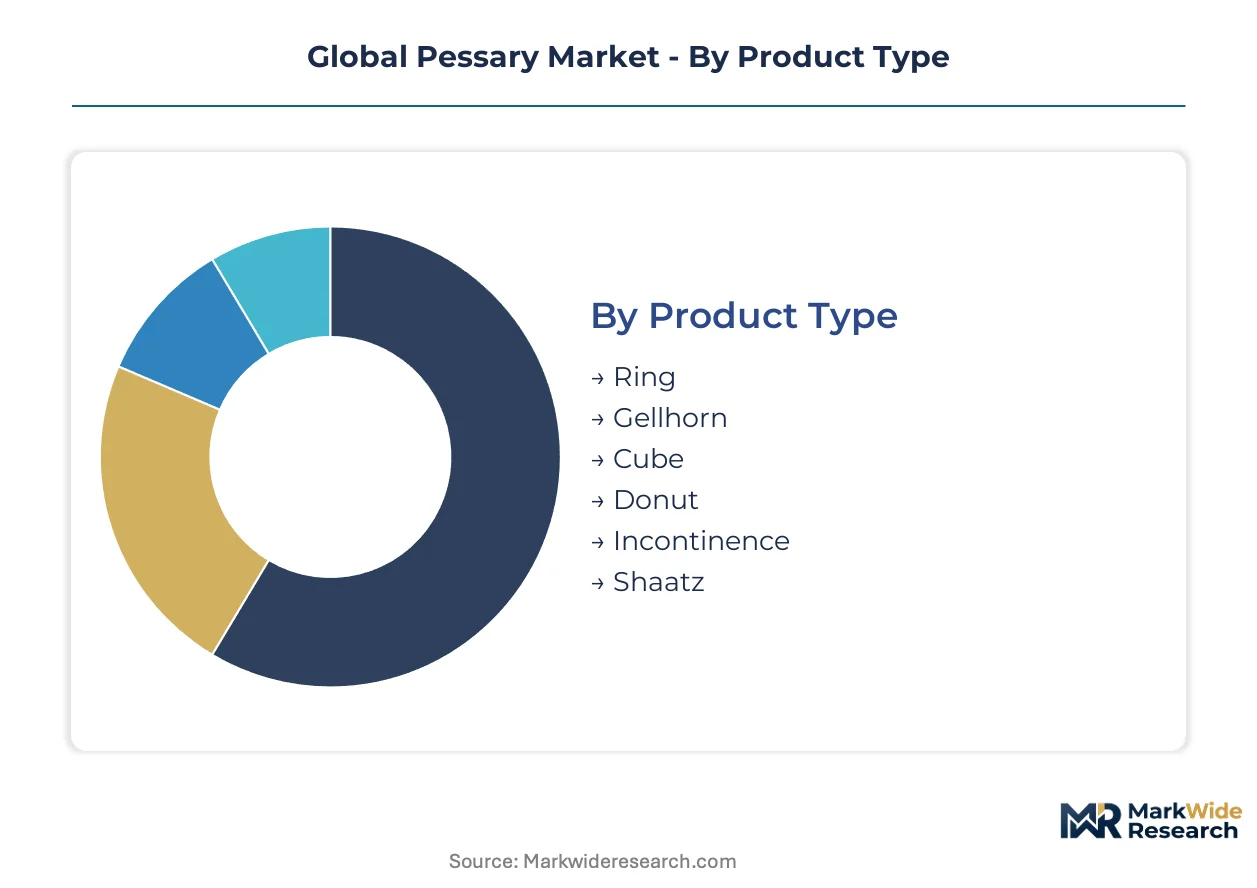
Pessary market segmentation reveals how regulatory pathways and clinical workflows fragment procurement across device geometries, material grades, and care settings. Manufacturers must align product portfolios with specific reimbursement codes and fitting protocols that vary by segment.
Product Type:
FDA 510(k) clearance requirements differ substantially across geometries, with ring and Gellhorn variants holding established predicate device libraries while novel shapes face extended review timelines.
- Ring:Circular silicone devices with flexible structural ribs dominate outpatient fitting protocols due to straightforward insertion techniques. Demand concentrates in United States gynecology clinics where same-day sizing protocols reduce specialist visit burdens. The FDA's substantial equivalence pathway for ring geometries compresses regulatory lead times versus experimental shapes.
- Gellhorn:Rigid stemmed devices with perforated bases provide structural support for advanced prolapse stages beyond ring capacity. German university hospitals specify platinum-cured silicone Gellhorn variants for patients with prior surgical mesh complications. EMA clinical evaluation reports for Gellhorn modifications require post-market surveillance commitments that elevate compliance costs.
- Cube:Six-faced devices with concave surfaces generate suction-based retention for complex anatomical presentations.
- Donut:Toroidal designs with central perforations suit patients requiring circumferential support without stem protrusion.
- Incontinence:Urethral compression variants with specialized curvature profiles target stress urinary incontinence specifically.
- Shaatz:Oval-ring hybrids with asymmetric support surfaces address combined prolapse-incontinence presentations.
Leading the category by volume: Ring. Growing fastest: Incontinence.
Material:
Input cost tiers separate segments, with platinum-cured silicone commanding premium positioning against commodity latex and PVC alternatives.
- Silicone:Platinum-cured medical-grade formulations with Shore A 30-50 durometer balance biocompatibility with structural integrity. Japanese super-aged patient populations drive preference for extended-wear silicone tolerance in Tokyo and Osaka metropolitan clinics. ISO 10993 testing protocols for silicone cytotoxicity and sensitization are standardized across FDA, EMA, and PMDA jurisdictions.
- Latex:Natural rubber compounds with sulfur vulcanization occupy price-sensitive procurement segments despite hypersensitivity documentation burdens.
- PVC:Plasticized polyvinyl chloride alternatives face restricted formulary placement in California and Texas Catholic health systems.
- Thermoplastic Elastomer:SEBS-based compounds enable overmolding processes for hybrid comfort-support designs.
- Polyurethane:Medical-grade urethane formulations with hydrolytic stability target long-term implantation scenarios.
Silicone commands the premium tier by margin. Thermoplastic elastomer is expanding most quickly via hybrid device adoption.
Application:
Reimbursement coding density varies by indication, with pelvic organ prolapse carrying established procedure codes versus emerging coverage frameworks for postpartum support.
- Pelvic Organ Prolapse:Anterior, posterior, and apical compartment support applications align with established CPT and ICD-10 coding systems. United States Medicare coverage determinations for pessary fitting require documented POP-Q staging measurements.
- Stress Urinary Incontinence:Urethral compression mechanisms target hypermobility-related incontinence without surgical intervention.
- Postpartum Support:Temporary pelvic floor stabilization following vaginal delivery occupies emerging indication territory with limited payer recognition.
- Vaginal Support:Generalized structural indications for post-hysterectomy vault prolapse or congenital support deficiencies.
Pelvic organ prolapse generates the deepest procedure volume. Postpartum support is gaining share fastest as obstetric networks expand conservative therapy protocols.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks controlling hospital purchasing versus independent physician ownership of clinic formulary decisions.
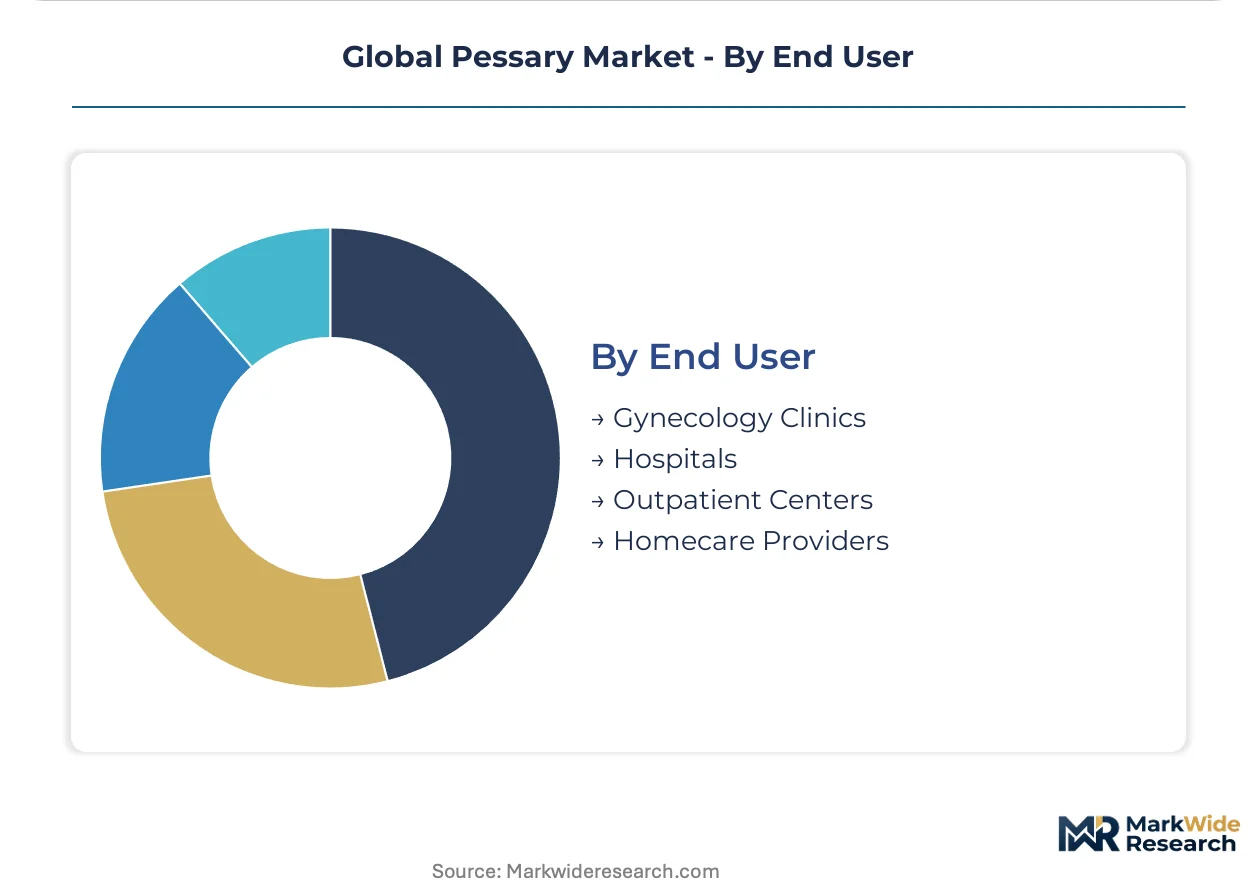
- Gynecology Clinics:Independent and network-affiliated specialty practices with dedicated pelvic floor therapists conduct the majority of fitting procedures. Texas and California clinic consolidation is standardizing silicone-only procurement policies across regional footprints.
- Hospitals:Academic medical centers and community hospitals with inpatient urogynecology services manage complex case referrals.
- Outpatient Centers:Ambulatory surgical facilities with same-day discharge protocols handle post-surgical pessary fitting transitions.
- Homecare Providers:Durable medical equipment suppliers with remote patient monitoring capabilities support long-term device maintenance.
Gynecology clinics dominate fitting volume. Homecare providers are climbing the fastest as remote monitoring platforms extend care beyond metropolitan hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone production clusters in Germany and Japan anchor supply-side capacity for premium pessary manufacturing. These material hubs feed fabrication networks across North America, Western Europe, and East Asia where aging patient populations and established reimbursement frameworks sustain clinical demand.
United States
Medicare coverage determinations for pelvic organ prolapse management require documented POP-Q staging measurements before pessary fitting reimbursement. The FDA's 510(k) substantial equivalence pathway compresses regulatory timelines for ring geometries versus experimental shapes. Texas and California clinic consolidation is standardizing silicone-only procurement policies across integrated delivery network footprints.
Germany
University hospitals in Bavaria and Baden-Württemberg specify platinum-cured silicone Gellhorn variants for patients with prior surgical mesh complications. EMA clinical evaluation reports under the Medical Device Regulation mandate post-market surveillance commitments that elevate compliance costs for novel geometries. Specialty polymer production clusters in the Rhine-Ruhr region supply medical-grade silicone inputs to device fabricators.
Japan
Super-aged demographic structures in Tokyo and Osaka metropolitan areas generate sustained clinical volume for conservative prolapse management as operative eligibility narrows. PMDA oversight aligns with ISO 10993 biocompatibility frameworks that reduce regulatory friction for silicone device manufacturers. The country's national health insurance system maintains established reimbursement codes for pessary fitting procedures.
India
Gynecology clinic density in tier-2 urban centers remains below threshold for pessary fitting service availability, creating access gaps outside metropolitan hospital networks. CDSCO medical device registration requirements are tightening quality management system expectations for imported silicone devices. Maharashtra and Karnataka host expanding women's health specialty practices in Mumbai and Bangalore that are adopting conservative pelvic floor therapy protocols.
United Kingdom
NICE clinical guidelines emphasize pessary therapy as first-line management for pelvic organ prolapse before surgical referral. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements for post-Brexit device market access. London and Southeast England academic medical centers are piloting digital fitting assistance platforms to extend specialist reach beyond tertiary hospital networks.
Global Pessary Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in digital patient management and remote fitting assistance. The vendor base stratifies across three tiers: multinational women's health conglomerates with broad portfolio leverage, specialized silicone device fabricators with premium material capabilities, and regional cost-efficient manufacturers serving price-sensitive procurement segments. Dominant competitive moves include hospital system contract consolidation through sole-source agreements and backward integration into medical-grade silicone compounding to secure input cost stability.
Within the premium silicone tier, CooperSurgical Inc. and Integra LifeSciences exemplify archetypes of portfolio breadth versus specialized manufacturing depth. Dr. Arabin GmbH & Co. KG occupies a position representing European precision fabrication heritage. These three anchors illustrate how competitive positioning diverges across material science capability, clinical service integration, and geographic market access rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| Integra LifeSciences |
| MedGyn Products, Inc. |
| Panpac Medical Corp. |
| Bioteque America, Inc. |
| Dr. Arabin GmbH & Co. KG |
| Personal Medical Corp. |
| Bliss GVS Pharma Limited |
| Coloplast Group |
| Others |
Supply & Pricing Matrix
Platinum-cured silicone compounding advances in Germany and Japan simultaneously compress per-unit production costs and concentrate premium-grade supply among specialized polymer manufacturers with validated ISO 10993 testing infrastructure. This dual effect elevates pricing power for medical-grade material holders while forcing device fabricators to absorb biocompatibility certification premiums or cede margin to backward-integrated competitors.
Pricing Analysis
Service bundling separates premium-tier suppliers offering clinical training and fitting protocol support from commodity competitors selling unbundled devices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, platinum-cured versus peroxide-cured silicone grades, and included clinical education programs. Cost compression in economy latex and PVC tiers intensifies because California and Texas Catholic health systems have eliminated these alternatives entirely from formularies. Price-sensitive outpatient networks in India and Southeast Asia drive volume procurement of unbundled standard silicone rings, while German university hospitals absorb premium positioning for Gellhorn variants with mesh-complication patient populations.
Supply Chain Analysis
Reverse logistics for pessary devices remain underdeveloped, with limited refurbishment infrastructure for platinum-cured silicone products and negligible remanufacturing flows compared to orthopedic implant categories. Raw material supply draws from specialty polymer production clusters in Germany, Japan, and the United States, with medical-grade silicone compounding concentrated among three dominant chemical suppliers. Component dependencies include platinum catalyst systems, Shore A durometer testing equipment, and precision injection molding tooling. Single-source vulnerability in platinum-cured silicone feedstock creates supply chain risk when pharmaceutical-grade polymer capacity tightens. Distribution runs through hospital system GPO contracts in the United States, regional procurement consortia in France and Italy, and direct-to-clinic relationships in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone compounding capacity constraints prop pricing premiums for validated biocompatibility tiers, creating supply-constrained conditions that favor incumbent material holders over price-competitive entrants lacking certified manufacturing infrastructure.
For Market Incumbents: Anchor market position through captive supply of platinum-cured silicone compounds and exclusive hospital system contracts spanning multi-year procurement cycles. Defensive consolidation moves include acquiring specialized polymer testing laboratories to internalize ISO 10993 validation costs and negotiating sole-source agreements with expanding integrated delivery networks in Texas and California. The emerging threat of digital fitting platforms displacing traditional clinical channel relationships demands preemptive investment in telehealth-compatible sizing assistance tools. For New Entrants and Emerging Players: Tier-2 Indian cities with gynecology clinic density below pessary fitting service thresholds represent the most penetrable geographic white space. Remote patient monitoring capabilities for homecare providers offer a second entry vector beyond metropolitan hospital networks. A telehealth-integrated go-to-market angle combining digital sizing algorithms with direct-to-clinic logistics bypasses incumbent GPO contract lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with specialized silicone device fabricators possessing validated EMA MDR vigilance infrastructure given post-market surveillance requirements elevating compliance costs for smaller competitors. Long-term viability over a multi-year horizon rests on material science differentiation rather than commodity volume positioning. The signal to watch is CMS value-based care pilot expansion linking reimbursement bundling to documented patient-reported outcomes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive supply of medical-grade polymer secures input cost stability against German and Japanese production volatility. |
| Digital Fitting Platform Development | Remote sizing algorithms paired with telehealth consultations extend access beyond metropolitan hospital networks. |
| EMA MDR Vigilance Infrastructure Investment | Post-market surveillance capabilities satisfy French and Italian hospital procurement consortia prioritizing traceability systems. |
| Hospital System Sole-Source Contracting | Multi-year agreements with integrated delivery networks in California and Texas standardize silicone-only procurement policies. |
| Reimbursement Strategy Alignment | CMS value-based care pilot participation creates incentive alignment for conservative therapy first-line protocols. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EMA MDR clinical evaluation report submissions, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with urogynecologists, pelvic floor physiotherapists, biomedical engineers, GPO contracts managers, and silicone polymer procurement leads. Secondary validation drew from FDA device classification databases, EMA medical device registration filings, CMS Medicare coverage determinations, and hospital procurement database extracts. Bottom-up fitting procedure volume estimates triangulated against top-down medical-grade silicone consumption data from specialty chemical trade associations.
Input-output matrix modeling connected platinum-cured silicone raw material flows through injection molding fabrication to end-use demand across ring, Gellhorn, and incontinence device geometries over the projection horizon. Segmentation dimensions included product type, material grade tier, application indication, and end-user setting. CAGRs derived from fitted trend extrapolation of procedure volumes adjusted for demographic aging trajectories and reimbursement policy shift probabilities. Industry-specific forecast inputs incorporated POP-Q staging measurement adoption rates and digital fitting platform penetration assumptions.
Revisions become necessary when EMA MDR technical documentation requirements intensify, medical-grade silicone supply disruptions materialize, or CMS value-based care pilots expand beyond current geographic scope. Practitioners should monitor hospital system procurement consolidation patterns and platinum-cured silicone spot pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Airway Management Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Pericardial Patches Market