
 Global Coronary Artery Bypass Graft Devices Market | 2026-2036
Global Coronary Artery Bypass Graft Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coronary Artery Bypass Graft Devices Market Foresight
Polytetrafluoroethylene is repositioning synthetic graft economics by displacing older polyester-based conduits in high-flow arterial applications. Medtronic leverages integrated manufacturing from raw polymer to finished graft to sustain margin control across its cardiovascular portfolio. Terumo Corporation anchors its competitive stance through specialized coating technologies that reduce thrombogenicity in synthetic bypass conduits.
Coronary artery bypass graft devices encompass implantable conduits, mechanical stabilizers, vascular occluders, and suturing systems designed to restore myocardial perfusion by diverting blood flow around stenosed coronary segments, with ePTFE and saphenous vein grafts typically achieving patency rates exceeding 85 percent at one year when deployed in arterial configurations. Graft conduits command the deepest margin pools due to material complexity and regulatory validation burdens, while minimally invasive surgery applications are expanding fastest as cardiac surgery centers invest in thoracoscopic and robotic platforms that reduce sternotomy-related morbidity. Deployment through hybrid catheterization labs is maturing as a distinct channel, blurring traditional boundaries between surgical and interventional cardiology service lines.
FDA premarket notification and EU MDR conformity assessment govern graft biocompatibility and long-term implant performance standards, with FDA 510(k) pathways requiring substantial equivalence demonstrations that extend development timelines for novel materials. Japan's PMDA enforces distinct clinical evidence requirements for foreign-manufactured cardiovascular implants, creating asymmetric market access conditions across major jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for off-pump and robotic-assisted procedures as payers in Germany and the United States recalibrate coverage policies based on comparative effectiveness evidence.
Market Dynamics
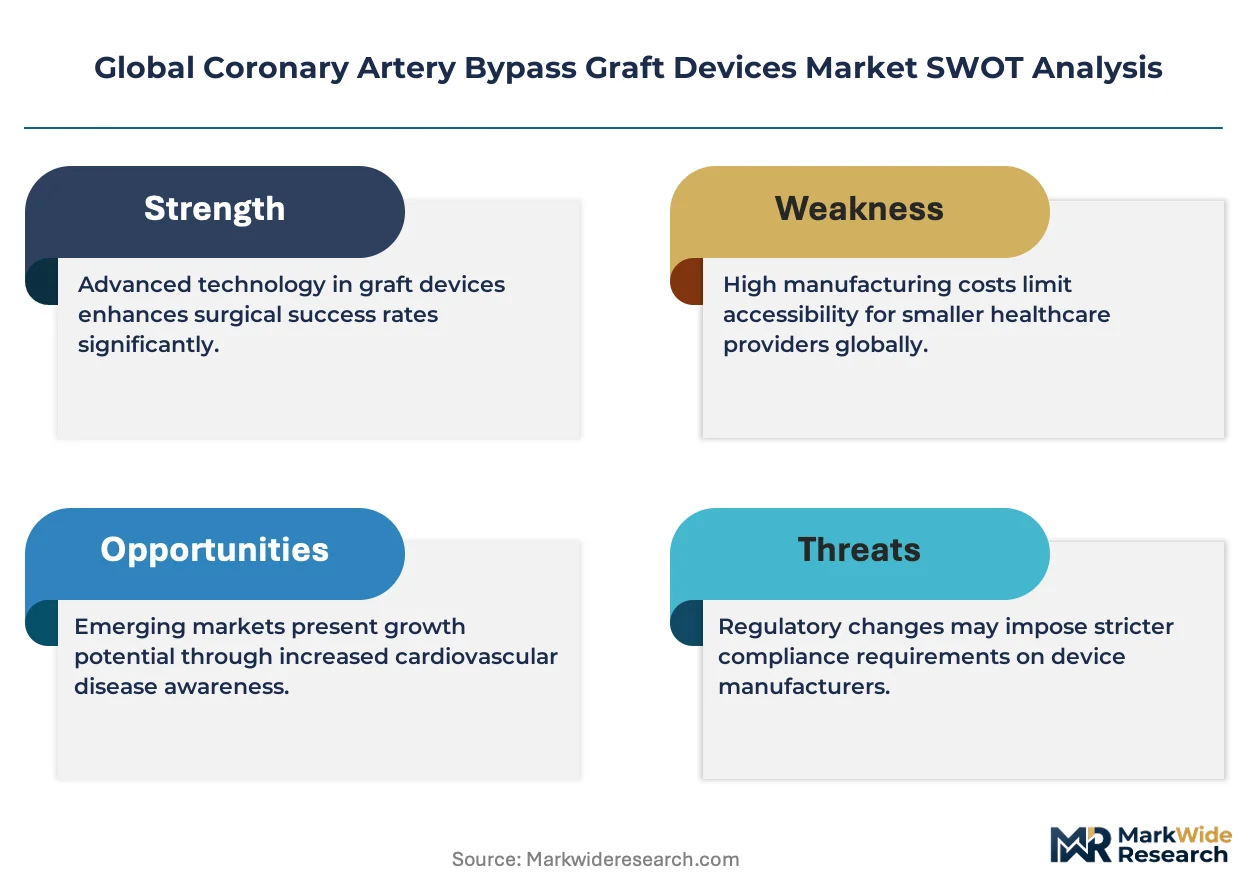
Hybrid catheterization labs are dissolving the surgical-interventional boundary as cardiac centers consolidate bypass and percutaneous capabilities under single rooflines, forcing graft manufacturers to serve dual-specialty procurement committees rather than discrete cardiac surgery departments.
Growth Catalysts
- EU MDR harmonization:Streamlined conformity assessment across European Economic Area member states reduces redundant testing burdens for graft manufacturers seeking multi-country market access.
- Japan's aging surgical population:PMDA reimbursement adjustments for off-pump procedures expand addressable patient pools beyond traditional sternotomy candidates.
- Endoscopic harvesting systems:Minimally invasive vein extraction technologies reduce donor-site morbidity and accelerate postoperative recovery trajectories.
Market Restraints
- Polymer feedstock concentration:Medical-grade ePTFE resin supply concentrates among three specialty chemical producers, exposing graft manufacturers to input price volatility.
- FDA substantial equivalence barriers:510(k) pathway requirements for novel synthetic conduits extend development timelines beyond typical venture capital horizons.
- Arterial revascularization alternatives:Advancements in percutaneous coronary intervention with drug-eluting stents capture hemodynamically suitable candidates who previously required surgical bypass.
Strategic Opportunities
- Robotic-assisted anastomosis:Convergence of surgical robotics with precision suturing platforms enables remote-procedure capabilities and standardizes graft attachment quality.
- India's tertiary cardiac center expansion:Government medical college hospital upgrades create procurement channels for mid-tier bypass device portfolios.
- Germany's DRG recalibration:Bundled reimbursement reforms for complex coronary interventions incentivize investment in hybrid operating suites combining surgical and interventional infrastructure.
Industry Challenges
- Cardiac surgeon workforce constraints:Fellowship training program bottlenecks limit institutional capacity to deploy advanced bypass technologies at scale.
- EU MDR technical documentation:Expanded clinical evidence requirements for legacy graft products force resource reallocation from R&D toward regulatory remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coronary Artery Bypass Graft Devices Market |
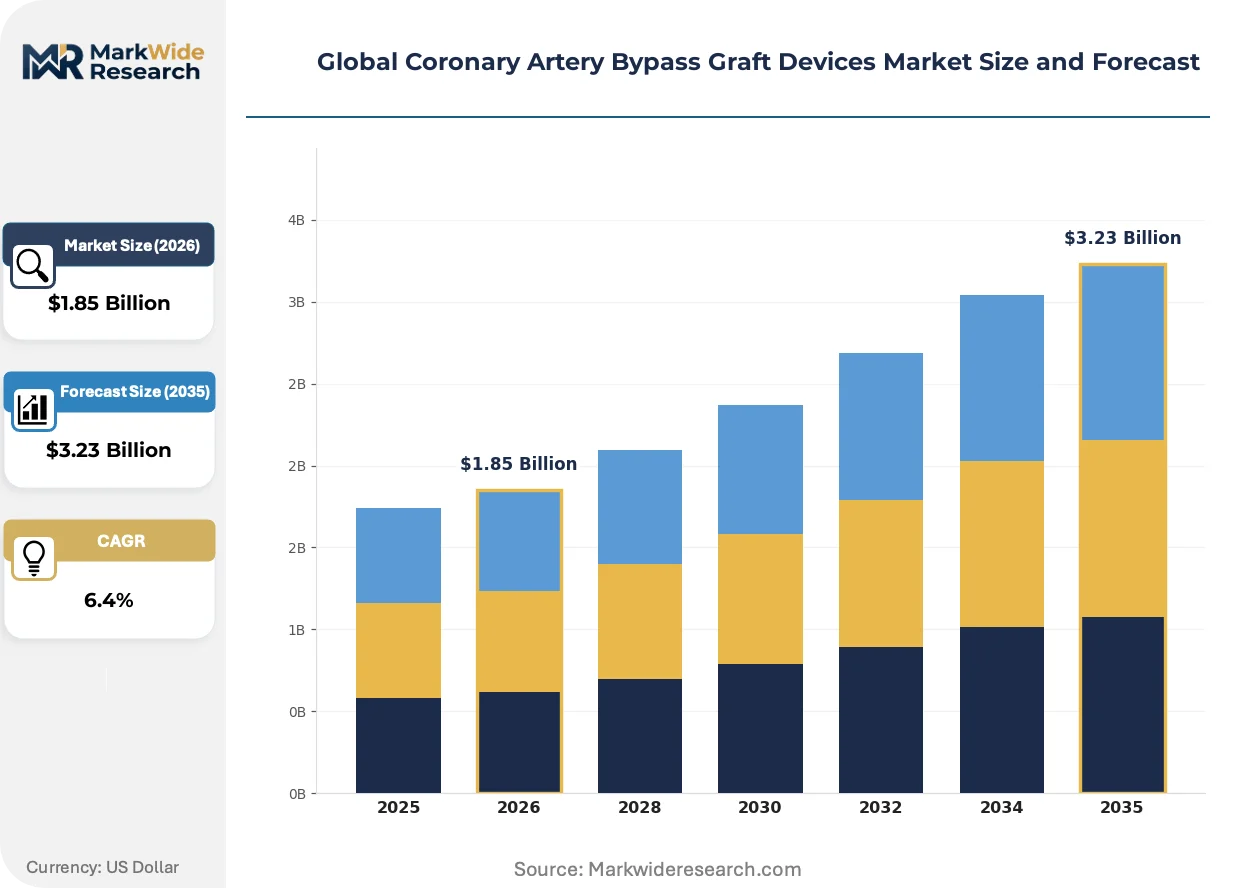
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vascular Clips, Surgical Sutures, Graft Conduits, Stabilizers, Occluders Application: Single Vessel Bypass, Multi Vessel Bypass, Minimally Invasive Surgery, Off-Pump Surgery, Reoperative Procedures End User: Cardiac Surgery Centers, Specialty Clinics, Ambulatory Surgical Units, Rehabilitation Centers Deployment: Hospital Operating Rooms, Outpatient Surgical Facilities, Mobile Surgical Units, Hybrid Catheterization Labs |
| Companies Covered | Medtronic, Terumo Corporation, Getinge AB, W. L. Gore & Associates, B. Braun SE, Abbott, LivaNova plc, Edwards Lifesciences, Genesee Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coronary Artery Bypass Graft Devices Market Shifts & Advancements
Computational modeling and advanced biomaterials are converging to redefine graft design paradigms, shifting competitive advantage from manufacturing scale toward predictive performance validation and personalized conduit specification.
Computational fluid dynamics simulation platforms are automating preclinical graft performance assessment by modeling hemodynamic patterns, wall shear stress distribution, and thrombogenic risk profiles prior to physical prototyping. Cardiovascular device manufacturers integrate these tools into design loops to compress iteration cycles. This capability is automating the transition from empirical bench testing toward in-silico validation pathways that reduce animal study requirements.
Japan's PMDA has tightened clinical evidence standards for foreign-manufactured cardiovascular implants, requiring extended follow-up data from domestic patient populations before reimbursement approval. Graft manufacturers must now sponsor Japan-specific registry studies or partner with local academic medical centers. Synthetic conduit suppliers with established saphenous vein graft competitors face particular pressure to demonstrate non-inferior patency outcomes under these evidentiary conditions.
Hospital procurement committees are consolidating bypass device purchasing across previously separate cardiac surgery and interventional cardiology service lines. Single-source contracting for graft conduits, closure devices, and ancillary instrumentation displaces specialty-specific vendor relationships. This concentration is most pronounced in United States integrated delivery networks and German hospital federations seeking volume-based price concessions.
Global Coronary Artery Bypass Graft Devices Market Segmentation
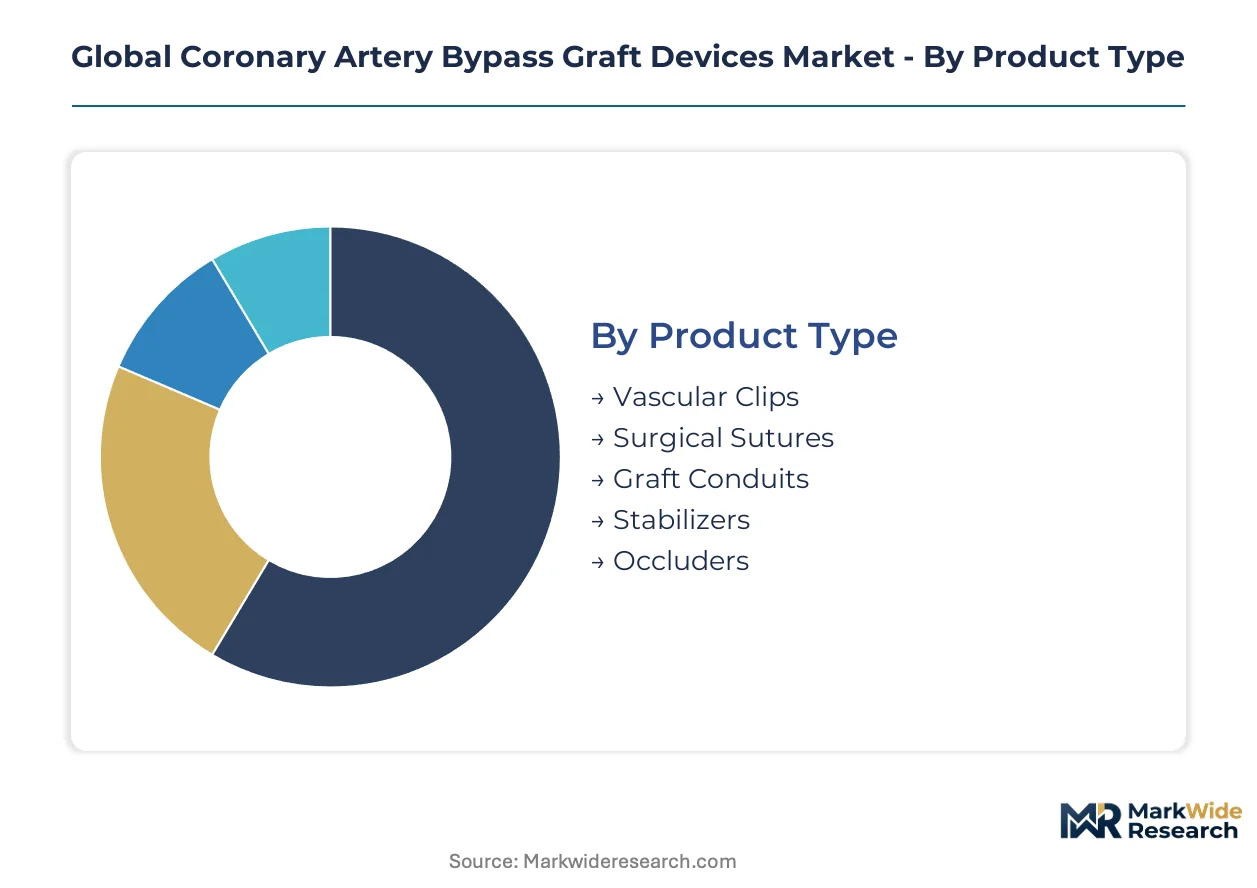
Segmentation in coronary artery bypass graft devices reveals how procurement committees balance upfront capital costs against long-term patency outcomes. Manufacturers must calibrate portfolio depth across implantable conduits, mechanical stabilizers, and suturing systems to capture differential margin pools.
Product Type:
Graft conduits absorb the majority of material science investment, while mechanical stabilizers and occluders compete on price-performance ratios in high-volume procurement environments.
- Graft Conduits:ePTFE and saphenous vein configurations dominate arterial revascularization, with biocompatibility validation extending development timelines. Demand concentrates in United States academic medical centers where FDA 510(k) substantial equivalence requirements favor established polymer platforms over novel biomaterials.
- Surgical Sutures:Precision suturing systems enable anastomosis quality standardization, particularly in robotic-assisted procedures. German cardiac surgery centers are expanding procurement of coated braided polyester threads that reduce thrombogenicity in high-shear arterial environments.
- Stabilizers:Mechanical platforms immobilize target vessels during off-pump procedures, with suction-based designs displacing compression alternatives in Japan's aging surgical population.
- Occluders:Vascular closure devices manage collateral flow during anastomosis construction, with demand clustering in hybrid catheterization labs combining surgical and interventional capabilities.
- Vascular Clips:Titanium and polymer ligation systems secure side branches during conduit harvesting, with cost pressures favoring disposable over reusable configurations in ambulatory settings.
Today's leader: Graft Conduits. Tomorrow's challenger: Surgical Sutures.
Application:
Procedure complexity stratifies device requirements, with single-vessel interventions favoring disposable efficiency and multi-vessel reconstructions demanding premium conduit durability.
- Multi Vessel Bypass:Three or more arterial grafts require extended operative times and specialized stabilizer platforms. Japanese PMDA reimbursement adjustments for complex procedures are expanding addressable volumes beyond traditional sternotomy candidates.
- Minimally Invasive Surgery:Thoracoscopic and robotic approaches reduce sternotomy-related morbidity but constrain instrument maneuverability. United States integrated delivery networks are consolidating procurement of endoscopic harvesting systems and port-access stabilizers for these applications.
- Off-Pump Surgery:Beating-heart procedures eliminate cardiopulmonary bypass but demand superior hemodynamic stabilization. German DRG recalibration is incentivizing investment in hybrid operating suites that accommodate off-pump and percutaneous alternatives.
- Single Vessel Bypass:Isolated left anterior descending revascularization favors simplified conduit and suturing configurations, with cost containment priorities dominating procurement in India's expanding tertiary cardiac centers.
- Reoperative Procedures:Redo sternotomy carries elevated risk profiles, driving demand for adhesive barriers and pericardial substitute materials alongside standard graft systems.
Multi Vessel Bypass commands premium pricing. Minimally Invasive Surgery is gaining share fastest.
End User:
Institutional scale determines procurement authority, with high-volume cardiac surgery centers negotiating direct manufacturer relationships while smaller facilities rely on distributor networks.
- Cardiac Surgery Centers:Dedicated cardiovascular institutions perform the majority of complex multi-vessel procedures, with procurement committees consolidating graft conduit, stabilizer, and closure device purchasing under single-source contracts.
- Specialty Clinics:Focused cardiac practices concentrate on diagnostic and postoperative management, with limited direct device procurement beyond office-based monitoring equipment.
- Ambulatory Surgical Units:Same-day discharge protocols favor disposable instrumentation and simplified suturing platforms that reduce operative complexity.
- Rehabilitation Centers:Postoperative recovery facilities influence downstream graft patency monitoring but do not directly procure implantable devices.
Cardiac Surgery Centers anchor volume concentration. Ambulatory Surgical Units represent the steepest expansion trajectory.
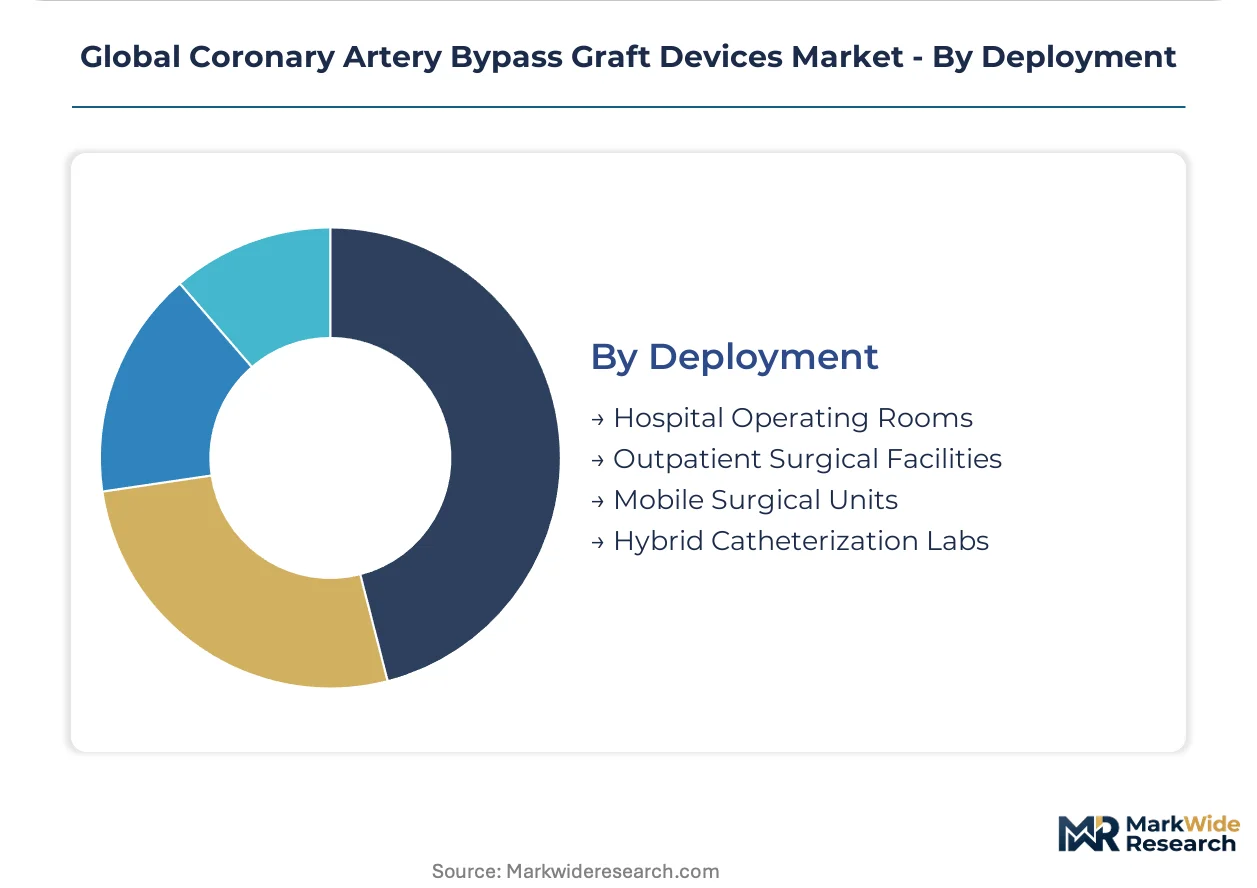
Deployment:
Physical infrastructure constraints shape device specification, with fixed operating rooms optimizing for reusable platforms and mobile units prioritizing disposable efficiency.
- Hospital Operating Rooms:Fixed surgical suites accommodate full robotic platforms and comprehensive stabilizer systems, with capital equipment amortization over high procedure volumes.
- Hybrid Catheterization Labs:Combined surgical-interventional environments are dissolving traditional specialty boundaries, forcing graft manufacturers to serve dual-committee procurement structures.
- Outpatient Surgical Facilities:Limited-stay centers constrain inventory breadth, favoring standardized conduit and suturing configurations across procedure types.
- Mobile Surgical Units:Deployable platforms for rural or emergency applications prioritize compact, disposable instrumentation over capital-intensive robotic systems.
Hospital Operating Rooms dominate capital deployment. Hybrid Catheterization Labs are reshaping vendor-customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleveland Clinic anchors cardiac surgery innovation, drawing device manufacturers to establish clinical validation partnerships in Northeast Ohio. Reimbursement frameworks in developed economies determine procedure accessibility and graft procurement volumes.
United States
Integrated delivery networks consolidate bypass device purchasing across cardiac surgery and interventional cardiology departments. FDA 510(k) substantial equivalence requirements favor established ePTFE polymer platforms over novel biomaterial submissions. Cleveland Clinic and Mayo Clinic anchor clinical trial infrastructure for graft patency studies.
Germany
Hospital federations negotiate volume-based price concessions for graft conduits and stabilizer platforms. EU MDR conformity assessment harmonizes technical documentation across the European Economic Area. DRG recalibration for complex coronary interventions incentivizes hybrid operating suite investment in Baden-Württemberg and Bavaria.
Japan
PMDA reimbursement adjustments for off-pump procedures expand patient pools beyond traditional sternotomy candidates. Extended follow-up requirements for foreign-manufactured implants force sponsors to conduct domestic registry studies. Tokyo and Osaka academic medical centers anchor clinical evidence generation for synthetic conduit approval.
India
Government medical college hospital upgrades create procurement channels for mid-tier bypass device portfolios. CDSCO medical device rules govern import licensing and post-market surveillance for cardiovascular implants. Maharashtra and Karnataka tertiary cardiac centers concentrate procedure volume and training program capacity.
United Kingdom
NHS England procurement frameworks standardize graft conduit specifications across cardiac surgery networks. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining domestic approval pathways. London and Manchester teaching hospitals anchor multi-center clinical studies for novel anastomosis technologies.
Global Coronary Artery Bypass Graft Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory validation capabilities and clinical evidence generation. The vendor base stratifies into three tiers: integrated cardiovascular conglomerates with captive polymer supply, specialized graft manufacturers with coating technology differentiation, and emerging entrants targeting price-sensitive procurement environments. Dominant competitive moves include backward integration into medical-grade resin production and strategic partnerships with academic medical centers for registry-based evidence development.
Within the integrated cardiovascular conglomerate tier, Medtronic and Abbott exemplify archetypes that control manufacturing from raw polymer through finished graft distribution. Terumo Corporation occupies a position among specialized coating technology providers that reduce thrombogenicity in synthetic conduits. W. L. Gore & Associates anchors the high-performance materials segment with expertise in expanded polytetrafluoroethylene applications. These three represent distinct strategic postures: full value chain control, functional specialization, and materials science depth.
| Leading Market Players |
|---|
| Medtronic |
| Terumo Corporation |
| Getinge AB |
| W. L. Gore & Associates |
| B. Braun SE |
| Abbott |
| LivaNova plc |
| Edwards Lifesciences |
| Genesee Biomedical |
| Others |
Supply & Pricing Matrix
Medical-grade ePTFE resin procurement costs cascade through three distinct pricing tiers as the material moves from specialty chemical producers in the United States and Japan through graft manufacturers to cardiac surgery centers in Germany and the United States.
Pricing Analysis
Input-cost pass-through from concentrated polymer feedstock suppliers governs margin structures across synthetic conduit tiers. Pricing stratifies across premium saphenous vein graft alternatives, standard polyester-based configurations, and economy-tier single-use stabilizer platforms. Cost compression in economy tiers intensifies as Indian tertiary centers expand procurement volume. Ambulatory surgical units exhibit highest price sensitivity; academic medical centers in Japan and Germany demonstrate lowest sensitivity due to bundled reimbursement frameworks.
Supply Chain Analysis
Medical-grade ePTFE resin supply rests on specialty chemical producers in the United States, Japan, and Germany, with graft manufacturers drawing from this tripartite concentration. Raw material dependencies center on fluoropolymer precursors, precision extrusion equipment, and biocompatibility testing capacity. Single-source vulnerability in resin supply exposes manufacturers to input price volatility. Distribution runs through direct manufacturer relationships with high-volume cardiac surgery centers and distributor networks serving smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Japan's extended PMDA clinical evidence requirements and India's streamlined CDSCO import pathways for mid-tier device portfolios.
For Market Incumbents: Anticipate margin compression from robotic-assisted anastomosis platforms by securing backward integration into coating technology supply. Consolidate procurement committee relationships across hybrid catheterization labs before interventional cardiology departments gain independent contracting authority. Prioritize EU MDR technical documentation remediation over novel biomaterial R&D to defend reimbursement eligibility in German hospital federations. For New Entrants and Emerging Players: Computational fluid dynamics-enabled graft design platforms offer a technology-first wedge into the preclinical validation services segment. Target India's government medical college hospital upgrades with mid-tier conduit portfolios priced below Medtronic and Terumo Corporation benchmarks. Pursue hospital system partnership models that bundle graft supply with endoscopic harvesting system placement. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed standalone R&D budgets for specialized coating technology providers. Five-to-ten-year viability favors acquirers of Japan-specific clinical registry infrastructure. Watch PMDA reimbursement adjustments for off-pump procedures as the inflection signal for robotic platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Substantial equivalence pathways in the United States favor established ePTFE platforms over novel biomaterials. |
| CE Marking Pathway | EU MDR harmonization reduces redundant testing burdens for multi-country European Economic Area access. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate bypass device purchasing across cardiac surgery and interventional cardiology. |
| Software Companion Development | Computational fluid dynamics platforms compress graft design iteration cycles and reduce animal study requirements. |
| Reimbursement Strategy | German DRG recalibration for complex coronary interventions incentivizes hybrid operating suite infrastructure investment. |
Research Methodology
Multiple input streams — cardiac surgeon interviews, hospital procurement committee discussions, biomedical engineering director consultations, and regulatory affairs specialist exchanges — were reconciled against FDA 510(k) filings, EU MDR technical documentation databases, PMDA reimbursement bulletins, and hospital procurement contract records. Bottom-up procedure volume estimates from cardiac surgery centers in the United States, Germany, Japan, India, and the United Kingdom were cross-validated against top-down manufacturer revenue allocations across graft conduits, stabilizers, and suturing systems.
Historical patent and clinical trial trajectories were cross-referenced against expert panel assessments of robotic platform adoption timelines and hybrid catheterization lab deployment rates. Segmentation modeling spanned product type, application complexity, end-user institutional scale, and deployment infrastructure across the projection horizon. CAGRs were derived from procedure volume elasticity to aging demographic shifts and reimbursement policy adjustments, with particular weighting applied to Japan's PMDA evidentiary requirements and Germany's DRG recalibration dynamics.
The model holds under stable regulatory convergence between FDA and EU MDR biocompatibility standards; deviation in polymer feedstock supply disruption or surgeon workforce constraint severity would shift volume and value trajectories. A small set of named triggers — PMDA off-pump reimbursement expansion velocity, Indian tertiary center upgrade budget allocation, and EU MDR legacy product remediation cost escalation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Bariatric Beds Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Snare Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Cardiac Implants Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Global Wearable Pregnancy Devices Market