
 Roflumilast API Market | 2026-2036
Roflumilast API Market Size, Share, and Industry Trends Forecast 2026-2036
Roflumilast API Market Insights
Buyer concentration among large respiratory drug developers is realigning contract manufacturing relationships across the roflumilast API supply base. Boehringer Ingelheim leverages its in-house fermentation and chemical synthesis expertise to sustain captive production of phosphodiesterase-4 inhibitor compounds. Aurobindo Pharma Limited anchors South Asian supply through large-volume API export operations serving European and North American formulators. Interquim SA specializes in high-purity custom synthesis for specialty pharmaceutical clients seeking GMP-compliant roflumilast intermediates.
Roflumilast API denotes the active pharmaceutical ingredient of a selective phosphodiesterase-4 inhibitor, synthesized through multi-step organic chemistry involving 3-(cyclopropylmethoxy)-N-(3,5-dichloropyridin-4-yl)-4-(difluoromethoxy)benzamide formation with final purity specifications typically exceeding 99.5% and stringent residual solvent controls under ICH Q3C guidelines. The compound serves primarily as a once-daily oral maintenance therapy for chronic obstructive pulmonary disease, reducing exacerbation frequency through anti-inflammatory mechanisms in lung tissue. Tablet formulations dominate current demand due to established bioequivalence pathways and patient compliance advantages, while injectable forms represent a faster-growing segment driven by hospital-based acute exacerbation protocols requiring rapid therapeutic onset. Chronic obstructive pulmonary disease applications command the largest volume share, though asthma management indications are gaining traction as clinicians explore broader phosphodiesterase-4 inhibition in reactive airway disease.
FDA enforces current good manufacturing practice standards through ICH Q7 and dedicated API inspection programs, while EMA's REACH and MDR frameworks govern import chemistry and device-drug combination products containing roflumilast. India's CDSCO and China's NMPA impose parallel registration requirements that shape market access timelines for multinational generic developers. Stakeholders must monitor evolving pharmacopeial monograph revisions and real-time release testing mandates that will determine which synthesis routes achieve sustainable regulatory approval across multiple jurisdictions.
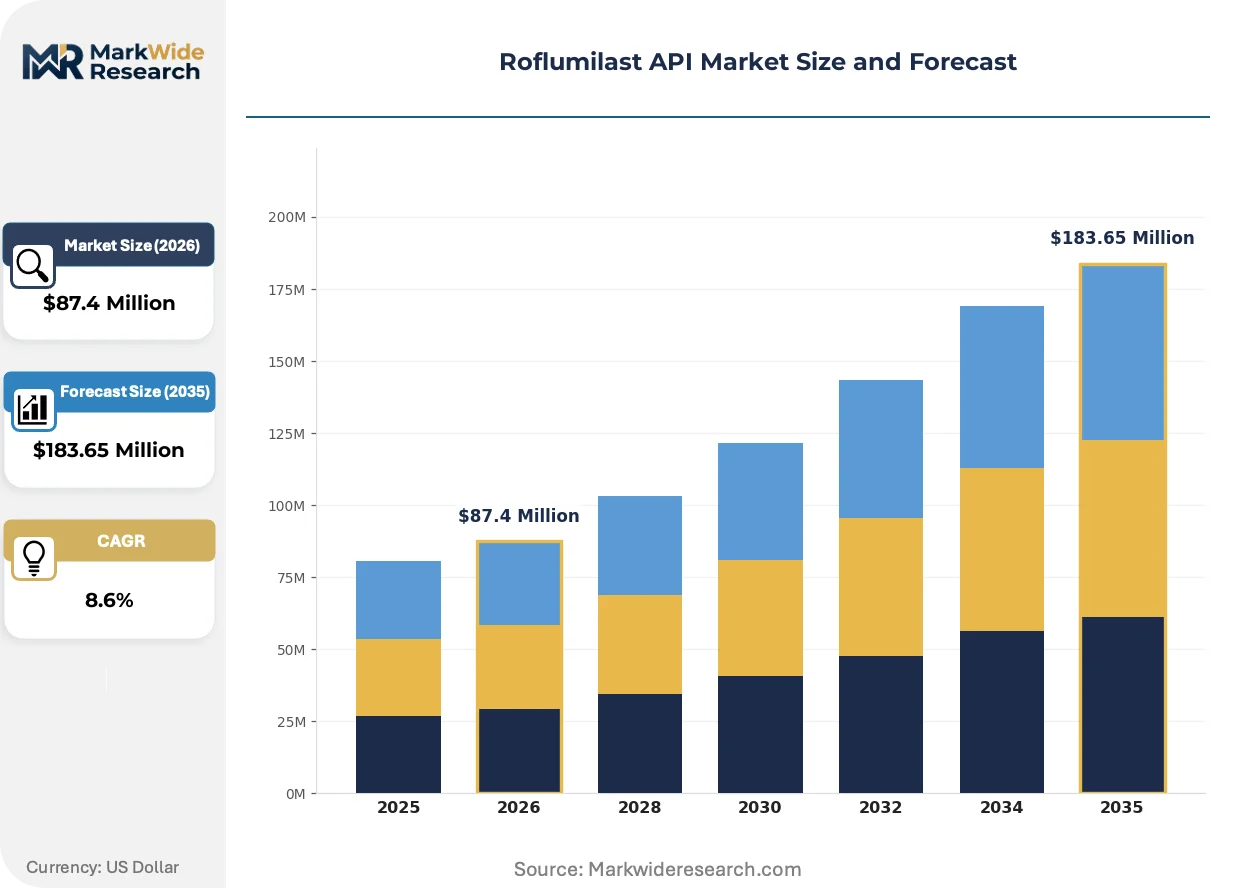
Market Dynamics
API procurement consolidation among respiratory drug developers is reshaping contract manufacturing relationships, with specialty pharmaceutical firms demanding captive synthesis capabilities and real-time release testing protocols to secure supply continuity for chronic obstructive pulmonary disease formulations.
Growth Catalysts
- ICH Q7 Compliance Mandates:Stringent good manufacturing practice standards are filtering out subscale producers, concentrating volume among qualified manufacturers capable of residual solvent control below ICH Q3C thresholds.
- Hospital-Based Acute Protocols:Injectable roflumilast formulations for exacerbation management are expanding addressable demand beyond maintenance tablet therapy into emergency respiratory care settings.
- India:Large-scale chemical synthesis infrastructure and cost-competitive technical labor are positioning Indian API exporters to capture incremental volume from European and North American formulators seeking dual-source strategies.
Market Restraints
- Fluorinated Intermediate Volatility:Difluoromethoxybenzamide precursors face input cost instability due to constrained supply of fluorinating agents and energy-intensive halogenation processes.
- Single-Geography Concentration:Bulk fermentation and chemical synthesis capacity clusters in China and India, creating exposure to regional logistics disruptions and export license delays.
- Substitution Pressure:Inhaled corticosteroid-long-acting beta-agonist combinations and emerging biologics for COPD compete for prescriber preference and formulary placement against oral phosphodiesterase-4 inhibitors.
Strategic Opportunities
- United States:Underpenetrated specialty pharmacy distribution for oral maintenance therapies creates white space for direct-to-patient API-formulator partnerships bypassing traditional wholesale channels.
- Asthma Indication Expansion:Clinician exploration of phosphodiesterase-4 inhibition in reactive airway disease is opening adjacent therapeutic applications beyond established COPD labeling.
- Continuous Flow Chemistry:Adoption of microreactor synthesis platforms by contract manufacturers is enabling process intensification that reduces batch cycle times and solvent waste profiles.
Industry Challenges
- Analytical Method Transfer:Cross-site validation of impurity profiling and dissolution testing protocols creates timeline friction when shifting production between contract manufacturing organizations.
- Genotoxic Impurity Control:Nitrosamine risk assessment and control strategy implementation for secondary amine intermediates demands specialized toxicology expertise and extended development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roflumilast API Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Solutions, Injectable Forms, Powders Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Respiratory Disorders, Other Therapeutic Areas End User: Hospitals, Clinics, Pharmacies, Research Institutions Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retail Pharmacies |
| Companies Covered | Boehringer Ingelheim, AstraZeneca, Novartis, Teva Pharmaceutical Industries, Pfizer, Merck & Co., Sanofi, Aurobindo Pharma Limited, Interquim SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roflumilast API Market Trends and Innovations
Process analytical technology and real-time release testing are displacing traditional batch-release paradigms, while regulatory convergence around ICH quality guidelines is harmonizing compliance burdens across major pharmaceutical markets.
Continuous manufacturing platforms for multi-step organic synthesis are absorbing development investment from leading contract development organizations. Specialty API producers in India and Europe are retrofitting batch facilities with flow chemistry modules to achieve tighter process control and reduced solvent consumption. This technology transition is compressing batch-to-batch variability and enabling just-in-time inventory models for respiratory drug formulators.
EMA's evolving nitrosamine impurity guidelines and FDA's quality metrics reporting requirements are tightening residual contaminant thresholds for phosphodiesterase-4 inhibitor synthesis. API manufacturers must implement enhanced analytical testing and supplier qualification protocols to maintain regulatory approval across European and North American markets. Small-scale custom synthesis houses face disproportionate compliance cost burdens relative to high-volume commodity producers.
Direct sourcing relationships between respiratory drug developers and API manufacturers are displacing traditional distributor intermediaries in procurement channels. Large pharmaceutical formulators are negotiating multi-year supply agreements with embedded capacity reservations and audit rights. This channel consolidation is most visible in North America and Western Europe, where buyer concentration among specialty pharmaceutical firms has strengthened negotiating leverage over contract manufacturing pricing and service terms.
Roflumilast API Market Segmentation
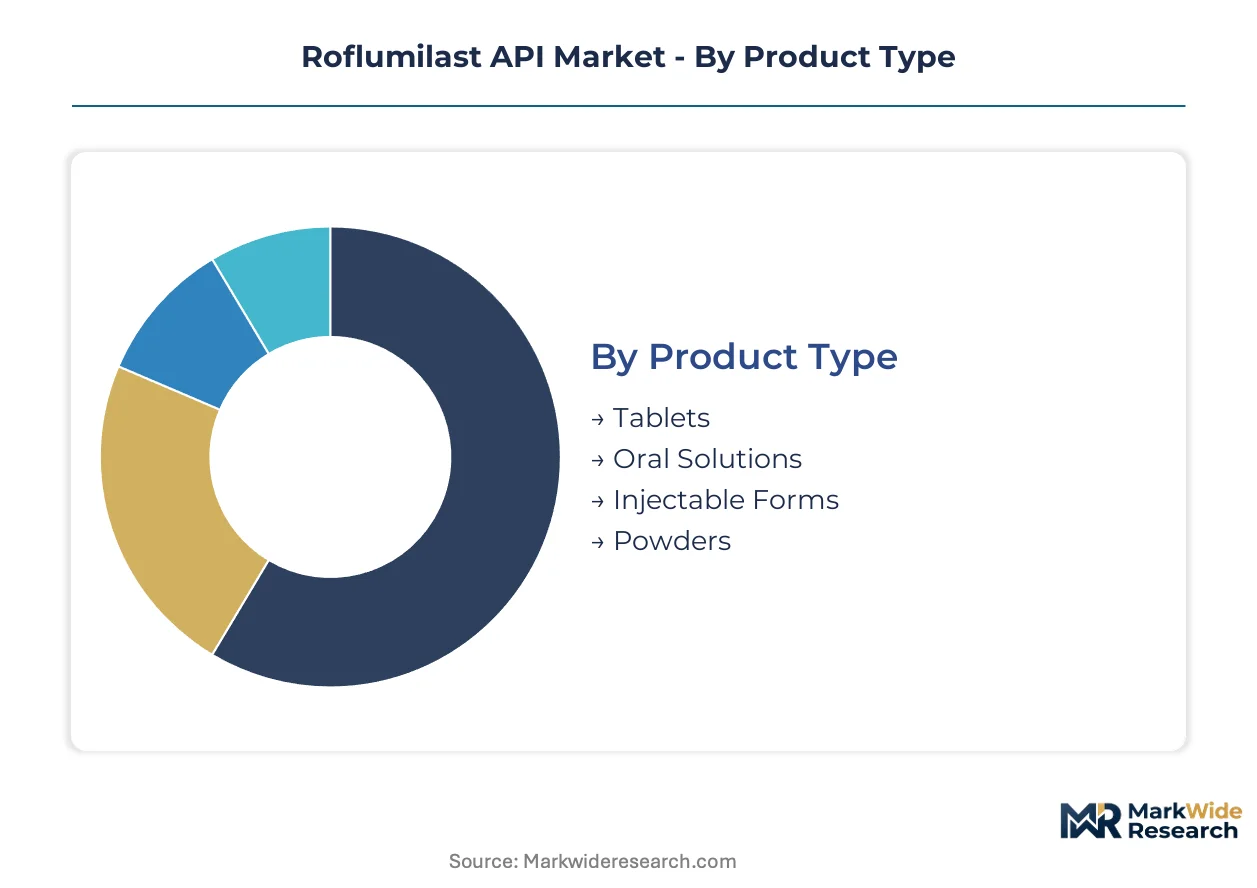
Roflumilast API demand fragments across formulation types, therapeutic applications, and procurement channels. Understanding these segment boundaries clarifies where contract manufacturers should concentrate capacity investments and compliance resources.
Product Type:
Formulation complexity and regulatory pathway duration separate buyers in this category.
- Tablets:Compressed solid dosage forms containing roflumilast with established bioequivalence pathways dominate current procurement volumes. North American specialty pharmaceutical developers source tablet-grade API under long-term supply agreements with embedded audit rights and real-time release testing protocols.
- Injectable Forms:Sterile liquid formulations for hospital-based acute exacerbation management require advanced aseptic processing capabilities and endotoxin controls. European respiratory drug developers are expanding procurement of parenteral-grade API as emergency care protocols adopt phosphodiesterase-4 inhibition for rapid therapeutic onset.
- Oral Solutions:Liquid formulations for pediatric or geriatric populations with swallowing difficulties.
- Powders:Bulk API for in-house formulation or compounding pharmacy applications.
Volume sits with Tablets; growth tilts toward Injectable Forms.
Application:
Prescriber familiarity and reimbursement density determine API consumption patterns across therapeutic targets.
- Chronic Obstructive Pulmonary Disease:Maintenance therapy for reducing exacerbation frequency in COPD patients represents the anchor indication with mature clinical guidelines. Indian API exporters serve European and North American formulators seeking cost-competitive supply for this high-volume, price-sensitive segment.
- Asthma Management:Off-label and emerging label use of phosphodiesterase-4 inhibition in reactive airway disease is gaining clinician traction. Research institutions in Germany and the United Kingdom are driving exploratory demand for GMP-compliant API in investigator-initiated trials.
- Respiratory Disorders:Broader inflammatory lung conditions beyond COPD and asthma.
- Other Therapeutic Areas:Investigational applications including psoriasis and inflammatory bowel disease.
Revenue concentrates in Chronic Obstructive Pulmonary Disease; Asthma Management is climbing the fastest.
End User:
Procurement scale and quality documentation requirements distinguish customer types in this dimension.
- Hospitals:Large-volume purchasers of parenteral formulations for acute care protocols with stringent cold-chain and traceability mandates. Hospital procurement departments in the United States negotiate direct API-formulator relationships bypassing traditional wholesale intermediaries.
- Clinics:Outpatient facilities prescribing oral maintenance therapies with recurring prescription patterns.
- Pharmacies:Retail dispensers of chronic medications with inventory turnover constraints.
- Research Institutions:Small-batch purchasers for clinical trial material and mechanistic studies.
Procurement scale peaks at Hospitals; Research Institutions show the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer sophistication, volume scale, and geographic proximity to manufacturing.
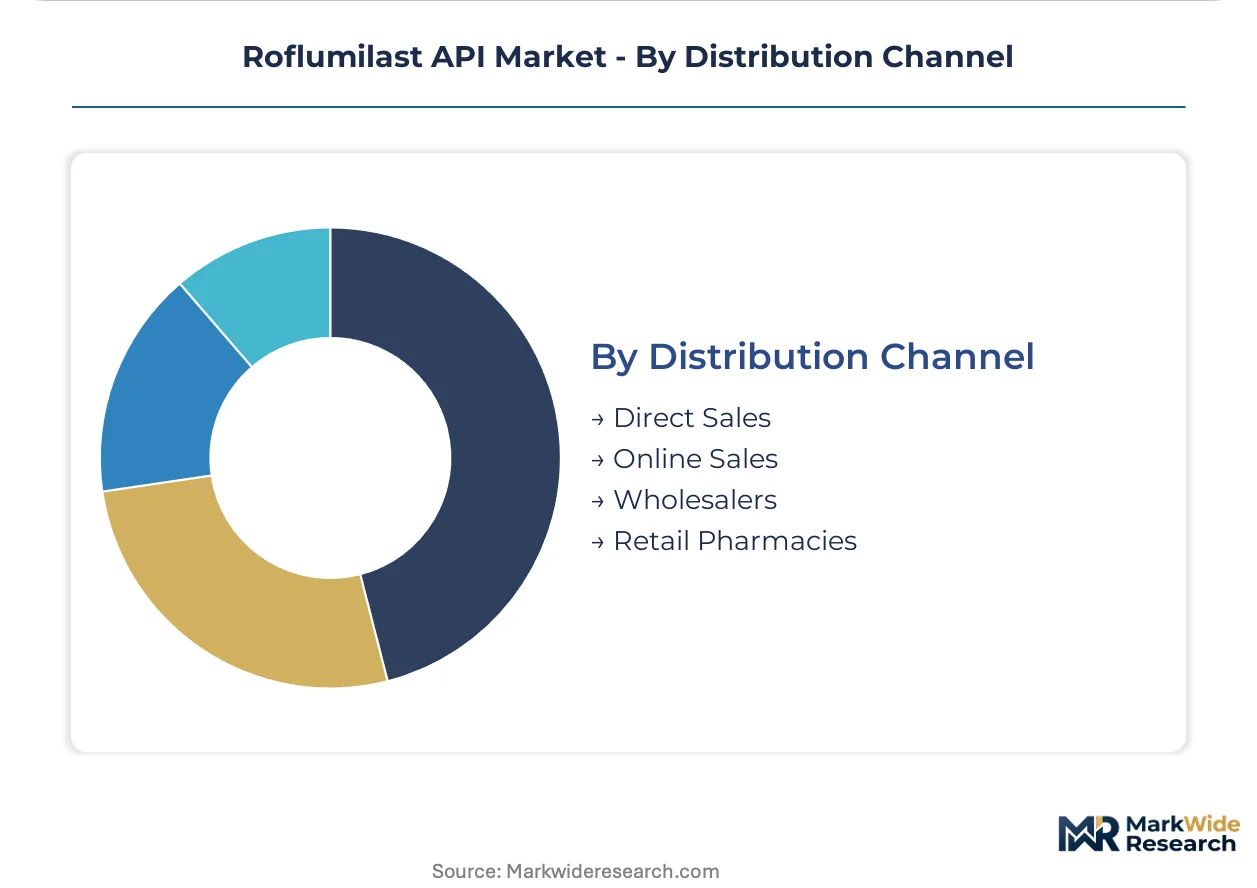
- Direct Sales:Long-term supply agreements between API manufacturers and respiratory drug developers with embedded capacity reservations. Direct relationships are displacing distributor intermediaries in North America and Western Europe as buyer concentration strengthens negotiating leverage.
- Wholesalers:Traditional intermediaries serving mid-tier formulators without dedicated procurement infrastructure.
- Online Sales:Digital procurement platforms for small-volume buyers and research institutions.
- Retail Pharmacies:End-channel dispensers with limited API procurement relevance.
Transaction volume flows through Direct Sales; Online Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorinated benzamide precursor production concentrates in Zhejiang and Jiangsu provinces, anchoring East Asian supply chains for phosphodiesterase-4 inhibitor synthesis. European formulators source heavily from this manufacturing corridor while building secondary supply relationships across the Indian subcontinent.
China
Hospital procurement of parenteral-grade API for acute COPD exacerbation protocols is expanding in Shanghai and Beijing medical centers. NMPA enforces ICH Q7 alignment through intensified API facility inspections and real-time release testing mandates. The Yangtze River Delta chemical manufacturing cluster around Nantong and Taizhou hosts multi-step organic synthesis operations serving European respiratory drug developers.
India
Contract manufacturing organizations in Hyderabad and Visakhapatnam are securing long-term supply agreements with North American specialty pharmaceutical firms. CDSCO's parallel registration requirements for API export certification are compressing market access timelines for multinational generic developers. The Pharma City corridor outside Hyderabad is attracting capacity investments from fermentation and chemical synthesis specialists targeting regulated markets.
United States
Specialty pharmacy distribution channels for oral maintenance therapies are creating procurement white space for direct API-formulator partnerships. FDA's quality metrics reporting requirements and dedicated API inspection programs are elevating compliance thresholds for imported active pharmaceutical ingredients. The Research Triangle Park cluster in North Carolina anchors respiratory drug development operations with embedded analytical method transfer capabilities.
Germany
Research institutions in Munich and Heidelberg are driving exploratory demand for GMP-compliant API in investigator-initiated asthma management trials. EMA's REACH frameworks and evolving nitrosamine impurity guidelines are tightening residual contaminant thresholds for phosphodiesterase-4 inhibitor synthesis. The Rhine-Main chemical manufacturing region around Frankfurt maintains specialist capabilities for high-purity custom synthesis serving European formulators.
Switzerland
Swissmedic's stringent pharmacopeial monograph enforcement is shaping synthesis route selection for API producers seeking Alpine market access. Basel's pharmaceutical innovation cluster supports early-phase clinical material supply relationships with global respiratory drug developers. The country's precision chemical manufacturing heritage sustains niche capabilities for fluorinated intermediate production under ICH Q3C residual solvent controls.
Roflumilast API Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue continuous flow chemistry platforms and real-time release testing protocols to differentiate contract manufacturing offerings. The supply base concentrates among qualified manufacturers capable of ICH Q7 compliance and residual solvent control below regulatory thresholds. Three archetypes dominate: vertically integrated innovators with in-house fermentation expertise, large-volume API exporters leveraging cost-competitive synthesis infrastructure, and high-purity custom synthesis houses serving specialty pharmaceutical clients. Competitive positioning hardens around multi-year supply agreements with embedded capacity reservations, while process intensification investments compress batch cycle times.
Among European-anchored innovators, Boehringer Ingelheim exemplifies the vertically integrated archetype with captive phosphodiesterase-4 inhibitor production capabilities. Aurobindo Pharma Limited occupies a position within the large-volume API export tier, serving formulators in regulated markets through South Asian manufacturing infrastructure. Interquim SA represents the high-purity custom synthesis segment, anchoring specialist capabilities for GMP-compliant intermediate supply to respiratory drug developers.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| AstraZeneca |
| Novartis |
| Teva Pharmaceutical Industries |
| Pfizer |
| Merck & Co. |
| Sanofi |
| Aurobindo Pharma Limited |
| Interquim SA |
| Others |
Pricing and Supply Chain Analysis
Fluorinated intermediate synthesis specialists concentrated in Zhejiang province command wage premiums that compress standard-tier margins while amplifying spreads between GMP-certified premium supply and unvalidated economy-grade material. Labor-cost differentials between the Yangtze River Delta and South Asian chemical corridors directly determine pricing-tier spreads for difluoromethoxybenzamide precursors.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements for tablet-grade API, while margin capture sits with parenteral formulations requiring endotoxin validation and aseptic processing certification. Price differentiation hinges on ICH Q7 compliance tier and real-time release testing capability, with European formulators paying premiums for embedded audit rights. Cost compression in standard-grade supply is intensifying because Indian exporters are absorbing CDSCO registration fees to secure North American contracts. Research institutions show highest price sensitivity; hospital procurement departments demonstrate lowest sensitivity due to formulary lock-in.
Supply Chain Analysis
Difluoromethoxybenzamide precursor supply rests on Chinese fluorinating agent producers and Indian contract manufacturing organizations with multi-step organic synthesis capabilities. Raw material dependencies include cyclopropylmethanol, dichloropyridine intermediates, and specialty fluorinating reagents under ICH Q3C residual solvent controls. Single-source vulnerability concentrates in Zhejiang province halogenation facilities, where energy-intensive processes face grid reliability exposure. Distribution runs through direct sales relationships with embedded capacity reservations, displacing wholesale intermediaries in North American and Western European procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: qualified GMP manufacturing capacity for phosphodiesterase-4 inhibitor synthesis remains bottlenecked by ICH Q7 inspection backlogs, propping pricing power for validated producers.
For Market Incumbents: Deploy continuous flow chemistry retrofit programs to compress batch cycle times and defend margin position against emerging entrants with greenfield microreactor platforms. Incumbents should anchor backward integration into difluoromethoxybenzamide precursor production to offset fluorinating agent cost volatility. Captive synthesis capabilities insulate against substitution pressure from inhaled corticosteroid-long-acting beta-agonist combinations.
For New Entrants and Emerging Players: Begin with parenteral-grade API supply for hospital-based acute exacerbation protocols, the most penetrable segment given European respiratory drug developers' procurement expansion. Target research institutions in Germany and the United Kingdom with GMP-compliant material for investigator-initiated asthma management trials. A specialty synthesis positioning with embedded toxicology expertise for nitrosamine risk assessment offers differentiation against commodity producers.
For Investors and Strategic Acquirers: Re-rating potential sits with high-purity custom synthesis houses given EMA's evolving nitrosamine impurity guidelines and FDA quality metrics reporting requirements. Long-term viability favors producers with demonstrated ICH Q7 compliance and multi-jurisdiction regulatory approval across the projection horizon. Watch CDSCO and NMPA inspection clearance timelines as the inflection indicator for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Microreactor platforms enable process intensification that reduces solvent waste and batch variability for respiratory drug formulators. |
| Backward Integration into Fluorinated Intermediates | In-house production of difluoromethoxybenzamide precursors mitigates input cost instability from constrained fluorinating agent supply. |
| Real-Time Release Testing Implementation | Process analytical technology protocols satisfy FDA quality metrics mandates and compress market access timelines for multinational generic developers. |
| Multi-Jurisdiction Regulatory Approval | Parallel ICH Q7 alignment across FDA, EMA, CDSCO, and NMPA frameworks secures supply continuity for dual-source procurement strategies. |
| Long-Term Supply Agreement Negotiation | Embedded capacity reservations with audit rights strengthen negotiating leverage over contract manufacturing pricing and service terms. |
Research Methodology
Multi-period observation of API procurement volumes, regulatory inspection clearance rates, and contract manufacturing pricing trends anchored the trend analysis, supplemented by interviews with regulatory affairs leads at European respiratory drug developers, CDSCO registration specialists, hospital procurement managers, and chemical synthesis plant managers. Secondary validation drew from FDA API inspection databases, EMA nitrosamine impurity guidance documents, CDSCO export certification records, and customs trade data for fluorinated intermediate flows. Bottom-up volume modeling and top-down market sizing triangulated demand estimates across formulation types and therapeutic applications.
Segment-weighting approaches distributed value projections across tablet and injectable formulation tiers, with COPD maintenance therapy and asthma management applications modeled separately. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking capacity expansion announcements across the analysis window. Forecast inputs incorporated ICH Q7 compliance cost trajectories, fluorinating agent price indices, and real-time release testing adoption curves by contract manufacturing organizations.
Underlying measurement precision varies by segment; tablet-grade API procurement carries tighter precision than exploratory research institution demand. Forecasts reflect assumptions about regulatory inspection throughput, fluorinated intermediate supply stability, and substitution dynamics from emerging biologics. A small set of triggers warrants ongoing watch: CDSCO registration timeline compression, NMPA inspection intensity shifts, and clinician adoption of phosphodiesterase-4 inhibition in reactive airway disease.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Simvastatin Market