
 Europe Chronic Disease Management Market | 2026-2036
Europe Chronic Disease Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chronic Disease Management Market Insights
Hospital procurement teams is rotating toward home healthcare and remote consultation models as reimbursement frameworks evolve. Philips sustains technology leadership in connected monitoring devices across Dutch and German hospital networks. Medtronic anchors therapeutic equipment supply through deep clinical relationships with European cardiac centers. Epic Systems dominates electronic health record integration for chronic care workflows in France and the Nordic region.
Chronic disease management encompasses coordinated clinical interventions, patient monitoring protocols, and data-driven care pathways designed to reduce acute episodes and slow disease progression in long-term conditions such as diabetes, hypertension, and cardiovascular disorders. Platforms incorporate continuous glucose monitoring thresholds, blood pressure telemetry, and algorithmic risk stratification to enable proactive intervention before decompensation. Telehealth solutions and mobile apps capture the fastest expansion as patient-facing interfaces mature, while monitoring devices retain the largest installed base and recurring revenue pool. Hospital-based delivery still occupies the dominant share of spend, though home healthcare segments are narrowing the gap as ambulatory reimbursement expands.
EMA medical device guidance, EU Medical Device Regulation (MDR) software classifications, and GDPR health data provisions collectively determine product registration timelines and cross-border data architecture for platform vendors. MDR compliance costs particularly burden smaller telehealth developers seeking CE marking for algorithm-based diagnostic support. Stakeholders must track how national health technology assessment bodies weigh remote monitoring outcomes against traditional in-person care metrics.
Market Dynamics
EU Medical Device Regulation software classifications are forcing platform vendors to re-architect data pipelines and clinical validation protocols, compressing product development timelines while raising capital requirements for algorithm-based diagnostic tools.
Growth Catalysts
- Integrated care networks:Germany's Gesundes Kinzigtum model demonstrates how capitated reimbursement pools incentivize preventive monitoring investments across hospital-primary care handoffs.
- MDR Article 10 clinical evidence requirements:The regulation's software-as-medical-device pathway creates regulatory clarity that accelerates CE marking for validated chronic disease algorithms.
- Continuous glucose monitoring:Sensor-to-cloud architectures enable real-time glycemic pattern recognition that reduces diabetic ketoacidosis admissions in Dutch hospital networks.
Market Restraints
- GDPR health data architecture:Cross-border patient data flows require national data localization infrastructure that fragments platform economics and duplicates hosting costs.
- Notified body capacity:Concentration of MDR certification capacity in Germany and the Netherlands creates queuing delays that extend time-to-revenue for telehealth developers.
- Legacy EHR interoperability:Proprietary data formats in French and Nordic hospital systems impose integration tax on remote monitoring deployments.
Strategic Opportunities
- Poland and Romania:Underpenetrated ambulatory care networks present first-mover advantages for remote patient monitoring vendors as EU cohesion funds modernize primary care infrastructure.
- EU AI Act high-risk system classification:Early compliance with clinical AI transparency requirements positions vendors for preferred procurement status in public health tenders.
- Pharmacy channel convergence:Community pharmacies in Spain and Italy are expanding into chronic care coaching, creating new distribution nodes for connected monitoring devices.
Industry Challenges
- Clinical informatics talent scarcity:Shortage of professionals who bridge algorithm development and clinical workflow design slows deployment velocity in French hospital systems.
- MDR technical documentation burden:Post-market surveillance requirements demand dedicated regulatory affairs capacity that strains mid-sized telehealth developers.
- Multi-stakeholder data governance:Aligning hospital IT, primary care networks, and patient consent frameworks across Belgian regional health authorities complicates platform rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chronic Disease Management Market |
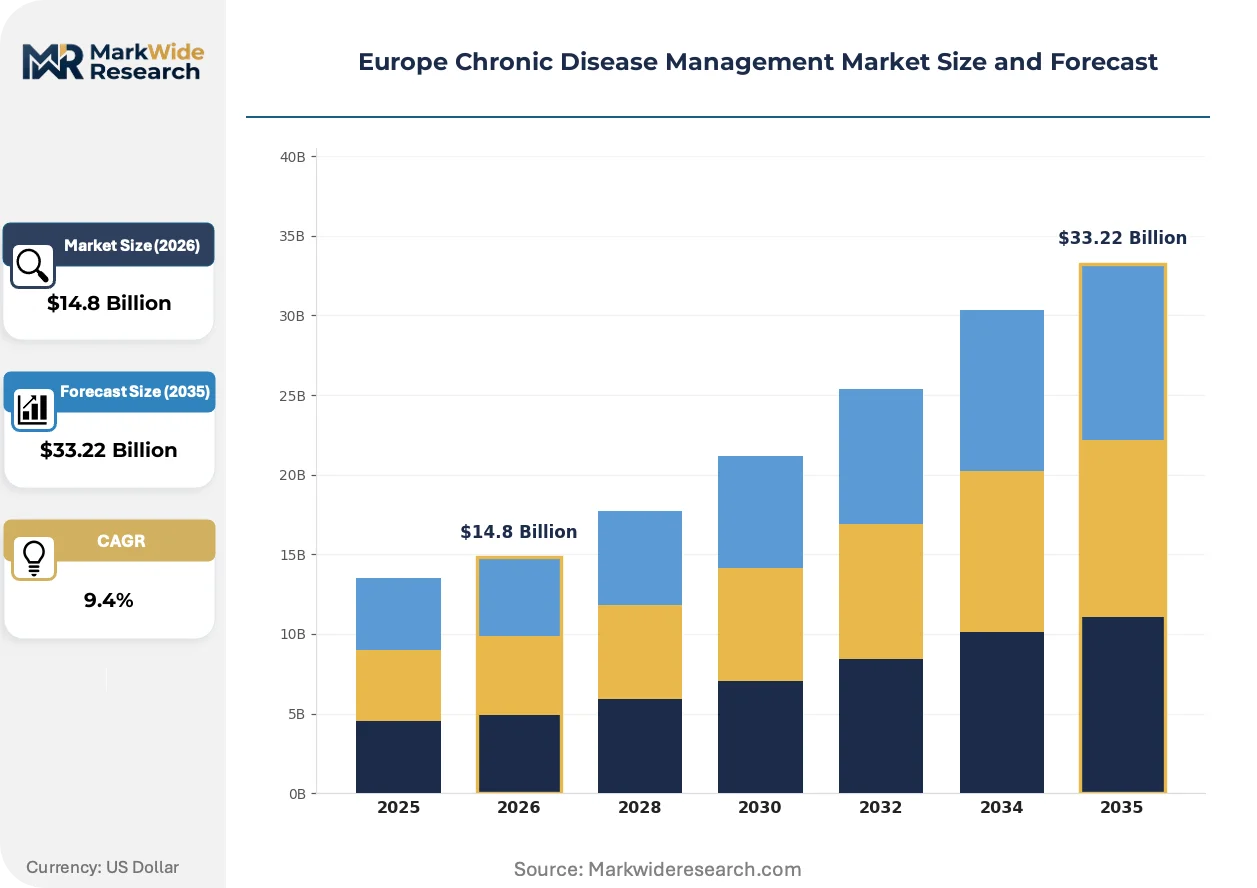
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Therapeutic Equipment, Mobile Apps, Telehealth Solutions Delivery Mode: In-person, Remote Consultation, Hospital-based, Home Healthcare End User: Healthcare Providers, Patients, Caregivers, Insurance Companies Condition Type: Diabetes, Hypertension, Asthma, Chronic Pain |
| Companies Covered | Koninklijke Philips N.V., Infosys Limited, Health Catalyst, Inc., Allscripts Healthcare Solutions, Inc., Epic Systems Corporation, ExlService Holdings, Inc., Medtronic, Cognizant Technology Solutions, WellSky, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chronic Disease Management Market Trends and Innovations
Algorithmic risk stratification and wearable form-factor compression are converging to shift chronic disease surveillance from episodic clinic visits toward continuous, ambient monitoring architectures embedded in daily routines.
Continuous glucose monitoring hardware is miniaturizing from patch-based sensors toward microneedle arrays and optical non-invasive prototypes. Nordic diabetes centers are piloting these reduced-footprint devices for Type 2 populations previously non-compliant with fingerstick protocols. The technology is miniaturizing the addressable market by removing adherence barriers that excluded less-motivated patient segments from monitoring programs.
EMA's 2023 guidance on clinical evidence for software medical devices tightens validation requirements for algorithmic diagnostic outputs. The framework mandates prospective clinical studies for risk stratification tools that previously relied on retrospective training data. Cardiac monitoring platforms targeting atrial fibrillation detection face the steepest compliance curve, with several vendors redesigning study protocols to meet the new evidentiary threshold.
Hospital procurement teams in Germany and the Netherlands are bundling remote monitoring hardware with outcome guarantees that tie vendor payments to reduced admission rates. The risk-transfer mechanism displaces traditional capital equipment purchasing in integrated care contracts. This model concentrates most visibly in diabetes and heart failure programs where acute episode costs are quantifiable and intervention timelines are compressed.
Europe Chronic Disease Management Market Segmentation
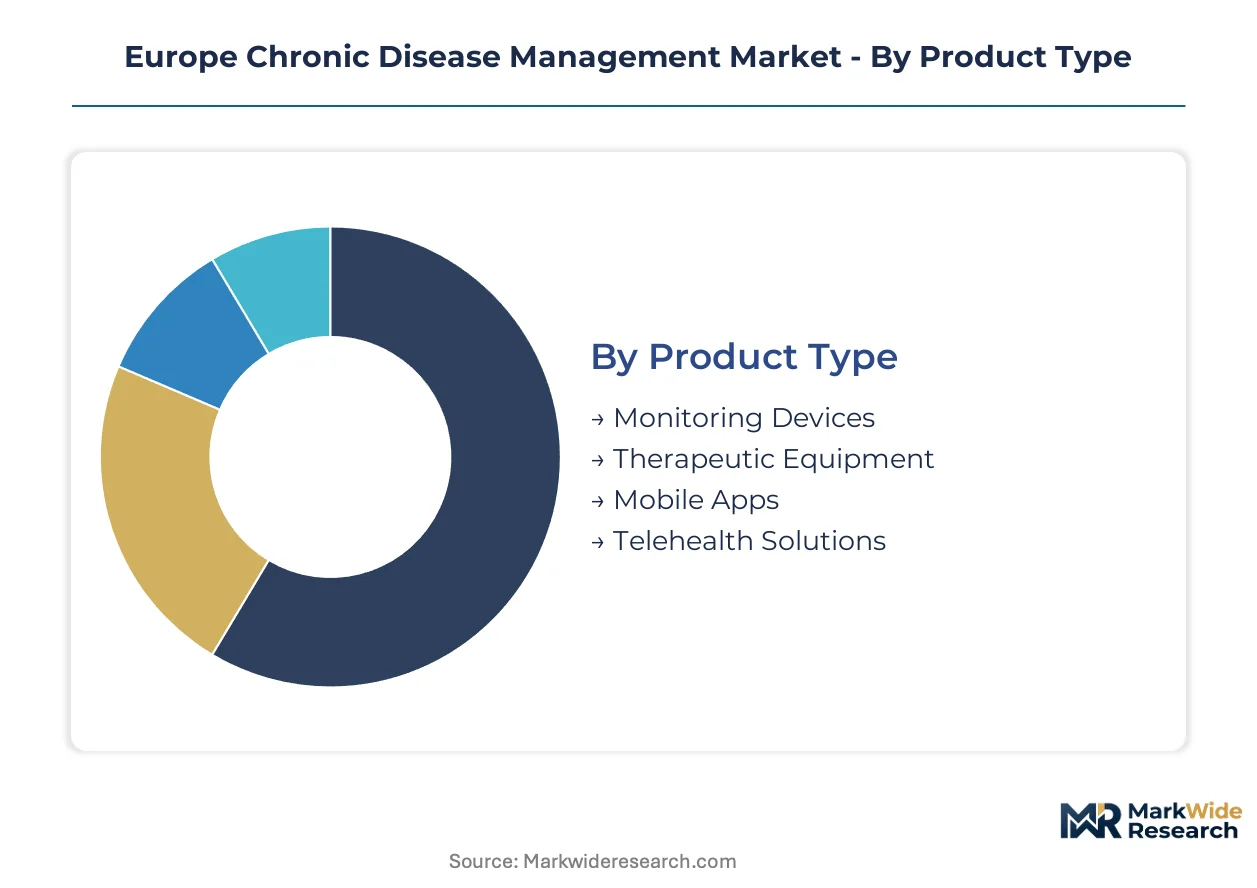
Chronic disease management platforms fragment across four intersecting dimensions that determine reimbursement pathways, regulatory classification, and procurement authority. Understanding how product specifications align with delivery infrastructure and end-user decision rights clarifies go-to-market architecture for platform vendors.
Product Type:
German and Dutch hospital networks drive demand for monitoring devices and therapeutic equipment, while telehealth solutions and mobile apps attract export-led adoption from Southern and Eastern European markets seeking lower-cost entry points.
- Monitoring Devices:Continuous glucose monitors, blood pressure telemetry units, and pulse oximeters form the hardware backbone of integrated care networks. Philips and Medtronic supply Dutch cardiac centers and German diabetes clinics with sensor-to-cloud architectures that feed directly into hospital EHR systems. These devices retain the largest installed base and recurring revenue pool across European chronic care programs.
- Telehealth Solutions:Video consultation platforms and asynchronous messaging systems capture the steepest expansion trajectory as France and the Nordic region scale ambulatory reimbursement. GDPR-compliant hosting infrastructure and MDR software classification requirements concentrate development investment in Germany and the Netherlands, creating geographic supply concentration that shapes vendor selection criteria.
- Therapeutic Equipment:Insulin pumps, nebulizers, and cardiac resynchronization devices anchor deep clinical relationships with European specialist centers.
- Mobile Apps:Patient-facing interfaces for medication adherence and symptom tracking proliferate fastest in Spain and Italy where pharmacy channel convergence creates new distribution nodes.
Monitoring Devices holds the largest share; momentum sits with Telehealth Solutions.
Delivery Mode:
Cost tier differentiation separates capital-intensive hospital-based programs from leaner home healthcare models that reduce per-episode expenditure.
- Hospital-based:Inpatient chronic care units and specialized diabetes centers in Germany and France maintain dominant spend share through integrated capitated contracts. These programs bundle remote monitoring hardware with outcome guarantees that tie vendor payments to reduced admission rates, displacing traditional equipment purchasing.
- Home Healthcare:Ambulatory nursing services and domiciliary monitoring expand fastest as Belgium and the Netherlands extend reimbursement for remote patient surveillance. EU cohesion funds modernizing primary care infrastructure in Poland and Romania prioritize home-based delivery to stretch limited specialist capacity.
- In-person:Traditional clinic visits retain residual volume in markets with slower telehealth reimbursement adoption.
- Remote Consultation:Synchronous video and asynchronous provider messaging bridge geographic access gaps in rural France and Nordic regions.
Hospital-based delivery commands current spend; Home Healthcare is climbing the fastest.
End User:
Customer type determines procurement authority, with healthcare providers holding formal buying power while patients and caregivers influence adherence and device selection.
- Healthcare Providers:Hospital procurement teams and primary care networks in Germany and the Netherlands rotate toward outcome-based contracting that transfers admission risk to vendors. Epic Systems dominates EHR integration requirements that gate platform deployment in French and Nordic hospital systems.
- Patients:Direct-to-consumer device purchases and app subscriptions grow in Spain and Italy where pharmacy networks expand chronic care coaching services. Continuous glucose monitoring miniaturization removes adherence barriers for Type 2 populations previously non-compliant with fingerstick protocols.
- Caregivers:Family members and professional home aides utilize monitoring dashboards to coordinate handoffs between hospital discharge and community care.
- Insurance Companies:German sickness funds and Dutch health insurers increasingly pre-approve remote monitoring expenditures as part of integrated care network capitation.
Healthcare Providers retain formal procurement authority; Patients are gaining share fastest as direct purchasing channels mature.
Condition Type:
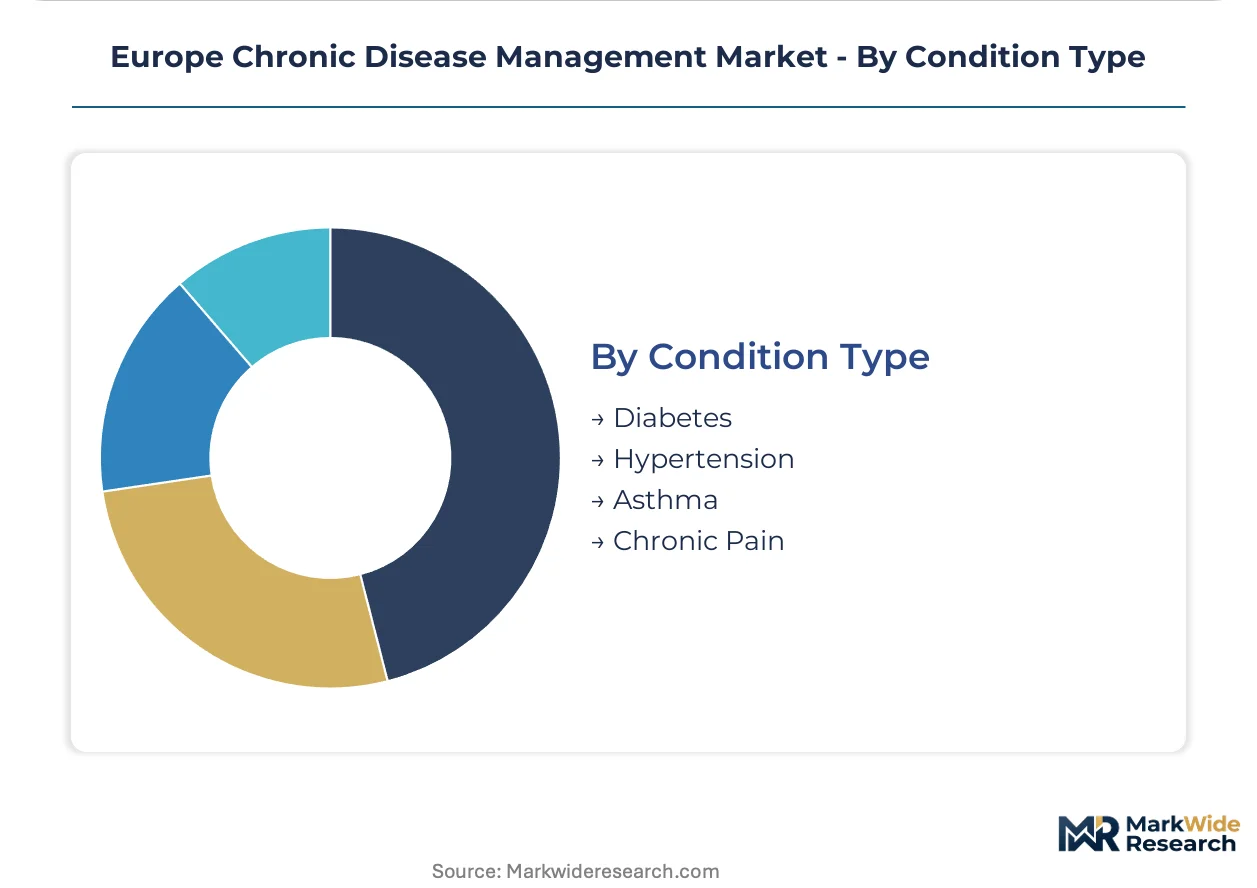
Application focus shapes clinical validation requirements and algorithmic risk stratification complexity, with cardiovascular and metabolic conditions offering the most quantifiable outcome metrics.
- Diabetes:Continuous glucose monitoring and insulin delivery systems anchor the most mature remote monitoring programs. Dutch hospital networks demonstrate quantifiable reductions in diabetic ketoacidosis admissions through real-time glycemic pattern recognition, creating template contracts that vendors replicate across German integrated care networks.
- Hypertension:Blood pressure telemetry enables proactive intervention before decompensation, though outcome attribution proves more diffuse than glucose monitoring. French primary care networks pilot bundled payment models for hypertensive populations with elevated stroke risk.
- Asthma:Peak flow monitoring and environmental trigger alerts concentrate in pediatric populations where caregiver engagement drives adherence.
- Chronic Pain:Multimodal monitoring combining activity tracking and patient-reported outcomes faces steeper GDPR consent complexity for subjective data capture.
Diabetes holds the largest share; momentum sits with Hypertension as outcome attribution methodologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German integrated care networks export remote monitoring protocols to Dutch hospital systems, establishing a cross-border clinical standards corridor that shapes procurement specifications across the Low Countries.
Germany
Gesundes Kinzigtum capitated contracts drive preventive monitoring investments across hospital-primary care handoffs. MDR Article 10 clinical evidence requirements create regulatory clarity that accelerates CE marking for validated chronic disease algorithms. Berlin-Brandenburg health clusters concentrate notified body capacity that extends certification queues for telehealth developers.
Netherlands
Dutch cardiac centers demand sensor-to-cloud architectures feeding directly into hospital EHR systems. GDPR health data provisions mandate national data localization infrastructure that fragments platform economics. Rotterdam-Delft medtech corridors pilot continuous glucose monitoring miniaturization for Type 2 populations previously non-compliant with fingerstick protocols.
France
French primary care networks pilot bundled payment models for hypertensive populations with elevated stroke risk. ANSM and CNIL jointly oversee medical device and data protection compliance that lengthens product registration timelines. Paris-Saclay hospital clusters anchor Epic Systems dominance in electronic health record integration for chronic care workflows.
Spain
Community pharmacies expand chronic care coaching services, creating new distribution nodes for connected monitoring devices. EU cohesion funds modernize primary care infrastructure in underpenetrated ambulatory networks. Barcelona-Madrid pharmacy chains capture patient-facing interface expansion as direct purchasing channels mature.
Poland
Underpenetrated ambulatory care networks present first-mover advantages for remote patient monitoring vendors. EU cohesion funds prioritize home-based delivery to stretch limited specialist capacity. Warsaw-Kraków hospital systems rotate toward outcome-based contracting that transfers admission risk to platform vendors.
Europe Chronic Disease Management Market Competitive Landscape
Player mix skews toward diversified health technology conglomerates and specialized clinical software developers. Market structure concentrates around three tiers: integrated device-platform vendors, standalone telehealth developers, and health IT services providers. Dominant competitive moves include M&A for regulatory capability acquisition and strategic partnerships for EHR interoperability.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and Medtronic exemplify integrated device-platform archetypes that anchor hardware supply through deep clinical relationships with European cardiac and diabetes centers. Epic Systems Corporation occupies a position within the clinical software tier, representing EHR integration requirements that gate platform deployment in French and Nordic hospital systems.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Infosys Limited |
| Health Catalyst, Inc. |
| Allscripts Healthcare Solutions, Inc. |
| Epic Systems Corporation |
| ExlService Holdings, Inc. |
| Medtronic |
| Cognizant Technology Solutions |
| WellSky |
| Others |
Pricing and Supply Chain Analysis
EU Medical Device Regulation software classifications gate both supply qualification and price differentiation simultaneously, as CE marking tiers separate validated algorithm vendors from uncertified competitors while MDR Article 10 clinical evidence requirements compress development timelines and concentrate procurement authority in German and Dutch hospital networks.
Pricing Analysis
Current-generation continuous glucose monitoring patches command premium positioning against prior-generation fingerstick systems and emerging optical non-invasive prototypes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from notified body queuing delays that extend time-to-revenue for telehealth developers. Home healthcare segments exhibit highest price sensitivity as EU cohesion funds constrain procurement budgets in Poland and Romania.
Supply Chain Analysis
Strait of Hormuz transit underwrites semiconductor supply security for sensor-to-cloud architectures, though Dutch and German medtech corridors maintain captive production of monitoring device assemblies. Component sourcing draws from Taiwan for microcontrollers, South Korea for display modules, and Germany for precision sensor substrates. Single-source vulnerability concentrates in EHR integration modules where Epic Systems dominates French and Nordic hospital procurement. Distribution runs through hospital procurement committees in capitated contracts and pharmacy channel convergence in Spain and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European chronic disease management enters cyclical recovery as MDR regulatory clarity accelerates CE marking velocity for validated algorithms, releasing pent-up platform deployment demand across integrated care networks.
For Market Incumbents: Consolidate regulatory affairs capacity through acquisition of notified body relationships, addressing certification queue bottlenecks that delay competitor market entry. Deepen backward integration into sensor manufacturing to capture margin compression from semiconductor supply constraints. Defend against standalone telehealth developers by embedding outcome guarantees in German Gesundes Kinzigtum contract renewals.
For New Entrants and Emerging Players: Differentiate on GDPR-compliant hosting infrastructure as cross-border data localization fragments incumbent platform economics. Target Polish and Romanian ambulatory networks where EU cohesion fund modernization creates first-mover windows for remote patient monitoring deployment. Pursue pharmacy channel partnerships in Spain and Italy as community pharmacies expand chronic care coaching services.
For Investors and Strategic Acquirers: EU AI Act high-risk system classification reshapes the acquisition landscape toward clinical AI transparency compliance as a preferred procurement gating factor. Long-term viability centers on vendors with prospective clinical study infrastructure for algorithmic diagnostic validation. Target mid-sized telehealth developers with dedicated MDR technical documentation capacity. Monitor notified body capacity expansion in Berlin-Brandenburg health clusters as inflection signal for certification velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance accelerates market access for algorithm-based diagnostic tools in Dutch hospital networks. |
| Hospital System Partnership | German integrated care contracts bundle remote monitoring hardware with outcome guarantees that transfer admission risk. |
| Software Companion Development | GDPR-compliant mobile interfaces capture patient-facing expansion as pharmacy channels mature in Spain and Italy. |
| Reimbursement Strategy | Belgian and Dutch ambulatory reimbursement extensions narrow the home healthcare spend gap against hospital-based delivery. |
| Regulatory Capability Acquisition | Notified body relationship purchases compress certification timelines for cardiac monitoring platforms targeting atrial fibrillation detection. |
Research Methodology
Desk research of EMA guidance documents, EU MDR technical specifications, and hospital procurement databases preceded structured interviews with biomedical engineers, GPO contracts managers, and clinicians across German, Dutch, and French healthcare systems. Primary fieldwork with telehealth developers and notified body representatives validated secondary data on certification timelines and software classification pathways. Bottom-up sizing of monitoring device installations and top-down reconciliation against national health expenditure reports anchored value estimates.
Variance decomposition across product type, delivery mode, end user, and condition type segmentation dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from installed base growth rates and reimbursement expansion trajectories modeled continuous glucose monitoring miniaturization adoption curves and telehealth solution penetration in underpenetrated Eastern European markets.
The analysis sits within stated boundaries; outcomes outside MDR enforcement consistency and GDPR cross-border data flow agreements would require recalibration. Forecasts reflect assumptions on notified body capacity expansion and ambulatory reimbursement policy continuity. Practitioners should keep alternative scenarios live as EU AI Act implementation timelines and cohesion fund disbursement velocities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Otoplasty Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market