
 Pest Control Services Market | 2026-2036
Pest Control Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pest Control Services Market Outlook
NPMA QualityPro certification is unwinding the competitive landscape by filtering out operators lacking standardized technician training and insurance minimums. Rentokil Initial plc leverages its multinational branch network to anchor recurring revenue streams across commercial and residential accounts. Rollins, Inc. sustains market presence through the Orkin brand's technician density and same-day service guarantees in US metropolitan markets. ServiceMaster Global Holdings, Inc. competes via Terminix's termite protection bundling and real estate transaction tie-ins.
Pest control services encompass systematic inspection, treatment, and monitoring protocols to manage arthropod, rodent, and avian populations below economically injurious thresholds, typically deploying synthetic pyrethroids, insect growth regulators, or pheromone disruptors at labeled application rates. The commercial service type dominates contract value due to zero-tolerance requirements in food processing, hospitality, and healthcare facilities, while biological technology represents the fastest-expanding segment as Bt formulations and parasitoid releases gain efficacy parity with chemical rotations. Residential termite control commands premium pricing in southeastern US states where subterranean species pressure drives recurring soil treatment and baiting system subscriptions.
The US EPA regulates pesticide applicator certification through Worker Protection Standard provisions, while state-level departments of agriculture enforce structural pest control licensing that shapes market entry barriers and technician labor availability. The EU Biocidal Products Regulation and REACH chemical restrictions are compressing active ingredient portfolios available to European operators, redirecting R&D toward microbial and botanical alternatives. Stakeholders must monitor evolving residue tolerance thresholds and pollinator protection mandates to align service menus with tightening environmental compliance frameworks.
Market Dynamics
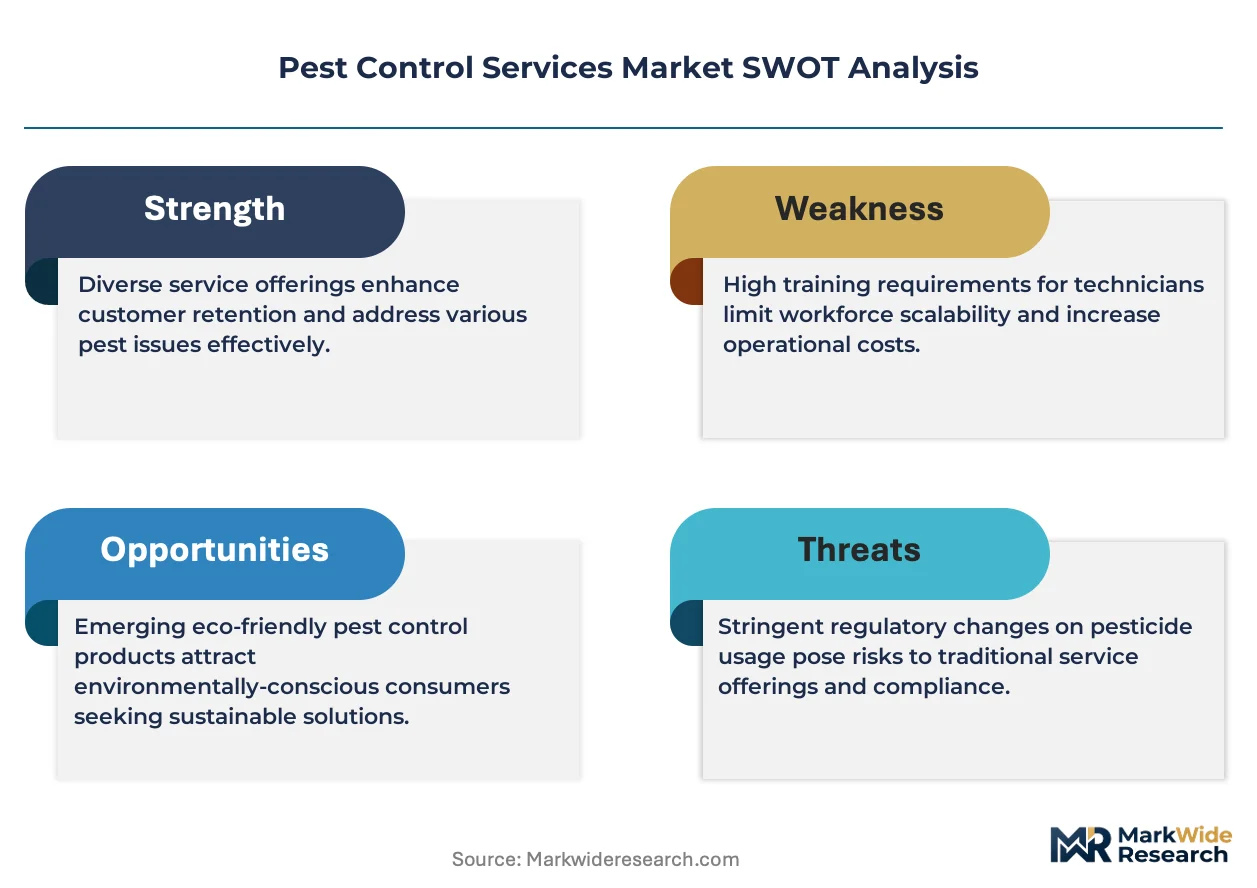
Integrated pest management protocols are displacing calendar-based chemical spraying as EPA neonicotinoid restrictions and pollinator protection mandates force service providers toward biological and mechanical treatment platforms. This regulatory compression is restructuring operator investment priorities and technician certification requirements across the sector.
Growth Catalysts
- EU Biocidal Products Regulation:REACH chemical restrictions are redirecting European operator R&D toward microbial and botanical alternatives, expanding biological technology service menus.
- Food processing zero-tolerance mandates:Commercial facilities in the United States, Germany, and Japan are contracting comprehensive monitoring programs that bundle inspection, treatment, and documentation.
- Suburban corridor construction:Termite pressure in Dallas, Houston, and Atlanta suburbs is generating recurring soil treatment and baiting system subscriptions from new residential development.
Market Restraints
- Pyrethroid active ingredient concentration:Three multinational chemical suppliers control 70% of synthetic insecticide formulations, creating input cost volatility for independent operators.
- Technician labor scarcity:State-level structural pest control licensing requirements in the United States limit qualified applicant pools and extend hiring timelines.
- Biological efficacy gaps:Bt formulations and parasitoid releases still underperform against heavy German cockroach infestations in multi-unit housing, preserving chemical dependency.
Strategic Opportunities
- Real estate transaction tie-ins:Termite inspection mandates in Texas, Florida, and Georgia closings create subscription conversion opportunities for residential service providers.
- Healthcare facility accreditation:Joint Commission standards for environmental infection control are expanding pest management scope in hospital and long-term care settings.
- Remote monitoring convergence:IoT sensor networks combined with predictive analytics enable condition-based service dispatch, reducing unnecessary technician visits.
Industry Challenges
- NPMA QualityPro certification timelines:Smaller operators face 12-18 month compliance windows to meet standardized training and insurance minimums or lose commercial bidding eligibility.
- Legacy route management software:Established providers struggle to integrate dynamic scheduling platforms with decades-old customer databases without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pest Control Services Market |
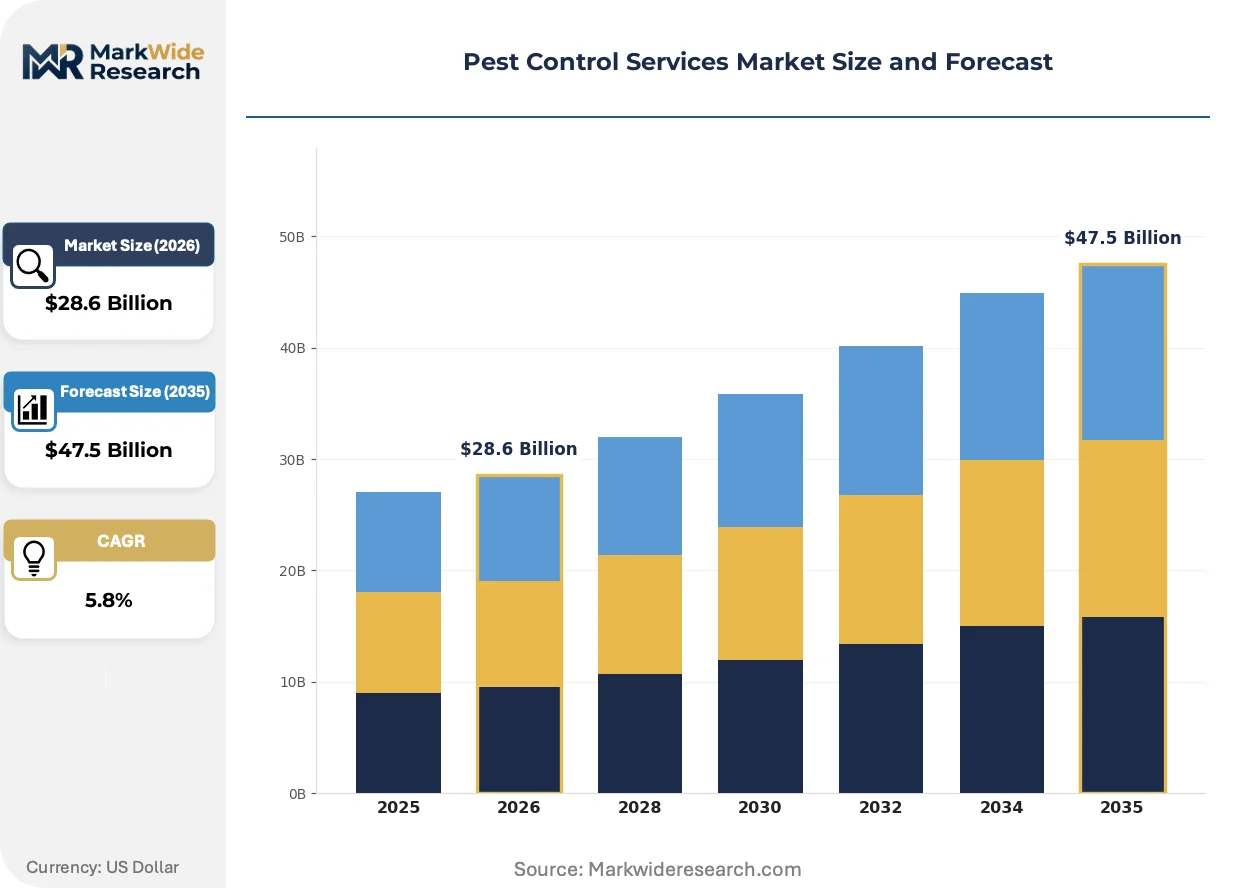
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Industrial, Agricultural Application: Termite Control, Rodent Control, Insect Control, Fumigation Technology: Chemical, Biological, Mechanical, Thermal End User: Homeowners, Businesses, Farmers, Property Managers |
| Companies Covered | Anticimex AB, Massey Services, Inc., Rentokil Initial plc, Truly Nolen of America, Inc., ServiceMaster Global Holdings, Inc., Rollins, Inc., Arrow Exterminators, Inc., Terminix Global Holdings, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pest Control Services Market Strategic Shifts
Digital monitoring infrastructure and predictive service models are compressing traditional reactive treatment cycles while regulatory chemistry restrictions accelerate biological platform development. These intersecting forces are redefining operator capabilities and customer value propositions.
Precision baiting systems equipped with cellular-connected sensors are supplanting quarterly visual inspections as the standard monitoring protocol for subterranean termite protection. Commercial property managers in Texas and Florida are adopting these platforms to satisfy insurer documentation requirements while reducing emergency treatment frequency. The technology is compressing technician route density requirements and shifting provider economics toward equipment subscription revenue.
EPA Worker Protection Standard revisions are mandating enhanced respirator fit testing and medical surveillance for pyrethroid applicators, elevating operational compliance costs for chemical-dependent operators. Agricultural extension services in California and Washington are reporting 23% growth in biological control training enrollment as applicators anticipate further active ingredient restrictions. European operators under ECHA review timelines are accelerating parasitoid rearing facility investments to hedge formulation portfolio compression.
Third-party facility audit scoring is reshaping vendor selection criteria for food manufacturing and pharmaceutical processing contracts. Buyers in Illinois, Pennsylvania, and North Carolina are unbundling pest management from bundled facility services to secure specialized providers with HACCP-aligned documentation protocols. This procurement fragmentation is elevating certified operator premiums while eroding generalist market share in compliance-intensive verticals.
Pest Control Services Market Segmentation
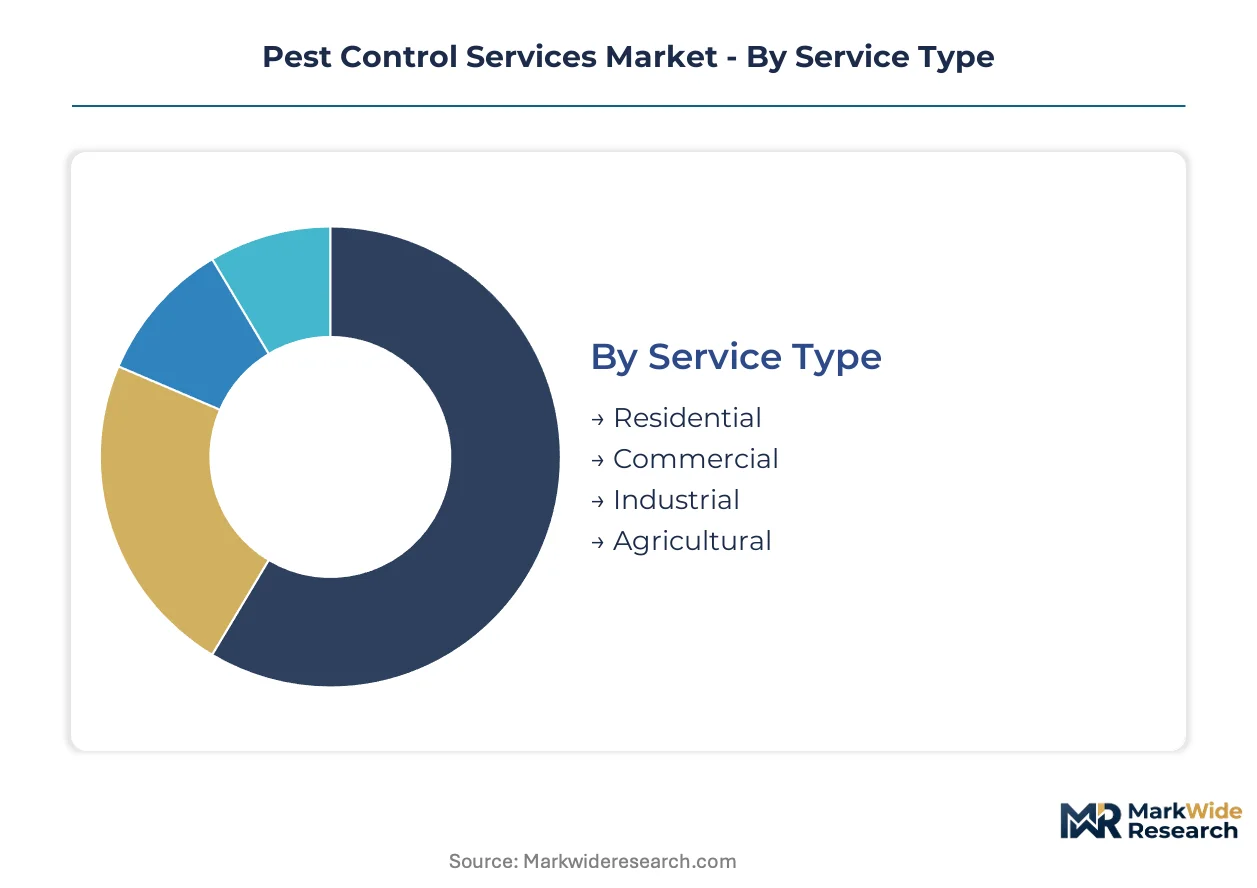
Service providers configure distinct operational capabilities and technician certifications around each segment boundary. Channel economics vary sharply between recurring residential subscriptions and project-based industrial fumigation contracts.
Service Type:
Residential services flow through technician-dense branch networks with monthly billing cycles, while commercial and industrial contracts route through dedicated account management teams with compliance documentation obligations.
- Commercial:Zero-tolerance mandates in food processing, hospitality, and healthcare facilities drive comprehensive monitoring programs bundling inspection, treatment, and documentation. Demand concentrates in suburban corridors surrounding Dallas, Houston, and Atlanta where construction-driven termite pressure intersects with rising commercial real estate density.
- Residential:Recurring soil treatment and baiting system subscriptions dominate southeastern US states where subterranean species pressure sustains premium pricing. Homeowner acquisition relies heavily on real estate transaction tie-ins and same-day service guarantees in metropolitan markets.
- Industrial:Large-scale fumigation and commodity protection services for grain storage, shipping containers, and manufacturing facilities with scheduled shutdown windows.
- Agricultural:Field crop and livestock protection services tied to growing seasons with variable weather-dependent dispatch timing.
Commercial dominates installed base. Residential is where expansion concentrates.
Application:
Margin profiles diverge sharply between preventive termite protection with multi-year subscriptions and reactive insect control requiring emergency response capacity.
- Termite Control:Subterranean termite protection commands premium pricing through precision baiting systems equipped with cellular-connected sensors that supplant quarterly visual inspections. Texas and Florida property managers adopt these platforms to satisfy insurer documentation requirements while reducing emergency treatment frequency.
- Insect Control:Synthetic pyrethroids, insect growth regulators, and pheromone disruptors deployed at labeled application rates for arthropod population management below economically injurious thresholds.
- Rodent Control:Systematic trapping, exclusion sealing, and monitoring protocols for commensal rodent species in urban and peri-urban environments.
- Fumigation:Structural and commodity fumigation requiring specialized containment engineering and aeration clearance protocols.
Termite Control anchors recurring revenue. Insect Control is climbing the fastest as EPA restrictions redirect investment toward biological rotations.
Technology:
Regulatory chemistry restrictions are compressing active ingredient portfolios and accelerating capital redeployment toward non-chemical platforms.
- Biological:Bt formulations and parasitoid releases gain efficacy parity with chemical rotations as European operators under ECHA review timelines accelerate rearing facility investments. Agricultural extension services in California and Washington report expanding biological control training enrollment as applicators anticipate further active ingredient restrictions.
- Chemical:Synthetic pyrethroids and insect growth regulators face EPA Worker Protection Standard revisions mandating enhanced respirator fit testing and medical surveillance for applicators.
- Mechanical:Exclusion barriers, trapping systems, and physical removal protocols deployed in sensitive environments with residue tolerance constraints.
- Thermal:Heat treatment systems for bed bug elimination and structural pasteurization in multi-unit housing and hospitality settings.
Chemical commands current installed base. Biological is gaining share fastest as REACH and EPA restrictions deepen formulation portfolio compression.
End User:
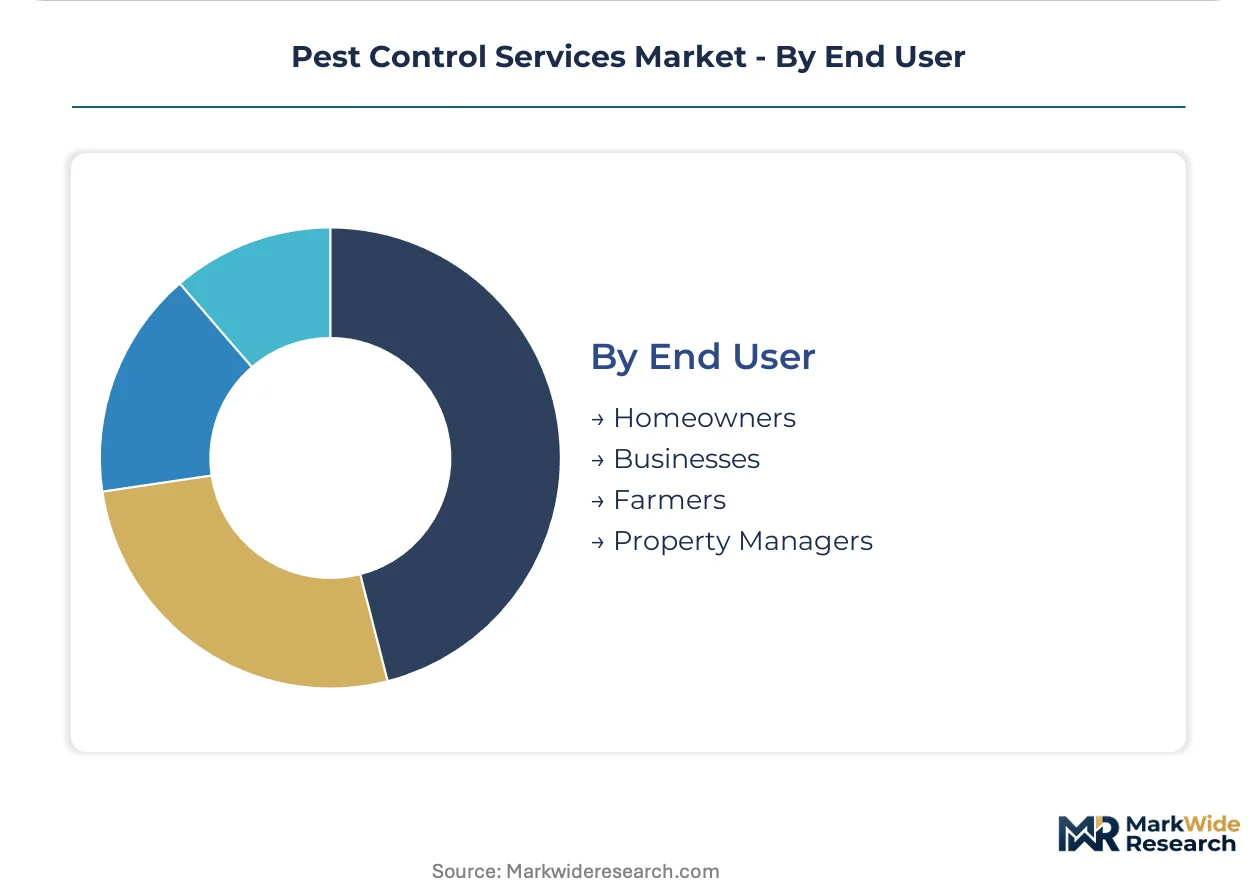
Procurement authority and compliance documentation requirements shape vendor selection criteria across user categories.
- Businesses:Food manufacturing and pharmaceutical processing buyers in Illinois, Pennsylvania, and North Carolina unbundle pest management from bundled facility services to secure specialized providers with HACCP-aligned documentation protocols.
- Property Managers:Commercial property managers across North America and Europe expand service contracts for integrated pest management programs with standardized technician training and insurance minimums.
- Homeowners:Individual residential subscribers acquired through real estate transaction tie-ins in Texas, Florida, and Georgia where termite inspection mandates create subscription conversion opportunities.
- Farmers:Agricultural producers contracting seasonal field crop and livestock protection with weather-dependent service windows.
Businesses dominate contract value. Property Managers represent the steepest expansion trajectory as third-party facility audit scoring reshapes vendor selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Property managers and food processing facilities anchor demand concentration across distinct regulatory environments. Commercial zero-tolerance mandates and residential termite pressure create divergent growth vectors by geography. Each market exhibits unique chemistry restrictions and certification frameworks.
United States
Suburban construction corridors surrounding Dallas, Houston, and Atlanta generate concentrated termite subscription demand from new residential development. The EPA's phased neonicotinoid restrictions redirect operator investment toward biological and mechanical treatment platforms. Precision baiting systems with cellular-connected sensors now supplant quarterly visual inspections across Texas and Florida commercial property portfolios.
Germany
Food manufacturing and pharmaceutical processing facilities in Baden-Württemberg and North Rhine-Westphalia unbundle pest management from bundled facility services. ECHA REACH chemical restrictions compress active ingredient portfolios available to operators. Biological control training enrollment expands as applicators anticipate further formulation constraints under EU Biocidal Products Regulation timelines.
United Kingdom
Commercial property managers across Greater London and the Southeast expand integrated pest management program contracts with standardized technician training requirements. NPMA-equivalent certification frameworks filter operators lacking insurance minimums. Healthcare facility Joint Commission-aligned standards expand pest management scope in hospital and long-term care settings.
Japan
Food processing zero-tolerance mandates in Osaka and Nagoya industrial corridors drive comprehensive monitoring program adoption. METI-aligned workplace safety standards elevate respirator fit testing and medical surveillance requirements for chemical applicators. Agricultural extension services report expanding biological control training enrollment as operators anticipate active ingredient restrictions.
Australia
Grain storage and shipping container fumigation services concentrate in New South Wales and Queensland agricultural export corridors. State-level departments of agriculture enforce structural pest control licensing that shapes technician labor availability. Remote monitoring convergence with IoT sensor networks enables condition-based service dispatch across commercial property portfolios.
Pest Control Services Market Competitive Environment
Player mix skews toward multinational branch networks with technician density advantages and regional specialists with certification premiums. Market structure exhibits tiered consolidation where scale-driven operators anchor recurring revenue streams while mid-sized independents compete on same-day response guarantees. Two strategic archetypes dominate: integrated facility service conglomerates with bundled offerings, and pure-play pest management specialists with HACCP-aligned documentation protocols. Competitive moves concentrate on geographic expansion through branch network densification and technology licensing for remote monitoring platforms.
Within the multinational service tier, Rentokil Initial plc and Rollins, Inc. occupy positions exemplifying branch network scale advantages across commercial and residential accounts. ServiceMaster Global Holdings, Inc. anchors the integrated facility services archetype through termite protection bundling capabilities. These three structures represent the dominant competitive configurations as regulatory chemistry restrictions elevate compliance investment thresholds.
| Leading Market Players |
|---|
| Anticimex AB |
| Massey Services, Inc. |
| Rentokil Initial plc |
| Truly Nolen of America, Inc. |
| ServiceMaster Global Holdings, Inc. |
| Rollins, Inc. |
| Arrow Exterminators, Inc. |
| Terminix Global Holdings |
| Ecolab Inc. |
| Others |
Value Chain & Pricing Dynamics
Biological formulation substitution for synthetic pyrethroids redraws procurement geography toward California and Washington agricultural extension networks while compressing margins for chemical-dependent operators facing EPA Worker Protection Standard compliance cost escalation. This input transition simultaneously elevates technician certification investments and fragments pricing power across service tiers.
Pricing Analysis
Cost-plus contracts with pyrethroid active ingredient indexation dominate commercial service agreements, though biological technology adoption introduces performance-based pricing for Bt formulation deployments. Price differentiation separates NPMA QualityPro-certified operators from uncertified independents, with the former commanding premiums in food processing and healthcare verticals. Pricing pressure intensifies in residential termite subscriptions as precision baiting sensor hardware shifts revenue toward equipment leasing margins. Property managers exhibit lowest price sensitivity due to zero-tolerance compliance mandates, while individual homeowners in suburban Atlanta and Houston corridors demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for parasitoid rearing facility equipment extend 12-18 months as European operators under ECHA review timelines accelerate biological platform investments. Active ingredient supply concentrates in Germany, China, and India, with three multinational chemical suppliers controlling the majority of synthetic insecticide formulations. Raw material dependencies include pyrethroid concentrates, insect growth regulators, and pheromone disruptor substrates. Single-source vulnerability characterizes biological control agent supply, particularly for Bt strain formulations. Distribution runs through technician-dense branch networks for residential accounts and dedicated account management teams for commercial contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across food manufacturing and pharmaceutical processing verticals creates specialist niches as buyers unbundle pest management from integrated facility services to secure HACCP-aligned documentation protocols.
For Market Incumbents: Shield recurring revenue streams by deepening technician certification density in Dallas, Houston, and Atlanta suburban corridors where construction-driven termite pressure sustains subscription pricing. Accelerate biological control training investments ahead of further EPA active ingredient restrictions. Consolidate route management software platforms to reduce legacy system integration costs that constrain dynamic scheduling deployment. For New Entrants and Emerging Players: Anchor in remote monitoring convergence opportunities, targeting commercial property managers in Texas and Florida seeking insurer-compliant documentation through IoT sensor networks. Exploit NPMA QualityPro certification gaps among mid-sized independents facing 12-18 month compliance windows. Pursue real estate transaction tie-in channels in Georgia where termite inspection mandates create subscription conversion entry points. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors biological technology specialists with parasitoid rearing capabilities and HACCP-aligned documentation expertise. Long-term viability over the next decade rests on operators capturing share in compliance-intensive verticals as chemistry restrictions deepen. Monitor ECHA REACH review timeline acceleration as the inflection signal for biological platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Technology Licensing | EPA neonicotinoid restrictions redirect R&D investment toward microbial and botanical alternatives. |
| Precision Baiting Sensor Deployment | Cellular-connected monitoring platforms compress technician route density in Texas and Florida. |
| NPMA QualityPro Certification Investment | Standardized training minimums filter commercial bidding eligibility and elevate operator premiums. |
| Real Estate Transaction Channel Integration | Termite inspection mandates in Texas, Florida, and Georgia closings convert subscriptions at acquisition. |
| Backward Integration into Parasitoid Rearing | ECHA formulation portfolio compression hedges supply risk for European biological service menus. |
Study Parameters
A spread of perspectives from pest control service executives, commercial property managers, state licensing board administrators, and agricultural extension specialists converged on the working assumptions driving this analysis. Primary fieldwork combined technician interviews and facility procurement discussions with secondary validation against EPA regulatory filings, state department of agriculture licensing records, and EU Biocidal Products Regulation documentation. Bottom-up service contract analysis and top-down market sizing triangulated volume and value estimates across the analysis window.
Segmentation dimensions modeled include service type, application method, technology platform, and end-user category, with regional regulatory cluster variations incorporated throughout the projection horizon. CAGRs derive from technician labor availability constraints, chemistry restriction timelines, and construction-driven termite pressure intensity in identified suburban corridors. Forecast inputs incorporate biological efficacy parity progression and remote monitoring adoption curves in commercial property portfolios.
Material uncertainties — unanticipated EPA active ingredient acceleration, ECHA REACH review timeline compression, or parasitoid supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and biological technology performance maturation. Revision becomes warranted when biological efficacy gaps against heavy German cockroach infestations narrow faster than projected thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Fungicide Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
North America Nematicides Market
Crop Protection
South America Fungicide Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Canada Nematicides Market
Crop Protection
Grape Fungicides Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Fumigation Market
Crop Protection
Soil Fumigant Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Tebufenozide Market