
 Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market | 2026-2036
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market Foresight
Modular dosing configurations for granulocyte colony-stimulating factors is shifting how oncology centers procure neutropenia prophylaxis, moving from single-agent vials toward bundled cycle-support kits that simplify inventory management. Amgen Inc. anchors the reference biologic segment with decades of clinical validation and entrenched hospital formularies. Sandoz competes aggressively in the biosimilars space, leveraging European regulatory familiarity to accelerate market access. Coherus BioSciences specializes in pegfilgrastim alternatives, positioning its portfolio for payer-driven substitution mandates.
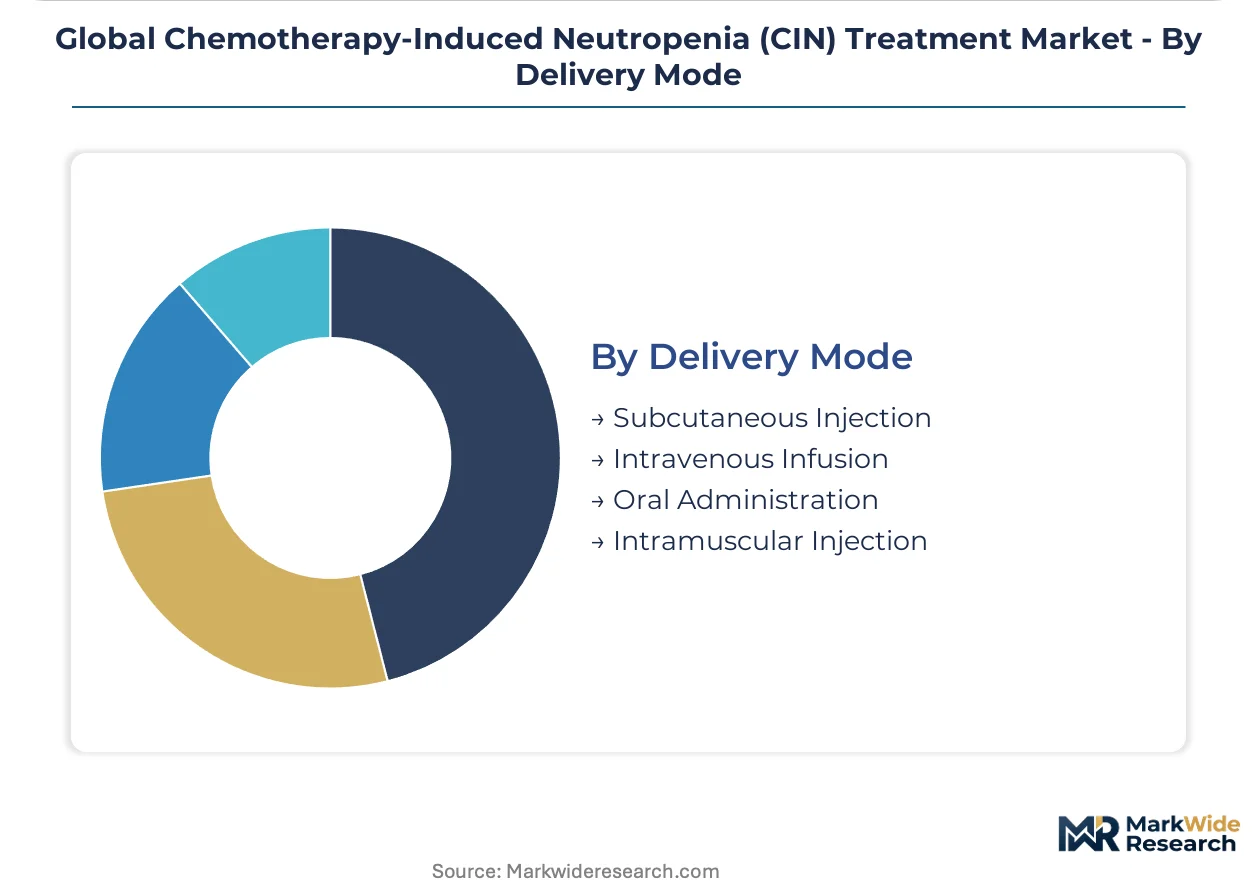
Chemotherapy-induced neutropenia treatment encompasses pharmacologic interventions that restore or preserve absolute neutrophil count thresholds in patients receiving myelosuppressive cancer regimens, primarily through recombinant human granulocyte colony-stimulating factor proteins manufactured via E. coli or CHO cell expression systems with polyethylene glycol conjugation to extend circulating half-life. The primary commercial purpose is preventing febrile neutropenia hospitalizations and enabling full-dose chemotherapy delivery per protocol. Granulocyte colony-stimulating factors command the dominant value share as the established standard of care across solid tumor and hematologic malignancy indications. Biosimilars represent the fastest-expanding segment as regulatory parity demonstrations and interchangeability designations unlock automatic substitution at the pharmacy level. Subcutaneous injection maintains volume leadership for delivery mode due to on-body injector innovations that permit outpatient administration without infusion center visits.
FDA biosimilar guidance and EMA scientific advice frameworks shape development costs and commercial timelines for new entrants, while WHO prequalification pathways influence procurement decisions in lower-income health systems. The EU AI Act and FDA's evolving digital health oversight will increasingly govern algorithm-driven neutropenia risk prediction tools that guide prophylaxis decisions. Stakeholders must monitor evolving interchangeability standards and real-world evidence requirements that determine whether biosimilars capture hospital contract tiers or remain restricted to naïve-patient starts.
Market Dynamics
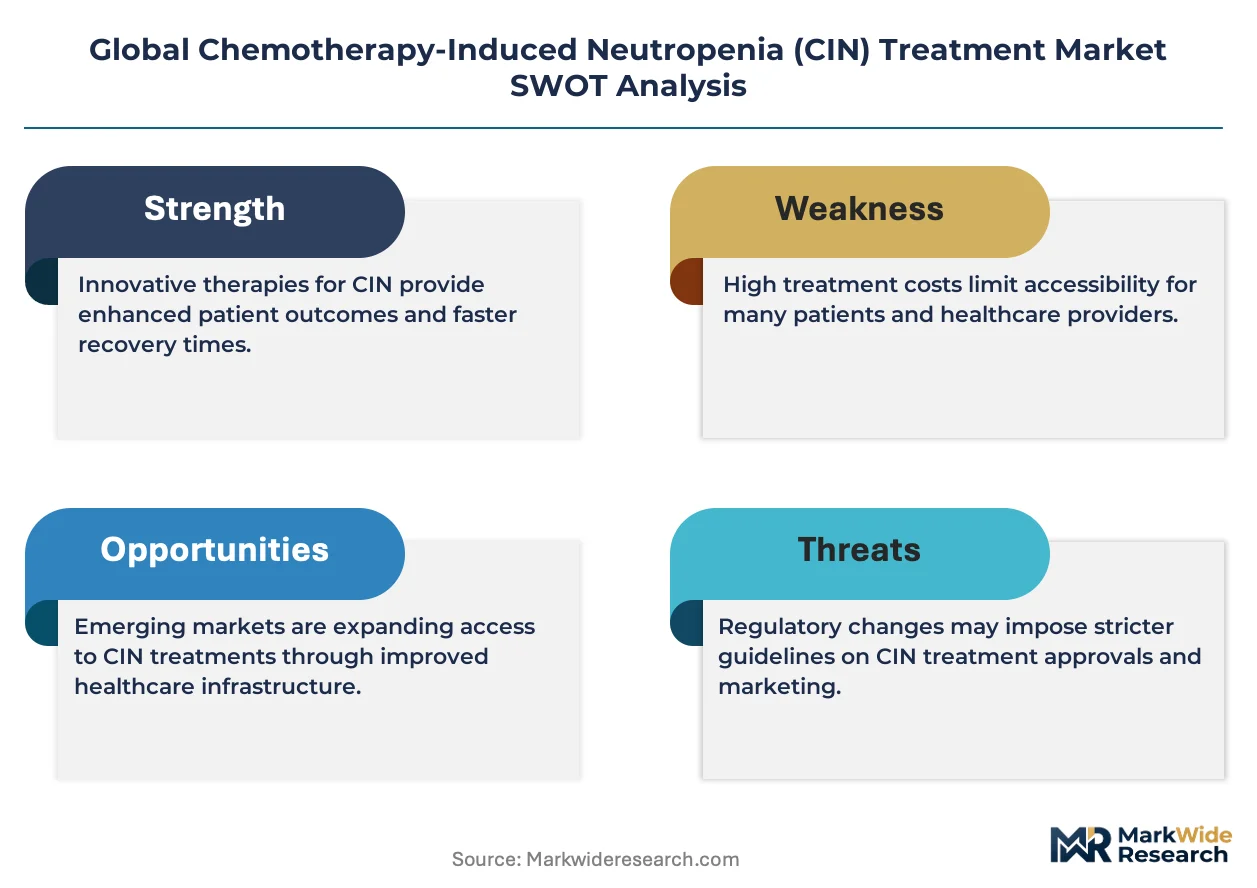
The FDA's biosimilar interchangeability pathway is compressing reference biologic pricing power while oncology centers consolidate purchasing through integrated delivery networks, fundamentally restructuring how G-CSF prophylaxis is procured and administered across hospital systems.
Growth Catalysts
- Intensified chemotherapy protocols:Dose-dense regimens for breast and lung malignancies are expanding the addressable patient pool for prophylactic colony-stimulating factor support across academic medical centers.
- EMA biosimilar scientific advice frameworks:Streamlined development guidance accelerates European market entry for pegfilgrastim alternatives, compressing regulatory timelines for second-wave competitors.
- On-body injector platforms:Wearable delivery systems eliminate infusion center dependency, extending prophylaxis access to community oncology practices with limited nursing capacity.
Market Restraints
- Reference biologic supply concentration:Legacy manufacturing capacity for filgrastim and pegfilgrastim active pharmaceutical ingredients concentrates among contract biologics organizations in Switzerland and Singapore, creating single-source vulnerability.
- Interchangeability designation friction:FDA's state-by-state pharmacy substitution rules create formulary access fragmentation that delays automatic biosimilar uptake despite regulatory approval.
- Recombinant protein production costs:CHO cell culture and polyethylene glycol conjugation chemistry require capital-intensive bioreactor infrastructure that elevates minimum viable scale for new entrants.
Strategic Opportunities
- China's hospital-based infusion expansion:Tier-2 and tier-3 city oncology centers are building myelosuppressive chemotherapy capacity without established G-CSF formularies, creating first-mover positioning for biosimilar suppliers.
- WHO prequalification procurement pathways:Prequalification status unlocks pooled purchasing for lower-income health systems in sub-Saharan Africa and Southeast Asia currently reliant on originator donation programs.
- Algorithm-driven risk stratification:Machine learning tools predicting febrile neutropenia probability are converging with electronic health record workflows to identify under-prophylaxed high-risk patients.
Industry Challenges
- Immunogenicity surveillance infrastructure:Post-market pharmacovigilance for biosimilar neutralizing antibody detection requires specialized bioanalytical capabilities that contract research organizations struggle to staff at scale.
- Cold chain integrity for on-body devices:Temperature-controlled distribution of pre-filled wearable injectors demands last-mile logistics investment that exceeds traditional vial shipping requirements.
- Formulary committee composition delays:Pharmacy and therapeutics review cycles at integrated delivery networks average six to nine months, compressing commercial launch windows before contract renewal periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market |
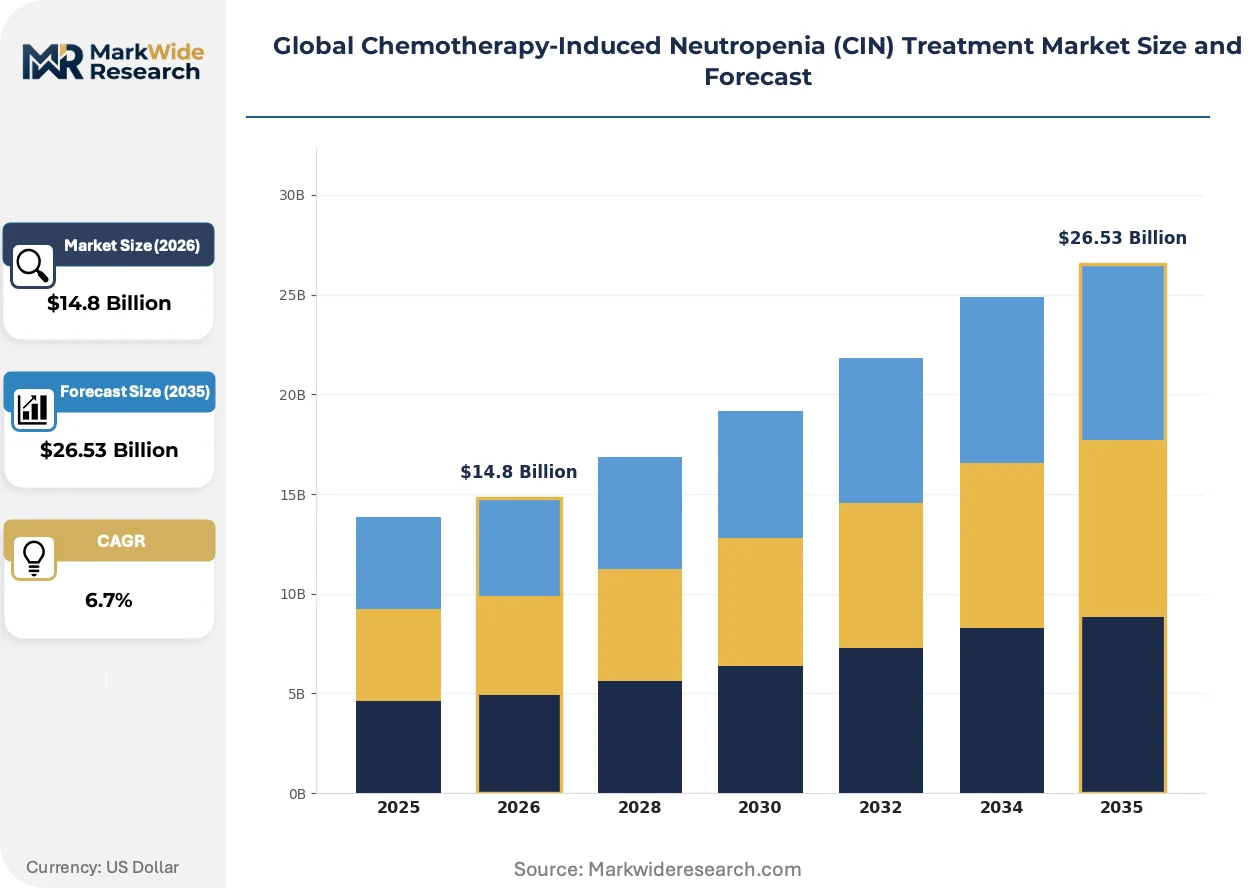
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulocyte Colony-Stimulating Factors, Biosimilars, Antibiotics, Immunomodulators, Recombinant Proteins Therapy Area: Solid Tumors, Hematologic Malignancies, Lymphoma, Leukemia, Multiple Myeloma End User: Oncology Centers, Specialty Clinics, Diagnostic Laboratories, Research Institutes, Ambulatory Care Facilities Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Intramuscular Injection |
| Companies Covered | Amgen Inc., Sandoz, Coherus BioSciences, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Viatris Inc., Biocon Biologics Inc., G1 Therapeutics Inc., Evive Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market Shifts & Advancements
Neutropenia prophylaxis is fragmenting from standardized single-agent administration toward personalized cycle-support architectures, with technology and procurement models evolving in parallel to enable more precise risk-adjusted intervention.
On-body injector systems for pegfilgrastim delivery are modularizing how outpatient chemotherapy support is organized. These wearable devices automate subcutaneous dosing 24-27 hours post-chemotherapy, eliminating the need for next-day clinic returns. Community oncology practices with constrained nursing staff are adopting the technology fastest, compressing hospital infusion center volumes while shifting site-of-care economics toward the physician office setting.
The EU AI Act's risk classification framework for clinical decision support software is reshaping algorithmic neutropenia prediction tools. Systems generating patient-specific febrile neutropenia probability scores now face conformity assessment requirements that elevate documentation burdens for developers. European oncology software vendors are responding by restructuring quality management systems to meet Class IIa medical device standards, while US developers await FDA digital health guidance convergence.
Hospital purchasing cooperatives are consolidating G-CSF procurement through multi-year sole-source agreements that bundle reference and biosimilar products under single distribution contracts. This behavior is displacing open formulary competition at individual facility level. The shift is most visible in United States integrated delivery networks where pharmacy benefit managers exert centralized control over oncology drug spend across dozens of affiliated sites.
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market Segmentation
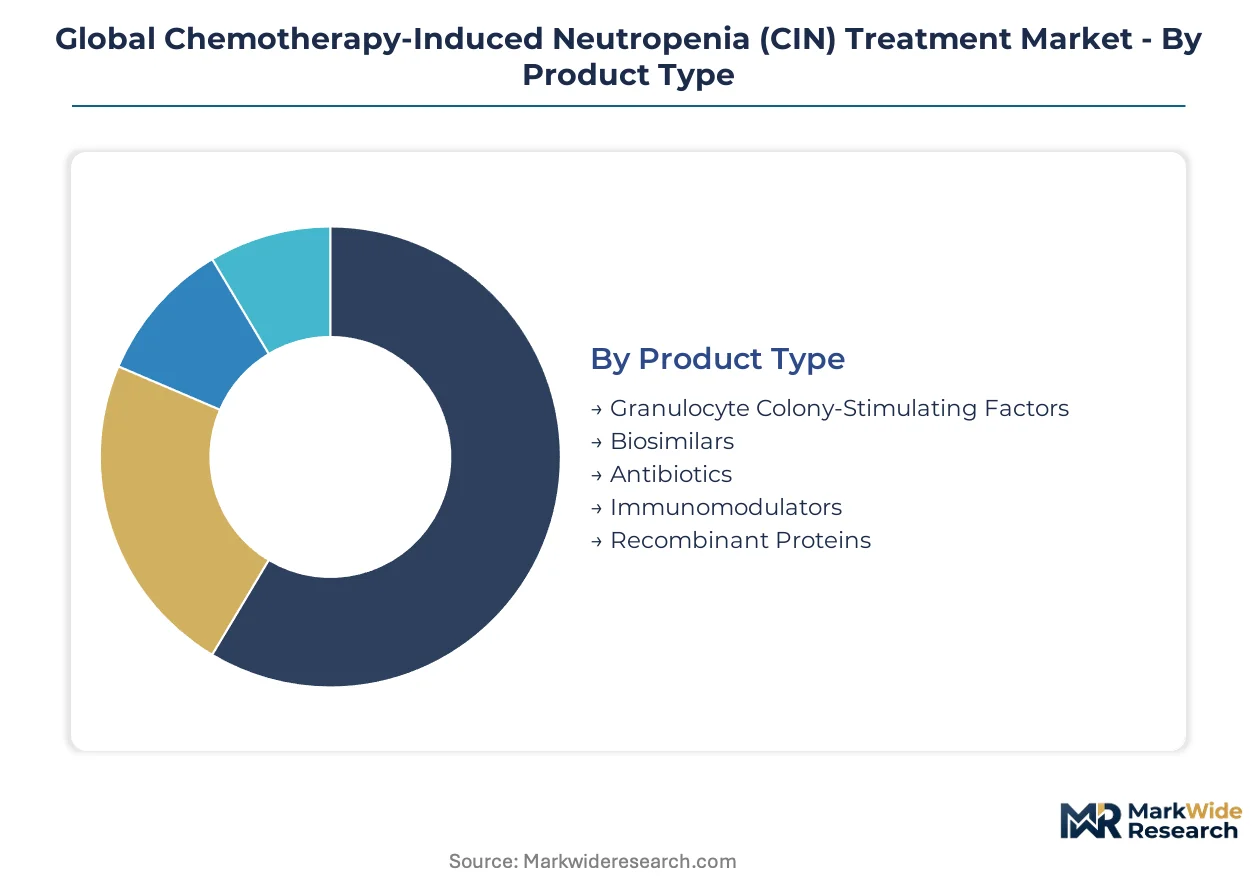
Granulocyte colony-stimulating factor procurement varies sharply by segment, with FDA interchangeability designations and EMA scientific advice frameworks creating divergent certification burdens across product categories. Hospital formularies segment their purchasing strategies accordingly, prioritizing segments with established reimbursement pathways over experimental modalities.
Product Type:
EMA biosimilar scientific advice and FDA interchangeability pathways impose distinct regulatory burdens across product categories, with polyethylene glycol conjugation chemistry and CHO cell expression systems requiring specialized manufacturing inspections that shape competitive entry timelines.
- Granulocyte Colony-Stimulating Factors:Recombinant human proteins manufactured via E. coli or CHO cell systems with PEGylation to extend circulating half-life. Demand concentrates in United States academic medical centers where dose-dense breast and lung cancer protocols require prophylactic neutrophil support, constrained by reference biologic pricing power erosion from biosimilar entry.
- Biosimilars:Follow-on biologics demonstrating analytical and clinical similarity to reference pegfilgrastim or filgrastim through abbreviated FDA 351(k) pathways. European oncology centers in Germany and France are expanding formulary access fastest as EMA marketing authorizations accumulate, though state-by-state US pharmacy substitution rules fragment automatic uptake.
- Antibiotics:Prophylactic antibacterial agents for febrile neutropenia management, typically fluoroquinolone or cephalosporin classes.
- Immunomodulators:Agents modifying neutrophil production kinetics through alternative hematopoietic pathways.
- Recombinant Proteins:Non-G-CSF growth factors and cytokine therapies with neutropenia mitigation properties.
Leading the category by volume: Granulocyte Colony-Stimulating Factors. Growing fastest: Biosimilars.
Therapy Area:
Myelosuppressive intensity varies substantially across malignancy types, with chemotherapy regimen aggressiveness determining prophylaxis thresholds and G-CSF dosing frequency.
- Solid Tumors:Breast, lung, and colorectal carcinomas treated with dose-dense or dose-intensified protocols generating predictable neutropenia risk windows. China's tier-2 city oncology centers are building capacity fastest for these indications as hospital-based infusion networks expand.
- Hematologic Malignancies:Aggressive leukemias and lymphomas requiring sustained neutrophil recovery between induction cycles. United States integrated delivery networks concentrate purchasing for this segment through bundled cycle-support contracts that span diagnosis-specific patient pathways.
- Lymphoma:Hodgkin and non-Hodgkin subtypes with R-CHOP and similar combination regimens.
- Leukemia:Acute myeloid and lymphoblastic variants with prolonged aplastic phases.
- Multiple Myeloma:Plasma cell dyscrasias treated with immunomodulatory drug combinations.
Volume leadership sits with Solid Tumors. Steepest expansion trajectory: Hematologic Malignancies.
End User:
Site-of-care economics and nursing capacity constraints segment demand across facility types, with reimbursement differentials favoring outpatient administration where on-body injector platforms permit.
- Oncology Centers:Hospital-affiliated infusion units and standalone cancer centers administering myelosuppressive chemotherapy. Germany's university hospital networks and Japan's designated cancer care hospitals anchor procurement volume for reference biologics.
- Specialty Clinics:Community-based hematology-oncology practices with limited nursing staff. United States physician office settings are adopting wearable injector technology fastest to eliminate next-day clinic returns.
- Diagnostic Laboratories:Facilities performing absolute neutrophil count monitoring and febrile neutropenia biomarker assessment.
- Research Institutes:Academic centers conducting clinical trials with novel prophylaxis protocols.
- Ambulatory Care Facilities:Same-day surgery and infusion centers with limited overnight capability.
Oncology Centers dominate procurement volume. Specialty Clinics are climbing the fastest.
Delivery Mode:
Patient convenience and cold chain logistics segment administration preferences, with wearable technology investments shifting economics toward subcutaneous routes.
- Subcutaneous Injection:Preferred route for pegfilgrastim and biosimilar administration via prefilled syringes or on-body injector systems. Singapore's biomedical manufacturing clusters supply wearable device components, while Switzerland hosts contract biologics organizations producing active pharmaceutical ingredients for this delivery mode.
- Intravenous Infusion:Reserved for hospitalized febrile neutropenia episodes or patients unable to tolerate subcutaneous administration. China's expanding tier-3 hospital infrastructure is building IV capacity without established G-CSF formularies.
- Oral Administration:Limited to antibiotic prophylaxis and supportive care agents.
- Intramuscular Injection:Alternative parenteral route for specific clinical scenarios.
Subcutaneous Injection leads by volume. Intravenous Infusion is gaining share fastest in emerging hospital infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production clusters in Switzerland and Singapore while consumption concentrates in United States oncology centers and China's expanding hospital networks. This geographic split shapes regulatory compliance burdens and cold chain logistics investments across the value chain.
United States
Oncology centers in academic medical centers and integrated delivery networks drive G-CSF procurement volume as dose-dense breast and lung cancer protocols expand. FDA interchangeability designations and state-level pharmacy substitution rules create formulary access fragmentation that delays automatic biosimilar uptake. The Greater Boston biotech corridor hosts contract research organizations specializing in immunogenicity surveillance for post-market pharmacovigilance.
China
Tier-2 and tier-3 city oncology centers are building myelosuppressive chemotherapy capacity without established G-CSF formularies, creating first-mover positioning for biosimilar suppliers. NMPA marketing authorization pathways and hospital procurement reforms under centralized volume-based purchasing reshape competitive entry timelines. Yangtze River Delta manufacturing clusters supply recombinant protein production infrastructure for domestic and export markets.
Germany
University hospital networks anchor European procurement volume for reference biologics as EMA biosimilar scientific advice frameworks accelerate formulary access. Germany's national pharmaceutical reimbursement system and hospital procurement cooperatives consolidate purchasing power across state-level hospital associations. The Rhine-Main biopharma corridor hosts contract biologics organizations specializing in CHO cell culture and polyethylene glycol conjugation chemistry.
Japan
Designated cancer care hospitals concentrate demand for prophylactic colony-stimulating factor support as aging demographics expand the addressable patient pool. PMDA regulatory pathways and national health insurance reimbursement listings determine commercial timelines for new entrants. The Kanto region's pharmaceutical manufacturing base supplies prefilled syringe and on-body injector device components for regional distribution.
Switzerland
Contract biologics organizations concentrate legacy manufacturing capacity for filgrastim and pegfilgrastim active pharmaceutical ingredients, creating single-source vulnerability for global supply. Swissmedic regulatory oversight and European Medicines Agency centralized marketing authorizations govern export compliance for reference biologic production. Basel's biopharma cluster hosts specialized bioreactor infrastructure for recombinant protein manufacturing.
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market Competitive Landscape
The competitive structure tilts toward reference biologic incumbents with entrenched hospital formularies and biosimilar specialists leveraging regulatory parity demonstrations. Market concentration remains moderate as FDA interchangeability pathways compress pricing power without consolidating share among top-tier players. Two strategic archetypes dominate: legacy biopharmaceutical manufacturers with decades of clinical validation and focused biosimilar developers exploiting abbreviated approval pathways. Competitive moves center on hospital contract tier positioning and on-body injector platform differentiation rather than manufacturing capacity expansion.
Within the reference biologic tier, Amgen Inc. anchors entrenched formulary relationships across United States academic medical centers. Sandoz and Coherus BioSciences exemplify biosimilar specialists competing through European regulatory familiarity and payer-driven substitution mandates respectively. These three entities represent the spectrum from legacy clinical validation to regulatory agility that defines current competitive positioning.
| Leading Market Players |
|---|
| Amgen Inc. |
| Sandoz |
| Coherus BioSciences |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Viatris Inc. |
| Biocon Biologics Inc. |
| G1 Therapeutics Inc. |
| Evive Biotech |
| Others |
Supply & Pricing Matrix
United States integrated delivery networks and hospital purchasing cooperatives command pricing leverage through multi-year sole-source agreements that bundle reference and biosimilar G-CSF products, compressing margins for manufacturers while rewarding volume scale.
Pricing Analysis
Price erosion across reference biologics traces to FDA interchangeability designations that unlock automatic pharmacy substitution, forcing originator manufacturers into defensive contract rebidding. Three-tier pricing structure across originator, interchangeable biosimilar, and non-interchangeable biosimilar levels segments hospital formularies by substitution eligibility. Cost-down pressure on pegfilgrastim alternatives accelerates because European EMA scientific advice frameworks accelerate competitor entry timelines. Community oncology practices exhibit highest price sensitivity due to constrained reimbursement rates, while academic medical centers prioritize clinical validation over acquisition cost.
Supply Chain Analysis
Dual-sourcing mandates from hospital purchasing cooperatives require contract biologics organizations to qualify secondary manufacturing sites for filgrastim and pegfilgrastim active pharmaceutical ingredients. Supply concentrates in Switzerland and Singapore for CHO cell culture and polyethylene glycol conjugation chemistry, with Yangtze River Delta clusters expanding recombinant protein capacity for domestic Chinese consumption. Cold chain integrity for on-body injector platforms rests on temperature-controlled distribution infrastructure that exceeds traditional vial logistics. Single-source vulnerability persists for legacy API production. Distribution runs through specialized pharmaceutical wholesalers with biologics handling certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into CHO cell culture capacity and captive polyethylene glycol conjugation chemistry represents the decisive competitive lever as pricing power erodes and supply security becomes a differentiator.
For Market Incumbents: Hedge reference biologic revenue erosion by securing interchangeable designation for biosimilar portfolio extensions and locking multi-year hospital system contracts before formulary renewal cycles. Prioritize on-body injector platform differentiation to defend site-of-care economics against infusion center competitors. Invest in immunogenicity surveillance infrastructure to maintain pharmacovigilance credibility. For New Entrants and Emerging Players: Begin with China's tier-2 and tier-3 city oncology centers where G-CSF formularies remain unestablished and centralized volume-based purchasing creates rapid access pathways. Target hematologic malignancy indications where bundled cycle-support contracts span diagnosis-specific patient pathways. Pursue WHO prequalification status to unlock pooled procurement in sub-Saharan Africa and Southeast Asia. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract biologics organizations with validated CHO cell culture infrastructure in Switzerland or Singapore amid pricing compression. Long-term viability hinges on manufacturing scale rather than brand equity in this commoditizing biologic segment. Watch FDA interchangeability designation velocity as the inflection signal for automatic substitution penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeability Designation Pursuit | FDA interchangeability unlocks automatic pharmacy substitution and accelerates hospital formulary access. |
| On-Body Injector Platform Development | Wearable delivery systems shift site-of-care economics toward outpatient settings and reduce nursing dependency. |
| CHO Cell Culture Capacity Expansion | Captive bioreactor infrastructure insulates against single-source API vulnerability and secures supply continuity. |
| WHO Prequalification Pathway | Prequalification status enables pooled procurement access across lower-income health systems in Africa and Asia. |
| Algorithmic Risk Stratification Integration | EU AI Act compliance for Class IIa medical device standards positions predictive tools for EHR workflow adoption. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists underwrites the qualitative findings on formulary dynamics and substitution patterns. Secondary validation draws from FDA 351(k) biosimilar filings, EMA scientific advice documentation, ClinicalTrials.gov protocol registries, and hospital GPO contract databases. Bottom-up patient-flow modeling triangulates against top-down manufacturer revenue disclosures to anchor volume estimates.
Comparable-period anchoring to historical biosimilar launch trajectories in oncology supportive care establishes the forecast framework's baseline substitution velocity assumptions. Segmentation dimensions span product type, therapy area, end user facility class, and delivery mode across the projection horizon. CAGRs derive from regression-adjusted uptake curves incorporating regulatory approval timelines and interchangeability designation status. Forecast inputs include myelosuppressive chemotherapy protocol expansion rates and on-body injector adoption curves by practice setting.
Underlying measurement precision varies by segment; biosimilar volume projections carry tighter precision than novel immunomodulator estimates due to established approval pathway visibility. Forecasts reflect assumptions regarding FDA interchangeability designation velocity and EMA scientific advice throughput. Deviation in China's centralized volume-based purchasing implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market