
 Gonorrhea Therapeutics Market | 2026-2036
Gonorrhea Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Gonorrhea Therapeutics Market Outlook
The gap between premium novel antibiotics and commodity generic cephalosporins is repositioning procurement economics in hospital formularies. Pfizer Inc. leverages its manufacturing scale to sustain supply chain reliability for established injectable therapies across North American and European distribution channels. Entasis Therapeutics differentiates through targeted R&D intensity in novel bacterial topoisomerase inhibitors, while GlaxoSmithKline plc anchors its competitive stance through geographic dominance in emerging market access programs.
Gonorrhea therapeutics comprise antimicrobial agents, vaccine candidates, diagnostic platforms, and adjunct antiseptics designed to eliminate Neisseria gonorrhoeae infection or prevent its transmission, with injectable extended-spectrum cephalosporins remaining the first-line clinical standard due to their pharmacokinetic profile against urogenital and extragenital sites. Antibiotics command the largest revenue pool within product type segmentation as resistance surveillance drives demand for reserve agents, while combination therapy approaches are gaining structural share as monotherapy failure rates climb in high-prevalence clinical settings. Injectable delivery mode maintains institutional preference for severe or complicated cases, though oral formulations occupy expanding ambulatory care channels where adherence logistics favor outpatient management.
The FDA's Qualified Infectious Disease Product designation and EMA's PRIME pathway are accelerating development timelines for novel mechanism antibacterials, while the WHO Global Gonococcal Antimicrobial Surveillance Programme shapes resistance tracking standards that directly inform national treatment guideline revisions. The CDC's STI Treatment Guidelines and the European Centre for Disease Prevention and Control framework collectively constrain empirical prescribing options, forcing manufacturers to align clinical trial endpoints with evolving breakpoint criteria. Stakeholders must monitor resistance surveillance data streams and regulatory exclusivity thresholds to time portfolio investments against the narrowing window of existing therapeutic efficacy.
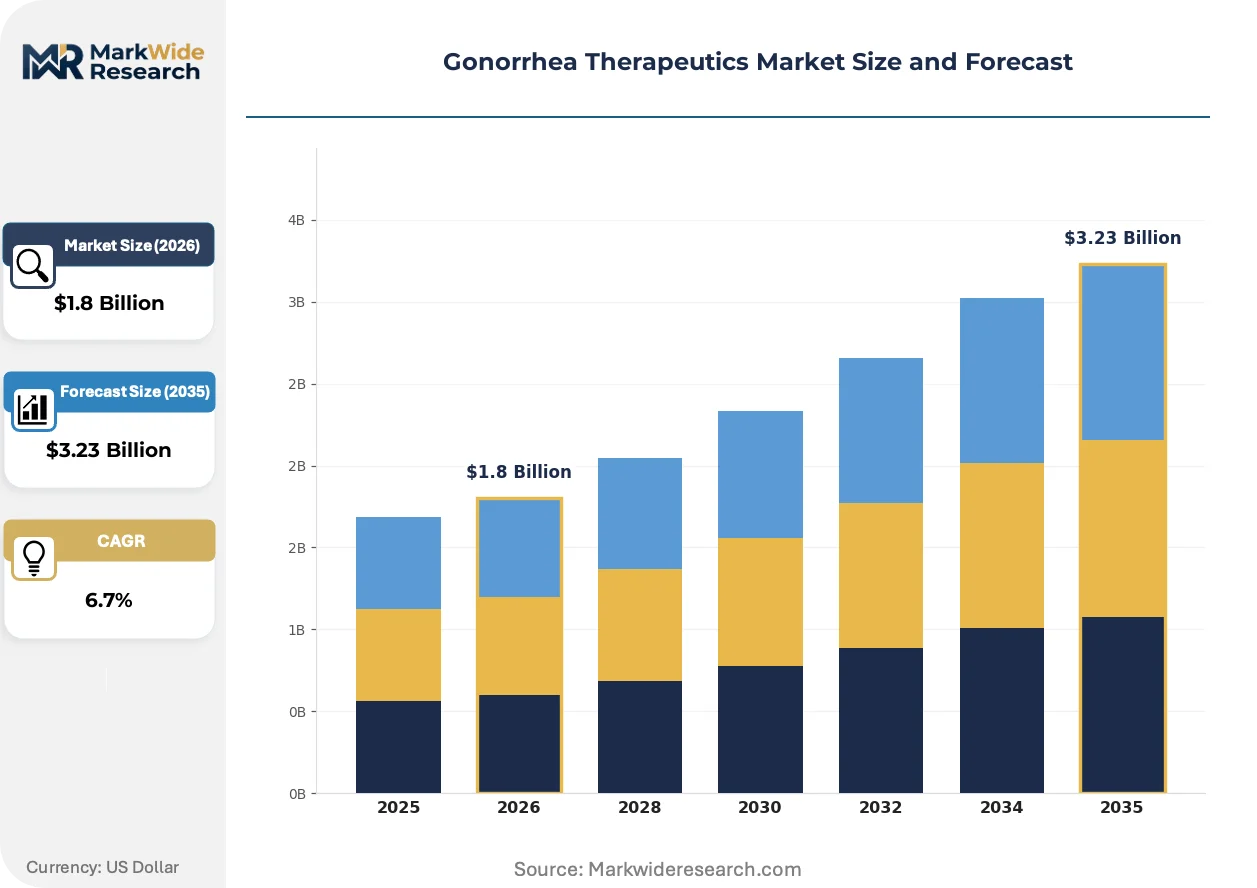
Market Dynamics
Cephalosporin resistance surveillance is compressing the effective lifespan of frontline antibiotics, forcing health systems to accelerate formulary transitions toward reserve agents and combination protocols.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:This pathway accelerates novel antibacterial development timelines by granting priority review and extended market exclusivity for gonorrhea therapeutics targeting resistant strains.
- WHO Global Gonococcal Antimicrobial Surveillance Programme:Standardized resistance tracking across 80 countries enables evidence-based guideline revisions that drive demand for updated therapeutic options in high-burden settings.
- Point-of-care nucleic acid amplification testing:Diagnostic sensitivity improvements in urban STI clinics are expanding same-day test-and-treat protocols, compressing time-to-therapy initiation.
Market Restraints
- API supply concentration in Asian manufacturing clusters:Active pharmaceutical ingredient production for extended-spectrum cephalosporins concentrates in China and India, exposing procurement to geopolitical trade friction and quality enforcement variability.
- Clinical trial recruitment complexity:Gonorrhea's asymptomatic presentation in extragenital sites complicates endpoint validation, extending development timelines for novel mechanism candidates.
- Generic injectable price compression:Commodity ceftriaxone vials from multiple suppliers anchor hospital formulary expectations, constraining premium pricing for differentiated reserve agents.
Strategic Opportunities
- Sub-Saharan African public health procurement:Underpenetrated screening infrastructure in Nigeria, Kenya, and South Africa presents volume expansion potential as PEPFAR and Global Fund programs scale STI integration.
- Bacterial topoisomerase inhibitor-vaccine adjuvant pairing:Convergence of novel antibiotic mechanisms with transmission-blocking immunization candidates could reshape prophylaxis-treatment sequencing.
- Telehealth prescription pathways:Post-pandemic regulatory accommodations for asynchronous care in US state Medicaid programs are opening direct-to-patient oral therapy distribution.
Industry Challenges
- Antimicrobial stewardship compliance training:Hospital pharmacy and infectious disease departments require specialized personnel to implement resistance-guided prescribing algorithms, creating talent pipeline constraints.
- Multisite clinical trial coordination:EMA's divergent breakpoint criteria from FDA susceptibility standards force parallel protocol designs, inflating regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gonorrhea Therapeutics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Diagnostics, Antiseptics Delivery Mode: Injectable, Oral, Topical, Intravenous End User: Hospitals, Clinics, Home Care, Laboratories Treatment Approach: Combination Therapy, Monotherapy, Supportive Care, Preventive Care |
| Companies Covered | Merck & Co., Inc., AstraZeneca, Pfizer Inc., TherapyX Inc., Debiopharm International SA, GlaxoSmithKline plc, Innoviva Specialty Therapeutics, Inc., Entasis Therapeutics, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gonorrhea Therapeutics Market Strategic Shifts
Novel bacterial topoisomerase inhibitors and diagnostic-guided therapy selection are compressing the gap between resistance emergence and clinical response, restructuring how health systems manage Neisseria gonorrhoeae treatment protocols.
Next-generation topoisomerase inhibitors with distinct binding kinetics from fluoroquinolones are rewriting the clinical utility window for oral gonorrhea therapy. Academic medical centers in the United States and United Kingdom are prioritizing these candidates for expedited formulary review as ceftriaxone susceptibility thresholds decline. The technology is compressing the historical trade-off between outpatient adherence convenience and resistance coverage breadth.
EMA's PRIME pathway for medicines addressing unmet medical needs is accelerating conditional approval timelines for novel mechanism antibacterials. European national health technology assessment bodies are aligning reimbursement decisions with resistance surveillance data streams, tightening market access for agents without documented local susceptibility. Hospital pharmacies in Germany and France are restructuring procurement contracts around breakpoint currency rather than static formulary listings.
Same-day test-and-treat protocols in US municipal STI clinics are displacing traditional referral-based care pathways. Public health departments in New York, Los Angeles, and Chicago are consolidating diagnostic and therapeutic services into single-visit encounters, compressing loss-to-follow-up rates. This operational shift is elevating oral formulation preference over injectable delivery in ambulatory settings where patient throughput constraints dominate resource allocation.
Gonorrhea Therapeutics Market Segmentation
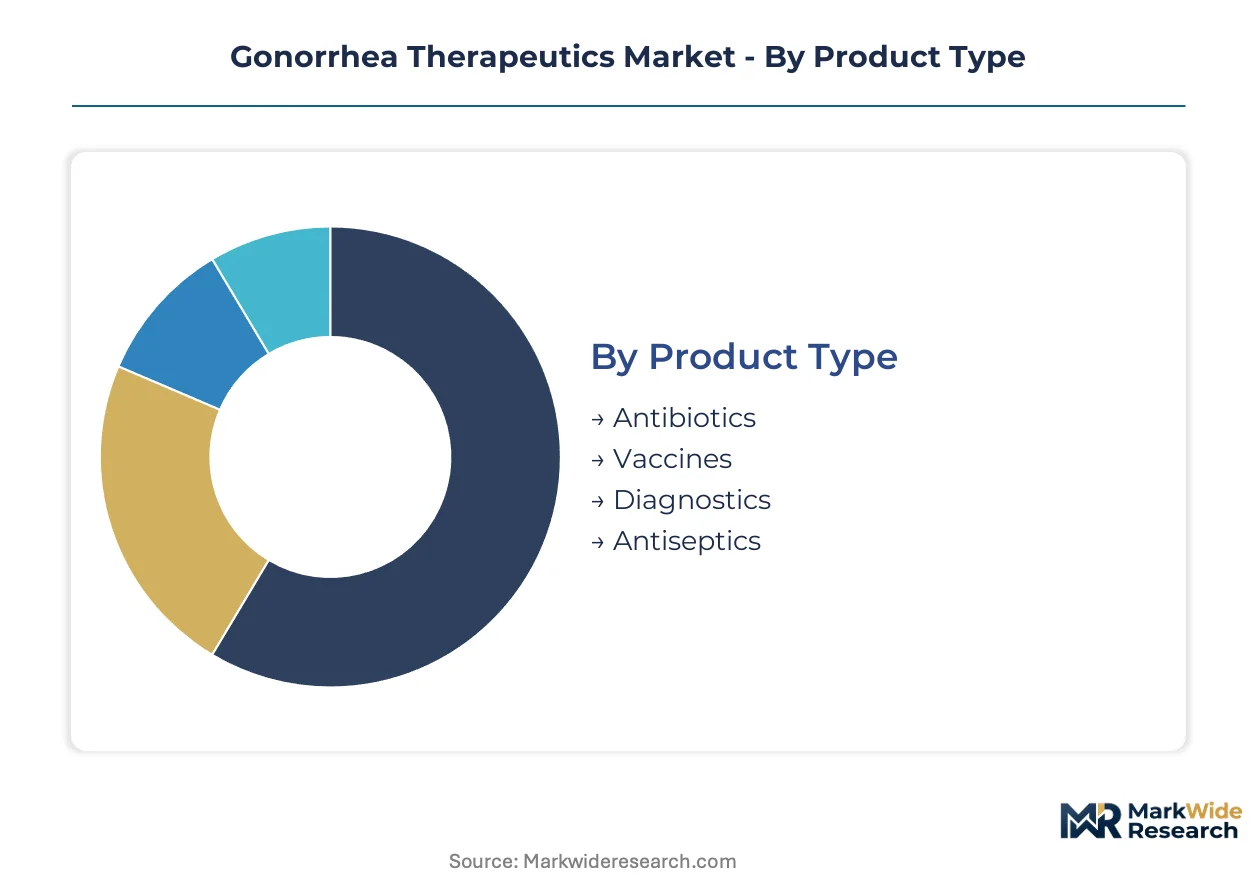
Gonorrhea therapeutics segmentation reflects the tension between established antimicrobial protocols and emerging resistance-driven alternatives. Each axis—product composition, administration route, care setting, and therapeutic strategy—carries distinct procurement economics and regulatory pathway implications.
Product Type:
Antimicrobial mechanism and clinical utility define value capture across this axis, with resistance surveillance directly reshaping portfolio prioritization.
- Antibiotics:Extended-spectrum cephalosporins and novel bacterial topoisomerase inhibitors constitute the revenue core, with hospital formularies in the United States and Germany accelerating procurement of reserve agents as susceptibility breakpoints shift. Injectable ceftriaxone retains institutional preference despite climbing resistance rates in high-prevalence urban clinics.
- Vaccines:Transmission-blocking immunization candidates target extragenital infection reservoirs, with GlaxoSmithKline and academic consortia advancing Phase I/II trials. Development timelines stretch longer than antibacterial pathways, constraining near-term revenue contribution despite substantial unmet prevention need.
- Diagnostics:Nucleic acid amplification platforms enable same-day test-and-treat protocols in municipal STI clinics across New York, Los Angeles, and Chicago.
- Antiseptics:Adjunct topical agents occupy niche prophylaxis applications with limited formulary penetration outside specialized sexual health services.
Mature deployment sits with Antibiotics. Newer deployment is concentrated in Vaccines.
Delivery Mode:
Route of administration shapes adherence logistics, institutional resource allocation, and reimbursement pathway complexity across care settings.
- Injectable:Intramuscular ceftriaxone dominates severe and complicated case management, with hospital pharmacy procurement contracting around supply chain reliability rather than unit cost alone. Extended-spectrum formulations retain preference in extragenital site infections where pharmacokinetic coverage breadth determines clinical outcome.
- Oral:Azithromycin-fluoroquinolone alternatives are reclaiming utility in ambulatory settings where novel topoisomerase inhibitors demonstrate preserved susceptibility, particularly in United Kingdom sexual health clinics piloting resistance-guided prescribing algorithms.
- Topical:Limited to adjuvant antiseptic applications with minimal therapeutic claim substantiation.
- Intravenous:Reserved for disseminated gonococcal infection and inpatient sepsis protocols in tertiary referral centers.
Injectable retains the steepest expansion trajectory in hospital procurement. Oral formulations are gaining share fastest in telehealth-enabled ambulatory channels.
End User:
Care setting determines reimbursement mechanics, prescribing authority constraints, and patient population acuity mix.
- Hospitals:Antimicrobial stewardship programs in United States academic medical centers and German university hospitals constrain empirical prescribing, forcing alignment with real-time resistance surveillance feeds. Formulary transitions toward novel mechanisms accelerate where cephalosporin breakpoint failures exceed institutional thresholds.
- Clinics:Municipal STI services in high-prevalence urban corridors—Atlanta, London, Sydney—pioneer same-day diagnostic-treatment integration, compressing loss-to-follow-up through point-of-care nucleic acid platforms.
- Home Care:Oral therapy distribution through asynchronous telehealth prescriptions expands in US state Medicaid programs with post-pandemic regulatory accommodations.
- Laboratories:Reference testing infrastructure supports resistance surveillance data generation for national treatment guideline revision cycles.
Hospitals anchor procurement volume concentration. Clinics represent the fastest-climbing site of care for test-and-treat operational innovation.
Treatment Approach:
Therapeutic sequencing strategy reflects resistance pressure intensity and clinical presentation complexity.
- Combination Therapy:Dual-agent protocols pairing extended-spectrum cephalosporins with macrolides or novel topoisomerase inhibitors are displacing monotherapy in high-resistance prevalence settings, particularly in United States southeastern states and United Kingdom metropolitan sexual health services where treatment failure surveillance triggers protocol revision.
- Monotherapy:Single-agent ceftriaxone persists in low-resistance prevalence corridors and resource-constrained procurement environments where formulary simplicity outweighs coverage breadth optimization.
- Supportive Care:Symptom management and complication mitigation for pelvic inflammatory disease and disseminated infection sequelae.
- Preventive Care:Partner notification protocols and post-exposure prophylaxis pilot programs in select public health jurisdictions.
Monotherapy retains mature protocol deployment in standard-care pathways. Combination Therapy is concentrating in newer resistance-driven guideline implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors the largest municipal STI screening infrastructure in the United States, with municipal clinics processing over 150,000 gonorrhea tests annually and pioneering same-day nucleic acid amplification protocols that compress time-to-treatment initiation.
United States
CDC-funded screening programs in Atlanta, Chicago, and Los Angeles sustain the highest per-capita testing volumes globally, with public health departments integrating point-of-care diagnostics into single-visit encounters. The FDA's Qualified Infectious Disease Product designation accelerates novel antibacterial reviews, while the CDC's STI Treatment Guidelines constrain empirical prescribing options. Hospital pharmacies in academic medical centers across the Southeast are accelerating formulary transitions toward reserve agents as cephalosporin breakpoint failures exceed institutional thresholds.
Germany
University hospitals in Berlin and Munich anchor resistance surveillance data generation for EMA breakpoint criteria revisions, with antimicrobial stewardship programs tightening formulary controls across the national health system. The EMA's PRIME pathway accelerates conditional approval timelines for novel mechanism antibacterials. Hospital procurement in North Rhine-Westphalia is restructuring contracts around real-time susceptibility data rather than static formulary listings.
United Kingdom
Sexual health clinics in London and Manchester pilot resistance-guided prescribing algorithms for novel topoisomerase inhibitors, reclaiming oral therapy utility in ambulatory settings. The UK Health Security Agency coordinates with the WHO Global Gonococcal Antimicrobial Surveillance Programme to inform national guideline revisions. Academic consortia in Oxford and Cambridge are advancing Phase I/II vaccine trials targeting extragenital infection reservoirs.
India
Active pharmaceutical ingredient production for extended-spectrum cephalosporins concentrates in manufacturing clusters near Hyderabad and Ahmedabad, exposing global procurement to quality enforcement variability. The country's national pharmaceutical regulator aligns with WHO prequalification standards for export-oriented production. Hospital formularies in Maharashtra and Karnataka remain dependent on generic injectable supply chains where price compression constrains premium agent adoption.
Australia
The Kirby Institute in Sydney generates surveillance data that shapes WHO resistance tracking standards across the Western Pacific region. The Therapeutic Goods Administration prioritizes review pathways for antibacterials targeting multidrug-resistant Neisseria gonorrhoeae. Sexual health services in Melbourne and Brisbane are expanding same-day test-and-treat protocols through municipal funding allocations.
Gonorrhea Therapeutics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the gonorrhea therapeutics landscape, with integrated pharmaceutical conglomerates sustaining manufacturing scale advantages while specialized biotechnology firms concentrate R&D intensity on novel mechanisms. The market structure consolidates around three strategic archetypes: diversified multinationals with established injectable supply chains, mid-cap specialists pursuing targeted topoisomerase inhibitor development, and emerging platform companies advancing vaccine adjuvant technologies. Dominant competitive moves include strategic partnerships linking diagnostic and therapeutic capabilities, and geographic expansion into underpenetrated public health procurement corridors.
Within the diversified multinational tier, Pfizer Inc. and Merck & Co., Inc. represent manufacturing scale anchors sustaining supply chain reliability across North American and European distribution channels. Among specialized development-focused entities, Entasis Therapeutics occupies a position exemplifying targeted R&D intensity in novel bacterial topoisomerase inhibitors, while GlaxoSmithKline plc anchors emerging market access programs and transmission-blocking vaccine advancement. These three companies collectively illustrate the competitive spectrum from established antibiotic supply to next-generation mechanism exploration.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca |
| Pfizer Inc. |
| TherapyX Inc. |
| Debiopharm International SA |
| GlaxoSmithKline plc |
| Innoviva Specialty Therapeutics, Inc. |
| Entasis Therapeutics |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Chain & Pricing Dynamics
Hospital pharmacy procurement departments in the United States and Germany anchor demand concentration for gonorrhea therapeutics, forcing manufacturers toward value-based contracting tied to resistance surveillance outcomes rather than traditional unit pricing models.
Pricing Analysis
Outcome-linked reimbursement for novel bacterial topoisomerase inhibitors anchors value-based pricing in hospital formulary negotiations, with procurement contracts tying payment to documented susceptibility preservation. Price differentiation rests on FDA Qualified Infectious Disease Product designation status and EMA PRIME pathway eligibility, which extend exclusivity windows. Cost compression in generic injectable cephalosporins is intensifying because multi-supplier commoditization erodes margin buffers. Municipal STI clinics exhibit highest price sensitivity due to fixed public health budgets, while academic medical centers demonstrate lowest sensitivity where stewardship mandates override cost considerations.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive injectable formulations elevate distribution economics across North American and European hospital networks. Active pharmaceutical ingredient production draws from manufacturing clusters in India and China, with finished dose formulation concentrated in the United States and Germany. Supply chain risk centers on single-source vulnerability for extended-spectrum cephalosporin API where regulatory enforcement variability disrupts batch release timelines. Distribution runs through wholesale pharmaceutical distributors serving hospital group purchasing organizations and direct government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gonorrhea therapeutics occupy a technology-transition phase where novel bacterial topoisomerase inhibitors displace legacy cephalosporin protocols as resistance breakpoints shift.
For Market Incumbents: Acquire late-stage topoisomerase inhibitor assets to offset portfolio exposure to declining ceftriaxone efficacy. Entrench manufacturing scale advantages through backward integration into API production in India to neutralize supply concentration risk. Expand antimicrobial stewardship consulting services to hospital pharmacy departments, deepening account control as formulary decisions tighten.
For New Entrants and Emerging Players: Municipal STI clinics in high-prevalence US urban corridors represent the most penetrable channel for oral formulation pilots. Partner with telehealth platforms serving Medicaid populations to bypass traditional hospital procurement gatekeepers. Target resistance-guided prescribing algorithm pilots in United Kingdom sexual health services as proof-of-concept beachheads.
For Investors and Strategic Acquirers: The window for entry favors development-stage specialists with novel mechanism candidates and regulatory exclusivity runway. Long-term viability hinges on convergence capabilities linking diagnostics to therapeutic selection. Watch EMA-FDA breakpoint divergence as the signal indicating accelerated formulary turnover and premium pricing opportunity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment for novel topoisomerase inhibitors accelerates FDA Qualified Infectious Disease Product designation timelines. |
| Regulatory Approval Pathway | EMA PRIME pathway access compresses conditional approval windows for resistance-targeted antibacterials. |
| Manufacturing Scale-Up | API production expansion in India insulates supply chains against quality enforcement variability. |
| Strategic Partnership | Diagnostic-therapeutic pairings with point-of-care nucleic acid platforms enable same-day test-and-treat protocols. |
| Pipeline Diversification | Transmission-blocking vaccine adjuvant programs address extragenital infection reservoirs beyond antibiotic scope. |
Study Parameters
Document review covered FDA approval databases, EMA regulatory submissions, WHO surveillance reports, and hospital procurement records, complemented by interviews with infectious disease specialists, hospital pharmacy directors, formulary committee members, and public health program administrators. Secondary validation drew from ClinicalTrials.gov entries, CDC STI treatment guidelines, and antimicrobial resistance surveillance publications. Bottom-up demand modeling across patient population segments was triangulated against top-down expenditure flows from national health accounts.
Cross-referencing historical resistance surveillance trends against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product mechanism, administration route, care setting, treatment protocol type, and regional regulatory cluster. CAGRs were derived from iterative convergence of epidemiological burden projections and therapeutic substitution elasticity estimates. Forecast inputs incorporated breakpoint revision schedules from EUCAST and CLSI standards committees.
Several conditions sit outside the modeled scope, including pandemic-related STI screening disruption, geopolitical trade restrictions on API movement, and breakthrough vaccine efficacy results. Forecasts reflect documented assumptions about resistance emergence rates and regulatory exclusivity periods. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Contraceptive Pills Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market