
 Sulfonylureas Market | 2026-2036
Sulfonylureas Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfonylureas Market Analytics
REACH compliance for pharmaceutical impurities is recalibrating manufacturing cost structures across European sulfonylurea supply chains. Sanofi leverages its integrated active pharmaceutical ingredient capabilities to sustain margin control in glimepiride production. Novo Nordisk anchors its position through specialized diabetes care ecosystems that extend beyond molecule supply into patient monitoring services.
Sulfonylureas comprise a class of insulin secretagogue compounds—primarily second-generation agents such as glimepiride, glipizide, and glyburide—that stimulate pancreatic beta-cell insulin release via ATP-sensitive potassium channel closure, with therapeutic dosing typically administered once or twice daily for glycemic control in non-insulin-dependent diabetes mellitus. The application landscape tilts heavily toward combination therapy, where sulfonylureas pair with metformin or SGLT2 inhibitors to address progressive beta-cell dysfunction, while monotherapy demand contracts as treatment guidelines emphasize multi-agent regimens from diagnosis. Among distribution channels, hospital pharmacy procurement dominates volume for newly diagnosed patients, whereas retail pharmacy and online channels capture refill prescriptions as therapy stabilizes.
The FDA's bioequivalence protocols and the EMA's quality guidelines for generic antidiabetic medicines jointly determine which manufacturers gain market access in regulated economies. India's CDSCO enforces local stability testing requirements that filter out import-dependent suppliers lacking domestic analytical infrastructure. Stakeholders must monitor how pharmacovigilance databases track cardiovascular safety signals, since regulatory responses to emerging risk profiles can trigger label restrictions or formulary exclusions with immediate revenue consequences.
Market Dynamics
Combination therapy protocols are compressing monotherapy volumes while hospital procurement consolidation reshapes pricing power across the sulfonylureas value chain. The shift from first-line monotherapy to multi-agent regimens from diagnosis is altering prescriber behavior and reimbursement structures simultaneously.
Growth Catalysts
- CDSCO stability mandates:India's domestic testing requirements filter out import-dependent competitors, creating protected market space for local manufacturers with analytical infrastructure in Hyderabad and Mumbai.
- Progressive beta-cell dysfunction:Extended disease duration in aging populations sustains demand for insulin secretagogues as adjunct therapy alongside metformin and SGLT2 inhibitors.
- REACH compliance recalibration:ECHA impurity thresholds for pharmaceutical manufacturing are forcing supply chain upgrades that favor integrated API producers over pure-formulation players.
Market Restraints
- API concentration risk:Active pharmaceutical ingredient production for glimepiride concentrates among Chinese and Indian intermediates suppliers, exposing finished dose manufacturers to single-source vulnerability.
- Cardiovascular safety surveillance:FDA and EMA pharmacovigilance databases track emerging signals that can trigger label restrictions or formulary exclusions with immediate revenue impact.
- GLP-1 receptor agonist substitution:Semaglutide and tirzepatide are displacing sulfonylureas in treatment algorithms for patients with established cardiovascular disease or weight management needs.
Strategic Opportunities
- Tier-2 and tier-3 Indian outpatient expansion:Cost-sensitive markets in Nagpur, Indore, and Coimbatore remain underpenetrated by branded generics with established bioequivalence documentation.
- Fixed-dose combination innovation:Sulfonylurea-metformin and sulfonylurea-SGLT2 inhibitor co-formulations address adherence barriers in polypharmacy regimens.
- Digital pharmacy integration:Online refill channels capture stable maintenance prescriptions as hospital pharmacy volumes shift toward initial diagnosis and titration.
Industry Challenges
- Bioequivalence study capacity constraints:FDA and EMA protocol requirements for generic antidiabetic agents demand specialized clinical pharmacology units with limited geographic availability.
- Legacy batch record system migration:Electronic batch record implementation for Annex 11 compliance requires capital deployment and validation timelines that compress margin recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfonylureas Market |
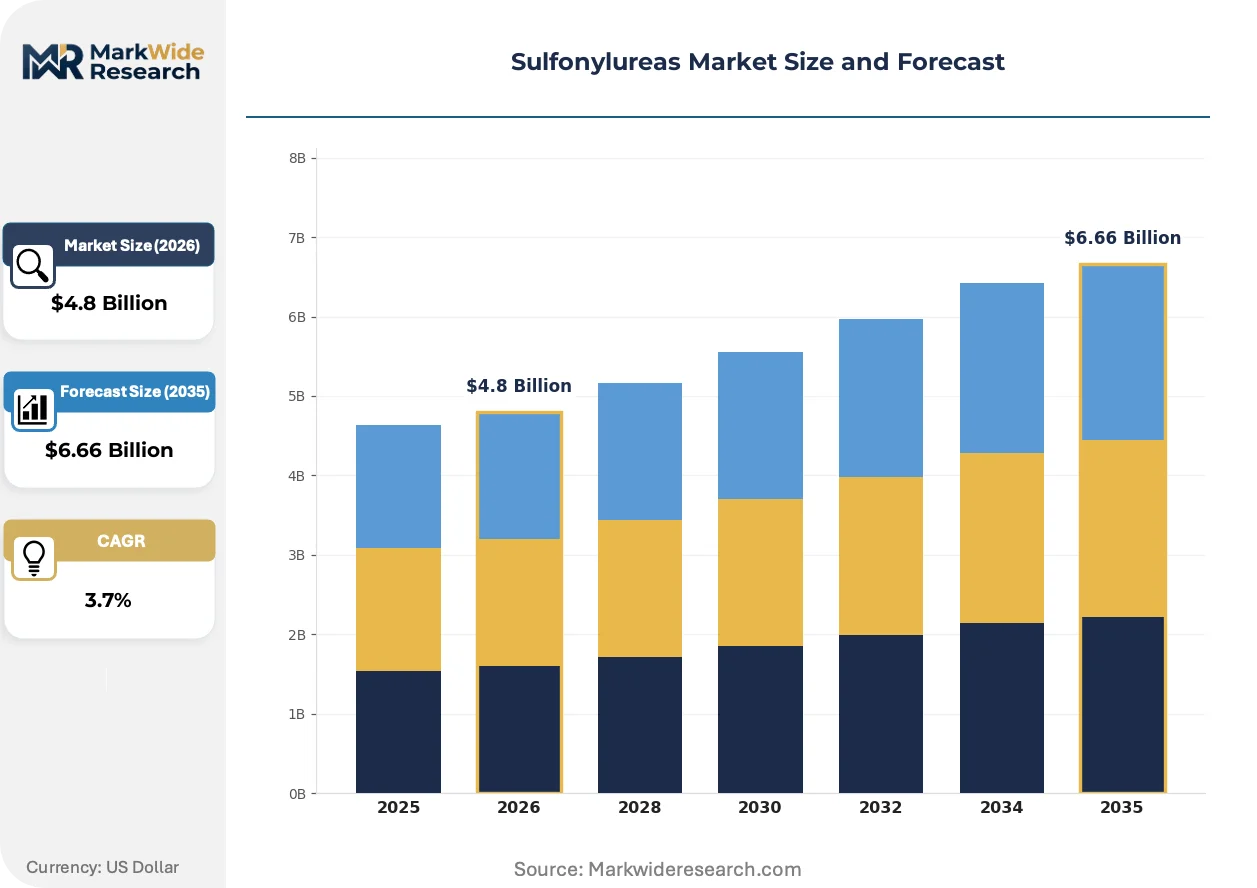
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glimepiride, Glipizide, Glyburide, Others Application: Type 2 Diabetes, Hypoglycemic Treatment, Monotherapy, Combination Therapy End User: Clinics, Hospitals, Homecare, Pharmacies Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers |
| Companies Covered | Lupin, Alembic, Pfizer, Eli Lilly, Boehringer Ingelheim, Sanofi, Mylan, Novo Nordisk, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfonylureas Market Evolving Landscape
Continuous glucose monitoring integration is reshaping how prescribers evaluate sulfonylurea efficacy, moving glycemic control assessment from periodic laboratory values to real-time pattern recognition. This data visibility is altering dosing protocols and combination therapy sequencing across diabetes care pathways.
Modified-release formulation technology is rewriting the competitive landscape for twice-daily agents. Osmotic pump and multiparticulate systems enable glipizide and glyburide administration adherence comparable to once-daily glimepiride. Hospital formularies in Germany and Japan are adopting these platforms for discharge planning where regimen simplification reduces readmission risk. The technology is compressing differentiation between second-generation agents and enabling generic substitution at premium price points.
EMA's revised guideline on quality of medicines for paediatric use is tightening impurity specifications for antidiabetic APIs with pediatric investigation plan obligations. Manufacturers must demonstrate control of nitrosamine and related compounds below tightened thresholds. European supply chains with dedicated pediatric product lines are investing in dedicated manufacturing suites, while commodity API suppliers face exclusion from high-value segments.
Hospital pharmacy consolidation into centralized procurement entities is altering competitive dynamics for newly diagnosed patient volumes. Integrated delivery networks in Texas, Florida, and California are negotiating sole-source agreements for therapeutic classes, displacing traditional prescriber-driven brand selection. Retail and mail-order channels capture stable maintenance volumes, but entry positioning at diagnosis determines longitudinal prescription capture.
Sulfonylureas Market Segmentation
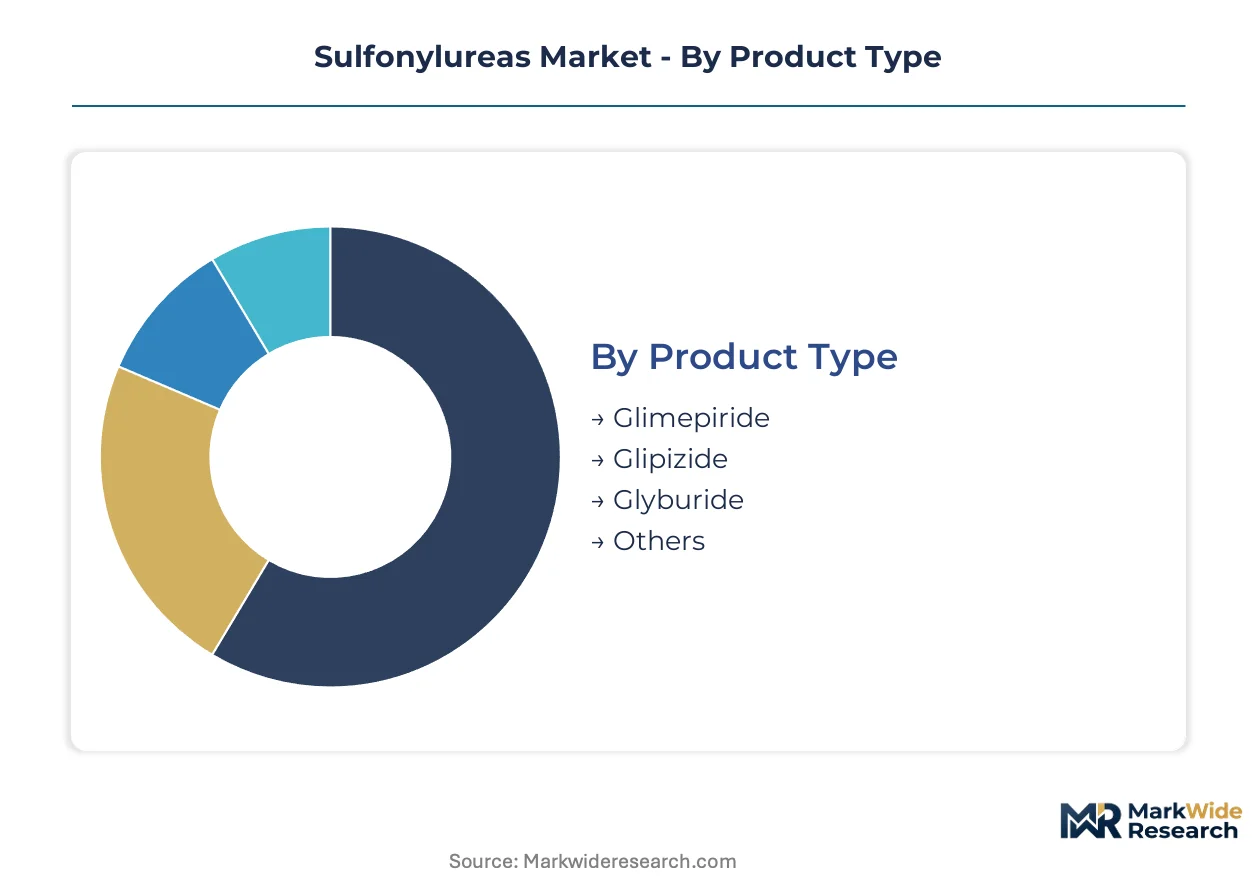
Sulfonylurea market segmentation reveals how formulation chemistry, treatment protocols, and procurement channels create distinct competitive arenas. Each dimension shapes pricing power, regulatory exposure, and manufacturer positioning differently across the value chain.
Product Type:
Standardization dominates second-generation agents, while formulation differentiation creates tiered positioning within each molecule class.
- Glimepiride:Once-daily dosing with lower hypoglycemia risk versus older agents drives preference in combination regimens. Hospital formularies in Germany and Japan favor glimepiride for discharge protocols where adherence simplicity reduces readmission penalties.
- Glipizide:Modified-release osmotic pump formulations enable adherence parity with glimepiride. Demand concentrates in US integrated delivery networks negotiating sole-source agreements for therapeutic classes.
- Glyburide:Compact description with legacy clinical data supporting cost-sensitive procurement in Indian tier-2 and tier-3 outpatient markets.
- Others:Compact description with first-generation tolbutamide and chlorpropamide retaining niche use in specific metabolic phenotypes.
Most installed capacity flows through glimepiride. Expansion is steepest in modified-release glipizide.
Application:
Volume distribution tracks the shift from monotherapy initiation to multi-agent maintenance across disease progression stages.
- Type 2 Diabetes:The core indication encompasses insulin secretagogue use across all disease durations. Prescription capture at diagnosis determines longitudinal therapy adherence in US hospital pharmacy consolidation models.
- Combination Therapy:Pairing with metformin or SGLT2 inhibitors addresses progressive beta-cell dysfunction. European EMA guidelines and US ADA protocols now recommend multi-agent regimens from diagnosis, compressing monotherapy windows.
- Monotherapy:Compact description with declining share as treatment algorithms emphasize early combination approaches.
- Hypoglycemic Treatment:Compact description with acute hypoglycemia management representing off-label rescue use in specific clinical scenarios.
Prescription volumes concentrate in combination therapy. Monotherapy contracts fastest across regulated markets.
End User:
Procurement authority varies sharply across settings, with centralized purchasing in hospitals contrasting decentralized retail decisions.
- Hospitals:Centralized procurement entities in Texas, Florida, and California negotiate sole-source agreements displacing prescriber-driven brand selection. Entry positioning at diagnosis determines longitudinal capture.
- Clinics:Outpatient diabetes centers in Indian cities like Nagpur and Indore drive cost-sensitive demand for bioequivalence-documented branded generics.
- Homecare:Compact description with stable maintenance prescriptions migrating to mail-order and digital pharmacy channels.
- Pharmacies:Compact description with retail and online refill capture as therapy stabilizes post-hospital discharge.
Hospital procurement governs initial prescription decisions. Homecare channels expand most quickly for maintenance volumes.
Distribution Channel:
Channel mix reflects the bifurcation between acute care procurement and chronic disease management logistics.
- Hospital Pharmacy:Dominates volume for newly diagnosed patients requiring titration and combination therapy initiation. Integrated delivery network consolidation in US markets reshapes competitive access.
- Retail Pharmacy:Captures stable refill prescriptions as glycemic control stabilizes. Indian tier-2 and tier-3 city expansion creates protected space for domestic manufacturers with CDSCO-compliant stability testing.
- Online Pharmacy:Compact description with digital refill platforms gaining share in maintenance therapy segments.
- Wholesalers:Compact description with distribution intermediaries facing margin compression from direct hospital contracting.
Hospital pharmacy anchors new patient acquisition. Online channels are gaining share fastest for chronic maintenance prescriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized clinical pharmacologists and bioequivalence study coordinators concentrate in Hyderabad, Mumbai, and Ahmedabad, anchoring India's dominance in generic sulfonylurea development. German chemical engineers and EMA regulatory specialists cluster around Frankfurt and Ludwigshafen, sustaining European formulation leadership. Japanese process chemists in Osaka and Tokyo maintain precision manufacturing standards for modified-release platforms.
United States
Integrated delivery networks in Texas, Florida, and California drive hospital pharmacy procurement consolidation for newly diagnosed type 2 diabetes patients. FDA bioequivalence protocols for generic glimepiride and glipizide filter market access to manufacturers with specialized clinical pharmacology units. Indianapolis and Research Triangle Park host contract research organizations conducting pivotal bioequivalence studies for ANDA submissions.
Germany
Hospital formularies in Bavaria and North Rhine-Westphalia prioritize glimepiride for discharge protocols where adherence simplicity reduces readmission penalties. EMA quality guidelines for generic antidiabetic medicines enforce impurity thresholds that favor integrated API producers. Ludwigshafen and Frankfurt host chemical manufacturing clusters upgrading REACH-compliant pharmaceutical supply chains.
India
CDSCO stability testing mandates filter out import-dependent competitors, creating protected market space for domestic manufacturers with analytical infrastructure. Outpatient diabetes centers in Nagpur, Indore, and Coimbatore drive cost-sensitive demand for bioequivalence-documented branded generics. Hyderabad and Mumbai analytical laboratories conduct mandatory local stability testing for glimepiride and glipizide formulations.
Japan
PMDA quality guidelines for modified-release formulations drive adoption of osmotic pump and multiparticulate glipizide systems in hospital discharge planning. Osaka and Nagoya pharmaceutical clusters specialize in precision coating technologies for twice-daily to once-daily conversion. Tokyo-based integrated delivery networks negotiate sole-source agreements for therapeutic classes in diabetes care pathways.
Sulfonylureas Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the sulfonylureas value chain, producing a tiered structure where API integration depth determines margin control. Large pharmaceutical conglomerates with captive active pharmaceutical ingredient production sustain pricing power against formulation-only competitors. Three archetypes dominate: integrated API-to-formulation conglomerates, regional branded generic specialists with CDSCO-compliant infrastructure, and contract development organizations serving bioequivalence study demand. Competitive moves concentrate on backward integration into intermediate chemical production and strategic partnerships with hospital procurement entities.
Among integrated pharmaceutical conglomerates, Sanofi and Novo Nordisk occupy positions exemplifying divergent strategic anchors. Sanofi represents the API-integrated archetype with captive manufacturing capabilities sustaining margin control in glimepiride production. Novo Nordisk exemplifies the diabetes ecosystem specialist, extending positioning beyond molecule supply into patient monitoring services. Lupin anchors the India-based branded generic tier, occupying a position shaped by CDSCO-compliant stability testing infrastructure and tier-2 city distribution reach.
| Leading Market Players |
|---|
| Lupin |
| Alembic |
| Pfizer |
| Eli Lilly |
| Boehringer Ingelheim |
| Sanofi |
| Mylan |
| Novo Nordisk |
| Merck |
| Others |
Value Network & Pricing Analysis
Captive API production in glimepiride anchors both supply security and margin control for integrated pharmaceutical conglomerates, while outsourced intermediate sourcing exposes pure-formulation players to cost volatility from Chinese and Indian chemical manufacturers. This integration choice separates pricing power between conglomerates with Ludwigshafen-based chemical clusters and commodity-dependent competitors.
Pricing Analysis
Unbundled API supply contracts versus bundled formulation-plus-stability-testing packages split pricing structures across the sulfonylureas value chain. Three-tier pricing structure across premium, standard, and economy levels tracks bioequivalence documentation depth and CDSCO compliance status. Cost compression in Indian tier-2 and tier-3 retail channels is intensifying because domestic manufacturers leverage local stability testing infrastructure. Government hospital procurement entities in Maharashtra and Gujarat exhibit highest price sensitivity; Japanese integrated delivery networks show lowest sensitivity due to adherence-focused formulary protocols.
Supply Chain Analysis
EMA REACH certification and FDA bioequivalence qualification gates filter API supplier eligibility, concentrating approved sources among Indian and Chinese intermediate manufacturers with dedicated pharmaceutical chemical suites. KSM and intermediate production for glimepiride draws from Hyderabad, Mumbai, and Zhejiang province chemical parks. Single-source vulnerability in glimepiride API intermediates exposes finished dose manufacturers to supply interruption. Distribution runs through hospital pharmacy procurement entities for initial diagnosis volumes, with retail and digital channels capturing maintenance refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-compliant European supply chains and CDSCO-filtered Indian domestic markets exploits a cost differential in stability testing infrastructure and regulatory compliance overhead.
For Market Incumbents: Hedge against GLP-1 receptor agonist substitution by deepening backward integration into glimepiride intermediate production and securing sole-source agreements with Texas and Florida integrated delivery networks. Captive API capabilities in Ludwigshafen insulate margin structures from Chinese intermediate price volatility.
For New Entrants and Emerging Players: CDSCO stability mandates in India open a window for analytical infrastructure investments in Hyderabad and Mumbai to capture protected tier-2 and tier-3 outpatient markets. Target Nagpur, Indore, and Coimbatore clinic networks with bioequivalence-documented branded generics. Partner with regional distribution cooperatives bypassing wholesaler markups.
For Investors and Strategic Acquirers: Roll-up economics work for CDSCO-compliant branded generic specialists because fragmented domestic manufacturing in India lacks scale efficiencies in stability testing. Five-to-ten year viability hinges on combination therapy formulation pipelines. Monitor FDA pharmacovigilance database entries for cardiovascular safety signals as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Intermediates | Captive KSM production in Hyderabad chemical parks insulates margin from Chinese supplier concentration. |
| Fixed-Dose Combination Development | Glimepiride-metformin co-formulations address EMA and ADA multi-agent protocol adherence barriers. |
| Digital Pharmacy Channel Partnership | Online refill platforms capture maintenance prescriptions shifting from hospital pharmacy consolidation. |
| REACH Compliance Upgrade | Dedicated pediatric manufacturing suites meet EMA tightened nitrosamine thresholds for European access. |
| Hospital Procurement Sole-Source Agreement | Integrated delivery network contracts in Texas and Florida lock in longitudinal prescription capture. |
Research Methodology
Bottom-up diabetes treatment line modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, CDSCO regulatory affairs leads, formulary directors in integrated delivery networks, and analytical laboratory heads in Hyderabad and Mumbai combined with secondary validation from FDA ANDA filings, EMA quality guideline documents, ClinicalTrials.gov bioequivalence study registrations, and Indian customs pharmaceutical trade data. Top-down supply-side capacity assessments and bottom-up prescription volume estimates triangulate to base case projections.
Input-output matrix framing connects glimepiride intermediate production volumes to finished dose formulation output across molecule type, application protocol, end-user setting, and distribution channel dimensions. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion across the projection horizon. Forecast inputs incorporate REACH compliance cost pass-through assumptions and GLP-1 substitution elasticity parameters for combination therapy segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pharmacovigilance-triggered label restrictions or API supply disruption scenarios. Forecasts reflect documented assumptions on regulatory stability and substitution technology penetration. A model refresh is warranted upon material change in FDA cardiovascular safety signal monitoring or CDSCO testing mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Calcimimetic Market