
 Trulicity Market | 2026-2036
Trulicity Market Size, Share, and Industry Trends Forecast 2026-2036
Trulicity Market Insights
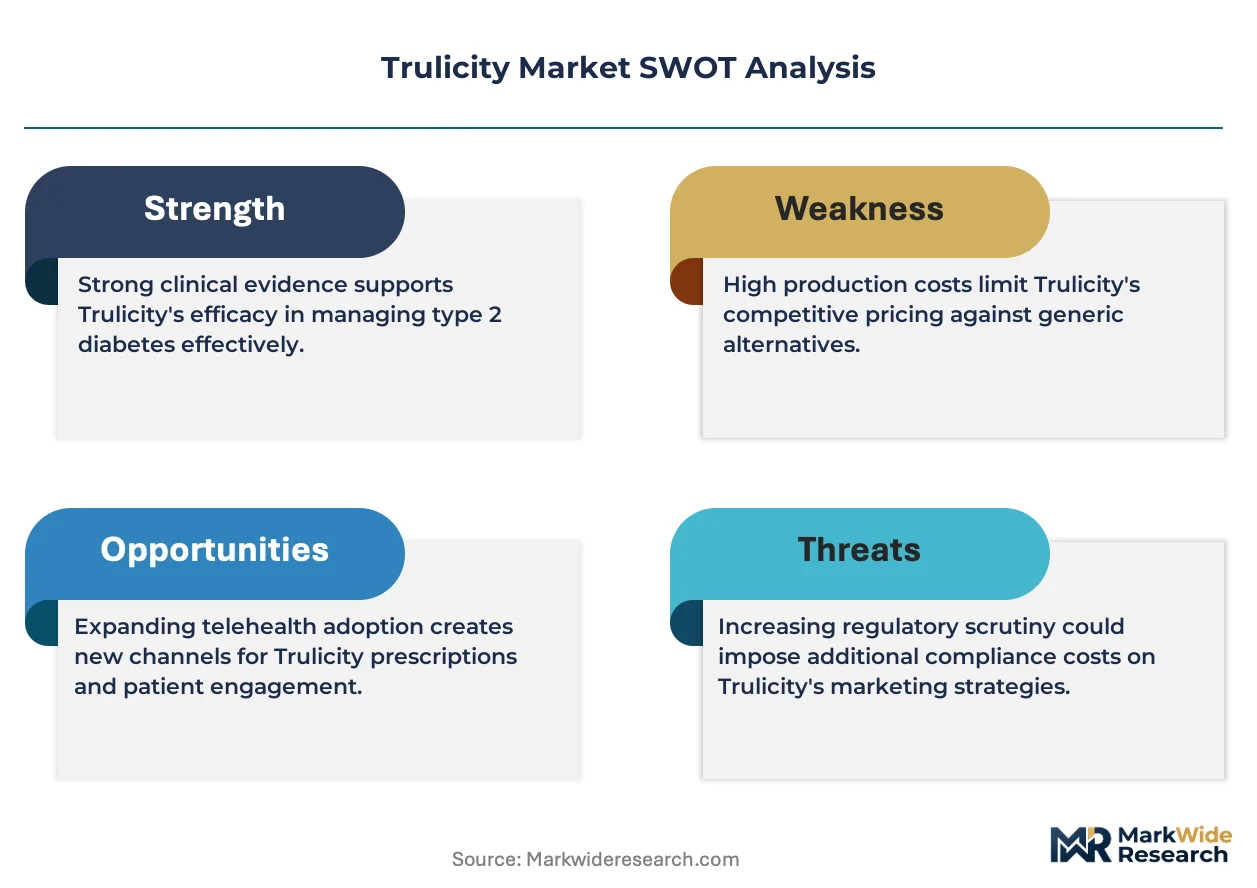
Hospital procurement committees are rotating volume toward once-weekly GLP-1 therapies as they seek to reduce nursing administration burden and improve outpatient adherence metrics. Eli Lilly and Company sustains manufacturing scale through captive biologics capacity in Indianapolis and Kinsale. Novo Nordisk competes through its integrated diabetes care platform that bundles device, drug, and digital support. Sanofi anchors European hospital channel access through established reimbursement relationships with Germany's G-BA and France's HAS.
Trulicity denotes dulaglutide, a glucagon-like peptide-1 receptor agonist administered via subcutaneous injection as a recombinant DNA-derived polypeptide fused to human immunoglobulin G4 fragment crystallizable region, designed to stimulate glucose-dependent insulin secretion and suppress glucagon release in adults with type 2 diabetes mellitus. The pen delivery format dominates ambulatory settings where patient self-administration reduces clinic visit burden, while the injection segment captures institutional volumes through prefilled syringe compatibility with automated dispensing cabinets. Weekly usage frequency commands the largest prescription share by aligning with patient lifestyle patterns and reducing pharmacy refill friction compared with daily alternatives.
The FDA's biosimilar approval framework and EMA's biosimilarity guidelines shape development timelines for follow-on dulaglutide candidates, while the EU AI Act and HIPAA compliance requirements constrain digital companion app data flows that manufacturers deploy alongside delivery devices. Japan's PMDA maintains distinct immunogenicity testing standards that extend registration timelines for foreign-origin biologics entering the world's third-largest diabetes market. Stakeholders must monitor patent litigation calendars and interchangeability designations that will determine whether pharmacy-level substitution erodes originator pricing power before biosimilar entrants achieve manufacturing parity.
Market Dynamics
Hospital formulary committees are consolidating weekly GLP-1 purchasing through centralized procurement frameworks that favor single-source contracts for high-volume biologics, compressing supplier diversity and amplifying price negotiation leverage against originator manufacturers.
Growth Catalysts
- US Medicare Part D coverage expansion:Broadened reimbursement for GLP-1 receptor agonists in outpatient settings drives prescription volume through retail pharmacy channels and reduces patient out-of-pocket abandonment rates.
- Prefilled pen device adoption:Self-administration technology eliminates clinic visit requirements and aligns with patient preference for discreet, portable diabetes management solutions in ambulatory care.
- Japan's aging diabetes population:Metabolic disease prevalence among adults over sixty-five creates sustained demand for adherence-optimized therapies with reduced dosing frequency.
Market Restraints
- Fermentation capacity scarcity:Recombinant peptide production requires specialized bioreactor infrastructure concentrated among contract manufacturers in Ireland and Singapore, creating supply bottlenecks during demand surges.
- EMA immunogenicity testing requirements:Extended pharmacovigilance protocols for biologics delay biosimilar market entry and sustain originator pricing power beyond patent expiry.
- Semaglutide substitution pressure:Oral and injectable alternatives with cardiovascular outcome benefits erode dulaglutide prescription share among cardiologist-influenced patient populations.
Strategic Opportunities
- Germany's DiGA fast-track pathway:Digital therapeutics integration with injectable therapies qualifies for statutory health insurance reimbursement, opening bundled prescription-digital service models.
- Hospital-at-home expansion:Skilled nursing facilities and home infusion providers represent underpenetrated channels for weekly injectable administration outside traditional clinic settings.
- Combination device convergence:Integration of dose tracking sensors with disposable pens enables adherence monitoring data streams that differentiate offerings in payer value-based contracts.
Industry Challenges
- Biologics manufacturing workforce scarcity:Cell culture specialists and aseptic filling operators command premium compensation in competitive labor markets around Indianapolis and Kinsale production clusters.
- Interchangeability designation uncertainty:FDA guidance gaps on pharmacy-level substitution without physician consultation create commercial planning volatility for biosimilar developers.
- Cold chain integrity complexity:Temperature excursion risks during last-mile distribution to retail pharmacies require redundant monitoring systems that inflate logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trulicity Market |
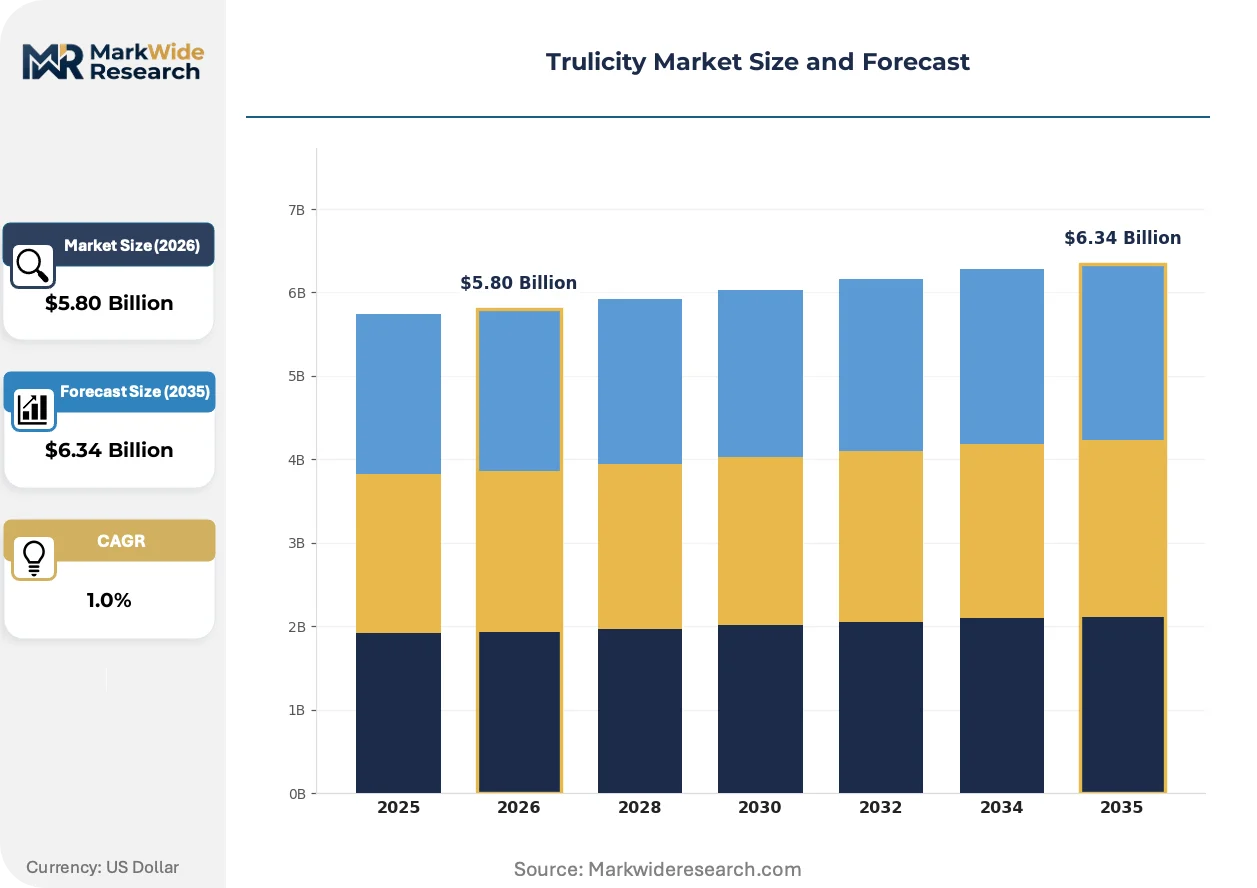
| Market Size in 2026 | $5.80 Billion |
| Market Size in 2035 | $6.34 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Pen, Vial, Cartridge End User: Patients, Healthcare Providers, Pharmacies, Hospitals Delivery Mode: Subcutaneous, Intravenous, Oral, Topical Usage Frequency: Daily, Weekly, Monthly, On-demand |
| Companies Covered | Eli Lilly and Company, Novo Nordisk, Sanofi, AstraZeneca, Merck and Co, Johnson and Johnson, Pfizer, Boehringer Ingelheim, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trulicity Market Trends and Innovations
Device engineering and regulatory science are converging to reshape competitive differentiation in weekly injectable diabetes therapy, with manufacturers racing to embed connectivity and reduce physical footprint before biosimilar commoditization accelerates.
Connected pen technology is miniaturizing Bluetooth-enabled dose capture into disposable injection devices without compromising drug stability or shelf life. Endocrinology practices in the United States are piloting these instruments for remote adherence verification. The capability is compressing differentiation timelines as digital features become baseline expectations rather than premium upgrades.
EMA's Medical Device Regulation (MDR) reclassification of drug-device combination products is forcing manufacturers to submit enhanced clinical evidence for pen injector modifications. The requirement extends registration timelines by twelve to eighteen months for delivery system updates. German notified bodies are experiencing backlog congestion that delays CE marking for next-generation devices.
Hospital procurement departments are consolidating insulin and GLP-1 purchasing through single-source distribution agreements that bundle diabetes device categories. Cardinal Health and McKesson are capturing volume through inventory management guarantees that displace fragmented multi-supplier arrangements. The concentration is most visible in integrated delivery networks across Texas and Florida where formulary standardization reduces nursing training burden.
Trulicity Market Segmentation
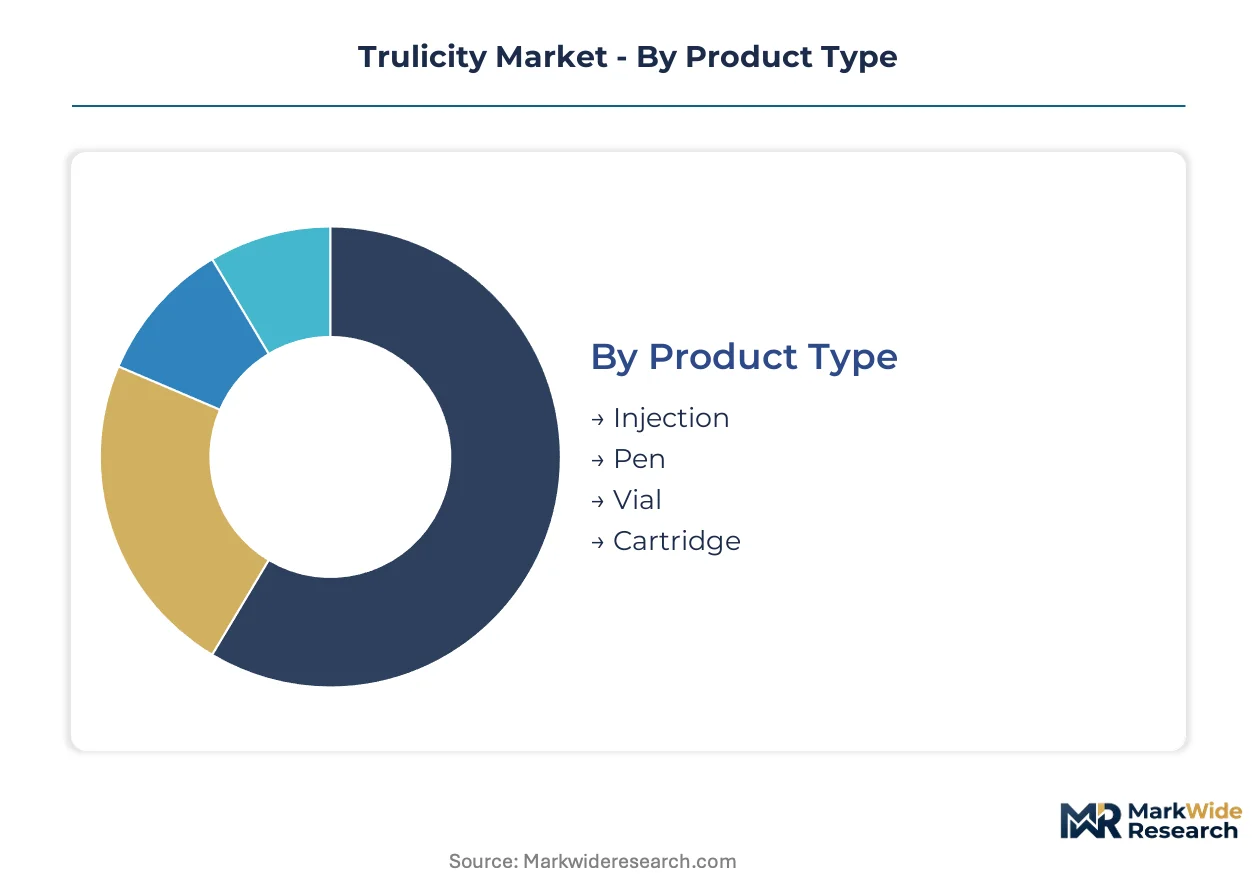
Weekly dulaglutide therapy fragments across four distinct segmentation axes that determine pricing power, channel access, and manufacturing scale. Product format and delivery mode concentrate margin in device-integrated offerings, while usage frequency and end-user type dictate volume distribution across retail pharmacy and institutional procurement channels.
Product Type:
Margin pools concentrate in prefilled formats that eliminate compounding steps and capture recurring device revenue alongside drug substance.
- Injection:Prefilled syringes compatible with automated dispensing cabinets dominate hospital formulary adoption. United States integrated delivery networks in Texas and Florida rotate procurement toward this format to reduce nursing training burden and standardize inventory across multiple facilities.
- Pen:Disposable injection devices with dose-adjustment mechanisms command ambulatory prescription preference. Patient self-administration in Germany and Japan reduces clinic visit frequency while generating higher per-unit revenue through integrated device pricing.
- Vial:Multi-dose containers serve compounding pharmacies and institutional settings with specialized dosing requirements. Refrigeration requirements and manual draw protocols limit retail pharmacy distribution.
- Cartridge:Reusable pen-compatible reservoirs target cost-sensitive markets and sustainability-focused procurement committees. Compatibility constraints with proprietary device platforms restrict addressable volume.
Pen holds installed capacity. Injection is rotating up the share rankings.
End User:
Volume concentration follows reimbursement pathway complexity, with institutional purchasers leveraging centralized procurement against fragmented retail channels.
- Patients:Direct-to-consumer demand concentrates in United States Medicare Part D and Japan's statutory health insurance coverage tiers. Out-of-pocket sensitivity drives abandonment rates at pharmacy counters when prior authorization delays extend beyond fourteen days.
- Healthcare Providers:Endocrinology practices and primary care clinics in Germany capture prescription initiation through integrated diabetes management protocols. Physician preference for weekly dosing frequency sustains formulary positioning against oral alternatives.
- Pharmacies:Retail chains and specialty distributors manage cold chain logistics for temperature-sensitive biologics. Cardinal Health and McKesson consolidate inventory guarantees that displace fragmented regional suppliers.
- Hospitals:Formulary committees in United States integrated delivery networks bundle insulin and GLP-1 purchasing through single-source agreements. Centralized procurement frameworks compress supplier diversity and amplify price negotiation leverage.
Healthcare providers anchor prescription initiation volume. Pharmacies are expanding fastest in logistics infrastructure investment.
Delivery Mode:
Technical validation requirements and immunogenicity risk profiles determine regulatory pathway costs and timeline predictability.
- Subcutaneous:Abdominal or thigh injection of dulaglutide represents the validated administration route with established pharmacokinetic profiles. FDA and EMA guidelines support this mode with streamlined bioequivalence requirements for device modifications.
- Intravenous:Systemic delivery remains experimental for GLP-1 receptor agonists due to rapid clearance and immunogenicity concerns. Clinical development programs face extended timelines under EMA immunogenicity testing protocols.
- Oral:Alternative small-molecule GLP-1 agonists compete through this delivery mode, though dulaglutide's peptide structure requires injection for bioavailability. Patient preference surveys in Japan indicate strong demand for non-injectable alternatives.
- Topical:Transdermal peptide delivery encounters stability and permeation barriers that have stalled commercial development. No approved dulaglutide formulations utilize this route.
Subcutaneous holds installed capacity. Oral is climbing the fastest among competing therapeutic modalities.
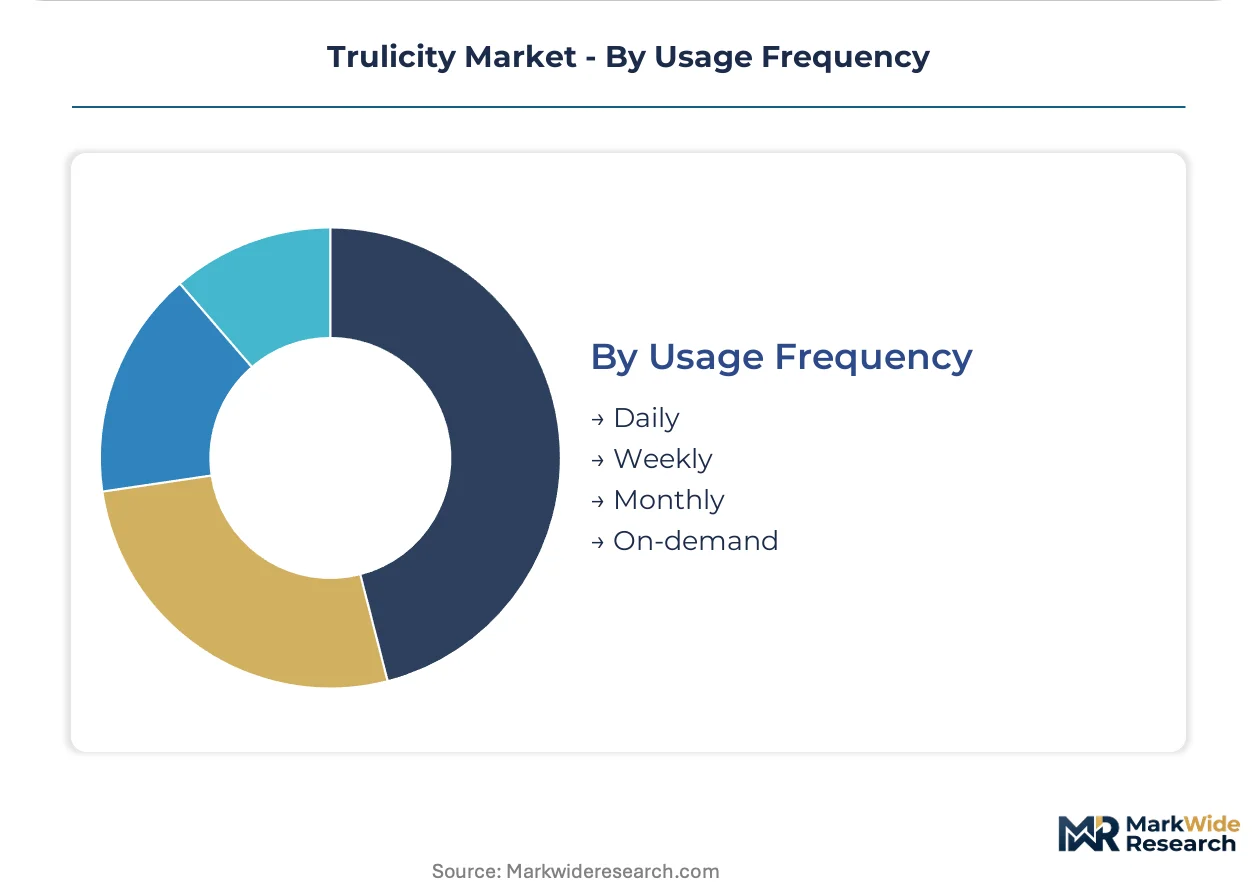
Usage Frequency:
Adherence optimization and pharmacy refill economics concentrate value in extended-interval dosing that aligns with patient lifestyle patterns.
- Weekly:Dulaglutide's dominant administration schedule reduces prescription refill friction and improves glycemic control persistence. United States retail pharmacy data shows lowest abandonment rates among GLP-1 therapies at this frequency.
- Daily:Alternative liraglutide and human insulin regimens compete through this schedule with established reimbursement pathways. Nursing administration burden in hospitals favors less frequent alternatives.
- Monthly:Extended-release formulations in development target patient preference for minimal injection burden. Japan's aging diabetes population over sixty-five demonstrates strongest stated preference for this interval.
- On-demand:Prandial glucose management applications remain niche for GLP-1 receptor agonists due to delayed onset of action. No approved dulaglutide indications support this usage pattern.
Weekly holds installed capacity. Monthly is gaining share fastest in development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and retail pharmacy chains concentrate purchasing power in markets with broad GLP-1 reimbursement coverage. Eli Lilly sustains manufacturing scale through captive biologics capacity in Indianapolis and Kinsale. Payer formulary decisions in Germany, Japan, and the United States determine volume allocation across weekly injectable therapies.
United States
Medicare Part D coverage expansion drives prescription volume through retail pharmacy channels and reduces patient out-of-pocket abandonment rates. FDA biosimilar pathway clarity shapes development timelines for follow-on dulaglutide candidates. Indianapolis hosts Eli Lilly's captive biologics manufacturing campus serving domestic hospital system procurement.
Germany
Statutory health insurance reimbursement for GLP-1 receptor agonists sustains prescription initiation through integrated diabetes management protocols. G-BA assessment procedures determine hospital formulary positioning for weekly injectable therapies. The Rhine-Ruhr metropolitan region anchors distribution infrastructure for temperature-sensitive biologics serving European hospital networks.
Japan
Metabolic disease prevalence among adults over sixty-five creates sustained demand for adherence-optimized therapies with reduced dosing frequency. PMDA immunogenicity testing standards extend registration timelines for foreign-origin biologics. The Kanto region surrounding Tokyo concentrates endocrinology practices prescribing weekly dulaglutide for type 2 diabetes management.
United Kingdom
NICE technology appraisals determine National Health Service funding for GLP-1 receptor agonists in primary care settings. MHRA post-Brexit regulatory autonomy creates distinct approval timelines from EMA centralized procedures. The Greater London area concentrates specialist diabetes centers influencing regional prescribing patterns for injectable therapies.
France
HAS transparency committee assessments shape hospital and ambulatory reimbursement for biologic diabetes therapies. ANSM pharmacovigilance requirements extend post-market surveillance obligations for immunogenicity monitoring. The Île-de-France region anchors hospital procurement consolidation for insulin and GLP-1 purchasing through single-source distribution agreements.
Trulicity Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with captive biologics manufacturing and established hospital channel relationships. Market structure concentrates around originator manufacturers with patent-protected peptide formulations and device-integrated delivery platforms. Two strategic archetypes dominate: vertically integrated biologics specialists controlling fermentation capacity, and diversified diabetes care platforms bundling drug, device, and digital services. Competitive moves center on manufacturing scale expansion and connected device technology licensing.
Within the originator biologics tier, Eli Lilly and Company, Novo Nordisk, and Sanofi exemplify contrasting strategic positions. Eli Lilly and Company represents the captive manufacturing archetype with bioreactor infrastructure concentrated in Indianapolis and Kinsale. Novo Nordisk occupies a position emphasizing integrated diabetes care platforms that bundle device, drug, and digital support. Sanofi anchors European hospital channel access through established reimbursement relationships with national health technology assessment bodies.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novo Nordisk |
| Sanofi |
| AstraZeneca |
| Merck and Co |
| Johnson and Johnson |
| Pfizer |
| Boehringer Ingelheim |
| GlaxoSmithKline |
| Others |
Pricing and Supply Chain Analysis
FDA biosimilar interchangeability standards gate both manufacturing qualification and price differentiation simultaneously, requiring originators to defend premium positioning through device-integrated offerings while biosimilar developers navigate extended immunogenicity testing timelines that compress margin windows.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate hospital procurement agreements for dulaglutide, linking device-integrated pen pricing to fermentation input costs. Three-tier pricing structure across premium connected-pen, standard disposable-pen, and economy vial formats separates patient self-administration convenience from institutional compounding flexibility. Pricing pressure stems from semaglutide cardiovascular outcome data shifting cardiologist prescribing preference. Retail pharmacy channels exhibit highest price sensitivity due to Medicare Part D out-of-pocket exposure, while integrated delivery networks leverage volume consolidation for contract concessions.
Supply Chain Analysis
Ireland and Singapore anchor recombinant peptide fermentation capacity, with Indianapolis and Kinsale hosting captive biologics manufacturing for originator supply security. Cell culture media, aseptic filling components, and cold-chain packaging materials draw from specialized chemical suppliers concentrated in Germany and Switzerland. Single-source vulnerability concentrates in contract manufacturing organization capacity for high-volume bioreactor runs. Distribution runs through Cardinal Health and McKesson inventory guarantee programs serving United States hospital networks, with regional cold-chain hubs in the Rhine-Ruhr metropolitan area covering European institutional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as oral semaglutide and emerging weekly injectable alternatives erode dulaglutide prescription share among cardiologist-influenced patient populations.
For Market Incumbents: Fortify manufacturing scale through captive bioreactor capacity expansion in Indianapolis and Kinsale to offset biosimilar volume capture. Deepen device-integrated differentiation via Bluetooth-enabled dose tracking that satisfies Germany's DiGA fast-track reimbursement requirements. Prioritize hospital-at-home channel partnerships to secure skilled nursing facility volume before biosimilar entrants achieve distribution parity. For New Entrants and Emerging Players: Japan's PMDA immunogenicity fast-track pathway offers accelerated registration timelines for biosimilar developers with established biologics characterization capabilities. Target Germany's statutory health insurance reimbursement tier for digital-therapeutic bundled offerings that combine injectable therapy with adherence monitoring apps. Pursue hospital procurement committee relationships in Texas and Florida integrated delivery networks where formulary standardization creates single-source contract opportunities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected-device manufacturing sub-segments as EMA MDR reclassification forces enhanced clinical evidence submissions. Five-to-ten year viability favors acquisition targets with captive fermentation capacity and established G-BA or HAS reimbursement relationships. Monitor FDA interchangeability designation calendars as the critical inflection signal for pharmacy-level substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biosimilar Development Program | EMA immunogenicity guidelines and FDA interchangeability pathways determine competitive entry timelines. |
| Connected Device Integration | Bluetooth-enabled dose tracking satisfies Germany's DiGA fast-track statutory health insurance reimbursement. |
| Hospital-at-Home Channel Expansion | Skilled nursing facilities represent underpenetrated administration venues outside traditional clinic settings. |
| Manufacturing Scale-Up | Captive bioreactor capacity in Indianapolis and Kinsale defends against contract manufacturing bottlenecks. |
| Digital Therapeutic Bundling | Companion adherence apps qualify for value-based payer contracts in United States Medicare Part D channels. |
Research Methodology
Initial hypotheses were tested against primary input from formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists and refined through secondary validation across FDA biosimilar approval filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and United States hospital procurement databases. Bottom-up prescription volume modeling triangulated against top-down reimbursement expenditure analysis produced convergent market size estimates.
Variance decomposition across product format, delivery mode, usage frequency, and end-user type segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from longitudinal prescription audit data and reimbursement trend analysis. Forecast inputs incorporated PMDA immunogenicity testing timeline assumptions and G-BA assessment procedure schedule probabilities.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Part D coverage expansion or accelerated FDA interchangeability designation would require recalibration. Forecasts reflect documented assumptions regarding biosimilar manufacturing parity achievement and digital therapeutic reimbursement pathway stability. Recalibration cycles align with material shifts in patent litigation calendars and EMA MDR notified body backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market