
 Glioblastoma Treatment Drugs Market | 2026-2036
Glioblastoma Treatment Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Glioblastoma Treatment Drugs Market Analysis
Oncology specialty pharmacy distribution is reconfiguring around patient-centric infusion models and limited distribution networks. Merck & Co., Inc. leverages its position in alkylating agent supply chains to sustain manufacturing scale across North American hospital systems. F. Hoffmann-La Roche Ltd. anchors European access through centralized compounding partnerships. Amgen, Inc. competes via differentiated biologic delivery platforms that reduce cold-chain complexity.
Glioblastoma treatment drugs comprise systemic and localized pharmaceutical agents designed to cross the blood-brain barrier or achieve intratumoral concentration, including temozolomide-based alkylators, bevacizumab-targeted VEGF inhibitors, and tumor-treating field devices. These therapies aim to extend progression-free survival in grade IV astrocytoma patients following surgical debulking. Chemotherapy retains the largest revenue pool due to generic substitution and protocol standardization, while immunotherapy represents the fastest-expanding segment as checkpoint inhibitors and CAR-T approaches enter Phase III glioblastoma trials. Intratumoral administration routes command premium positioning owing to catheter-based delivery complexity and neurosurgical coordination requirements.
FDA oncology center of excellence review standards, EMA orphan drug designation frameworks, and WHO essential medicines list criteria collectively shape trial design priorities and reimbursement thresholds across developed markets. Regulatory pressure for real-world evidence generation is intensifying post-approval commitments for novel mechanisms. Stakeholders must monitor biomarker-driven patient stratification protocols that will determine which development programs secure priority review and formulary placement.
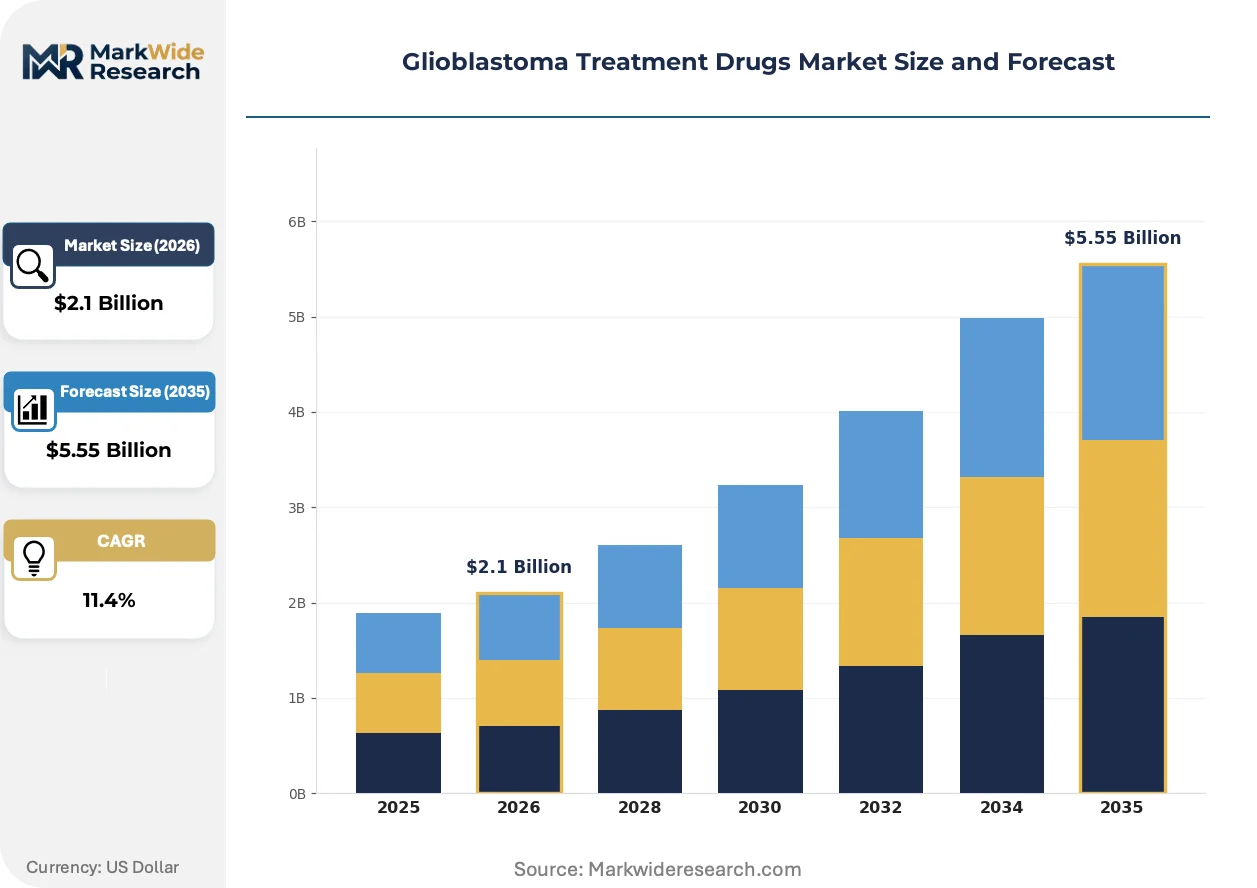
Market Dynamics
FDA accelerated approval pathways for oncology biologics are compressing development timelines and reshaping how pharmaceutical firms allocate R&D capital across glioblastoma drug portfolios.
Growth Catalysts
- EMA Orphan Drug Designation:European frameworks grant market exclusivity and fee waivers that incentivize biotech firms to pursue novel mechanisms for rare brain malignancies.
- Tumor-Treating Field Devices:Electromagnetic delivery systems are expanding addressable patient populations beyond surgical candidates into maintenance therapy protocols.
- Tertiary Care Center Density:United States academic medical centers concentrate glioblastoma case volumes and clinical trial enrollment capacity.
Market Restraints
- Blood-Brain Barrier Penetration:Structural limitations in CNS drug delivery constrain efficacy ceilings for systemic chemotherapy agents.
- Cold-Chain Infrastructure:Biologic stability requirements create distribution bottlenecks in rural hospital networks and emerging markets.
- Alkylating Agent Supply Concentration:Generic temozolomide production concentrates among a limited supplier base in Asian manufacturing hubs.
Strategic Opportunities
- CAR-T Intratumoral Delivery:Convergence of cellular therapy with catheter-based neurosurgical techniques opens localized administration protocols.
- Biomarker-Driven Stratification:MGMT methylation testing and IDH mutation screening enable precision patient selection for targeted trial enrollment.
- India CDSCO Fast-Track:Emerging market regulators are streamlining oncology drug approval pathways to accelerate access in high-burden populations.
Industry Challenges
- Neuro-oncology Specialist Scarcity:Fellowship-trained physicians capable of coordinating multimodal glioblastoma care remain concentrated in urban academic centers.
- Real-World Evidence Generation:Post-approval commitments for novel mechanisms demand expanded patient registries and long-term surveillance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glioblastoma Treatment Drugs Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy Administration Route: Intravenous, Oral, Intratumoral, Subcutaneous Patient Type: Adult, Pediatric, Elderly, Post-operative Development Stage: Clinical Trials, FDA Approved, Research Phase, Marketed |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd., Amgen, Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Arbor Pharmaceuticals, LLC, Amneal Pharmaceuticals, Novocure Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glioblastoma Treatment Drugs Market Emerging Trajectories
Checkpoint inhibitor combinations and localized drug delivery platforms are redrawing therapeutic protocols for grade IV astrocytoma management.
Focused ultrasound-mediated blood-brain barrier disruption is rendering obsolete conventional assumptions about CNS drug penetration limits. Neuro-oncology departments at major academic centers are integrating this technology into first-line combination protocols. The approach is compressing development timelines for agents previously shelved due to CNS exclusion.
REACH authorization requirements for novel pharmaceutical manufacturing processes are tightening impurity thresholds for biologic active ingredients. European contract manufacturers are retrofitting production lines to meet enhanced analytical specification demands. Glioblastoma immunotherapy developers sourcing European manufacturing capacity face extended qualification timelines.
Hospital pharmacy directors are consolidating oncology drug purchasing through limited distribution networks that bundle infusion services with product acquisition. Specialty pharmacy intermediaries are losing direct hospital access as health systems bring biologic administration in-house. This consolidation is most pronounced in United States integrated delivery networks with captive specialty pharmacy capabilities.
Glioblastoma Treatment Drugs Market Segmentation
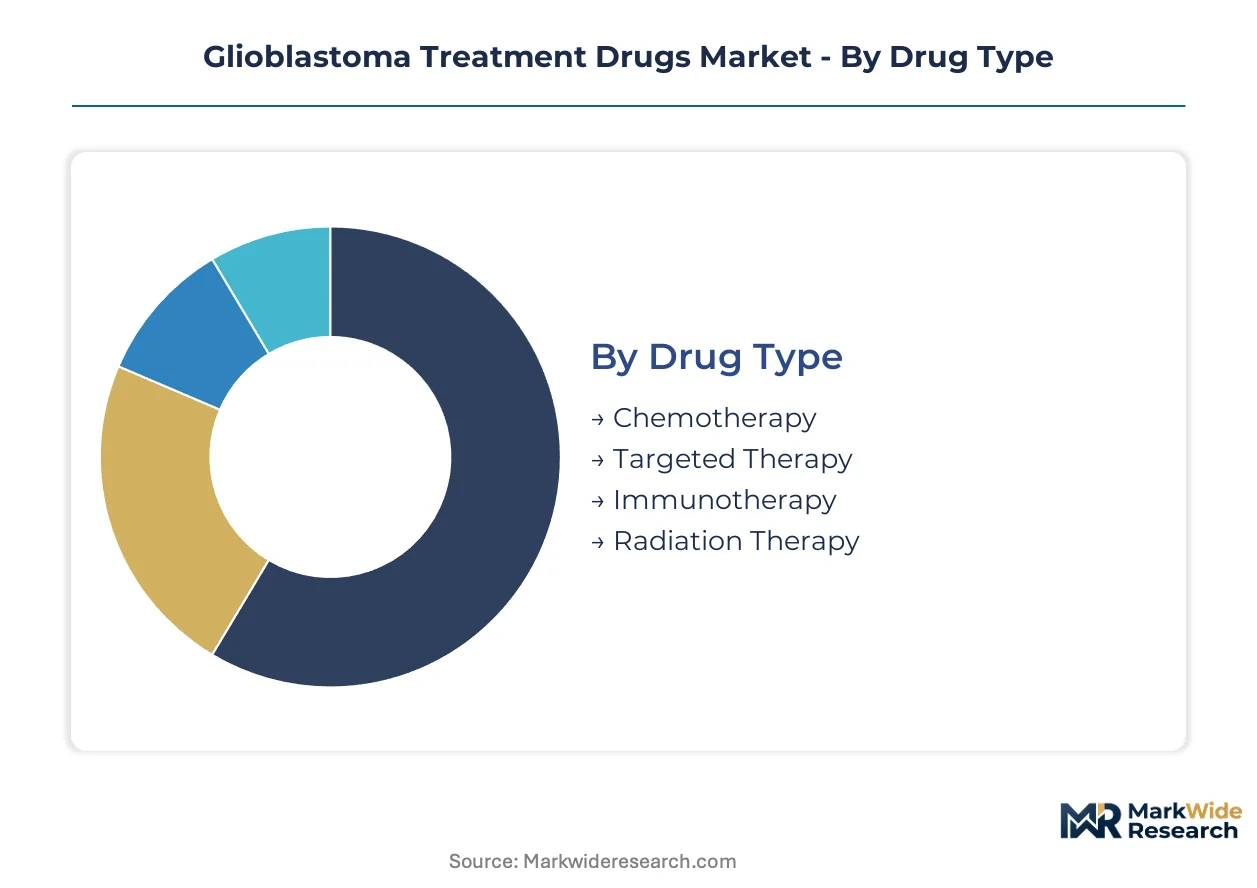
Glioblastoma treatment protocols demand precise patient stratification to match drug mechanisms with tumor biology and surgical status. Segmentation reveals how administration complexity, patient demographics, and regulatory maturity reshape competitive positioning across therapeutic categories.
Drug Type:
After-sales service intensity varies sharply across drug categories, with biologics requiring cold-chain monitoring, patient education programs, and adverse event reporting infrastructure that alkylating agents simply do not need.
- Chemotherapy:Temozolomide-based alkylating agents constitute the protocol backbone, with generic substitution driving cost compression across United States hospital formularies. Demand concentrates in post-surgical adjuvant settings where MGMT methylation status guides dosing intensity.
- Targeted Therapy:Bevacizumab and similar VEGF inhibitors command premium positioning through specialized infusion center requirements and biomarker-driven patient selection. Academic medical centers in Boston and Houston anchor United States adoption for recurrent disease protocols.
- Immunotherapy:Checkpoint inhibitors and CAR-T approaches are advancing through Phase III glioblastoma trials with substantial neuro-oncology specialist oversight requirements.
- Radiation Therapy:Tumor-treating field devices extend into maintenance therapy with electromagnetic delivery systems requiring patient training and device calibration support.
Chemotherapy holds the largest share; momentum sits with immunotherapy.
Administration Route:
Cost tier stratification separates catheter-based intratumoral delivery from standard infusion, with neurosurgical coordination adding substantial procedure economics to pharmaceutical acquisition.
- Intravenous:Bevacizumab and checkpoint inhibitors flow through hospital oncology infusion centers with established nursing protocols and pharmacy oversight. United States integrated delivery networks are bringing these services in-house to capture margin.
- Oral:Temozolomide capsules enable outpatient maintenance therapy with adherence monitoring programs replacing intensive clinical supervision. Generic substitution has compressed pricing across Medicare Part D formularies.
- Intratumoral:Convection-enhanced delivery and catheter-based administration require neurosurgical suite access and real-time imaging guidance, limiting addressable patients to tertiary referral centers.
- Subcutaneous:Emerging biologic formulations aim to reduce cold-chain burden and enable community oncology administration outside academic medical center catchment areas.
Intravenous delivery dominates current volume; intratumoral routes are climbing the fastest.
Patient Type:
Application urgency varies by surgical status and age-related tolerance for aggressive multimodal protocols, with post-operative patients presenting the most standardized treatment windows.
- Adult:Patients aged 18-65 constitute the core trial population and protocol standardization target, with KPS scores above 70 determining eligibility for combined chemoradiation.
- Pediatric:Diffuse intrinsic pontine glioma and high-grade astrocytoma in children require specialized dosing and distinct trial infrastructure at St. Jude and similar centers.
- Elderly:Patients over 65 with comorbidity burdens drive demand for de-escalated protocols and hypofractionated radiation schedules.
- Post-operative:Gross total resection status determines adjuvant therapy intensity and remains the critical stratification variable for clinical trial enrollment.
Adult patients represent the largest addressable population; pediatric segments are expanding most quickly as dedicated neuro-oncology programs mature.
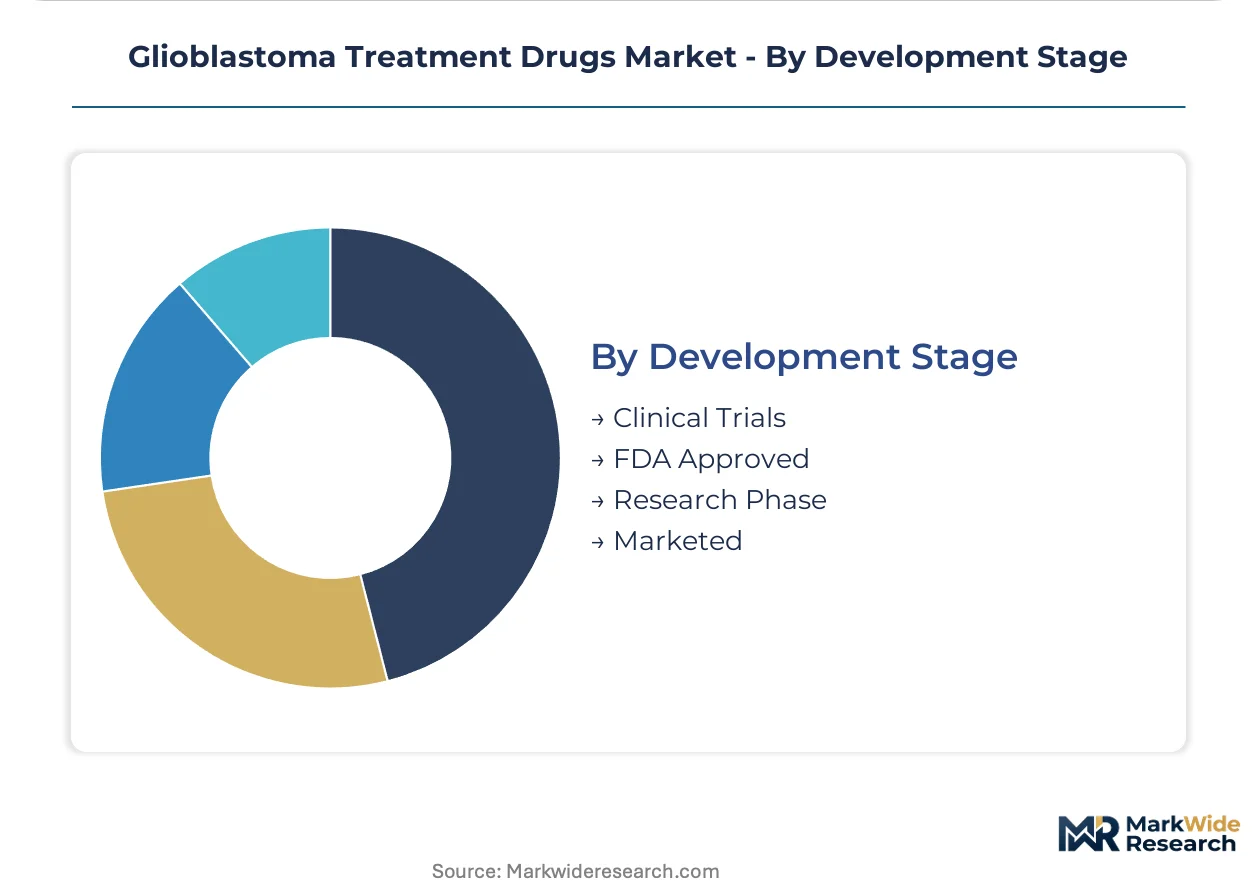
Development Stage:
Margin profiles diverge dramatically between marketed alkylators with generic competition and novel mechanisms still carrying full R&D capitalization through accelerated FDA review.
- Clinical Trials:Phase II and III glioblastoma studies concentrate at NCI-designated cancer centers with substantial patient screening infrastructure and biomarker analysis capabilities.
- FDA Approved:Temozolomide and bevacizumab carry established reimbursement codes with prior authorization requirements varying across United States commercial payers.
- Research Phase:Preclinical programs targeting IDH-mutant gliomas and novel delivery vectors occupy academic-industry partnership structures.
- Marketed:Tumor-treating field devices and approved systemic therapies flow through specialty pharmacy and durable medical equipment channels with distinct contracting dynamics.
FDA Approved therapies command current revenue; Clinical Trials are gaining share fastest as accelerated approval pathways compress development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in glioblastoma therapeutics concentrates in United States tertiary centers, while European reimbursement compression limits margin expansion despite comparable clinical standards. Japan commands premium positioning for novel mechanism approvals through PMDA Sakigake designation timelines. India emerges as a volume growth vector where CDSCO fast-track pathways accelerate access for high-burden populations.
United States
NCI-designated cancer centers in Houston and Boston anchor clinical trial enrollment density and protocol innovation. FDA oncology center of excellence review standards compress approval timelines for breakthrough-designated glioblastoma agents. Hospital pharmacy consolidation across integrated delivery networks is bringing biologic infusion services in-house to capture specialty pharmacy margin.
Germany
EMA centralized marketing authorization procedures position German university hospitals as early access sites for orphan-designated neuro-oncology therapies. REACH authorization requirements for novel biologic manufacturing processes are tightening impurity thresholds and extending European contract manufacturer qualification timelines. The Heidelberg-Mannheim medical cluster concentrates neurosurgical expertise and convection-enhanced delivery protocol development.
Japan
PMDA Sakigake designation creates accelerated review pathways for glioblastoma immunotherapies targeting unmet medical need. METI industrial policy supports domestic biologic manufacturing capacity expansion to reduce import dependency for cold-chain-dependent oncology products. The Tokyo-Osaka corridor concentrates Phase III trial infrastructure and biomarker analysis capabilities for MGMT methylation stratification protocols.
India
CDSCO fast-track oncology approval pathways are compressing regulatory timelines for high-burden brain malignancy populations. The country's national pharmaceutical regulator has streamlined import licensing for temperature-sensitive biologics to address cold-chain infrastructure gaps. Mumbai and Hyderabad anchor generic temozolomide production clusters supplying hospital procurement across South Asian markets.
United Kingdom
NICE technology appraisal processes create transparent reimbursement thresholds that shape glioblastoma drug launch sequencing across European markets. MHRA post-Brexit regulatory autonomy enables accelerated access partnerships for innovative neuro-oncology mechanisms. The London-Oxford-Cambridge triangle concentrates academic-industry collaboration structures for CAR-T intratumoral delivery vector development.
Glioblastoma Treatment Drugs Market Vendor Landscape
Alkylating agent specialists and biologic platform developers split the market along manufacturing complexity and cold-chain infrastructure requirements. The vendor base concentrates around three strategic archetypes: large-cap diversified pharmaceutics with hospital system contracting scale, mid-cap oncology specialists with accelerated regulatory track records, and device-therapy convergent players integrating electromagnetic delivery with pharmaceutical protocols. Dominant competitive moves include backward integration into generic active pharmaceutical ingredient supply and strategic partnerships with academic medical centers for real-world evidence generation.
Within the large-cap diversified tier, Merck & Co., Inc. and F. Hoffmann-La Roche Ltd. exemplify contrasting geographic anchoring strategies for hospital system access. Amgen, Inc. occupies a position representing biologic delivery platform specialization that reduces distribution complexity for community oncology networks. These three entities collectively illustrate how manufacturing scale, European centralized compounding partnerships, and differentiated administration technologies define competitive positioning in glioblastoma therapeutics procurement.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| Amgen, Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Arbor Pharmaceuticals, LLC |
| Amneal Pharmaceuticals |
| Novocure Ltd. |
| Others |
Supply Flow & Price Mechanics
Asian API manufacturing clusters for temozolomide active pharmaceutical ingredients concentrate among three dominant suppliers, anchoring margin capture at the generic formulation tier while hospital systems extract value through consolidated purchasing leverage. This upstream concentration forces downstream players to compete on infusion service bundling rather than pharmaceutical acquisition economics.
Pricing Analysis
The customization-premium spread separates standard oral temozolomide from catheter-based intratumoral delivery protocols, with neurosurgical coordination adding substantial procedure economics. Pricing stratifies across premium, standard, and economy tiers based on biomarker-driven patient stratification and cold-chain complexity. Cost compression in oral alkylating agents intensifies because of generic substitution across Medicare Part D formularies. Community oncology networks demonstrate highest price sensitivity, while academic medical centers absorb premium positioning for novel mechanisms.
Supply Chain Analysis
Supplier-financing facilities extended by Indian and Chinese API manufacturers enable working capital flexibility for generic formulation packagers facing hospital procurement payment delays. Biologic active ingredients draw from South Korean and Japanese fermentation capacity, with European contract manufacturers handling final fill-finish for checkpoint inhibitors. Single-source vulnerability concentrates in temperature-sensitive biologics dependent on specialized cold-chain logistics. Distribution runs through limited specialty pharmacy networks that bundle infusion services with product acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained neuro-oncology specialists capable of coordinating multimodal glioblastoma care remain concentrated in urban academic centers, creating a bottleneck that constrains addressable patient populations for novel delivery platforms.
For Market Incumbents: Pre-empt generic erosion in alkylating agents by securing backward integration into Asian API supply and expanding captive infusion center networks within integrated delivery systems. CAR-T intratumoral delivery programs from emerging biotech firms threaten premium positioning in maintenance therapy segments. Manufacturing scale in cold-chain biologics represents the critical defensive lever. For New Entrants and Emerging Players: Pursue convection-enhanced delivery partnerships with tertiary care centers in India and Southeast Asia where CDSCO fast-track pathways compress regulatory timelines. The pediatric diffuse intrinsic pontine glioma segment presents the most penetrable white space with dedicated trial infrastructure at St. Jude and similar centers. Go-to-market positioning should emphasize subcutaneous biologic formulations that reduce cold-chain burden for community oncology administration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharmacy intermediaries losing hospital access as health systems bring biologic administration in-house. Long-term viability hinges on platform durability across multiple oncology indications beyond glioblastoma. The signal to watch is FDA breakthrough therapy designation frequency for blood-brain barrier penetration technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III glioblastoma studies at NCI-designated centers accelerate biomarker-driven patient stratification protocols. |
| Manufacturing Scale-Up | Cold-chain biologic capacity expansion in South Korea reduces import dependency for Japanese oncology markets. |
| Regulatory Approval Pathway | FDA oncology center of excellence review standards compress timelines for breakthrough-designated agents. |
| Licensing Agreement | Academic-industry partnerships for CAR-T intratumoral delivery vectors leverage London-Oxford-Cambridge research clusters. |
| Pipeline Diversification | IDH-mutant glioma programs extend addressable populations beyond primary glioblastoma indications. |
Methodological Framework
The analysis maps chemotherapy, targeted therapy, immunotherapy, and tumor-treating field device segments, each validated through neuro-oncology specialists, hospital pharmacy directors, regulatory affairs leads, and payer access specialists. Primary interviews with formulary decision-makers at NCI-designated cancer centers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Assumption sets held regulatory approval timelines and reimbursement coding stability fixed while varying clinical trial success rates and biosimilar entry timing. Segmentation dimensions modeled include drug type, administration route, patient population, and regional regulatory cluster. CAGRs derived from patient volume projections, pricing trajectory assumptions, and protocol penetration curves. Forecast inputs incorporated MGMT methylation testing adoption rates and IDH mutation screening expansion.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, biologic manufacturing input costs, or cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway efficiency and hospital consolidation momentum. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market