
 Italy Diabetes Drugs Market | 2026-2036
Italy Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Diabetes Drugs Market Foresight
CE marking under the EU Medical Devices Regulation (MDR) for connected insulin delivery systems is collapsing the competitive field to manufacturers with notified body certification and post-market surveillance infrastructure. Novo Nordisk leverages its integrated diabetes care platform spanning GLP-1 agonists and smart pens to sustain leadership in Italian endocrinology wards. Sanofi anchors its position through long-acting insulin portfolios and hospital formulary relationships across northern Italy's major health districts. Eli Lilly differentiates via dual GIP/GLP-1 receptor agonist technology that competes for specialist preference in academic medical centers.
Italy diabetes drugs comprise pharmaceutical agents engineered to regulate blood glucose through hormonal modulation, enzymatic inhibition, or renal glucose excretion mechanisms, with formulations requiring precise bioavailability parameters and stability profiles for chronic administration. These therapies serve to prevent microvascular complications, reduce cardiovascular mortality, and maintain glycemic targets in type 1 and type 2 diabetes populations. GLP-1 agonists and SGLT2 inhibitors now command the fastest-expanding prescription volumes as cardiorenal outcome data reshapes Italian Society of Diabetology guidelines, while subcutaneous delivery dominates administration route preferences due to patient self-management feasibility and pharmacy reimbursement structures. Oral DPP-4 inhibitors occupy a mature, price-sensitive tier where generic substitution pressures concentrate margin pools.
AIFA, Italy's national pharmaceutical regulator, governs pricing and reimbursement access for diabetes therapies through health technology assessment protocols that delay market entry for non-inferior compounds. The EU MDR and national data privacy frameworks shape requirements for connected delivery devices and real-world evidence collection. Stakeholders must monitor AIFA's evolving evaluation criteria for cardiovascular outcome trials and the interplay between regional health authority formularies and centralized pricing negotiations.
Market Dynamics
AIFA's health technology assessment protocols are compressing reimbursement timelines for cardiovascular outcome trials, forcing manufacturers to front-load real-world evidence generation before formulary negotiations. This regulatory gatekeeping is concentrating market access among firms with established Italian hospital relationships.
Growth Catalysts
- Cardiorenal outcome data:Italian Society of Diabetology guideline updates are expanding GLP-1 agonist and SGLT2 inhibitor prescribing for comorbid populations beyond glycemic control alone.
- Lombardy regional concentration:Milan's academic hospital cluster generates early adoption pathways that diffuse southward through specialist referral networks and regional health authority formularies.
- EU MDR CE marking:Connected insulin delivery systems with notified body certification are capturing hospital procurement contracts as post-market surveillance infrastructure becomes a competitive filter.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing for biologic diabetes therapies remains dependent on Asian fermentation capacity, exposing Italian formularies to shipment volatility and customs delays.
- AIFA pricing compression:Centralized reimbursement negotiations for non-inferior compounds are eroding margin pools in mature oral DPP-4 inhibitor segments where generic substitution accelerates.
- Specialist workforce scarcity:Endocrinology fellowship vacancies in southern Italian regions constrain patient access to advanced therapy initiation and dose optimization protocols.
Strategic Opportunities
- Campania and Sicily underpenetration:Southern Italian regions with lower specialist density present whitespace for telemedicine-enabled diabetes management platforms that bridge geographic access gaps.
- Integrated care pathway mandates:Italy's National Health Service chronic disease protocol strengthening creates procurement openings for bundled glucose monitoring and insulin delivery ecosystems.
- Real-world evidence convergence:Linking connected pen data with regional health registry infrastructure is enabling outcome-based contract pilots with Lombardy and Veneto health authorities.
Industry Challenges
- EU MDR technical documentation:Software-as-medical-device classification for dose calculation algorithms is extending certification timelines and requiring notified body relationships that smaller manufacturers lack.
- Legacy system interoperability:Hospital electronic health record fragmentation across Italy's 20 regional health systems complicates connected device data integration and remote monitoring deployment.
- Pharmacovigilance talent scarcity:Post-market surveillance obligations for combination drug-device products are outstripping qualified regulatory affairs capacity in Italian affiliates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Diabetes Drugs Market |
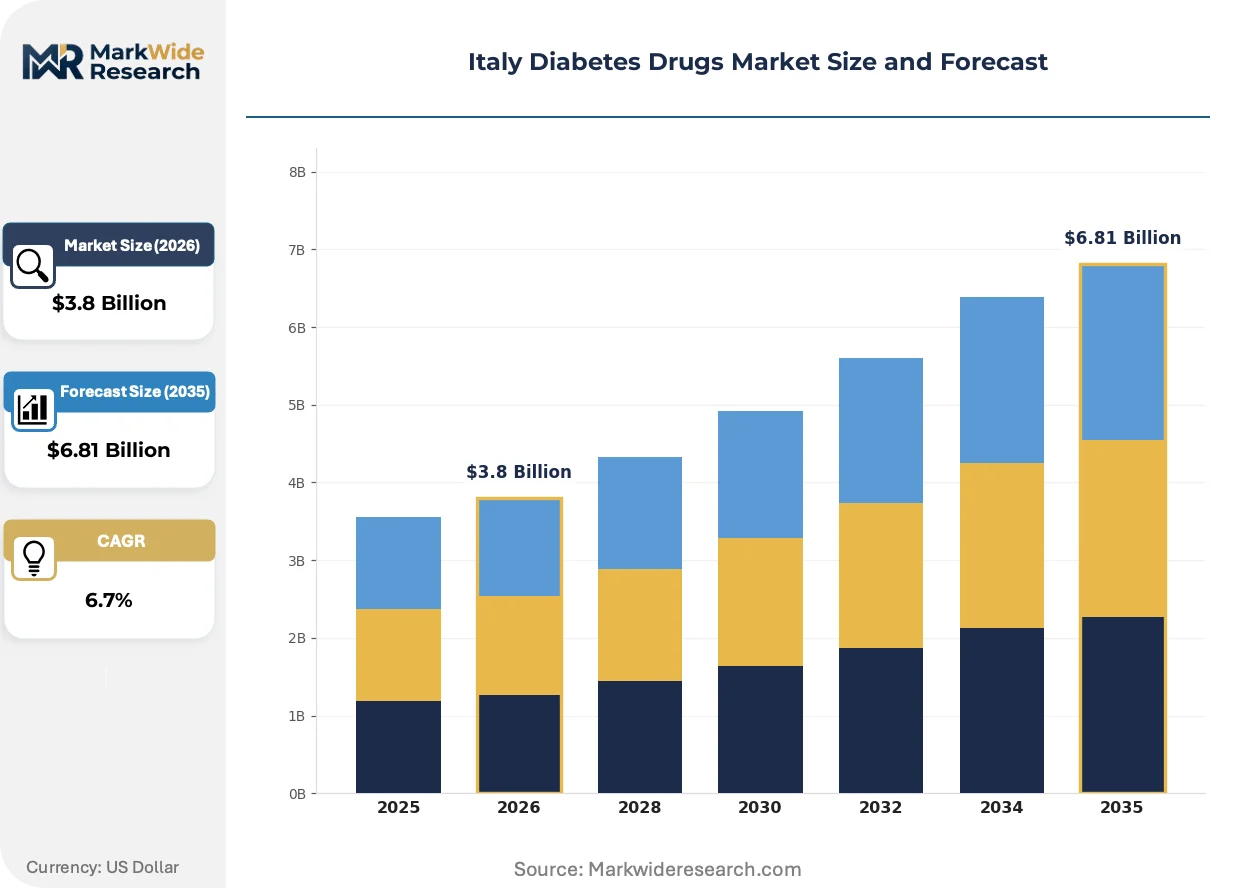
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, SGLT2 Inhibitors, DPP-4 Inhibitors Administration Route: Subcutaneous, Oral, Intravenous, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | AstraZeneca, Merck and Co., Novo Nordisk, Janssen Pharmaceuticals, Takeda, Sanofi, Boehringer Ingelheim, Pfizer, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Diabetes Drugs Market Shifts & Advancements
Dual GIP/GLP-1 receptor agonist mechanisms are compressing the therapeutic hierarchy in Italian academic centers, while connected delivery hardware and algorithmic dosing reshape how therapies are administered and reimbursed. These shifts are redrawing competitive boundaries between pharmaceutical and device manufacturers.
Dual GIP/GLP-1 receptor agonist technology delivers integrated metabolic control through simultaneous incretin pathway modulation and gastric emptying regulation. Endocrinology wards at Milan's Policlinico and Rome's Policlinico Gemelli are prioritizing these agents for complex type 2 diabetes with obesity comorbidity. This mechanism is supplanting sequential GLP-1 agonist and basal insulin escalation protocols in high-complexity patient populations.
AIFA's evolving cardiovascular outcome trial evaluation criteria are rewriting market access requirements for glucose-lowering agents seeking premium reimbursement tiers. Manufacturers must now submit integrated cardiorenal endpoint data before centralized pricing negotiations commence. Northern Italy's regional health authorities are responding by tightening formulary gates for agents lacking heart failure risk reduction evidence.
Specialist prescribing patterns in Italian diabetes care are rotating toward integrated drug-device ecosystems that bundle glucose sensors with algorithm-guided insulin delivery. Academic medical centers are displacing standalone pharmaceutical procurement with platform contracts covering continuous monitoring hardware, data analytics subscriptions, and therapy optimization services. This bundling behavior concentrates most visibly in Lombardy's integrated care districts where procurement consolidation is accelerating.
Italy Diabetes Drugs Market Segmentation
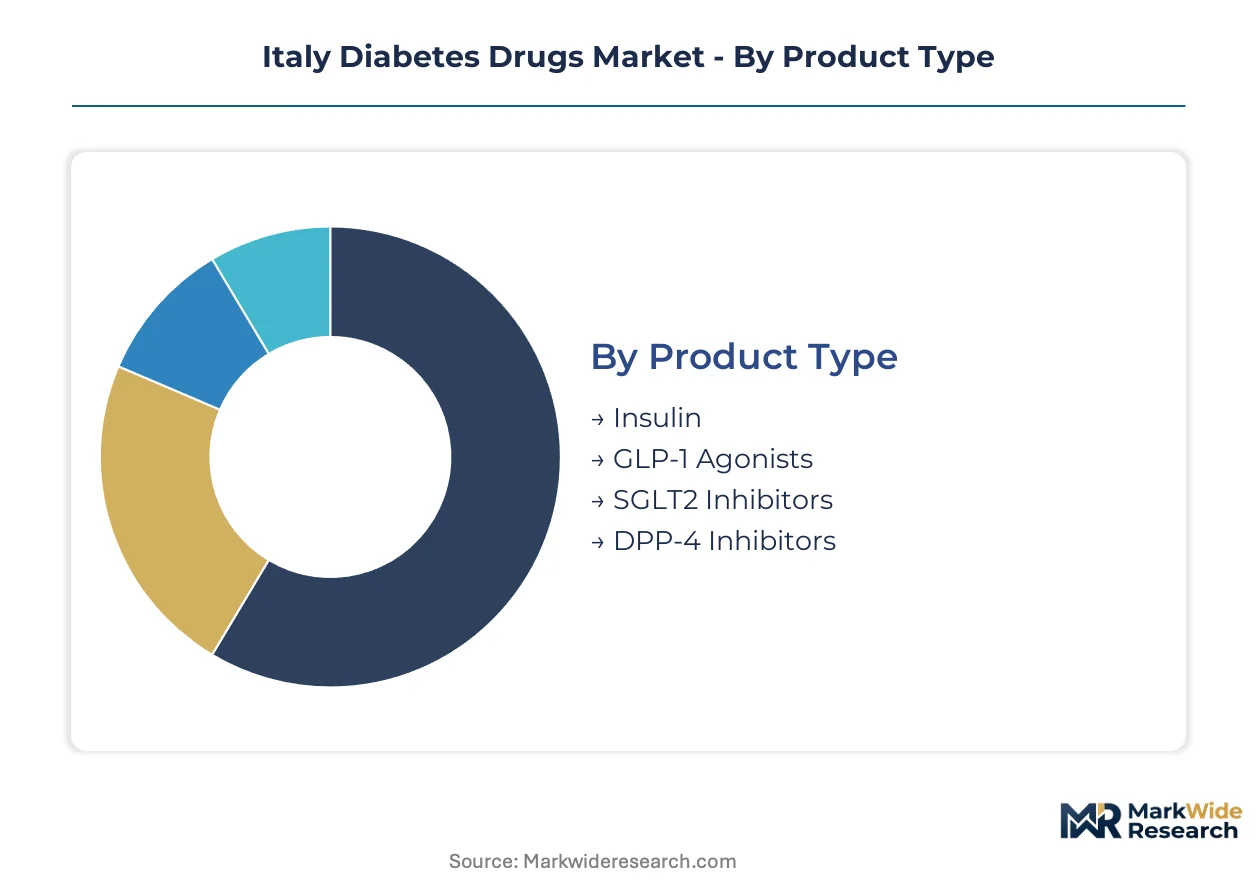
Segmentation of Italy's diabetes drugs market reveals how AIFA reimbursement tiers and regional prescribing authority allocate revenue across therapeutic classes and delivery modes. Understanding these divisions exposes where procurement power concentrates and which access pathways manufacturers must navigate.
Product Type:
Margin pools concentrate in biologic therapies where cardiovascular outcome data commands premium reimbursement tiers from AIFA, while oral generics face compressed pricing corridors.
- Insulin:Long-acting and rapid-acting analog formulations dominate hospital formularies across Lombardy and Veneto. Milan's Policlinico and Rome's Gemelli academic centers drive concentrated demand for next-generation basal insulin with reduced hypoglycemia profiles.
- GLP-1 Agonists:Weekly injectable and oral formulations engineered for incretin pathway modulation now anchor specialist prescribing in northern Italy's integrated care districts. Cardiorenal outcome evidence from recent trials is accelerating AIFA reimbursement approvals for type 2 diabetes with established cardiovascular disease.
- SGLT2 Inhibitors:Oral agents promoting renal glucose extraction with demonstrated heart failure risk reduction.
- DPP-4 Inhibitors:Mature oral enzymatic inhibitors facing generic substitution pressure and margin erosion in retail pharmacy channels.
Insulin holds installed capacity across hospital procurement networks. GLP-1 agonists is rotating up the share rankings as cardiometabolic guidelines expand eligible populations.
Administration Route:
Volume distribution skews heavily toward self-administered modes that align with Italy's pharmacy reimbursement structures and chronic disease management protocols.
- Subcutaneous:Prefilled pen devices and autoinjector systems dominate GLP-1 agonist and insulin delivery. Lombardy's regional health authorities are consolidating procurement around connected pen platforms that capture dosing data for remote monitoring programs.
- Oral:Small-molecule tablets and capsules for SGLT2 inhibitors and DPP-4 inhibitors concentrate demand in retail pharmacy channels where patient self-management is prioritized. Southern Italian regions with lower specialist density rely more heavily on oral-first treatment protocols.
- Intravenous:Hospital-administered insulin infusion for acute hyperglycemic crises and perioperative glycemic control.
- Inhalation:Pulmonary insulin delivery systems with limited formulary penetration due to reimbursement complexity and clinical positioning challenges.
Subcutaneous delivery maintains volume leadership through device ecosystem bundling. Oral administration retains stable share in primary care pathways where specialist access is constrained.
End User:
Customer concentration patterns reflect Italy's dual-track health system where public hospital procurement and private specialist channels operate under divergent access protocols.
- Hospitals:Academic medical centers and regional hub hospitals in Milan, Rome, and Naples initiate advanced therapies and set prescribing patterns that diffuse through specialist referral networks. AIFA centralized procurement for innovative agents concentrates purchasing power in these institutions.
- Clinics:Private endocrinology practices and diabetes centers in northern Italy handle dose optimization and therapy escalation for complex patients.
- Homecare:Nurse-supported insulin initiation and glucose monitoring for elderly populations with mobility limitations.
- Pharmacies:Community dispensing points for oral agents and refill prescriptions where generic substitution pressures are most acute.
Hospitals hold installed capacity as gatekeepers for biologic therapy initiation. Clinics is rotating up the share rankings as integrated care pathways shift follow-up care outside acute settings.
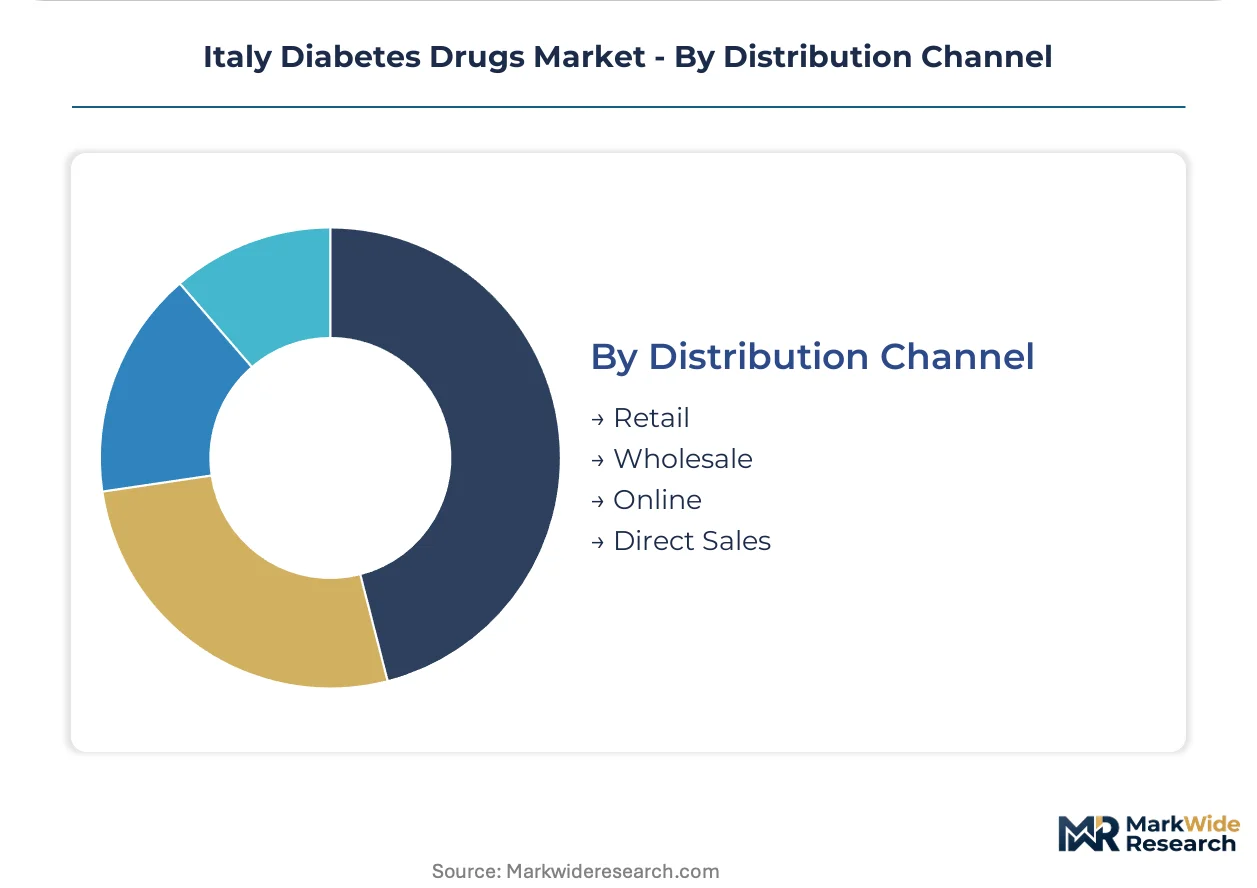
Distribution Channel:
Channel economics diverge sharply between AIFA-regulated wholesale tiers and emerging direct-to-provider models for connected device ecosystems.
- Retail:Community pharmacies across Italy's 20 regions handle the majority of oral agent dispensing under AIFA reimbursement codes. Generic DPP-4 inhibitors flow through this channel at compressed margins.
- Wholesale:Hospital procurement consortia and regional distribution networks manage bulk insulin and GLP-1 agonist supply to public health facilities.
- Online:Telemedicine platforms and digital pharmacies gaining traction for glucose monitoring supplies and device refills.
- Direct Sales:Manufacturer field forces engaging specialist prescribers in academic centers with clinical trial data and real-world evidence packages.
Retail channels hold installed capacity for oral therapy volume. Direct sales is rotating up the share rankings as platform contracts bundle drugs with connected delivery devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AIFA's centralized reimbursement negotiations and regional health authority procurement autonomy create a dual-layer market structure across Italy's 20 regions. The National Health Service's chronic disease protocol reforms are redistributing prescribing authority from acute hospitals to integrated care districts.
Lombardy
Milan's Policlinico and San Raffaele academic centers anchor specialist prescribing for GLP-1 agonists and SGLT2 inhibitors. Lombardy's regional health authority operates the most consolidated formulary procurement in Italy. The concentration of endocrinology fellowship programs in Milan generates diffusion pathways for therapy protocols that migrate southward through specialist networks.
Veneto
Padua and Verona hospital districts exhibit the highest per-capita adoption rates for connected insulin delivery systems. Veneto's regional health authority pioneered outcome-based contracting pilots with glucose monitoring platform vendors. The Veneto formulary committee tightened cardiovascular outcome evidence requirements ahead of AIFA's national guideline updates.
Emilia-Romagna
Bologna's university hospital system maintains extensive real-world evidence registries linking prescription data to cardiovascular outcomes. Emilia-Romagna's pharmaceutical procurement consortium negotiates volume discounts for biologic therapies that influence neighboring regional formularies. The region's diabetes prevalence rates exceed national averages, concentrating demand for advanced glucose-lowering agents.
Lazio
Rome's Policlinico Gemelli and Umberto I hospitals set prescribing patterns for central Italy's specialist referral networks. Lazio's regional health authority faces budget pressure from high-cost biologic therapies, accelerating generic substitution in DPP-4 inhibitor categories. The concentration of national regulatory institutions in Rome facilitates early dialogue between manufacturers and AIFA assessors.
Campania
Naples and surrounding provinces present significant underpenetration for advanced diabetes therapies relative to disease burden. Campania's lower endocrinology specialist density forces reliance on primary care oral-first treatment protocols. Telemedicine platforms are gaining traction to bridge geographic access gaps for insulin initiation and dose optimization services.
Italy Diabetes Drugs Market Competitive Landscape
Player mix skews toward integrated pharmaceutical-device platforms and pure-play biologic manufacturers with cardiovascular outcome trial portfolios. Market structure concentrates around three to four firms with established AIFA reimbursement relationships and northern Italian hospital formulary presence. Strategic archetypes include: platform bundlers combining glucose sensors with drug delivery hardware; outcome-data specialists leveraging cardiorenal trial evidence; and generic oral manufacturers competing on pharmacy channel price. Dominant competitive moves involve M&A for connected device capabilities and strategic partnerships with regional health authorities for real-world evidence collection.
Among the integrated platform specialists, Novo Nordisk and Sanofi occupy positions that exemplify the drug-device bundling archetype. Eli Lilly represents the outcome-data specialist tier with dual GIP/GLP-1 receptor agonist technology. AstraZeneca and Boehringer Ingelheim sit within the SGLT2 inhibitor-focused contingent competing on heart failure risk reduction evidence. Merck and Co. anchors the mature oral therapy segment where generic substitution pressures intensify.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck and Co. |
| Novo Nordisk |
| Janssen Pharmaceuticals |
| Takeda |
| Sanofi |
| Boehringer Ingelheim |
| Pfizer |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Outcome-based contracting pilots with Lombardy and Veneto health authorities lock in multi-year formulary access for connected insulin delivery platforms while capping per-patient expenditure ceilings. These agreements tether AIFA reimbursement rates to real-world glycemic outcomes, compressing margin visibility for manufacturers lacking post-market surveillance infrastructure.
Pricing Analysis
Certification level under EU MDR CE marking creates the primary spread between premium connected pen systems and commodity insulin analogs. AIFA's health technology assessment protocols enforce value-based pricing tiers where cardiovascular outcome trial data commands superior reimbursement rates. Cost compression in oral DPP-4 inhibitor segments is intensifying because generic substitution accelerates through retail pharmacy channels. Hospital procurement consortia exhibit lowest price sensitivity for biologic therapies with demonstrated cardiorenal benefits, while primary care pathways in southern Italy remain most responsive to out-of-pocket cost differentials.
Supply Chain Analysis
Strategic stockpiling of GLP-1 agonist APIs by northern Italian hospital networks buffers against fermentation capacity constraints in South Korea and Japan. Active pharmaceutical ingredient sourcing for biologic diabetes therapies draws from Chinese and Indian fermentation facilities, with peptide synthesis intermediates anchored in Swiss and German chemical manufacturing. Single-source vulnerability concentrates in recombinant DNA production lines for insulin analogs. Distribution runs through AIFA-regulated wholesale tiers for pharmaceutical products, while connected device ecosystems deploy direct-to-hospital logistics managed by manufacturer field operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy diabetes drugs market is recovering from AIFA pricing compression cycles as cardiorenal outcome data expands eligible populations for premium biologic therapies. Cyclical recovery momentum hinges on chronic disease protocol reforms redistributing prescribing authority toward integrated care districts.
For Market Incumbents: Fortify hospital formulary relationships in Lombardy and Veneto through real-world evidence partnerships that lock in platform procurement contracts. Invest in notified body certification capacity ahead of EU MDR software-as-medical-device classification expansions. Counter generic substitution threats in oral DPP-4 segments by accelerating patient migration to SGLT2 inhibitors with heart failure risk reduction profiles. For New Entrants and Emerging Players: Telemedicine-enabled dose optimization services in Campania and Sicily address geographic access gaps where endocrinology specialist scarcity constrains therapy initiation. Southern Italian primary care networks represent the most penetrable channel for algorithm-guided insulin delivery platforms. Partner with regional health authorities on outcome-based contract pilots that bypass established hospital procurement consortia. For Investors and Strategic Acquirers: Connected device manufacturers with EU MDR post-market surveillance infrastructure and Lombardy hospital relationships represent the priority acquisition archetype. Long-term viability over the next decade depends on bundling glucose sensors with drug delivery hardware as academic medical centers displace standalone pharmaceutical procurement. Monitor AIFA's evolving cardiovascular outcome trial evaluation criteria as the inflection signal for reimbursement tier reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Notified body certification filters competitive field to manufacturers with surveillance infrastructure. |
| Hospital System Partnership | Lombardy and Veneto academic centers set prescribing patterns that diffuse through specialist networks. |
| Software Companion Development | Algorithm-guided dosing apps capture dosing data for AIFA outcome-based contract eligibility. |
| Reimbursement Strategy | Cardiorenal trial evidence unlocks premium AIFA tiers ahead of centralized pricing negotiations. |
| Pipeline Diversification | Dual GIP/GLP-1 mechanisms compress therapeutic hierarchy in high-complexity patient populations. |
Research Methodology
Cross-validation between AIFA reimbursement databases and regional health authority procurement records anchors the qualitative findings on formulary access patterns. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation against EMA submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation ensure segmentation integrity across therapeutic classes.
Sensitivity analysis on API supply disruption scenarios and AIFA pricing compression timelines frames the forecast uncertainty bands across the analysis window. The analytical framework models patient population segments, administration route preferences, regional regulatory clusters, and cardiovascular comorbidity prevalence. CAGRs derive from epidemiological trend extrapolation and therapy substitution elasticity estimates. Forecast inputs incorporate AIFA health technology assessment queue dynamics and EU MDR certification timeline distributions.
Forecasts assume regulatory continuity in AIFA centralized pricing negotiations and EU MDR notified body capacity; material policy shifts would require re-modeling. Specific risks that could revise projections include API supply chain disruptions from Asian fermentation facilities and accelerated generic substitution mandates in oral therapy segments. Revision becomes warranted when cardiorenal outcome trial data accumulation crosses thresholds for guideline reclassification by the Italian Society of Diabetology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Pharmaceutical Pellets Market