
 AI Drug Development Market | 2026-2036
AI Drug Development Market Size, Share, and Industry Trends Forecast 2026-2036
AI Drug Development Market Insights
The capital-intensity divergence between AI-native drug developers and traditional pharmaceutical adopters is rotating competitive advantage toward platform-scale infrastructure. Exscientia leverages its end-to-end discovery engine to sustain autonomous molecule design capabilities. NVIDIA Corporation anchors the compute layer, dominating specialized hardware supply for neural network training across therapeutic modalities.
AI drug development encompasses computational platforms that apply machine learning algorithms, neural network architectures, and predictive analytics to molecular design, patient stratification, and safety profiling, typically processing genomic, proteomic, and clinical datasets through cloud-based or on-premise high-performance computing clusters. The primary purpose is compressing discovery timelines while expanding searchable chemical space beyond conventional high-throughput screening limits. Machine learning applications in preclinical studies currently occupy the largest value pool, while natural language processing for biomarker discovery and adverse effect prediction represents the fastest-expanding segment as regulatory agencies demand richer real-world evidence integration. Predictive analytics for lead optimization commands premium pricing due to its direct impact on candidate attrition rates.
The FDA, EMA, and WHO collectively shape market access through divergent validation standards for AI-generated safety and efficacy evidence, with the FDA's emerging framework for model-informed drug development creating compliance complexity for multi-regional sponsors. ISO and IEC standards for AI system risk management increasingly determine procurement eligibility for pharmaceutical buyers. Stakeholders must monitor how regulatory convergence on algorithmic transparency requirements reshapes platform architecture investments and partnership terms with contract research organizations.
Market Dynamics
The AI drug development market is undergoing structural compression as regulatory agencies demand algorithmic transparency while compute infrastructure concentrates among hyperscale cloud providers, forcing sponsors to choose between proprietary platform investments and outsourced model development partnerships.
Growth Catalysts
- Model-Informed Drug Development Framework:The FDA's evolving guidance creates validation pathways for AI-generated safety evidence, reducing regulatory uncertainty for sponsors submitting machine learning-derived pharmacokinetic models.
- Genomic Data Proliferation:Biobanks and multi-omics repositories in the United States are expanding training datasets for target identification algorithms, accelerating hit-to-lead timelines for rare disease programs.
- Contract Research Organization Integration:Computational biology platforms are embedding directly into CRO workflows, creating captive demand for predictive toxicology and patient stratification tools.
Market Restraints
- GPU Supply Concentration:Specialized neural network training hardware remains concentrated among a limited set of foundry-dependent suppliers, creating procurement bottlenecks for mid-cap biotech firms scaling model complexity.
- Validation Cost Escalation:The ISO/IEC 23053 standard for AI system risk management imposes documentation burdens that disproportionately burden development-stage companies without existing quality management infrastructure.
- Biological Complexity Ceiling:Current deep learning architectures face fundamental limitations modeling protein folding dynamics in membrane-bound targets, constraining applicability across certain therapeutic modalities.
Strategic Opportunities
- India's CDSCO Streamlining:The country's national pharmaceutical regulator is piloting accelerated review pathways for AI-enabled drug discovery tools, creating first-mover advantages for platform developers establishing local validation partnerships.
- Federated Learning Architectures:Privacy-preserving computation across hospital networks without centralizing patient data is opening real-world evidence integration previously blocked by HIPAA constraints.
- Quantum-Classical Hybrid Simulation:Convergence of quantum computing with conventional neural networks promises to expand searchable chemical space for molecular dynamics simulations beyond current classical limits.
Industry Challenges
- Computational Biology Talent Scarcity:The intersection of medicinal chemistry expertise and machine learning engineering remains critically underpopulated, forcing sponsors into bidding wars for hybrid skill profiles.
- Legacy System Integration Friction:Electronic laboratory information management systems at established pharmaceutical companies resist API connectivity with cloud-based AI platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Drug Development Market |
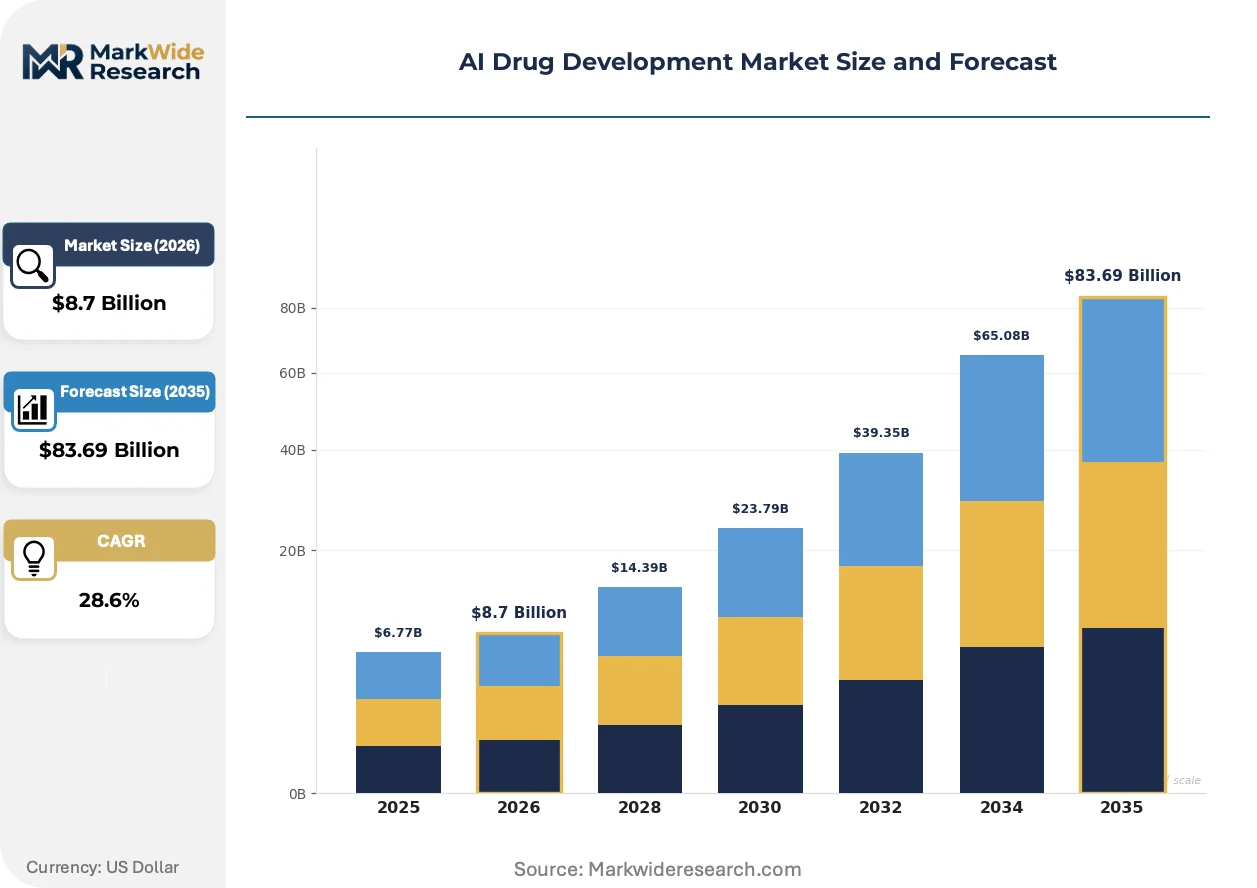
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $83.69 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Preclinical Studies, Clinical Trials, Drug Repurposing, Biomarker Discovery Technology: Machine Learning, Natural Language Processing, Neural Networks, Predictive Analytics End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Academic Organizations Use Case: Target Identification, Lead Optimization, Adverse Effect Prediction, Drug Formulation |
| Companies Covered | Exscientia, Insilico Medicine, Atomwise, Recursion Pharmaceuticals, BenevolentAI, Schrödinger, NVIDIA Corporation, Owkin, Valo Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Drug Development Market Trends and Innovations
Foundation models trained on molecular representations are actively displacing fragment-based screening workflows, while regulatory pressure on algorithmic explainability is reshaping platform architecture investments across the discovery value chain.
Generative chemistry platforms utilizing diffusion models and transformer architectures are bifurcating the hit identification market into autonomous molecule design services and human-in-the-loop optimization partnerships. Mid-cap biotech firms are adopting these tools at accelerated pace, compressing traditional medicinal chemistry cycles from months to weeks. The structural consequence is a widening capability gap between AI-native sponsors with end-to-end platforms and traditional adopters dependent on external software licenses.
The EU AI Act's risk classification framework for medical applications is imposing conformity assessment requirements on drug discovery algorithms processing patient data, forcing platform developers to rearchitect data governance systems. Industrial consequence includes mandatory documentation of training data provenance and model drift monitoring protocols. Sponsors targeting European market access are responding by establishing dedicated algorithmic impact assessment functions within regulatory affairs departments.
Biopharma procurement departments are unbundling discovery platform contracts from full-service research agreements, creating direct vendor relationships with specialized AI tool providers previously accessed through CRO intermediaries. This disintermediation is most visible in the United States, where venture-backed biotechs are negotiating standalone licenses for target identification and lead optimization modules. The shift enables faster technology refresh cycles but complicates vendor management and data integration responsibilities.
AI Drug Development Market Segmentation
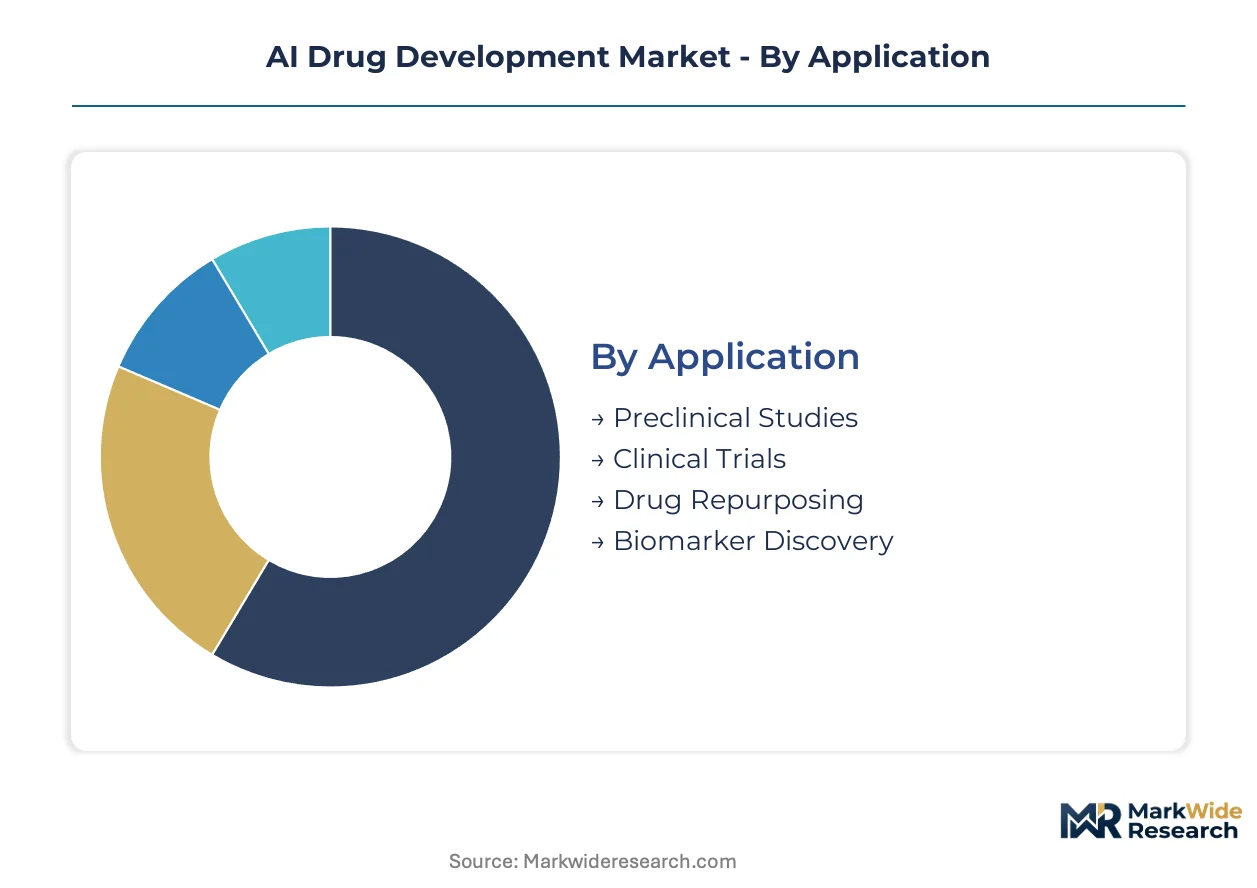
Segmentation in AI drug development reveals distinct margin architectures across the discovery value chain. Platform developers optimize pricing and partnership terms by aligning computational capabilities with specific therapeutic workflows and regulatory submission requirements.
Application:
Margin pools concentrate in preclinical validation workflows where attrition reduction delivers measurable ROI to sponsors.
- Preclinical Studies:Computational toxicology and pharmacokinetic modeling platforms process multi-omics datasets to predict safety profiles before IND submission. Pharmaceutical sponsors in the United States are expanding contracts for AI-driven toxicity prediction to compress GLP study timelines.
- Clinical Trials:Patient stratification algorithms and adaptive trial design tools optimize enrollment and endpoint selection. Demand is accelerating from mid-cap biotech firms seeking to rescue underpowered Phase II programs through synthetic control arm generation.
- Drug Repurposing:Knowledge graph traversal identifies approved compounds with mechanistic relevance to new indications.
- Biomarker Discovery:Multi-modal data fusion platforms extract signature patterns from genomic and imaging repositories.
The dominant share belongs to Preclinical Studies, while Biomarker Discovery is gaining share fastest through real-world evidence integration mandates.
Technology:
Cost tiers separate enterprise-grade neural network training infrastructure from deployable predictive modules.
- Machine Learning:Supervised and unsupervised algorithms for molecular property prediction and virtual screening constitute the foundational layer. Biotech procurement teams in the United States prioritize interpretable models for regulatory submission packages.
- Natural Language Processing:Transformer architectures extract relationships from biomedical literature and clinical narratives. FDA guidance on real-world evidence is driving sponsor investment in NLP pipelines for adverse event signal detection.
- Neural Networks:Deep learning architectures for protein structure prediction and generative chemistry.
- Predictive Analytics:Statistical and Bayesian methods for clinical outcome forecasting and trial simulation.
Machine Learning retains the largest installed base, though Natural Language Processing is climbing the fastest as literature mining becomes essential for target validation.
End User:
Volume concentrates among organizations with captive data assets and regulatory submission experience.
- Pharmaceutical Companies:Integrated discovery divisions deploy end-to-end platforms spanning target identification through candidate nomination. Top-tier sponsors maintain proprietary training datasets from decades of screening campaigns.
- Biotech Firms:Venture-backed developers license specialized modules for hit-to-lead acceleration without platform infrastructure investment. United States-based startups represent the fastest-expanding customer segment for outsourced AI discovery services.
- Research Institutions:Academic centers with biobank access develop algorithms for publication and spinout formation.
- Academic Organizations:University consortia train foundational models on public molecular databases.
Pharmaceutical Companies command the deepest platform commitments, while Biotech Firms are expanding contract value most rapidly.
Use Case:
Application maturity varies sharply between established workflows and emerging regulatory pathways.
- Target Identification:Genome-wide association study integration and druggability scoring algorithms prioritize therapeutic hypotheses. Research institutions in the United States are federating biobank access to expand training data for rare disease target discovery.
- Lead Optimization:Generative chemistry and multi-parameter optimization tools refine potency, selectivity, and ADMET properties simultaneously. CRO integration is accelerating adoption among sponsors without internal medicinal chemistry capacity.
- Adverse Effect Prediction:Toxicophore recognition and organ-specific liability models flag safety risks preclinically.
- Drug Formulation:Physics-informed neural networks predict solubility and stability profiles for delivery system design.
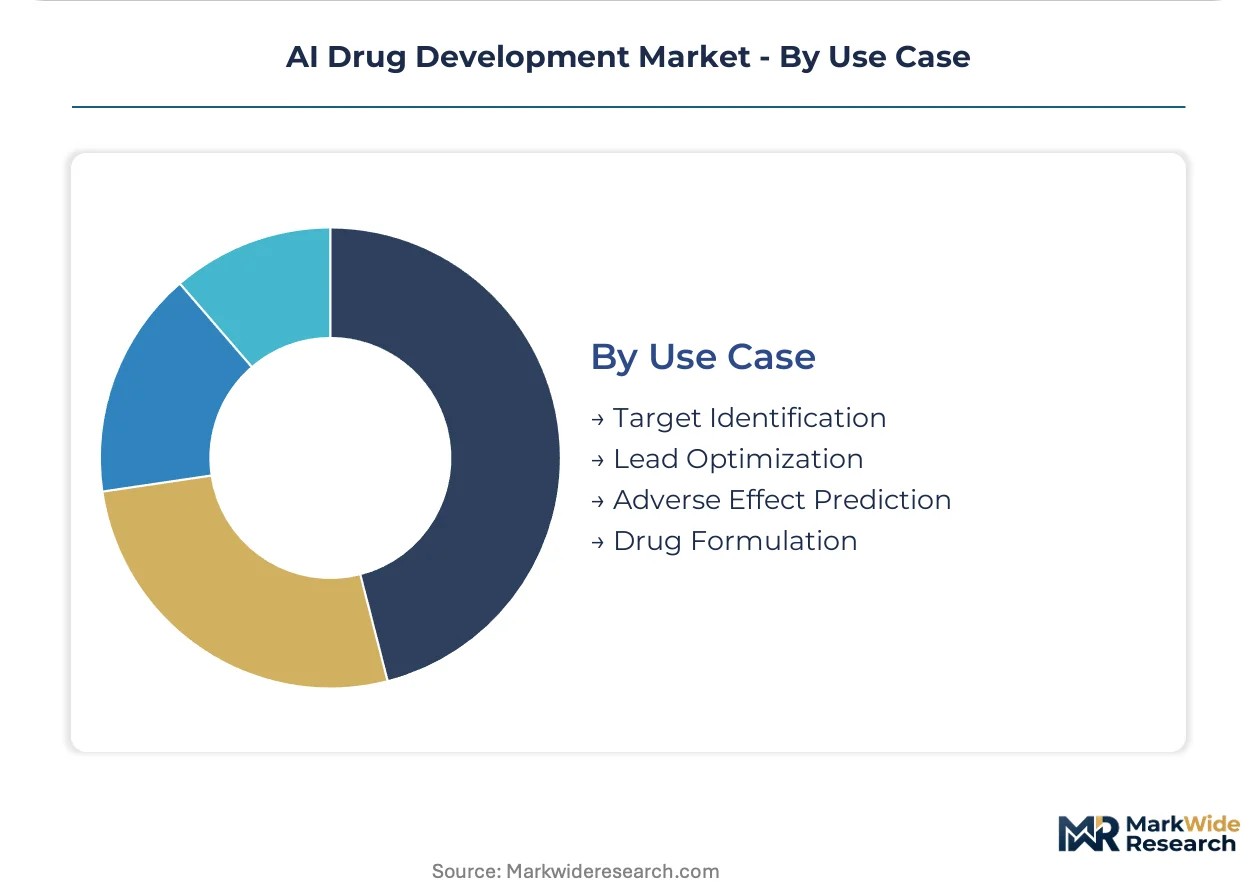
Lead Optimization holds the dominant position, while Adverse Effect Prediction is expanding most quickly under FDA pressure for richer safety evidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity for AI discovery platforms, while emerging biotech clusters in India and Southeast Asia face acute procurement constraints from GPU supply bottlenecks and currency volatility.
United States
Venture funding for computational biology platforms concentrates in Cambridge, San Francisco, and San Diego, where biotech sponsors prioritize end-to-end discovery engines over modular tool licenses. The FDA's model-informed drug development framework reduces regulatory uncertainty for machine learning-derived pharmacokinetic submissions. Greater Boston anchors the densest cluster of AI-native drug developers, with Kendall Square hosting multiple autonomous molecule design operations.
United Kingdom
London and Oxfordshire host specialized natural language processing firms extracting biomedical relationships from literature corpora. The Medicines and Healthcare products Regulatory Agency's alignment with FDA validation standards streamlines multi-regional submission pathways for UK-developed algorithms. The Golden Triangle research corridor federates biobank access to expand training datasets for rare disease target discovery.
China
Domestic pharmaceutical sponsors accelerate procurement of predictive toxicology modules to compress IND timelines amid competitive pressure from biosimilar developers. The National Medical Products Administration pilots accelerated review pathways for AI-enabled drug discovery tools through its Hainan Boao medical zone. Yangtze River Delta cities including Shanghai and Suzhou concentrate contract research organizations embedding computational biology into traditional workflows.
Switzerland
Basel-based pharmaceutical headquarters maintain proprietary training datasets from decades of screening campaigns, limiting external platform adoption to specialized lead optimization modules. Swissmedic's evolving guidance on algorithmic transparency requirements shapes procurement specifications for European market access. The Basel-Zurich corridor hosts precision medicine consortia federating hospital network data for biomarker discovery.
India
Hyderabad and Bangalore biotech clusters license outsourced AI discovery services to compress hit-to-lead timelines without captive infrastructure investment. The Central Drugs Standard Control Organization's pilot accelerated review pathways create first-mover advantages for platform developers establishing local validation partnerships. Genome Valley in Telangana anchors contract research organizations integrating computational biology modules into traditional medicinal chemistry workflows.
AI Drug Development Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in AI drug development, with platform-scale infrastructure separating autonomous molecule designers from modular tool vendors. The upper tier commands premium pricing through end-to-end discovery engines compressing target identification through candidate nomination. Three archetypes populate the competitive landscape: AI-native biotechs with captive therapeutic pipelines, computational platform vendors licensing software to pharmaceutical sponsors, and hardware suppliers anchoring the neural network training layer. Consolidation pressure intensifies through strategic partnerships between biotech sponsors and cloud hyperscalers, while vertical integration into proprietary training datasets emerges as a defensive maneuver.
Within the AI-native biotech tier, Exscientia and Recursion Pharmaceuticals exemplify platform-scale infrastructure investments, each occupying positions spanning autonomous molecule design through clinical candidate nomination. NVIDIA Corporation anchors the compute layer, with its specialized hardware supply dominating neural network training across therapeutic modalities. Among specialized software vendors, Schrödinger and BenevolentAI represent distinct archetypes—physics-based simulation engines versus knowledge graph traversal platforms—each capturing procurement budgets from distinct pharmaceutical sponsor segments based on internal medicinal chemistry capacity.
| Leading Market Players |
|---|
| Exscientia |
| Insilico Medicine |
| Atomwise |
| Recursion Pharmaceuticals |
| BenevolentAI |
| Schrödinger |
| NVIDIA Corporation |
| Owkin |
| Valo Health |
| Others |
Pricing and Supply Chain Analysis
GPU cluster utilization rates above 80% at hyperscale cloud facilities in the United States create scale economies that compress unit compute costs for neural network training while simultaneously concentrating supply leverage among NVIDIA and a handful of foundry-dependent hardware suppliers, establishing price floors that mid-cap biotech firms cannot negotiate away regardless of contract volume.
Pricing Analysis
Extended service contracts for model retraining and regulatory validation support generate lifetime value multiples exceeding initial platform licensing fees. Pricing stratifies across enterprise-grade end-to-end discovery engines, modular tool licenses for specific therapeutic workflows, and consumption-based API access for intermittent users. Cost compression in the mid-market tier is intensifying because venture-backed biotech sponsors are unbundling full-service CRO agreements to negotiate direct relationships with specialized AI vendors. Biotech firms with limited quality management infrastructure exhibit the highest price sensitivity, while top-tier pharmaceutical companies with proprietary training datasets demonstrate inelastic demand for premium interpretability features.
Supply Chain Analysis
Lead times for A100 and H100 GPU allocations currently stretch 26-40 weeks, forcing platform developers to pre-commit capital years ahead of revenue recognition. Neural network training hardware concentrates in Taiwan, South Korea, and the United States, with advanced packaging and memory integration tethered to TSMC's N4 and N3 process nodes. The supply chain draws from specialized foundry capacity, high-bandwidth memory from SK Hynix and Micron, and substrate materials from Japanese suppliers. Single-source vulnerability at the leading-edge node level creates procurement risk for any sponsor scaling model complexity beyond commodity cloud instances. Distribution runs through hyperscale cloud providers and direct OEM relationships, with pharmaceutical buyers increasingly favoring reserved instance contracts over on-demand consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the AI drug development value chain creates entry niches as regulatory agencies demand algorithmic transparency while biotech sponsors disintermediate traditional CRO relationships, splintering procurement authority and opening specialized vendor relationships previously bundled within full-service contracts.
For Market Incumbents: Shield proprietary training datasets from competitive replication by federating biobank access through exclusive partnerships with United States research institutions. Consolidate position by acquiring specialized natural language processing firms with FDA-validated literature mining pipelines, before emerging entrants can anchor regulatory submission workflows around open-source foundation models. The priority defensive lever rests on backward integration into captive genomic data assets that cannot be replicated through public repositories.
For New Entrants and Emerging Players: Federated learning infrastructure for privacy-preserving hospital network integration represents the most significant service-layer gap, as incumbents remain architecturally committed to centralized data governance models that violate HIPAA constraints on patient data mobility. Target mid-cap biotech sponsors in the United States seeking to rescue underpowered Phase II programs through synthetic control arm generation without infrastructure investment. The penetrable entry point sits in adaptive trial design tools with explainable model architectures that satisfy emerging FDA guidance on algorithmic transparency.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform developers with demonstrated regulatory submission experience over pure-play algorithm vendors lacking validation partnerships with the FDA or EMA. Long-term viability hinges on captive therapeutic pipelines generating proof-of-concept data rather than software licensing alone. Acquisition targets should display end-to-end discovery engines spanning target identification through candidate nomination. The critical inflection signal to monitor is the first FDA approval of an AI-designed molecule, which would validate platform economics and trigger consolidation toward proven regulatory navigators.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Partnership | FDA model-informed drug development framework participation reduces submission risk for machine learning-derived pharmacokinetic evidence. |
| Federated Learning Architecture Deployment | HIPAA-compliant hospital network integration unlocks real-world evidence pipelines previously blocked by patient data centralization restrictions. |
| GPU Supply Agreement Structuring | Reserved instance contracts with hyperscale cloud providers secure neural network training capacity amid foundry allocation constraints. |
| Biobank Access Federation | Exclusive partnerships with United States research institutions create defensible training data moats for rare disease target discovery. |
| Algorithmic Impact Assessment Function | Dedicated regulatory affairs capabilities address EU AI Act conformity requirements for medical application risk classification. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, computational biology platform engineers, and biotech procurement managers and refined through secondary validation against FDA guidance documents, EMA scientific advice outcomes, ClinicalTrials.gov protocol registrations, and venture financing databases. Bottom-up triangulation across sponsor-reported platform adoption timelines and top-down reconciliation against cloud hyperscaler healthcare vertical revenue disclosures anchored market sizing.
Variance decomposition across technology segments, application workflows, and end-user archetypes structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level adoption curves weighted by regulatory validation milestones and biotech funding cycle timing. Modeled dimensions encompassed therapeutic modality, development stage, deployment architecture, and regional regulatory cluster. Forecast inputs incorporated GPU supply allocation forecasts from foundry utilization reports and FDA guidance publication schedules.
Forecasts assume regulatory continuity in FDA model-informed drug development frameworks and EU AI Act implementation timelines; material policy shifts in algorithmic transparency requirements or export controls on specialized compute hardware would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
HPV Vaccines Market