
 Anti-Counterfeit Printing Ink Market | 2026-2036
Anti-Counterfeit Printing Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeit Printing Ink Market Analysis
Software-defined color verification and cloud-linked subscription authentication is repositioning how brand owners procure security ink systems. SICPA SA leverages its vault-to-print traceability architecture to sustain premium positioning in pharmaceutical serialization. Sun Chemical Corp anchors North American supply through backward integration into pigment synthesis and captive resin production.
Anti-counterfeit printing ink denotes a class of formulated coatings incorporating taggants, optically variable pigments, or covert luminescent markers detectable under specific wavelengths, manufactured via controlled dispersion of functional particles in resin vehicles at viscosities calibrated to substrate and print method. These inks serve the primary commercial purpose of enabling brand owners, tax authorities, and supply chain operators to verify product authenticity without specialized laboratory infrastructure. UV-curable formulations command the widest margin pool among product types due to instant polymerization enabling inline inspection and reduced solvent handling overhead; flexographic printing technology leads volume throughput for flexible packaging applications while digital printing represents the fastest-expanding installation base for variable-data serialization. Security printing and brand protection applications concentrate value capture as regulatory serialization deadlines force pharmaceutical and consumer goods manufacturers to upgrade legacy equipment.
FDA drug supply chain security mandates and the EU Falsified Medicines Directive frame compliance-driven demand in Western markets, while China's NMPA track-and-trace standards and India's CDSCO packaging authentication rules shape procurement specifications across Asia-Pacific manufacturing corridors. ISO 12931 performance criteria for authentication solutions establish baseline test protocols that determine market access for ink suppliers bidding on government and institutional contracts. Stakeholders must monitor divergence between regional serialization data formats and ink-substrate compatibility standards as compliance timelines compress implementation windows.
Market Dynamics
Serialization mandates across pharmaceutical supply chains are compressing implementation timelines, forcing ink suppliers to pre-validate formulations against evolving track-and-trace data standards before contract awards.
Growth Catalysts
- FDA Drug Supply Chain Security Act:US pharmaceutical manufacturers must achieve unit-level traceability, driving contract demand for UV-curable security inks with embedded verification codes.
- Flexible packaging conversion:Food and beverage brands in India and Brazil are adopting holographic hot-stamp inks to combat grey-market diversion of premium products.
- Digital printheads:Piezoelectric inkjet systems now handle variable-data serialization at pharmaceutical line speeds, expanding addressable applications beyond traditional analog methods.
Market Restraints
- Photoinitiator supply concentration:German and Chinese chemical producers control 70% of UV-curable ink raw material output, exposing formulators to input volatility.
- Substrate compatibility gaps:Security inks formulated for coated paper often fail adhesion testing on recycled polyethylene, limiting circular packaging adoption.
- REACH authorization delays:ECHA scrutiny of chromium-based pigments is extending reformulation cycles for European security printers.
Strategic Opportunities
- Indonesian tobacco excise:The country's tax authority is expanding holographic banderole programs, creating tender opportunities for multi-layer optical variable ink systems.
- Blockchain-ink convergence:Physical authentication markers paired with distributed ledger verification are opening subscription-based recurring revenue models.
- EU Green Deal alignment:Bio-based resin vehicles and water-borne security formulations qualify for preferential procurement scoring in public sector document contracts.
Industry Challenges
- Colorimetrist talent scarcity:Formulation chemists capable of balancing security function with printability across flexographic and gravure systems command premium compensation.
- Multi-standard validation:Ink suppliers must maintain parallel testing protocols for ISO 12931, EU FMD, and FDA DSCSA compliance, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeit Printing Ink Market |
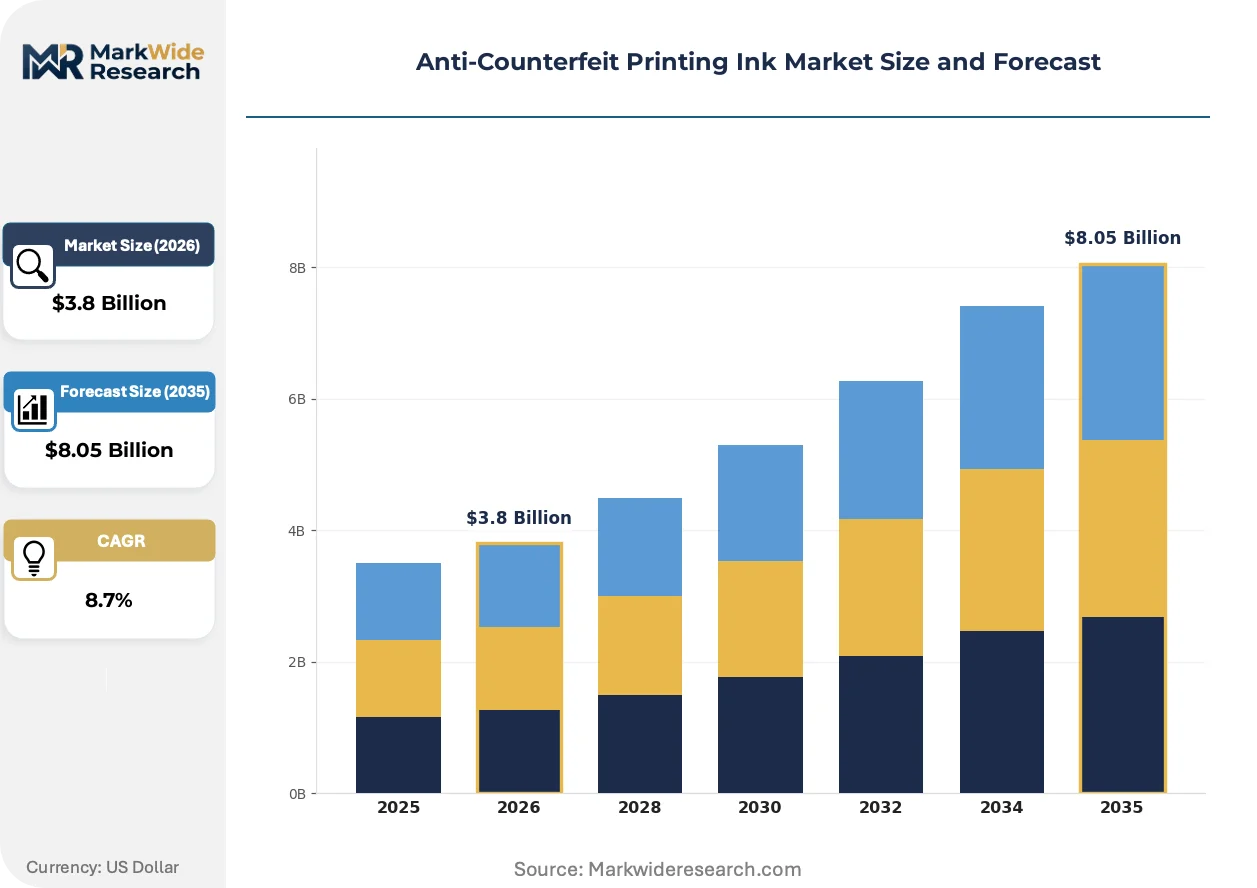
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Ink, Solvent-Based Ink, UV-Curable Ink, Inks with Special Effects Technology: Digital Printing, Flexographic Printing, Lithographic Printing, Screen Printing End User: Consumer Goods, Pharmaceuticals, Electronics, Packaging Industries Application: Labeling, Security Printing, Packaging, Brand Protection |
| Companies Covered | Avery Dennison Corporation, Siegwerk Druckfarben, SICPA SA, Tokyo Printing Ink, DIC Corporation, Sun Chemical Corp, Flint Group, Hubergroup, INX International Ink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeit Printing Ink Market Emerging Trajectories
Authentication technology is bifurcating between covert machine-readable markers and overt consumer-verifiable features, with cloud-linked verification architectures reshaping how security value is delivered and priced.
Machine-readable nanoparticle taggants is consolidating supplier power among integrated chemical producers capable of synthesizing, functionalizing, and dispersing proprietary markers at scale. Pharmaceutical contract packagers in Germany and Switzerland are specifying taggant-embedded UV inks for inline spectroscopic verification. This consolidation is compressing margins for regional ink blenders lacking captive nanoparticle production.
REACH restrictions on perfluorinated compounds are forcing reformulation of water-repellent document security coatings. Security printers serving French and German government credential contracts are accelerating qualification of silicone-based alternatives. Banknote substrate producers are absorbing extended validation timelines as central banks delay specification updates pending chemical safety assessments.
Brand owners are unbundling hardware ownership from authentication service subscriptions, treating security ink systems as operational expenditures rather than capital investments. Consumer goods manufacturers in Mexico and Turkey are piloting per-unit verification fees tied to cloud authentication queries. This model shift is most visible in wine and spirits packaging, where variable-data inkjet serialization enables lot-specific traceability without press retrofits.
Anti-Counterfeit Printing Ink Market Segmentation
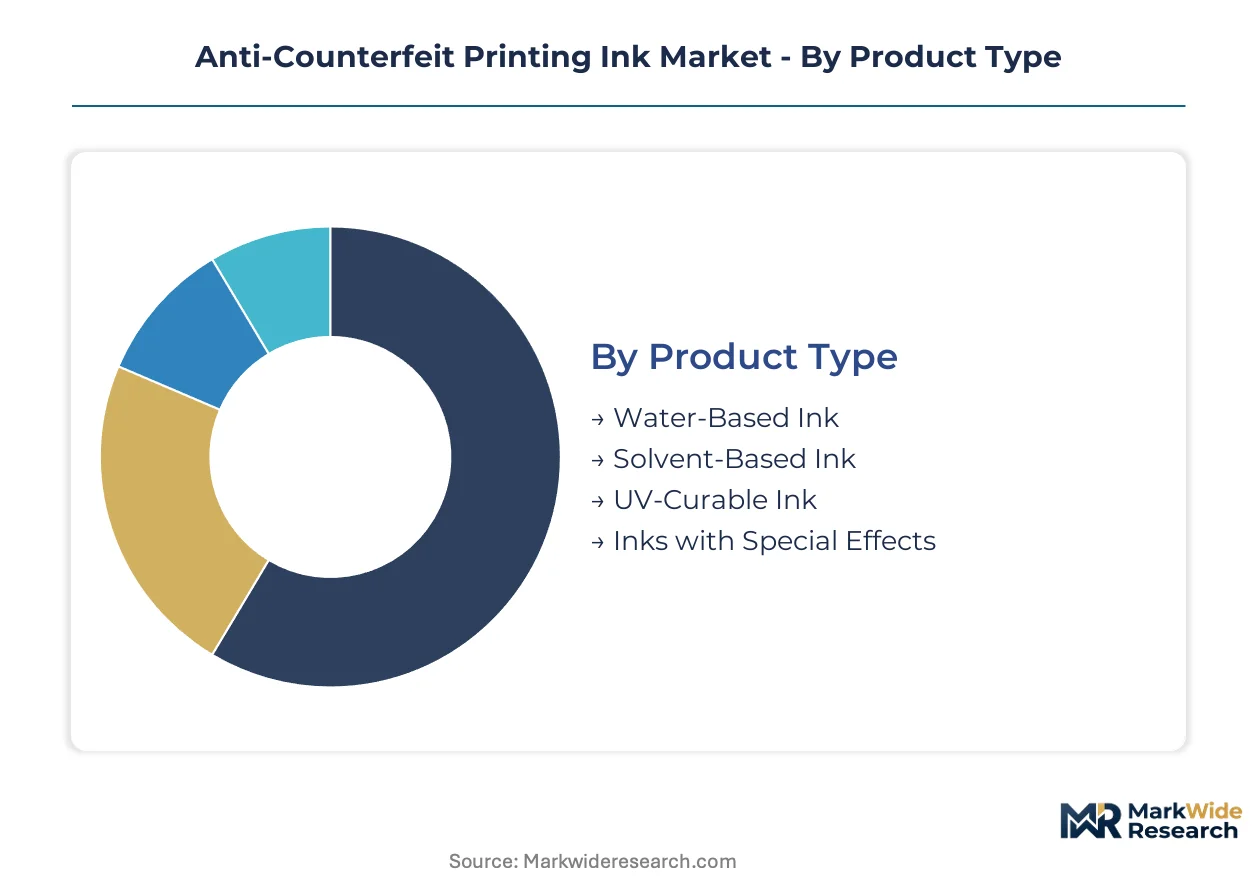
Anti-counterfeit printing ink procurement varies sharply by substrate compatibility, line speed requirements, and regulatory compliance tier. Formulation chemistry and print technology selection determine both upfront capital deployment and recurring authentication service economics.
Product Type:
Capital intensity peaks with UV-curable systems requiring inline photopolymerization units and nitrogen inerting infrastructure.
- UV-Curable Ink:Photoinitiator-loaded acrylate oligomers polymerize instantly under UV-A/UV-C exposure, enabling 600+ fpm pharmaceutical line speeds. US FDA DSCSA-mandated serialization lines in New Jersey and Illinois concentrate contract demand for these formulations. Premium margin pools reflect reduced solvent handling and elimination of thermal drying tunnels.
- Solvent-Based Ink:Volatile organic solvent vehicles dissolve nitrocellulose and polyamide resins for aggressive adhesion to non-porous films. India's CDSCO packaging authentication rules drive uptake across Mumbai and Hyderabad pharmaceutical contract manufacturing clusters. ECHA REACH volatility in photoinitiator feedstocks is redirecting some specification volume here.
- Water-Based Ink:Acrylic emulsion vehicles with lower VOC profiles suit porous substrates and sustainability-scored public tenders.
- Inks with Special Effects:Optically variable pigments and thermochromic leuco dyes add overt consumer verification layers.
Most installed capacity flows through solvent-based formulations. Expansion is steepest in UV-curable systems.
Technology:
Throughput economics and variable-data capability split procurement between high-volume analog and agile digital platforms.
- Flexographic Printing:Anilox roller metering of low-viscosity inks achieves 1000+ fpm on flexible packaging webs. Brazilian ANVISA pharmaceutical serialization deadlines concentrate retrofit demand in São Paulo and Rio de Janeiro. Plate costs and setup waste favor long-run security jobs.
- Digital Printing:Piezoelectric drop-on-demand heads jet variable codes, serial numbers, and encrypted markers without physical masters. German pharmaceutical contract packagers in Baden-Württemberg specify these systems for lot-specific traceability. Per-unit authentication service subscriptions are emerging here.
- Lithographic Printing:Planographic offset excels at fine-line security features on coated paper stocks for tax stamps and high-value documents.
- Screen Printing:Thick-film deposition of metallic and tactile varnishes suits heavy-substrate brand protection applications.
Flexographic lines carry the heaviest installed base. Digital installations are climbing the fastest.
End User:
Regulatory compliance timelines and diversion risk exposure determine authentication spend intensity across verticals.
- Pharmaceuticals:Unit-level serialization mandates in the US, EU, China, and India force continuous ink formulation validation against evolving data standards. Swissmedic and TGA alignment pressures extend qualification protocols for suppliers serving multi-market manufacturers.
- Consumer Goods:Premium spirits and cosmetics brands deploy holographic and taggant-embedded inks to combat grey-market arbitrage. Turkish and Mexican pilots of per-unit verification fees concentrate here.
- Electronics:Component-level authentication markers combat counterfeiting in semiconductor and battery supply chains.
- Packaging Industries:Converter-forward security integration serves food, beverage, and industrial brands lacking in-house print capacity.
Pharmaceutical compliance budgets anchor category revenue. Consumer goods authentication services are expanding most quickly.
Application:
Functional requirements span covert machine-readable verification through overt consumer engagement features.
- Security Printing:Central bank notes, tax stamps, and government credentials demand multi-layer authentication with forensic-grade traceability. Indonesian tobacco excise expansion is tendering multi-layer optical variable systems.
- Brand Protection:Consumer-facing verification via smartphone-readable markers or color-shifting pigments. Cloud-linked query architectures are unbundling hardware ownership from recurring authentication revenues.
- Labeling:Pressure-sensitive and in-mold labels carry serialized codes for supply chain track-and-trace.
- Packaging:Direct-to-substrate security printing on primary and secondary containers.
Security printing commands the highest specification rigor. Brand protection applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States serialization mandates outpace German pharmaceutical line upgrades by roughly eighteen months, while India's regulatory acceleration now rivals China's implementation velocity. National compliance calendars and industrial cluster specialization determine where ink suppliers concentrate validation resources.
United States
FDA Drug Supply Chain Security Act deadlines compress implementation windows for contract packagers. New Jersey and Illinois pharmaceutical corridors dominate UV-curable ink procurement for high-speed serialization lines. Sustained FDA enforcement activity validates formulation investments by domestic security ink specialists.
Germany
EMA serialization alignment pressures extend qualification protocols for multi-market manufacturers. Baden-Württemberg contract packaging clusters specify digital inkjet systems for lot-specific traceability. ECHA REACH scrutiny of chromium-based pigments forces extended reformulation cycles among security printers serving government credential contracts.
China
NMPA track-and-trace standards reshape procurement specifications across pharmaceutical manufacturing hubs. Yangtze River Delta production corridors concentrate demand for authentication-grade ink systems. MIIT industrial policy accelerates domestic supply chain localization for security formulation feedstocks.
India
CDSCO packaging authentication rules drive uptake across Mumbai and Hyderabad contract manufacturing clusters. Domestic pharmaceutical exporters face Swissmedic and TGA alignment pressures extending validation overhead. Government PLI scheme incentives support local ink formulation capacity expansion.
Brazil
ANVISA pharmaceutical serialization deadlines concentrate retrofit demand in São Paulo and Rio de Janeiro flexographic installations. Food and beverage brands adopt holographic security features to combat grey-market diversion of premium products. Grey-market arbitrage in consumer goods sustains authentication service demand.
Anti-Counterfeit Printing Ink Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium authentication services consolidating around integrated chemical producers while regional blenders compete on formulation flexibility. Three archetypes dominate: vault-to-print traceability architects, backward-integrated pigment specialists, and agile regional formulators. Capacity expansion and technology licensing represent the primary competitive vectors as compliance timelines compress.
Among Swiss-anchored authentication architects, SICPA SA occupies a position exemplifying vault-to-print traceability integration. Sun Chemical Corp represents North American supply security through captive resin production. Siegwerk Druckfarben exemplifies European formulation breadth across solvent-based and UV-curable portfolios. These three anchors illustrate how geographic origin and structural integration shape competitive positioning.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Siegwerk Druckfarben |
| SICPA SA |
| Tokyo Printing Ink |
| DIC Corporation |
| Sun Chemical Corp |
| Flint Group |
| Hubergroup |
| INX International Ink |
| Others |
Supply Flow & Price Mechanics
FDA DSCSA-mandated serialization upgrades in New Jersey and Illinois pharmaceutical corridors are forcing UV-curable ink buyers to absorb premium pricing for pre-validated formulations, compelling suppliers to secure captive photoinitiator supply or surrender margin to German and Chinese chemical producers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for authentication-grade ink systems. Three-tier pricing structure across premium, standard, and economy levels separates vault-to-print traceability architects from regional blenders lacking nanoparticle synthesis. Cost compression in economy-tier solvent-based formulations is intensifying because Indian CDSCO compliance deadlines concentrate contract awards among qualified suppliers. Pharmaceutical packagers exhibit lowest price sensitivity due to regulatory non-compliance penalties, while consumer goods brands in Brazil and Mexico drive hardest bargain on per-unit verification fees.
Supply Chain Analysis
ISO 12931 certification gating restricts market access to ink suppliers capable of maintaining parallel validation protocols across FDA, EMA, and NMPA jurisdictions. Manufacturing concentrates in Germany, Switzerland, and China, with photoinitiator feedstocks drawing from German and Chinese chemical producers controlling seventy percent of UV-curable raw material output. Formulation depends on specialty acrylate oligomers, optically variable pigments, and functionalized nanoparticle taggants. Single-source vulnerability in photoinitiator supply exposes formulators to input volatility. Distribution runs through converter-forward security integration and direct pharmaceutical line supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH reformulation cycles in Europe lag FDA enforcement intensity in the United States by roughly eighteen months, creating cost and qualification windows for agile suppliers.
For Market Incumbents: Lock in multi-year supply agreements with German and Chinese photoinitiator producers before capacity tightens further. Deepen backward integration into pigment synthesis to defend margin position against regional blenders gaining share through formulation flexibility. SICPA SA's vault-to-print architecture demonstrates how traceability integration sustains premium positioning against substitute authentication technologies. For New Entrants and Emerging Players: CDSCO packaging authentication rules in India open a window for domestic formulation capacity serving Mumbai and Hyderabad export corridors. Target water-based security ink qualification for EU Green Deal-scored public tenders where incumbents face extended REACH reformulation cycles. Pursue per-unit verification fee pilots with Turkish and Mexican consumer goods brands as cloud-linked subscription entry point. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap regional formulators possessing ISO 12931 validation infrastructure and untapped nanoparticle synthesis capability. Five-to-ten year viability favors suppliers consolidating authentication-grade ink production across pharmaceutical serialization and government credential verticals. Watch FDA enforcement activity against contract packagers missing DSCSA deadlines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Captive resin production insulates Sun Chemical Corp from German and Chinese chemical producer volatility. |
| Cloud-Linked Verification Platform Launch | Subscription authentication queries enable per-unit fee models with Mexican spirits brands. |
| Water-Based Formulation Qualification | Bio-based resin vehicles qualify Siegwerk Druckfarben for EU Green Deal preferential procurement scoring. |
| Digital Inkjet System Partnership | Piezoelectric drop-on-demand integration serves Baden-Württemberg pharmaceutical lot-specific traceability demand. |
| Indonesian Tobacco Excise Tender Capture | Multi-layer optical variable ink systems address expanding holographic banderole programs by the country's tax authority. |
Methodological Framework
Bottom-up pharmaceutical packaging modeling reconciled against top-down security ink production tracking forms the analytical core. Primary interviews with formulation chemists, pharmaceutical contract packaging procurement leads, flexographic press operators, and EMA regulatory affairs specialists combined with secondary validation against FDA DSCSA guidance documents, ECHA REACH substance restrictions, NMPA track-and-trace standards, and customs trade data. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map photoinitiator feedstock availability, resin vehicle pricing, and print technology installation bases against pharmaceutical serialization deadlines, consumer goods diversion risk exposure, and government credential contract awards. Segmentation dimensions span formulation chemistry, print technology platform, end-use vertical regulatory tier, and geographic compliance cluster. CAGRs derive from regression of historical qualification timelines against projected mandate implementation velocity, incorporating pigment synthesis capacity expansion and digital printhead adoption curves.
Revisions become necessary when FDA enforcement intensity shifts, ECHA REACH authorization timelines extend, or photoinitiator supply concentration breaches current thresholds. Deviation in Chinese MIIT industrial policy localization targets would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Printing Plate Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Food Grade Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
UV Cured Inks Market
Printing Inks
Security Printing Market
Printing Inks
Squid Ink Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Thermal Inkjet Inks Market