
 Molecular Ink Market | 2026-2036
Molecular Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Ink Market Analysis
Automotive sensor applications is broadening as a primary demand vertical for molecular ink formulations. BASF leverages its materials science depth to supply high-purity precursor chemistries for conductive layers. Daido Steel anchors regional supply chains through its specialty metal powder capabilities in East Asian markets. Ulvac competes via vacuum deposition expertise that extends into ink-compatible thin-film architectures.
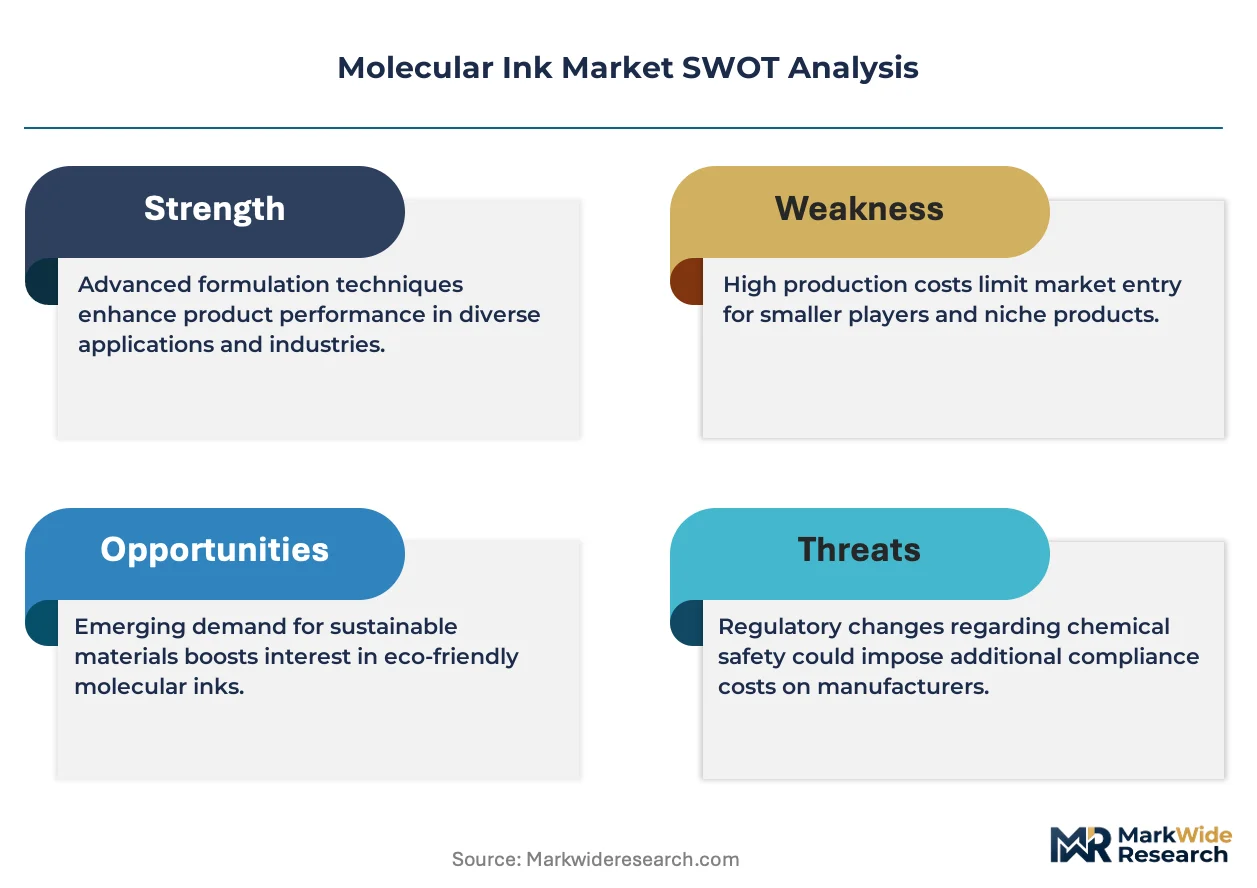
Molecular ink comprises functional formulations containing metallic nanoparticles, organic semiconductors, or dielectric polymers suspended in carrier vehicles, typically engineered for deposition thicknesses below 500 nanometers to enable precise electronic patterning on flexible or rigid substrates. The primary commercial purpose centers on additive manufacturing of conductive traces, resistive elements, and capacitive structures without subtractive etching processes. Conductive ink formulations currently occupy the largest value share due to their indispensability in printed circuit prototyping and RFID antenna production. UV-curable ink variants represent the fastest-expanding category as manufacturers seek instant polymerization that eliminates volatile organic compound emissions and reduces drying energy. Inkjet printing technology leads equipment pairings for molecular ink deployment, though screen printing sustains volume dominance in thick-film sensor and heater element fabrication where paste viscosity requirements exceed jetting parameters.
EPA regulations under the Toxic Substances Control Act govern nanoparticle reporting thresholds for molecular ink imports into the United States, while REACH registration mandates in Europe enforce full supply chain disclosure of organometallic constituents above one-ton annual thresholds. Japan's METI administers Chemical Substances Control Law classifications that determine whether novel conductive polymers qualify as new chemical entities requiring pre-market notification. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as fluorinated surfactants common in ink dispersion formulations face accelerating regulatory phase-out timelines that will force reformulation investments.
Market Dynamics
UV-curable molecular ink formulations are compressing production cycle times in printed electronics manufacturing, forcing incumbent solvent-based suppliers to reformulate product lines or cede share to instant-polymerization alternatives.
Growth Catalysts
- Automotive Sensor Integration:Tier-1 suppliers in Germany and Japan are specifying molecular ink for capacitive touch surfaces and printed heater elements in electric vehicle cabins.
- REACH Registration Thresholds:Full supply chain disclosure mandates above one-ton annual volumes are accelerating substitution toward pre-registered conductive polymer precursors.
- Inkjet Deposition Precision:Sub-500 nanometer layer control is enabling additive manufacturing of RFID antennas without subtractive etching waste streams.
Market Restraints
- Silver Nanoparticle Cost Volatility:Precious metal feedstock fluctuations compress gross margins for conductive ink formulators serving price-sensitive antenna producers.
- East Asian Supply Concentration:Specialty metal powder capabilities cluster in Japan and South Korea, creating single-source vulnerability for European and North American compounders.
- Fluorinated Surfactant Phase-Out:Accelerating per- and polyfluoroalkyl substance restrictions across multiple jurisdictions force unplanned reformulation investments.
Strategic Opportunities
- Flexible Hybrid Electronics:Convergence of printed conductive traces with micro-assembled semiconductor dies opens medical wearable applications previously closed to purely printed solutions.
- EPA Nanoparticle Reporting:Toxic Substances Control Act thresholds for imports create first-mover advantage for domestic U.S. synthesis capabilities.
- India Electronics Manufacturing:Production-linked incentive schemes for semiconductor packaging attract molecular ink suppliers to underpenetrated South Asian demand.
Industry Challenges
- Formulation Chemistry Expertise Gap:Shortage of organometallic synthesis specialists delays scale-up from laboratory validation to pilot production.
- Dual Certification Burden:Separate METI pre-market notification in Japan and EPA import compliance in the United States extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Ink Market |
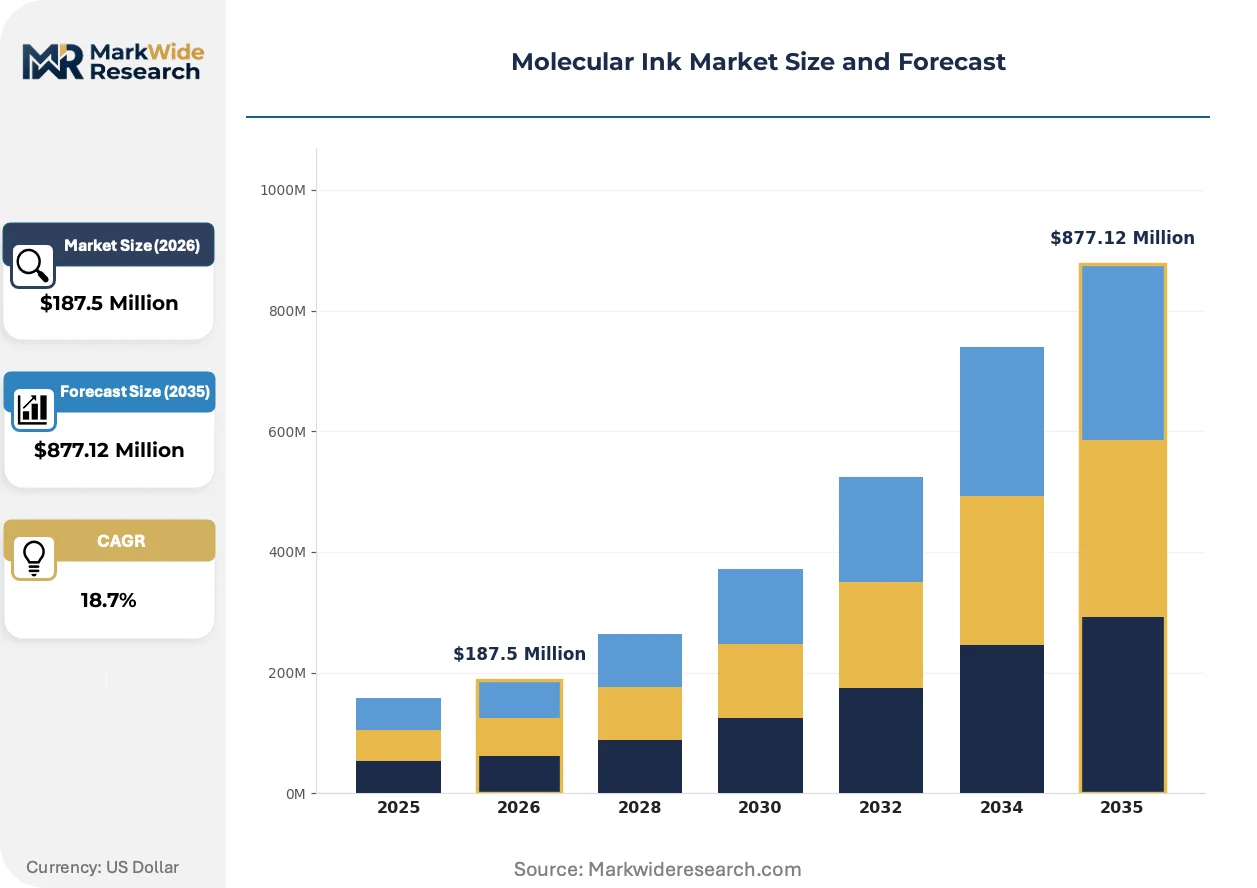
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $877.12 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Ink, UV-Curable Ink, Solvent-Based Ink, Water-Based Ink Application: Printed Electronics, Packaging, Sensors, Functional Coatings End User: Consumer Electronics, Automotive, Aerospace, Healthcare Technology: Inkjet Printing, Screen Printing, Flexographic Printing, Gravure Printing |
| Companies Covered | Ulvac, Corning Precision Material, DOW, Daido Steel, BASF, Materion, Atotech, MacDermid, Kobe Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Ink Market Emerging Trajectories
Digital printing architectures are displacing analog screen methods in applications where pattern complexity and lot-size flexibility outweigh paste viscosity advantages.
Aerosol jet deposition is automating conformal coating of three-dimensional automotive interior surfaces previously unreachable by flatbed screen equipment. Tier-1 cabin suppliers in Germany are qualifying the technology for curved touch-control panels. The process is automating integration of capacitive sensors into injection-molded trim without secondary assembly steps.
REACH enforcement is tightening disclosure requirements for organometallic constituents in conductive formulations imported above one-ton annual thresholds. ECHA registration dossiers now demand full toxicological profiles for novel precursor chemistries. European compounders are responding by consolidating supplier bases toward pre-registered material streams.
Specification-driven procurement is compressing qualification cycles for molecular ink suppliers serving automotive electronics divisions. Buyers in South Korea now require concurrent submission of conductivity stability data, adhesion testing, and volatile organic compound emission profiles. Tier-1 antenna producers are consolidating vendor lists to three approved sources per substrate category.
Molecular Ink Market Segmentation
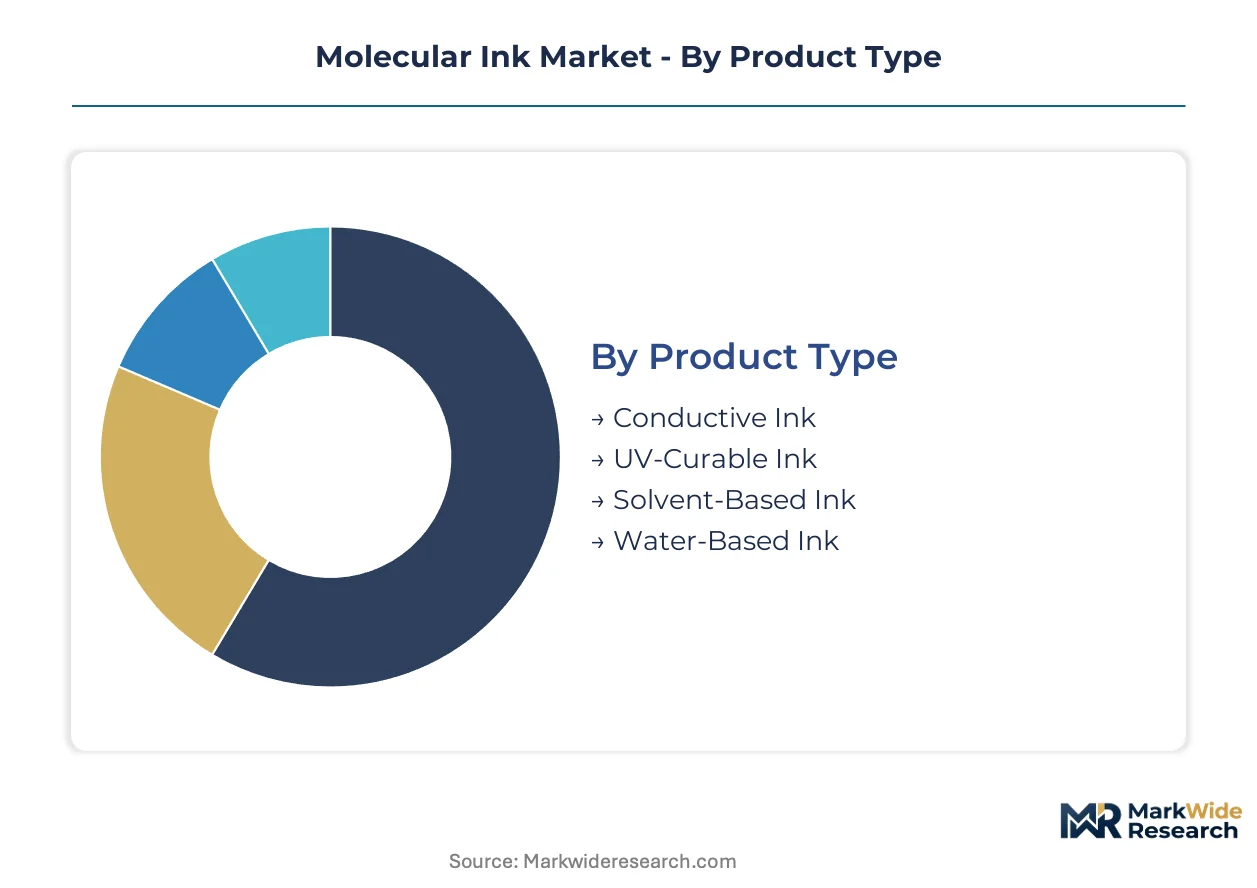
Molecular ink segmentation reveals how formulation chemistry, deposition physics, and end-use specifications intersect to create distinct supply economics. Each dimension carries implications for procurement strategy, regulatory exposure, and manufacturing scale.
Product Type:
Supply concentration varies sharply across formulation chemistries, with precious metal feedstock dependencies and curing infrastructure requirements creating divergent margin structures.
- Conductive Ink:Metallic nanoparticle suspensions—predominantly silver—enable additive manufacturing of circuit traces and RFID antennas. Demand clusters in South Korean antenna producers and German automotive sensor divisions where conductivity stability under thermal cycling is non-negotiable.
- UV-Curable Ink:Photoinitiator-loaded formulations polymerize instantly under UV exposure, eliminating volatile organic compound emissions and drying energy. Japanese printed electronics manufacturers are specifying these for flexible hybrid medical wearables where solvent residues compromise biocompatibility.
- Solvent-Based Ink:Traditional carrier vehicles with established supply chains serve thick-film heater elements where viscosity control outweighs environmental compliance priorities.
- Water-Based Ink:Surfactant-stabilized aqueous dispersions face accelerating reformulation pressure as fluorinated wetting agents face regulatory phase-out across multiple jurisdictions.
Conductive ink absorbs the bulk of installed capacity; UV-curable ink is expanding most quickly.
Application:
End-use physics dictate formulation specifications, with deposition thickness tolerances and substrate adhesion requirements creating technology lock-in effects.
- Printed Electronics:Additive patterning of conductive traces, resistive elements, and capacitive structures on flexible or rigid substrates without subtractive etching. German automotive tier-1 suppliers are driving specification convergence around sub-500 nanometer layer control for electric vehicle cabin interfaces.
- Sensors:Capacitive touch surfaces, printed heater elements, and strain gauges require calibrated conductivity stability across temperature ranges. Japanese electric vehicle manufacturers are qualifying molecular ink for curved interior panels previously served by mechanical switches.
- Packaging:Smart labels and anti-counterfeiting features integrate conductive authentication elements with graphic printing processes.
- Functional Coatings:EMI shielding and transparent conductive layers extend molecular ink utility beyond discrete electronic components.
Printed electronics commands the largest formulation volumes; sensor applications are climbing the fastest as automotive electrification accelerates.
End User:
Procurement sophistication and qualification cycle length vary dramatically across customer categories, with automotive and aerospace imposing the most stringent certification burdens.
- Consumer Electronics:High-volume antenna and touch sensor production for smartphones and wearables. South Korean device manufacturers are consolidating vendor lists to three approved sources per substrate category to compress qualification overhead.
- Automotive:Capacitive controls, printed heaters, and sensor interfaces in electric vehicle cabins. German tier-1 suppliers now require concurrent submission of conductivity stability data, adhesion testing, and volatile organic compound emission profiles.
- Healthcare:Biocompatible wearable sensors and diagnostic device electrodes demand precursor purity levels exceeding industrial grades.
- Aerospace:Lightweight conformal antennas and de-icing elements specify molecular ink for mass reduction in satellite and unmanned aerial vehicle applications.
Consumer electronics represents the largest addressable base; automotive procurement is gaining share fastest as cabin electrification intensifies.
Technology:
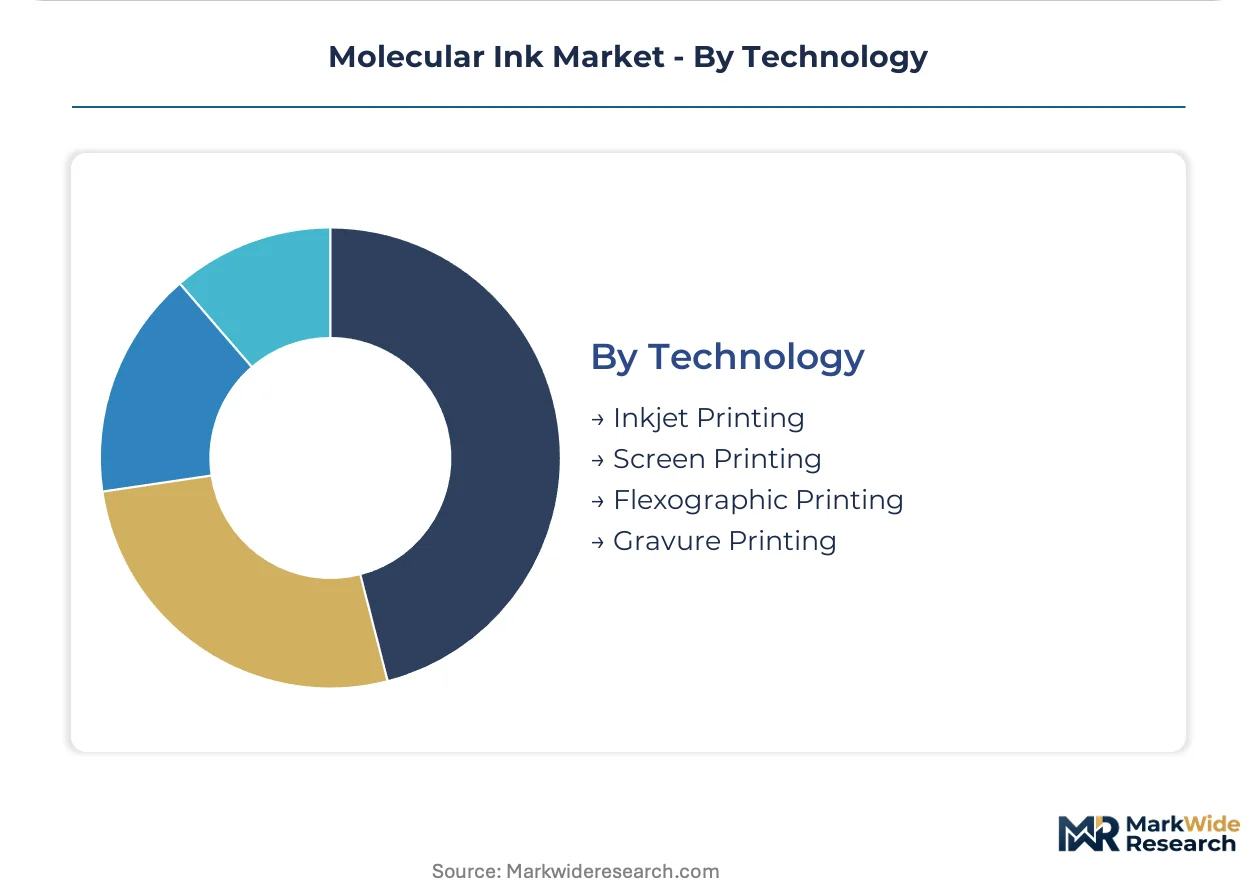
Deposition method selection determines formulation viscosity windows, particle size constraints, and capital equipment requirements.
- Inkjet Printing:Drop-on-demand deposition enables pattern complexity and lot-size flexibility for prototyping and short-run production. Japanese equipment manufacturers are integrating vision systems for real-time print uniformity correction in RFID antenna fabrication.
- Screen Printing:Paste-based methods sustain volume dominance in thick-film sensor and heater elements where viscosity requirements exceed jetting parameters. German automotive suppliers rely on rotary screen systems for curved touch-control panel production.
- Flexographic Printing:Continuous roll-to-roll processing suits high-volume packaging applications with repetitive graphic and conductive pattern integration.
- Gravure Printing:Engraved cylinder methods deliver precise ink transfer for long-run functional coating applications with minimal variation.
Screen printing retains the largest installed equipment base; inkjet printing is expanding most quickly as digital architectures displace analog methods in pattern-complexity applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in precision electronics manufacturing clusters concentrate molecular ink procurement. Tax incentives and streamlined customs procedures draw formulation suppliers to these corridors. Regional regulatory divergence shapes local competitive positioning.
Germany
Automotive tier-1 suppliers specify molecular ink for capacitive touch surfaces and printed heater elements in electric vehicle cabins. REACH registration mandates from ECHA enforce full supply chain disclosure for organometallic constituents above one-ton annual thresholds. The Stuttgart and Munich industrial corridors host concentrated procurement from sensor and antenna producers.
Japan
Electric vehicle manufacturers qualify molecular ink for curved interior panels previously served by mechanical switches. METI administers Chemical Substances Control Law classifications determining whether novel conductive polymers require pre-market notification. The Kansai and Chubu regions anchor specialty metal powder capabilities for regional supply chains.
South Korea
Device manufacturers consolidate vendor lists to three approved sources per substrate category for antenna and touch sensor production. MFDS-aligned chemical safety standards intersect with industrial material specifications. The Seoul Capital Area and Busan-Ulsan corridor concentrate printed electronics manufacturing capacity.
United States
Domestic synthesis capabilities attract investment as EPA nanoparticle reporting thresholds under the Toxic Substances Control Act create compliance barriers for imports. Production-linked incentive frameworks for semiconductor packaging expand addressable demand. The Pacific Northwest and Greater Boston clusters host precision deposition equipment integration.
India
Production-linked incentive schemes for semiconductor packaging attract molecular ink suppliers to underpenetrated South Asian demand. BIS certification requirements for electronic materials create qualification pathways for imported formulations. The Karnataka and Tamil Nadu electronics manufacturing clusters drive specification adoption.
Molecular Ink Market Vendor Landscape
Top-tier vendors anchor materials science depth, while mid-tier specialists compete on deposition technology compatibility. The vendor base stratifies across chemical precursor suppliers, thin-film equipment integrators, and specialty metal powder fabricators. Two strategic archetypes dominate: diversified materials conglomerates leveraging vertical control over feedstocks, and precision deposition specialists converting vacuum expertise into ink-compatible architectures. Competitive moves center on reformulation investments responding to fluorinated surfactant phase-outs, and strategic partnerships bridging precursor chemistry with printing equipment OEMs.
Within the materials conglomerate tier, BASF and DOW exemplify archetypes leveraging integrated chemical synthesis capabilities. Daido Steel occupies a position among specialty metal powder suppliers anchoring East Asian regional supply chains. Ulvac represents the deposition technology specialist archetype, sitting within the vacuum equipment-to-ink formulation translation layer.
| Leading Market Players |
|---|
| Ulvac |
| Corning Precision Material |
| DOW |
| Daido Steel |
| BASF |
| Materion |
| Atotech |
| MacDermid |
| Kobe Steel |
| Others |
Supply Flow & Price Mechanics
Silver nanoparticle feedstock volatility cascades through formulation pricing tiers as conductive ink compounders pass precious metal cost swings to automotive antenna producers in Germany and South Korea. REACH-registered precursor streams command sustained premiums over unregistered alternatives as ECHA disclosure mandates harden procurement specifications above one-ton annual thresholds.
Pricing Analysis
Short-lead-time orders for UV-curable formulations attract 15-20% premiums over standard contract terms as Japanese medical wearable manufacturers compress qualification cycles. Three-tier pricing structure across REACH-certified, pre-registered, and spot-market precursor grades separates automotive tier-1 suppliers from packaging converters and research prototyping labs. Cost compression in solvent-based conductive inks is intensifying because South Korean antenna producers are consolidating vendor lists to three approved sources per substrate category. Price-sensitive packaging converters in India drive spot-market negotiation, while German automotive electronics divisions absorb premium positioning for concurrent conductivity stability and VOC emission documentation.
Supply Chain Analysis
Freight costs for silver nanoparticle imports from Japan to European compounding facilities have risen disproportionately against intra-Asian lanes, compressing margins for non-integrated formulators. Specialty metal powder capabilities concentrate in Japan, South Korea, and Germany, with Daido Steel and Kobe Steel anchoring East Asian feedstock supply. Raw material dependencies rest on silver bullion contracts, photoinitiator chemistries from BASF, and fluorinated surfactant alternatives facing accelerated phase-out timelines. Single-source vulnerability pervades high-purity organometallic precursor streams qualified for automotive sensor applications. Distribution runs through authorized distributor networks in precision electronics manufacturing clusters rather than direct OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Molecular Ink Market operates as a cost-of-compliance arena where REACH registration investments above one-ton thresholds erect defensible moats for incumbent compounders against unregistered import competition.
For Market Incumbents: Lock in backward integration into high-purity silver nanoparticle synthesis or captive photoinitiator supply to neutralize feedstock volatility compressing gross margins. Secure dual METI and EPA pre-certification for novel conductive polymer streams to extend product launch timelines into 18-24 month barriers against emerging entrants. Prioritize qualification partnerships with inkjet equipment OEMs integrating vision systems for real-time print uniformity correction. For New Entrants and Emerging Players: Begin with India electronics manufacturing clusters where production-linked incentive schemes for semiconductor packaging attract molecular ink suppliers to underpenetrated South Asian demand. Target water-based ink reformulation services for European compounders facing fluorinated surfactant phase-out deadlines without internal organometallic synthesis capabilities. Pursue toll-manufacturing arrangements with established REACH-registered facilities to bypass registration capital requirements. For Investors and Strategic Acquirers: EPA import compliance investments by domestic U.S. synthesis capabilities are the leading indicator that first-mover advantage in nanoparticle reporting thresholds will consolidate regional supply positions. Five-to-ten year viability hinges on acquisition targets with pre-registered REACH dossiers and established automotive tier-1 qualification relationships. Monitor aerosol jet deposition equipment qualification cycles at German automotive interior suppliers as inflection signals for conformal coating technology adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Nanoparticle Synthesis | Captive feedstock supply neutralizes precious metal volatility compressing conductive ink margins. |
| Dual METI-EPA Pre-Certification Investment | Concurrent regulatory approval compresses launch timelines against unregistered competitors. |
| Aerosol Jet Deposition Partnership | Qualification with German tier-1 suppliers automates conformal coating of curved automotive panels. |
| Fluorinated Surfactant Reformulation Program | Pre-emptive transition to compliant wetting agents avoids forced supply interruptions under REACH phase-outs. |
| India Electronics Manufacturing Entry | Production-linked incentive schemes attract molecular ink suppliers to underpenetrated semiconductor packaging demand. |
Methodological Framework
Multi-period observation of automotive sensor procurement specifications, REACH registration filing volumes, and inkjet equipment installation rates anchored the trend analysis, supplemented by interviews with conductive ink formulation chemists, automotive tier-1 procurement directors, vacuum deposition equipment integrators, and ECHA regulatory affairs consultants. Secondary validation drew from customs trade data for silver nanoparticle imports, SEC 10-K filings of materials conglomerates, and METI Chemical Substances Control Law notification databases. Bottom-up segment sizing triangulated against top-down market aggregation from printed electronics equipment shipments.
Segment-weighting across formulation chemistry, deposition technology, and end-use application dimensions structured the analytical framework over the projection horizon. Conductive ink, UV-curable ink, solvent-based ink, and water-based ink categories were modeled separately with distinct precious metal feedstock exposure assumptions. Inkjet, screen, flexographic, and gravure printing technology adoption curves were cross-referenced against automotive electrification content-per-vehicle trajectories. CAGRs were derived from regression against historical qualification cycle compression and regulatory compliance investment patterns.
Underlying measurement precision varies by segment; automotive sensor applications carry tighter precision than packaging converters due to consolidated vendor reporting, while water-based ink forecasts embed higher uncertainty from fluorinated surfactant phase-out timeline variability. Forecasts reflect assumptions about REACH enforcement consistency and EPA nanoparticle reporting threshold stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Decorative Print Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Lithography Inks Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
UV Cured Inks Market
Printing Inks
United States Printing Inks Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Ink Additives Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Offset Ink Market