
 Flexo-Ink Market | 2026-2036
Flexo-Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Flexo-Ink Market Analysis
Flexible packaging converters are rotating share toward UV-curable flexo-ink systems as shelf-life and print-speed requirements tighten. DIC Corporation leverages captive resin production to control formulation consistency across Asian and European plants. Sun Chemical anchors North American supply through integrated pigment manufacturing and regional blending facilities. Siegwerk competes on regulatory compliance depth, maintaining dedicated food-contact certification laboratories in multiple jurisdictions.
Flexo-ink comprises pigmented or dyed fluid formulations engineered for transfer via anilox-roller metering to flexible photopolymer plates, typically operating at viscosities between 50 and 500 centipoise depending on solvent, water, or radiation-cure carrier chemistry. Its primary purpose is high-speed, high-volume decoration of corrugated cases, flexible films, labels, and folding cartons at press speeds exceeding 300 meters per minute. Water-based flexo-ink retains dominance in corrugated packaging where porous substrates and cost sensitivity define procurement criteria, while UV-curable grades command margin pools in premium labeling and shrink-sleeve applications where instant drying and chemical resistance justify higher unit pricing. Digital flexography technology segments are gaining traction among mid-volume converters seeking plateless changeovers for shorter runs.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based flexo-ink use in U.S. corrugated and flexible packaging operations, pressuring converters toward water-based or UV alternatives. REACH registration requirements and the EU Green Deal's carbon-border adjustments compel European ink suppliers to document substance toxicity and supply-chain emissions across imported raw materials. Stakeholders must monitor evolving state-level extended producer responsibility laws and anilox-cell engraving advances that alter ink-transfer efficiency and consumption rates per thousand impressions.
Market Dynamics
UV-curable flexo-ink chemistries are compressing drying times and enabling faster press speeds, forcing converters to reconfigure anilox specifications and curing equipment investments.
Growth Catalysts
- EU Green Deal VOC restrictions:REACH-mandated volatile organic compound limits in Germany and France are redirecting formulation strategies toward water-based and energy-cure systems.
- Flexible packaging converters:Shelf-life extension requirements for food-contact films are accelerating specification upgrades to UV-curable grades with enhanced chemical resistance.
- Digital flexography:Plateless changeover technology is miniaturizing setup waste and enabling mid-volume converters to compete for shorter-run label contracts.
Market Restraints
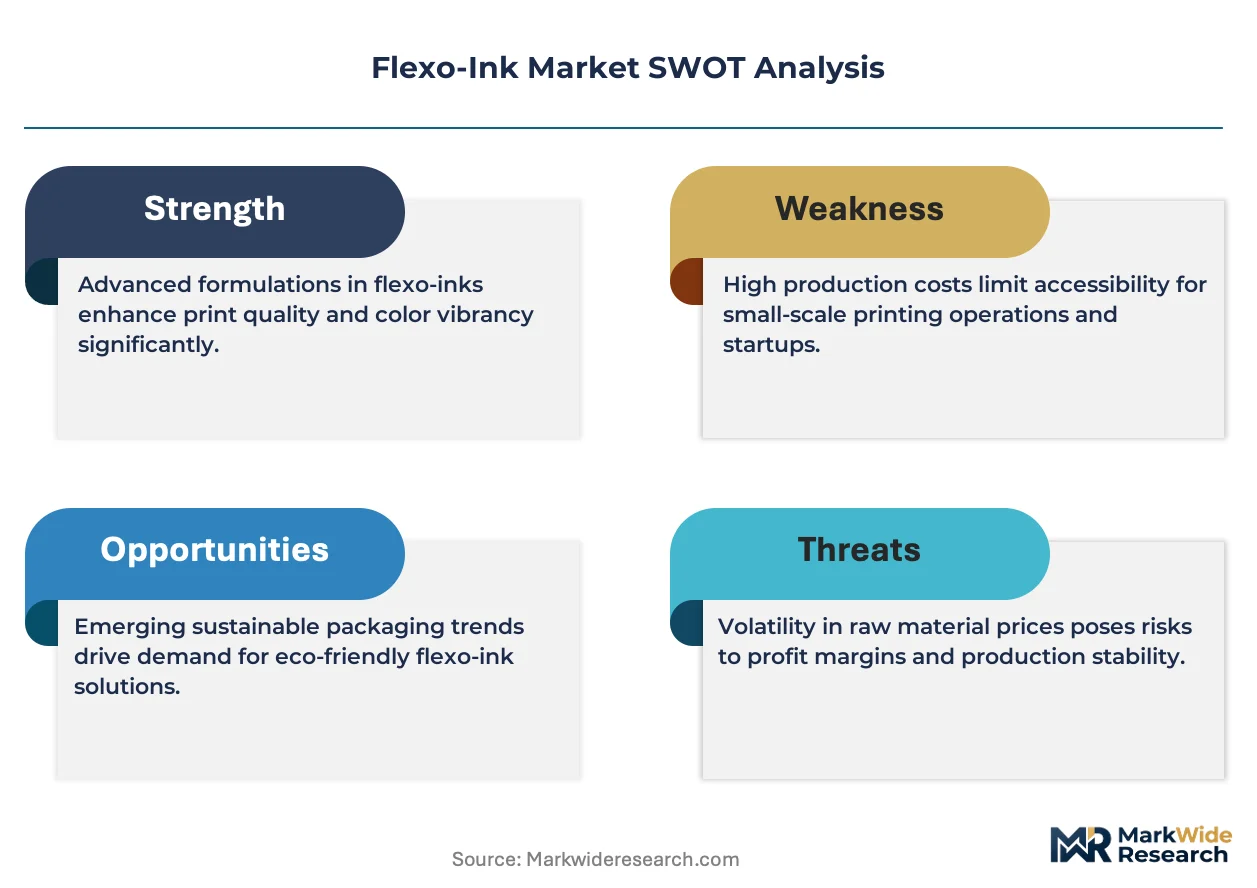
- Photoinitiator supply concentration:Specialty photoinitiator manufacturing clusters in China create raw material vulnerability for UV-curable ink producers.
- Legacy press incompatibility:Water-based viscosity requirements demand anilox-cell recutting or roller replacement, raising retrofit capital thresholds for corrugated converters.
- Substitution by digital inkjet:Narrow-web label printers are bypassing flexography entirely for variable-data short runs, eroding addressable volume in premium segments.
Strategic Opportunities
- India packaging expansion:FSSAI food-contact compliance investments by domestic flexible film producers are opening specification windows for certified low-migration ink systems.
- Shrink-sleeve decoration:Beverage and personal care brands are specifying UV-curable flexo for high-shrink substrates where gravure cannot achieve registration tolerances.
- Extended producer responsibility laws:State-level packaging waste mandates in California and New York are creating procurement preference for recyclable monolayer structures compatible with water-based inks.
Industry Challenges
- Colorimetric certification timelines:Brand owner Pantone-matching requirements and ISO 2846-1 compliance documentation are extending qualification cycles for new ink formulations.
- Anilox-cell engraving precision:Laser-engraved cell geometry tolerances below 2 micron variation demand skilled maintenance technicians that converter workforces lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexo-Ink Market |
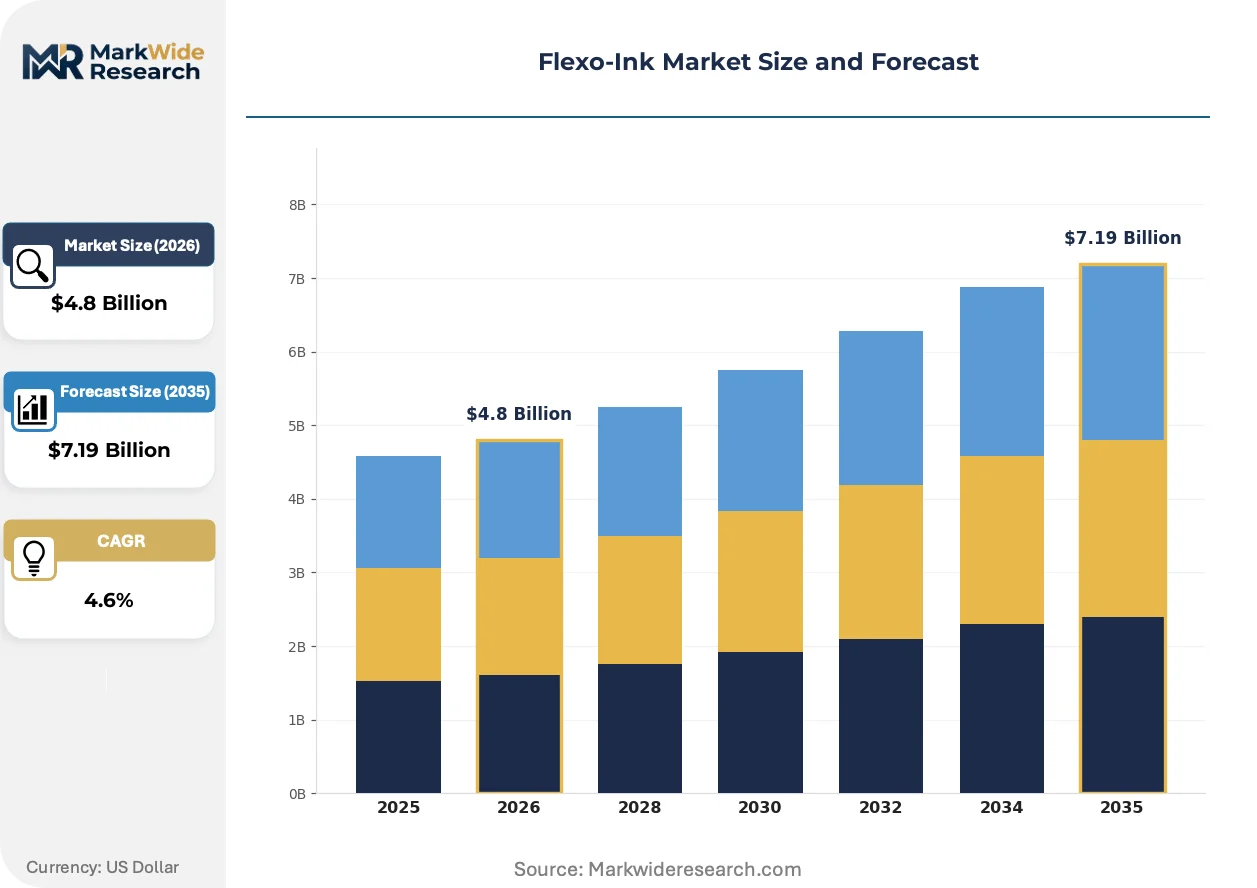
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, UV-Curable, All-Weather Application: Food Packaging, Labeling, Corrugated Packaging, Flexible Packaging End User: Printing Houses, Packaging Companies, Consumer Goods, Textiles Technology: Digital Flexography, Hybrid, Conventional Flexography, Gravure |
| Companies Covered | DIC Corporation, INX International Ink Co., Sun Chemical, T&K TOKA Corporation, Sakata INX Corporation, Flint Group, Toyo Ink, Apex International, Siegwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexo-Ink Market Emerging Trajectories
Electron-beam curing and LED-UV lamp architectures are reshaping capital deployment patterns, while bio-based resin feedstocks and recycled-content packaging compatibility are redefining formulation roadmaps.
LED-UV flexo-ink systems operate at lower wavelengths than conventional mercury-arc curing, reducing energy consumption and substrate heat exposure. Narrow-web label converters in Italy and Spain are retrofitting presses with LED arrays to handle heat-sensitive film stocks. This technology is miniaturizing the equipment footprint required for commercial-grade curing, enabling entry-level converters to access premium applications.
REACH registration dossiers under ECHA scrutiny now require substance toxicity documentation across imported raw material supply chains. European ink suppliers are consolidating supplier audits and carbon-footprint accounting to satisfy EU Green Deal border-adjustment mechanisms. Food-contact certification laboratories in Germany face backlog pressures as folding-carton printers accelerate compliance documentation for export markets.
Brand owners are unbundling ink supply from press maintenance contracts, shifting toward specification-based procurement with penalty clauses for color drift. Large retail chains in the United States are centralizing print buying through approved vendor lists, compressing converter margins and elevating technical service requirements. This concentration is most visible in private-label beverage packaging, where national account managers now dictate ink performance guarantees and inventory holding terms.
Flexo-Ink Market Segmentation
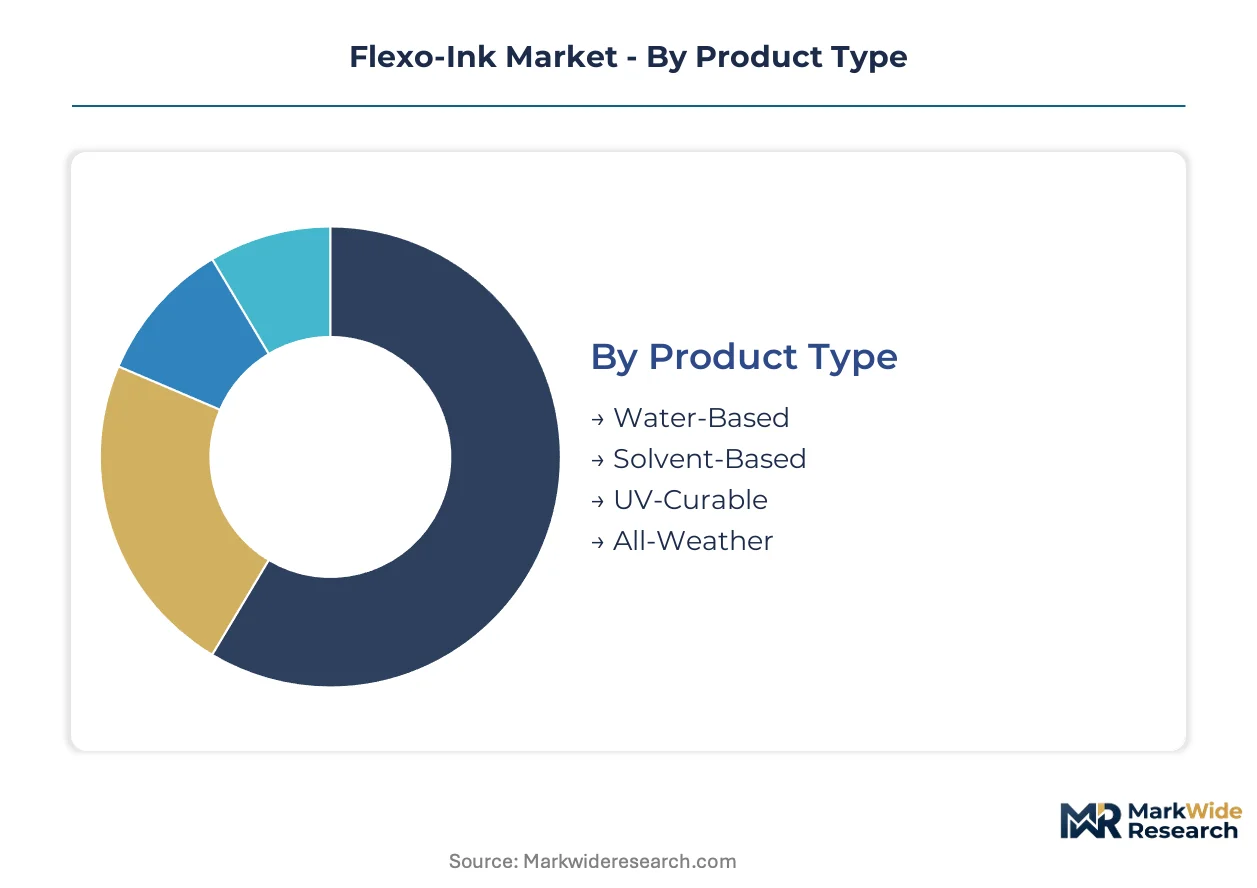
Flexo-ink procurement patterns diverge sharply across chemistry types and press technologies. Understanding where margin pools concentrate helps suppliers prioritize formulation investments and converter upgrade pathways.
Product Type:
Margin pools concentrate in radiation-cure chemistries where instant drying justifies premium pricing, while water-based formulations dominate volume throughput in cost-sensitive corrugated operations.
- Water-Based:Acrylic and polyurethane dispersions suspended in water carrier systems achieve viscosities between 50 and 200 centipoise for porous substrate penetration. Corrugated converters in Germany and France are accelerating specification shifts here to satisfy EU Green Deal VOC thresholds and REACH registration mandates.
- UV-Curable:Photoinitiator-activated oligomer systems polymerize instantly under mercury-arc or LED-UV exposure, eliminating thermal drying tunnels. Premium label printers in Italy and Spain are retrofitting narrow-web presses with LED arrays to access heat-sensitive film applications where solvent-based alternatives fail.
- Solvent-Based:Nitrocellulose and polyurethane solutions in alcohol-ester blends retain footholds in film lamination where adhesion chemistry demands aggressive substrate wetting.
- All-Weather:Modified acrylic formulations engineered for temperature and humidity extremes serve outdoor signage and agricultural packaging in climates with seasonal variation.
The dominant share belongs to Water-Based, while UV-Curable is closing the gap fastest.
Application:
Application-driven demand splits between high-volume commodity packaging and precision decoration where registration tolerances command specification premiums.
- Food Packaging:Low-migration ink systems certified for direct and indirect food contact dominate flexible film and folding-carton specifications. FSSAI compliance investments by Indian flexible film producers are opening procurement windows for certified formulations meeting global safety protocols.
- Labeling:Shrink-sleeve and pressure-sensitive applications demand UV-curable chemistries with chemical resistance to household cleaners and beverages. Beverage brands in Germany specify these systems for high-shrink substrates where gravure registration falls short.
- Corrugated Packaging:Water-based systems saturate this segment due to porous flute structures and extreme cost sensitivity in e-commerce shipping boxes.
- Flexible Packaging:Multi-layer film structures for snack and pet food applications require adhesion-promoting primers and lamination-grade ink systems.
Food Packaging commands the largest volume position, though Labeling delivers the steepest expansion trajectory as brand owners consolidate print buying through approved vendor lists.
End User:
Customer type determines service intensity, with packaging companies demanding technical support integration and consumer goods buyers centralizing procurement through national account structures.
- Printing Houses:Independent converters serving multiple brand owners require rapid color-matching capabilities and inventory flexibility. These operators face compressed margins as retail chains dictate performance guarantees and penalty clauses for color drift.
- Packaging Companies:Integrated film and carton producers specify ink systems aligned with in-house extrusion and forming equipment. Extended producer responsibility laws in California and New York are steering these buyers toward recyclable monolayer structures compatible with water-based chemistries.
- Consumer Goods:Brand-owner direct procurement of printed packaging concentrates buying power and elevates certification requirements.
- Textiles:Niche applications in nonwoven and fabric printing utilize specialized viscosity modifiers for absorbent substrates.
Packaging Companies represent the anchor demand segment, while Printing Houses are consolidating fastest through merger activity and national account defection.
Technology:
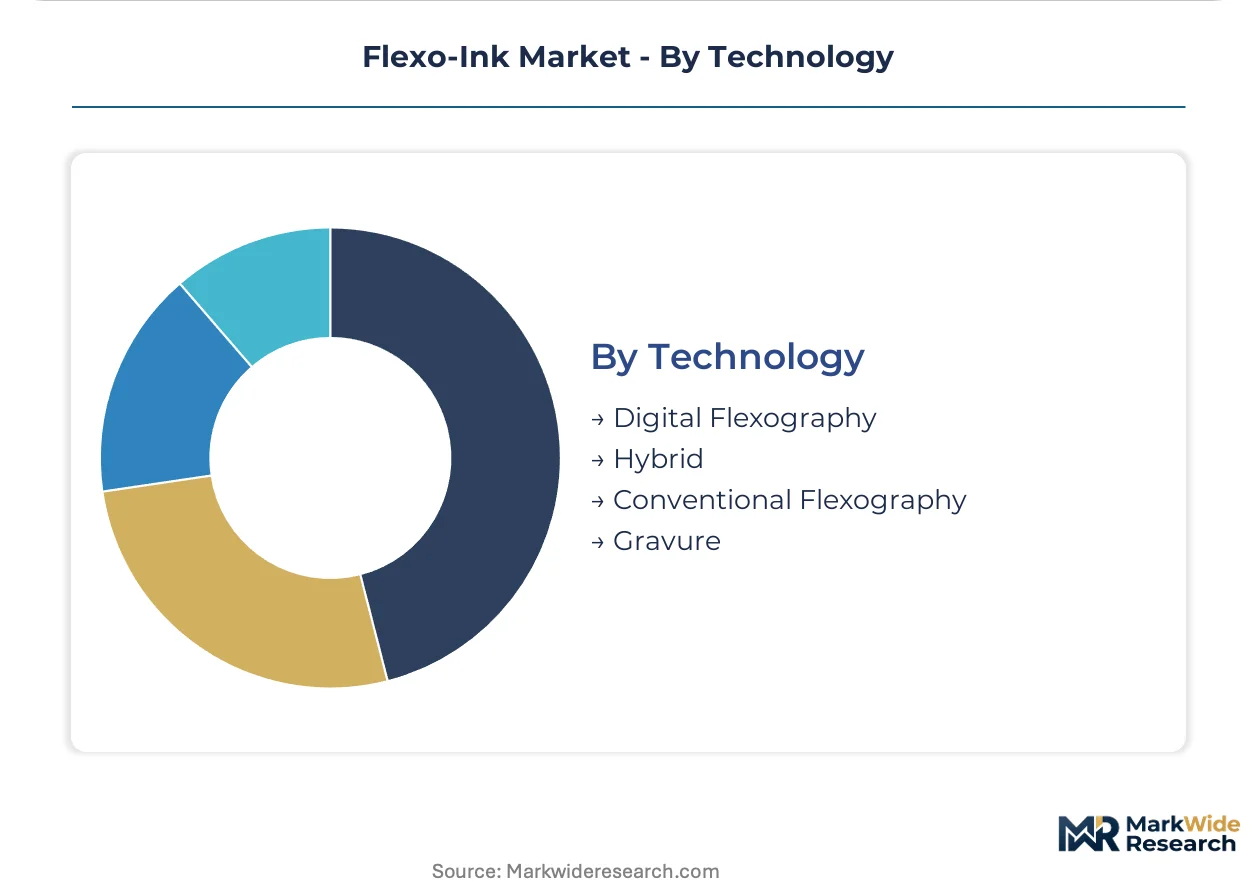
Technology segmentation tracks capital deployment patterns, with digital hybrid systems capturing mid-volume converters seeking plateless flexibility without abandoning flexographic speed advantages.
- Digital Flexography:Computer-to-plate imaging and automated impression setting enable changeovers without physical plate mounting. Mid-volume label converters in Italy and Spain deploy these systems to compete for shorter-run contracts against pure digital inkjet alternatives.
- Hybrid:Tandem configurations combining flexographic units with digital print stations merge variable-data capability with spot-color accuracy. These architectures serve pharmaceutical serialization and promotional versioning where regulatory compliance meets marketing customization.
- Conventional Flexography:Mechanical plate mounting and manual impression adjustment persist in high-volume corrugated operations where run lengths justify extended makeready times.
- Gravure:Engraved cylinder systems retain share in ultra-long-run publication and decorative laminate applications where amortization of cylinder costs is achievable.
Conventional Flexography maintains installed base dominance, though Digital Flexography is gaining share fastest as converter workforces adapt to automated makeready protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty photoinitiator manufacturing clusters in China create raw material vulnerability for UV-curable ink producers worldwide. REACH registration requirements and EU Green Deal carbon-border adjustments compel European suppliers to document substance toxicity across imported raw materials. Stakeholders must monitor evolving state-level extended producer responsibility laws and anilox-cell engraving advances that alter ink-transfer efficiency.
Germany
Premium label and folding-carton printers in Germany are upgrading press fleets to comply with tightened emissions rules. REACH-mandated volatile organic compound limits redirect formulation strategies toward water-based and energy-cure systems. The Baden-Württemberg and Bavaria industrial corridors concentrate folding-carton capacity where food-contact certification laboratories face backlog pressures.
United States
Narrow-web label converters in the United States are retrofitting presses with LED arrays to handle heat-sensitive film stocks. EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based flexo-ink use in corrugated and flexible packaging operations. California and New York state-level extended producer responsibility laws create procurement preference for recyclable monolayer structures compatible with water-based inks.
India
Flexible film producers in India are accelerating FSSAI food-contact compliance investments to open specification windows for certified low-migration ink systems. Domestic packaging expansion is creating demand for UV-curable grades with enhanced chemical resistance. The Maharashtra and Gujarat industrial belts concentrate flexible packaging converter capacity where mid-volume operators seek plateless changeover technology.
Italy
Narrow-web label converters in Italy are deploying digital flexography systems to compete for shorter-run contracts against pure digital inkjet alternatives. LED-UV flexo-ink retrofits enable handling of heat-sensitive film stocks with reduced energy consumption. The Lombardy and Emilia-Romagna packaging clusters anchor premium label production where beverage brands specify UV-curable systems for high-shrink substrates.
China
Raw material supply concentration for photoinitiators creates vulnerability for UV-curable ink producers dependent on Chinese specialty chemical manufacturing. Dual carbon goals under MEE oversight are pressuring domestic formulation strategies toward lower-emission chemistries. The Yangtze River Delta packaging corridor concentrates flexible film production where converters balance cost sensitivity with regulatory compliance documentation.
Flexo-Ink Market Vendor Landscape
Concentration sits with integrated ink and pigment manufacturers that control formulation consistency across multiple continents. The vendor base spans Japanese chemical conglomerates, European regulatory compliance specialists, and North American regional blenders. Three archetypes dominate: captive resin producers securing raw material supply, integrated pigment manufacturers anchoring color consistency, and food-contact certification laboratories differentiating on regulatory depth. Competitive moves center on backward integration into resin production and geographic expansion of blending facilities to reduce logistics exposure.
Among Japanese chemical conglomerates, DIC Corporation and T&K TOKA Corporation exemplify the captive resin producer archetype, leveraging in-house polymer manufacturing to control formulation variables across Asian and European plants. Sun Chemical anchors North American supply through integrated pigment manufacturing and regional blending facilities, representing the integrated colorant specialist model. Siegwerk occupies a position within the regulatory compliance tier, maintaining dedicated food-contact certification infrastructure in multiple jurisdictions to serve folding-carton and flexible packaging converters facing REACH and FDA documentation requirements.
| Leading Market Players |
|---|
| DIC Corporation |
| INX International Ink Co. |
| Sun Chemical |
| T&K TOKA Corporation |
| Sakata INX Corporation |
| Flint Group |
| Toyo Ink |
| Apex International |
| Siegwerk |
| Others |
Supply Flow & Price Mechanics
Scale economies in captive resin production anchor price floors across Asian and European manufacturing corridors, concentrating margin control among integrated chemical conglomerates while compressing tier-two blenders into commodity water-based formulations. REACH registration costs and EU Green Deal compliance documentation further stratify pricing power, as certification-capable suppliers capture premium positioning in food-contact and label applications.
Pricing Analysis
Volume-discount tiering structures separate UV-curable premium grades from standard water-based formulations and economy solvent-based alternatives. Price differentiation hinges on food-contact certification tier and pigment dispersion quality, with FSSAI and FDA-compliant systems commanding substantial premia over industrial-grade alternatives. Cost compression in corrugated water-based segments is intensifying because e-commerce box demand concentrates buying power among national retail chains. Packaging companies exhibit highest price sensitivity due to extended producer responsibility compliance costs, while premium label printers prioritize registration tolerance over unit economics.
Supply Chain Analysis
China and Germany anchor photoinitiator and specialty oligomer production respectively, creating bifurcated raw material sourcing for UV-curable ink manufacturers. Formulation consistency rests on imported acrylate monomers from South Korea and Japan, alongside pigment concentrates from domestic European facilities. Single-source vulnerability concentrates in Chinese photoinitiator manufacturing clusters, where environmental enforcement actions periodically constrain specialty chemical output. Distribution runs through regional blending facilities co-located with major flexible packaging converter clusters in Germany, Italy, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and color-matching retainers expand faster than base ink volume, converting transactional supply relationships into recurring-revenue arrangements as brand owners unbundle procurement from press maintenance.
For Market Incumbents: Compound defensive positioning through backward integration into photoinitiator synthesis and LED-UV curing equipment partnerships, neutralizing raw material vulnerability exposed by Chinese supply concentration. Siegwerk's multi-jurisdiction food-contact laboratory model offers a replicable template for regulatory compliance depth that digital inkjet substitution cannot replicate. For New Entrants and Emerging Players: Lead with FSSAI certification investments targeting Maharashtra and Gujarat flexible film producers, where domestic Indian packaging expansion outpaces multinational response capacity. Plateless digital flexography retrofits for mid-volume label converters in Italy and Spain present the most penetrable equipment-plus-ink bundling opportunity, with technical service intensity as the go-to-market wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among captive resin producers with integrated pigment manufacturing, where formulation consistency locks in multi-year supply agreements with folding-carton and beverage label printers. Acquisition targets should display backward integration into acrylic or polyurethane dispersion chemistry, with regulatory certification infrastructure as a secondary priority. The signal to watch is LED-UV retrofit penetration rates among narrow-web converters, indicating premium chemistry demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Manufacturing | Neutralizes Chinese supply concentration risk for UV-curable ink producers. |
| LED-UV Curing Equipment Partnership | Captures retrofit demand from Italian and Spanish narrow-web label converters. |
| FSSAI Certification Laboratory Investment | Opens specification windows with Maharashtra and Gujarat flexible film producers. |
| Digital Flexography Platform Integration | Enables plateless changeover capability for mid-volume converter segments. |
| Recyclable Monolayer Structure Compatibility Program | Aligns with California and New York extended producer responsibility procurement preferences. |
Methodological Framework
The analysis maps water-based, UV-curable, solvent-based, and all-weather chemistry segments, each validated through procurement directors at flexible packaging converters, technical service managers at ink manufacturers, anilox engraving equipment specialists, and food-contact certification laboratory directors. Primary interview findings triangulate against customs trade data for resin and pigment imports, ECHA REACH registration dossiers, EPA National Emission Standards compliance filings, and flexible packaging production capacity databases. Bottom-up volume estimates from converter equipment installations reconcile with top-down chemical consumption patterns across corrugated, label, and folding-carton applications.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation dimensions spanning chemistry type, substrate application, press technology architecture, and regional regulatory cluster. CAGRs derive from modeled unit consumption per thousand impressions, anilox-cell volume transfer efficiency improvements, and substitution elasticities between flexographic and digital inkjet systems. Forecast inputs incorporate LED-UV lamp retrofit penetration curves and EU Green Deal carbon-border adjustment implementation timelines.
Forecasts assume regulatory continuity in REACH, EPA NESHAP, and FSSAI regimes; material policy shifts would require re-modeling. Photoinitiator supply disruptions, anilox engraving precision bottlenecks, and digital inkjet substitution acceleration represent specific revision risks. Recalibration cycles align with material shifts in LED-UV equipment deployment and extended producer responsibility law enactment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Ink Additives Market
Printing Inks
Security Printing Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Zink Printing Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Food Marking Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
Eco-Friendly Inks Market