
 Continuous Inkjet Ink Market | 2026-2036
Continuous Inkjet Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Inkjet Ink Market Analysis
Food and beverage packaging is shifting toward higher-speed production lines that demand durable, legible codes on flexible substrates. Videojet Technologies leverages its North American installed base to sustain recurring ink revenue through captive supply agreements. Domino Printing Sciences anchors European demand with specialized formulations that navigate stringent chemical safety standards. Markem-Imaje competes through R&D intensity in low-migration ink chemistry for sensitive food-contact applications.
Continuous inkjet ink comprises a precisely formulated fluid of dyes or pigments, solvents, resins, and conductivity salts, engineered to break into electrically charged droplets at frequencies exceeding 100 kHz for non-contact deposition onto varied substrates. Its primary commercial purpose is high-speed, variable-data marking on production lines where permanence, contrast, and drying speed are critical. Solvent-based formulations dominate volume in industrial coding due to substrate versatility and fast dry times, while UV-curable inks capture margin pools in electronics and pharmaceutical labeling where chemical resistance and regulatory compliance command premium positioning. Water-based inks extend penetration into food packaging segments where volatile organic compound restrictions tighten.
EPA regulations in the United States constrain solvent emissions from industrial printing operations, pushing converters toward lower-VOC formulations or abatement investments. REACH registration requirements in Europe govern pigment and additive chemistries, reshaping supplier qualification criteria for ink manufacturers serving multinational brand owners. China's MEE enforces emission standards on packaging plants in the Yangtze and Pearl River Delta clusters, influencing local formulation priorities. Stakeholders must monitor evolving substance restrictions across these jurisdictions to align product portfolios with compliance timelines and avoid supply disqualification.
Market Dynamics
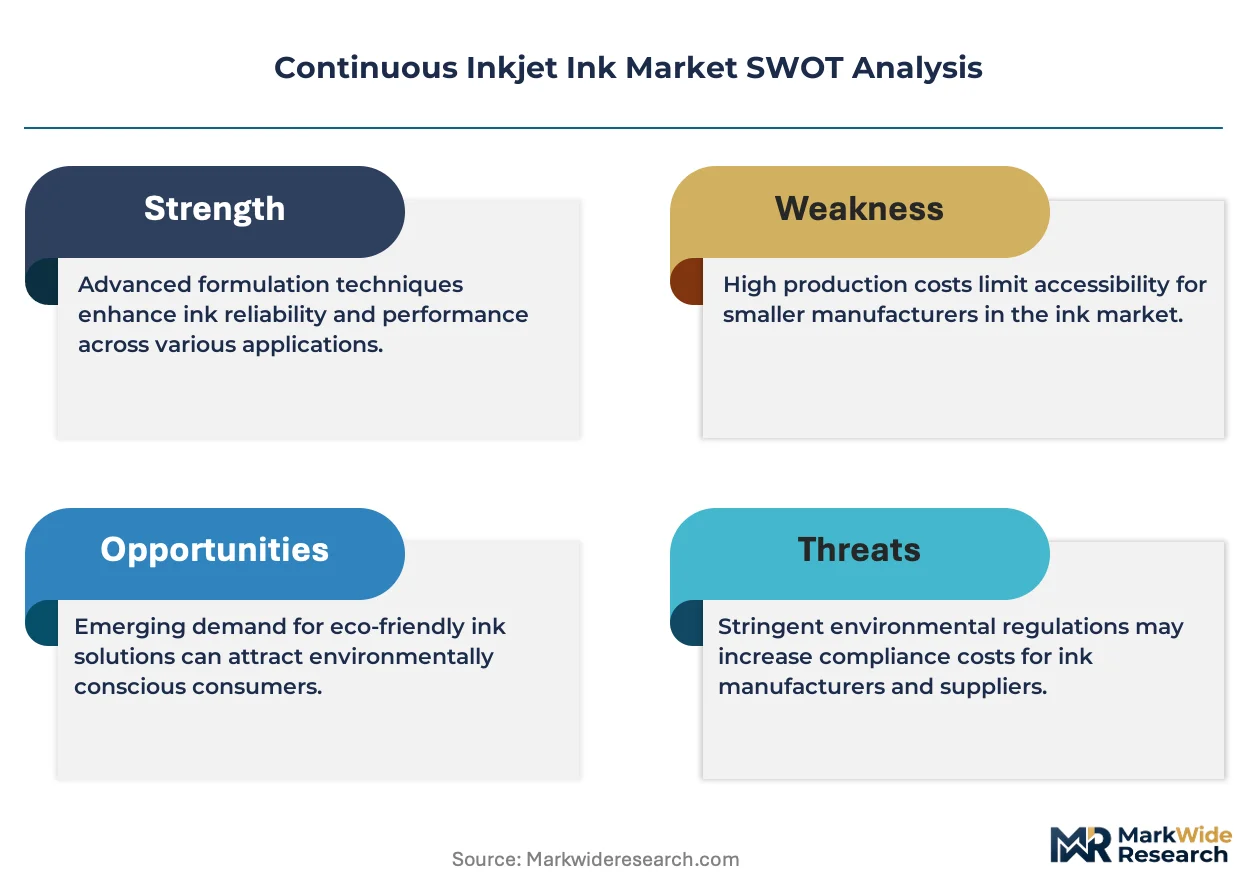
Formulation chemistry faces intensifying pressure from substance restrictions across major manufacturing jurisdictions, forcing ink producers to requalify pigment and solvent portfolios ahead of compliance deadlines while maintaining printhead compatibility and substrate adhesion performance.
Growth Catalysts
- Food-contact migration limits:EU Regulation 10/2011 on plastic materials and articles intended to come into contact with food is accelerating demand for low-migration ink systems in dairy and ready-meal packaging lines.
- China's domestic equipment buildout:Local production of continuous inkjet printers in the Yangtze River Delta is expanding captive consumption of MEK-based and pigment-based formulations for export-oriented consumer goods.
- Pharmaceutical serialization mandates:Track-and-trace requirements for unit-level drug packaging in multiple jurisdictions are embedding inkjet coding as a default technology for compliance marking.
Market Restraints
- Raw material concentration:Specialty dye and pigment supply concentrates among a limited set of chemical manufacturers in Germany and India, creating formulation cost volatility during supply disruptions.
- REACH substance evaluation:ECHA's ongoing assessment of certain glycol ethers and ketone solvents is forcing ink producers to maintain parallel formulation tracks pending authorization outcomes.
- Laser marking substitution:Fiber laser systems are capturing permanent coding applications on rigid plastics and metals where ink adhesion and solvent emissions create operational friction.
Strategic Opportunities
- Water-based ink penetration:Tightening EPA volatile organic compound limits in California and the Northeast corridor is opening formulation substitution opportunities in food packaging plants seeking abatement cost avoidance.
- UV-curable electronics labeling:Semiconductor and battery manufacturers in South Korea and Taiwan are adopting UV-inkjet for component marking where chemical resistance and fine-line resolution are critical.
- Refill and service contract bundling:Equipment vendors are restructuring commercial relationships around per-code pricing models that lock in recurring ink revenue through multi-year service agreements.
Industry Challenges
- Formulation chemist scarcity:Expertise in rheology control and charge-conductivity tuning for high-frequency droplet generation is concentrated among senior specialists approaching retirement in Western Europe and Japan.
- Printhead-material compatibility testing:Each new solvent or resin chemistry requires extended validation cycles with piezoelectric printhead suppliers, compressing product development timelines.
- Cross-jurisdiction substance registration:Maintaining active dossiers under REACH, TSCA, and China's new chemical notification regime simultaneously consumes regulatory affairs bandwidth at mid-sized ink producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Inkjet Ink Market |
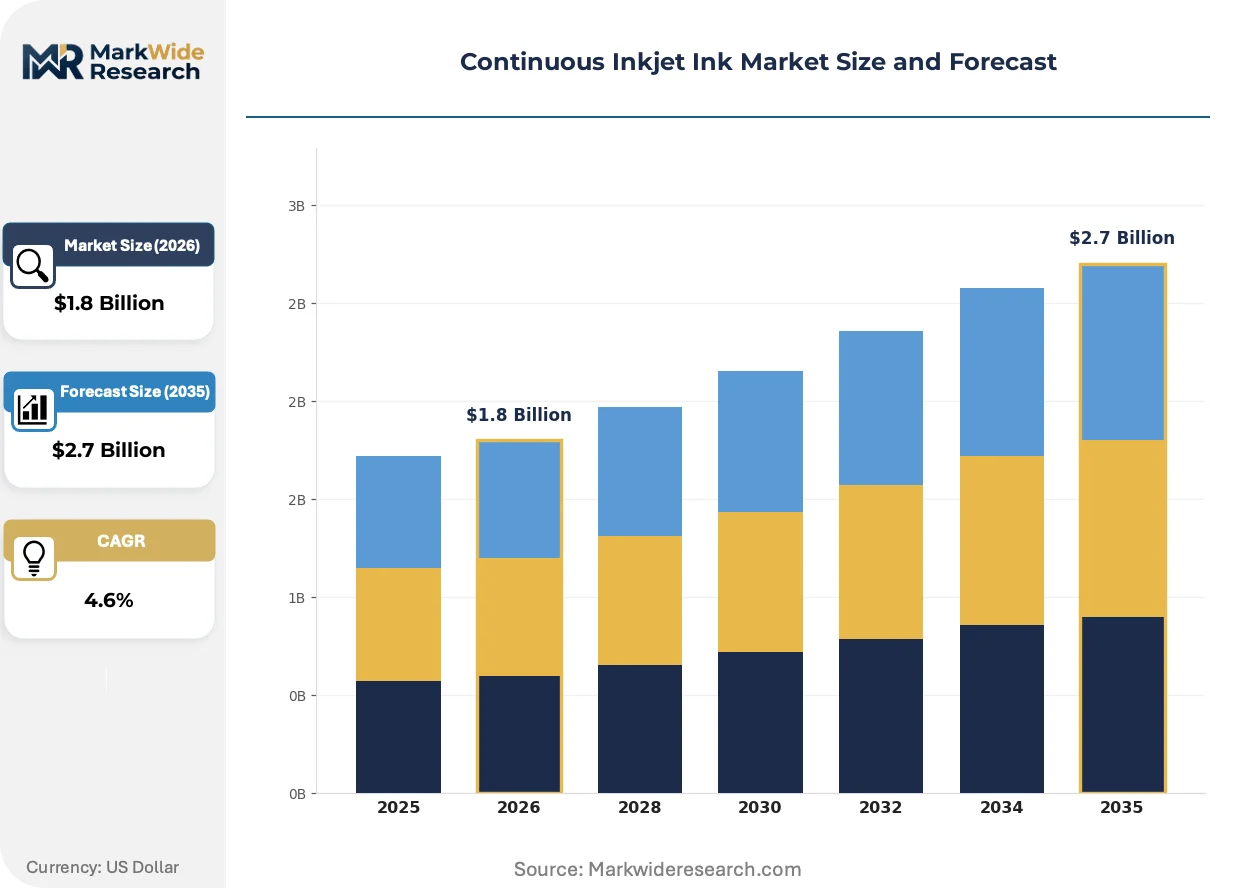
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-based, Water-based, UV-curable, Pigment-based Application: Packaging, Coding, Labeling, Marking End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Single-pass, Multi-pass, Hybrid, Digital |
| Companies Covered | Videojet Technologies, Markem-Imaje, Domino Printing Sciences, Hitachi Industrial Equipment Systems, Paul Leibinger, Linx Printing Technologies, KGK Jet, Squid Ink, Control Print, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Inkjet Ink Market Emerging Trajectories
Active chemistry and hardware integration is reshaping how ink formulations are specified, with printhead manufacturers and ink suppliers co-developing fluid systems rather than operating as independent specification layers.
Pigment dispersion technology is overtaking dye-based formulations in high-speed flexible packaging applications where lightfastness and substrate bleed resistance are critical. Converters running oriented polypropylene and polyethylene films are specifying pigment inks for beverage and snack lines. This shift is compressing the addressable market for conventional dye chemistries in outdoor and refrigerated supply chains.
REACH authorization requirements for specific solvent categories are forcing reformulation investments across European ink production facilities. The industrial consequence is a portfolio segmentation between authorized legacy formulations and next-generation alternatives with modified drying profiles. Food packaging converters in Germany and the Netherlands are absorbing the transition costs through qualified supplier changeover programs.
Service bundling is restructuring buyer-vendor relationships in the installed base. Print service contracts that consolidate hardware maintenance, ink supply, and remote diagnostics are displacing transactional ink purchasing in high-volume beverage and pharmaceutical plants. This model concentrates most visibly in North American and Western European operations where line uptime guarantees command premium positioning.
Continuous Inkjet Ink Market Segmentation
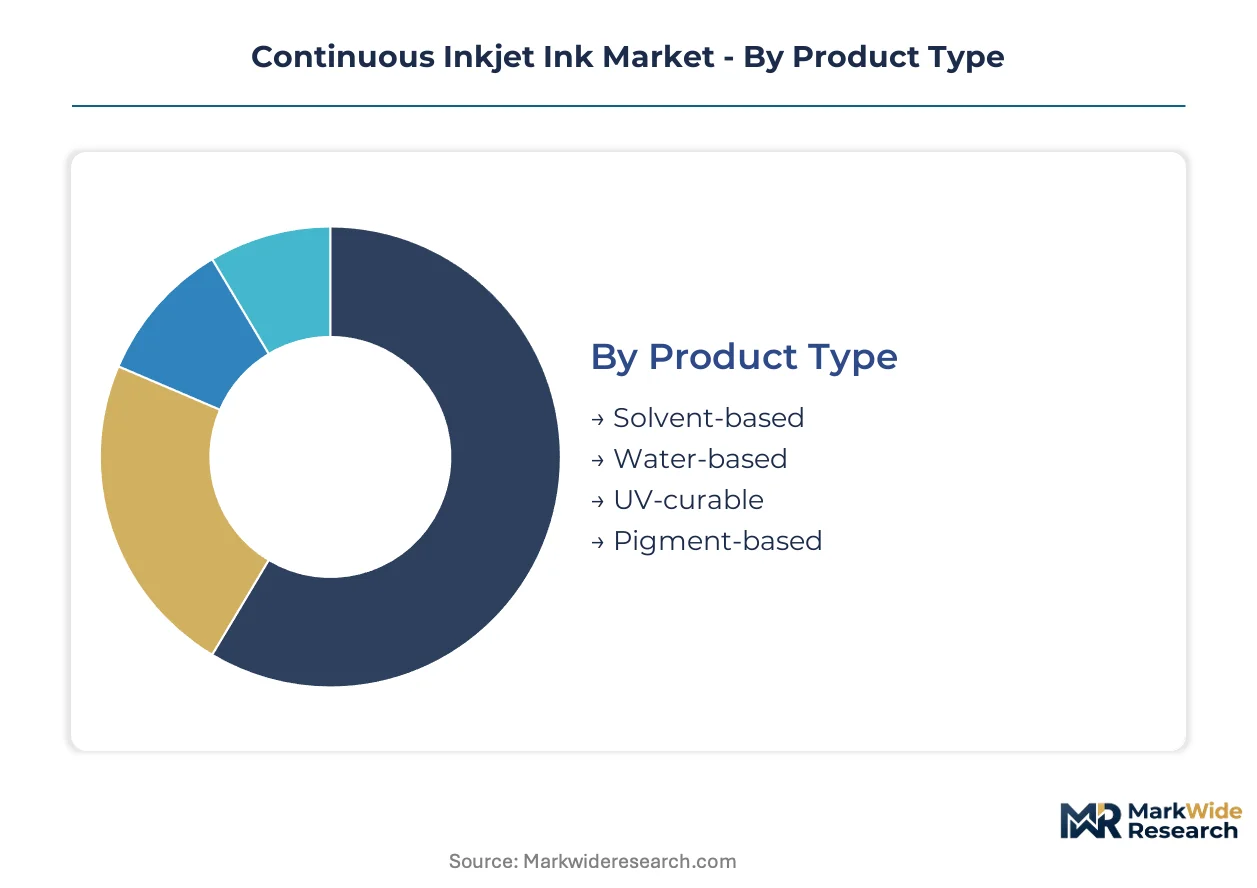
Formulation chemistry and application requirements fragment the continuous inkjet ink market into distinct supply tiers. Each segment carries unique regulatory burdens, raw material dependencies, and customer qualification barriers that reshape competitive positioning.
Product Type:
Specialty solvent and resin supply concentrates among German and Indian chemical manufacturers, creating formulation cost volatility during supply disruptions.
- Solvent-based:MEK and ethanol-based formulations dominate industrial coding for substrate versatility and sub-second drying. Beverage canning lines in China and flexible packaging converters in Germany absorb most volume, though EPA emission limits in the United States push some facilities toward abatement investments.
- Water-based:Glycol ether and surfactant-stabilized systems penetrate food packaging where volatile organic compound restrictions tighten. California and Northeast corridor plants seeking abatement cost avoidance are expanding procurement, though slower drying limits deployment on high-speed oriented polypropylene lines.
- UV-curable:Acrylate oligomer systems command premium positioning in electronics and pharmaceutical labeling where chemical resistance and fine-line resolution are critical.
- Pigment-based:Dispersed nanoparticle formulations overtake dye chemistries in outdoor and refrigerated supply chains requiring lightfastness.
Solvent-based formulations absorb the bulk of installed capacity; water-based alternatives are expanding most quickly.
Application:
Customer procurement patterns diverge sharply between high-volume commodity marking and precision variable-data coding.
- Packaging:Flexible film and corrugated board marking demands fast-drying, substrate-adherent formulations. Dairy and ready-meal converters in the Netherlands and Germany are qualifying low-migration ink systems under EU Regulation 10/2011, absorbing reformulation transition costs through supplier changeover programs.
- Coding:Lot numbers, expiration dates, and serial numbers require charge-conductive fluids compatible with piezoelectric printhead frequencies exceeding 100 kHz. Pharmaceutical track-and-trace mandates across multiple jurisdictions embed inkjet as default technology for unit-level compliance marking.
- Labeling:Pressure-sensitive and shrink-sleeve applications favor pigment dispersions for bleed resistance on synthetic stocks.
- Marking:Direct substrate imprinting on metals and rigid plastics faces substitution pressure from fiber laser systems where ink adhesion creates operational friction.
Packaging commands the deepest ink volume; coding applications are climbing the fastest on serialization mandate expansion.
End User:
Sector-specific regulatory frameworks govern formulation approval timelines and customer qualification intensity.
- Food & Beverage:Migration-tested formulations for dairy, snack, and beverage contact dominate R&D allocation. REACH substance evaluations on glycol ethers force parallel formulation tracks pending ECHA authorization outcomes.
- Pharmaceuticals:Unit-level serialization and aggregation requirements drive specification of validated ink systems with batch traceability documentation.
- Cosmetics:Fragrance and personal care marking favors UV-curable systems for chemical resistance against alcohol-based product contents.
- Electronics:Semiconductor and battery manufacturers in South Korea and Taiwan specify UV-inkjet for component marking where fine-line resolution and solvent-free processing are critical.
Food and beverage absorbs the bulk of installed capacity; electronics represents the steepest expansion trajectory on precision marking requirements.
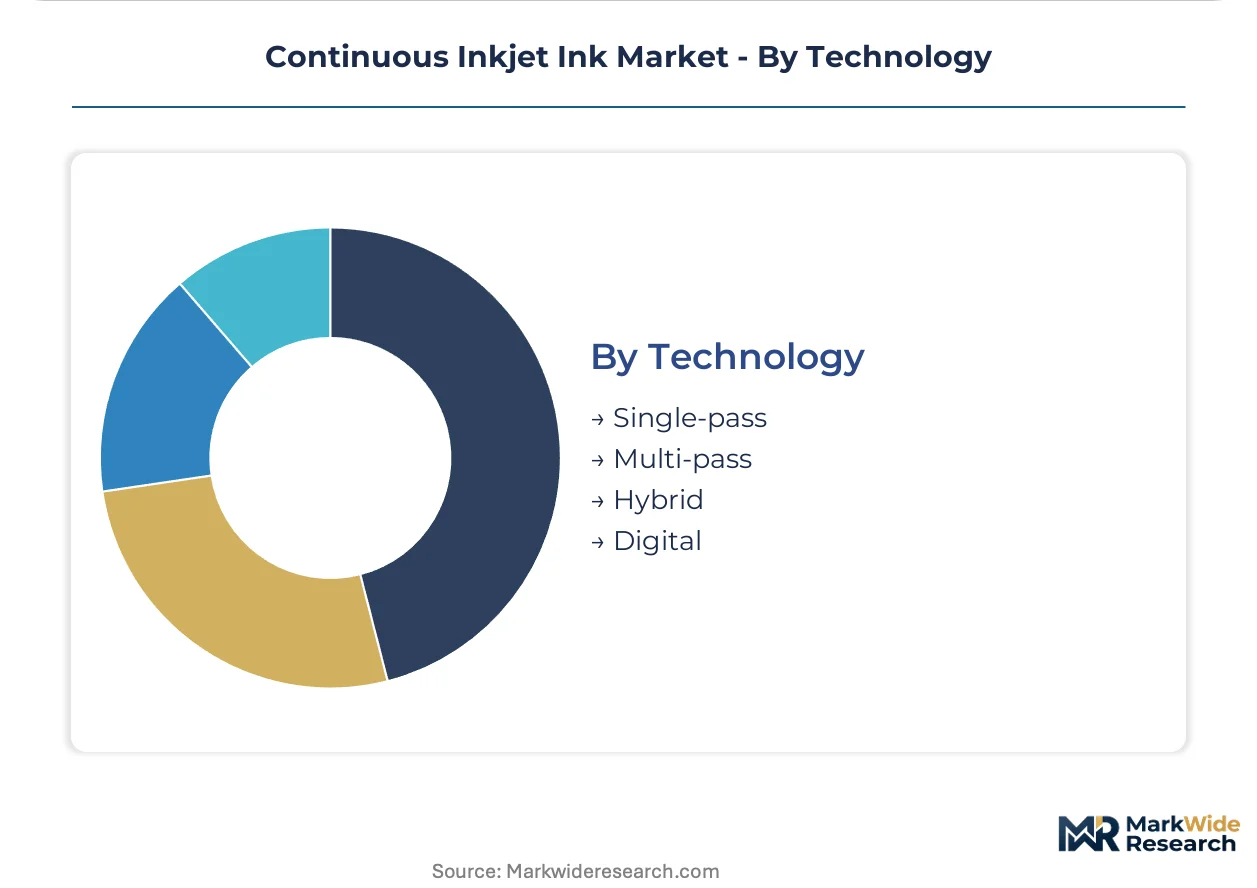
Technology:
Printhead hardware and fluid co-development is compressing standalone ink specification autonomy.
- Single-pass:Full-width array printing at production line speeds requires rheology-tuned formulations with precise viscosity and surface tension control. Wide-format corrugated and flexible film presses in the Yangtze River Delta are expanding captive consumption.
- Multi-pass:Scanning head architectures for lower-speed applications tolerate broader formulation windows, supporting legacy dye-based chemistries.
- Hybrid:Combined analog and digital systems demand ink compatibility with existing coating and drying infrastructure.
- Digital:Pure digital workflows without analog pre-treatment are gaining share in short-run pharmaceutical and cosmetic labeling.
Single-pass systems anchor current installed capacity; digital-only workflows are gaining share fastest on short-run flexibility demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate continuous inkjet printer manufacturing, drawing formulation suppliers into clustered supply relationships. Pearl River Delta export processing hubs generate parallel demand for MEK-based and pigment-based inks. Regulatory divergence across manufacturing jurisdictions is fragmenting formulation standards.
China
Domestic production of coding equipment in Suzhou and Shanghai expands captive ink consumption for export-oriented consumer goods. MEE emission standards on packaging plants in the Yangtze and Pearl River Delta clusters force reformulation toward lower-solvent alternatives. Shenzhen and Dongguan electronics assemblers specify UV-curable systems for component traceability marking.
Germany
Flexible packaging converters in the Ruhr region qualify low-migration ink systems under EU Regulation 10/2011 for dairy and ready-meal lines. REACH authorization requirements for glycol ethers and ketone solvents force parallel formulation tracks pending ECHA outcomes. Stuttgart and Munich automotive suppliers embed inkjet marking into component supply chains.
United States
Beverage canning lines in Wisconsin and California absorb solvent-based ink volume despite EPA emission constraints pushing some facilities toward abatement investments. California and Northeast corridor plants seeking VOC compliance cost avoidance expand water-based ink procurement. Chicago-area pharmaceutical serialization mandates embed inkjet as default compliance technology.
South Korea
Semiconductor and battery manufacturers in Gyeonggi Province specify UV-inkjet for component marking where chemical resistance and fine-line resolution are critical. MFDS pharmaceutical track-and-trace requirements drive validated ink system adoption with batch traceability documentation. Busan-Ulsan electronics clusters anchor precision marking demand growth.
India
Domestic coding equipment assembly in Pune and Chennai expands consumption of solvent-based formulations for FMCG export packaging. FSSAI food-contact migration limits accelerate low-migration ink qualification in dairy and snack processing plants. Gujarat pharmaceutical hubs adopt unit-level serialization marking under CDSCO guidance.
Continuous Inkjet Ink Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with equipment-integrated ink supply capturing recurring revenue in high-volume installations while independent formulators serve retrofit and specialty applications. The vendor base concentrates among printing equipment OEMs with captive ink portfolios and regional chemical specialists with formulation flexibility. Two strategic archetypes dominate: integrated hardware-ink systems vendors and independent specialty chemical suppliers. Competitive moves center on multi-year service contract bundling and geographic expansion through distributor qualification programs.
Among integrated systems vendors, Videojet Technologies, Markem-Imaje, and Domino Printing Sciences occupy positions that exemplify the hardware-captive ink model. These companies represent the archetype of installed-base monetization through recurring supply agreements, with North American and European operations anchoring their respective regional service infrastructures. Their market presence reflects the structural advantage of printhead-ink co-development in an industry where fluid compatibility determines operational reliability.
| Leading Market Players |
|---|
| Videojet Technologies |
| Markem-Imaje |
| Domino Printing Sciences |
| Hitachi Industrial Equipment Systems |
| Paul Leibinger |
| Linx Printing Technologies |
| KGK Jet |
| Squid Ink |
| Control Print |
| Others |
Supply Flow & Price Mechanics
Specialty dye and pigment feedstock costs cascade through formulation tiers, with German and Indian chemical manufacturers commanding premium positioning for REACH-compliant pigments while commodity solvent blends face compression in high-volume Chinese packaging clusters.
Pricing Analysis
Short lead-time premiums for REACH-authorized pigments separate expedited procurement from standard contract scheduling in European flexible packaging. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in solvent-based formulations is intensifying because MEE emission standards force abatement investments in Yangtze River Delta plants. Mid-sized converters in India's FMCG sector exhibit highest price sensitivity; pharmaceutical serialization mandates make European drug packaging buyers least sensitive.
Supply Chain Analysis
Formulation chemist scarcity in Western Europe and Japan constrains batch expansion capacity at specialty ink facilities. Supply concentrates in Germany for pigment synthesis, India for dye intermediates, and China for solvent blending and finished ink compounding. Raw material portfolios draw from acrylate oligomers, nanoparticle dispersions, and conductivity salts. Single-source vulnerability concentrates in piezoelectric printhead supply relationships. Distribution runs through equipment OEM captive networks and regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU REACH authorization timelines erect barrier-to-entry moats favoring incumbents with active substance dossiers and regulatory affairs bandwidth.
For Market Incumbents: Anchor recurring revenue through multi-year service contracts bundling hardware maintenance, ink supply, and remote diagnostics. Deepen backward integration into pigment dispersion capabilities to offset German chemical manufacturer pricing power. Laser marking substitution in rigid plastics and metals threatens permanent coding applications; counter with low-migration ink chemistry investments for sensitive food-contact segments. For New Entrants and Emerging Players: Water-based ink formulation expertise offers a technology-first wedge into California and Northeast corridor food packaging plants seeking VOC compliance cost avoidance. White-space targets include UV-curable electronics labeling for South Korean semiconductor manufacturers and refill ink systems for retrofit Chinese printer installations. Pursue distributor qualification programs in India's Pune and Chennai coding equipment assembly clusters. For Investors and Strategic Acquirers: ECHA authorization outcomes for glycol ethers and ketone solvents are the leading indicator that formulation portfolio segmentation will accelerate between legacy and next-generation alternatives. Long-term viability favors targets with active REACH dossiers and established pharmaceutical validation documentation. Watch for printhead-fluid co-development partnerships as signal of durable competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Authorization Investment | Secures pigment and solvent portfolio continuity for EU food packaging supply. |
| Water-Based Formulation Expansion | Captures California and Northeast corridor VOC compliance-driven substitution demand. |
| Printhead-Fluid Co-Development | Locks in operational reliability through piezoelectric supplier technical partnerships. |
| Per-Code Pricing Model Rollout | Concentrates recurring ink revenue in North American beverage and pharmaceutical plants. |
| Low-Migration Chemistry R&D | Addresses EU Regulation 10/2011 migration limits for dairy and ready-meal packaging. |
Methodological Framework
Independent corroboration across formulation chemists at German and Indian specialty chemical manufacturers, procurement leads at flexible packaging converters, and regulatory affairs directors at multinational ink producers underwrites the qualitative findings. Primary fieldwork encompassed technical R&D directors, plant managers at Yangtze River Delta compounding facilities, and distribution channel partners serving pharmaceutical serialization mandates. Secondary validation drew from ECHA substance evaluation databases, EPA emission standard filings, customs trade data for dye and pigment flows, and SEC disclosures from integrated equipment-ink vendors. Bottom-up volume estimates triangulated against top-down market sizing across formulation chemistry segments.
Rate-of-change decomposition isolated volume and value drivers across solvent-based, water-based, UV-curable, and pigment-based product categories over the projection horizon. Segmentation dimensions modeled include formulation chemistry, application requirements, end-user regulatory frameworks, and technology architectures. CAGRs derived from historical shipment data, installed base expansion rates, and substitution elasticity estimates for laser marking alternatives. Industry-specific forecast inputs incorporated REACH authorization timelines and pharmaceutical serialization mandate rollouts across jurisdictions.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting German-Indian pigment supply corridors, breakthrough printhead technologies obsoleting current fluid compatibility requirements, and ECHA accelerated substance restrictions beyond evaluated glycol ethers. Forecasts reflect assumptions about regulatory implementation pacing and equipment replacement cycles. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Flexographic Inks Market
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
Low-Odor Inkjet Inks for On-Line Food Coding in Aseptic Filling Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Squid Ink Market
Printing Inks
North America Ink Market
Printing Inks
Global Printing Blanket Market
Printing Inks
United States Printing Inks Market
Printing Inks
Global Digital Inks Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Anti-Counterfeit Printing Ink Market