
 Lithographic Printing Chemicals Market | 2026-2036
Lithographic Printing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Lithographic Printing Chemicals Market Analysis
The lithographic printing chemicals supply chain is recalibrating around a widening gap between premium UV-curable and commodity solvent-based formulations, with converters demanding shorter makeready times and lower energy curing. DIC Corporation leverages its integrated resin and pigment operations to control raw material quality across Asian markets. Siegwerk Druckfarben AG & Co. KGaA anchors its position through specialized low-migration ink systems for food-contact packaging. Sun Chemical competes on global manufacturing scale, operating production networks that span North America, Europe, and Asia-Pacific.
Lithographic printing chemicals encompass inks, fountain solutions, plate treatments, and pressroom cleaners formulated for offset lithography, a planographic process where image and non-image areas coexist on a single flat surface separated by the mutual repulsion of grease and water. These chemicals typically contain pigments or dyes at 15-40% concentration, vehicle resins, and additives such as driers or waxes, with viscosity specifications ranging from 30-100 Pa·s depending on application. The primary commercial purpose is to enable high-speed, high-fidelity reproduction of text and graphics on paper, board, and synthetic substrates for mass communication and product decoration. UV-curable technology captures expanding margin pools as brand owners mandate instant-dry, scratch-resistant finishes for premium packaging. Water-based formulations sustain volume leadership in commercial publishing applications where regulatory pressure on solvent emissions remains intense. Solvent-based chemistry occupies a shrinking but defended niche in specialized label and flexible packaging segments requiring adhesion to non-porous films.
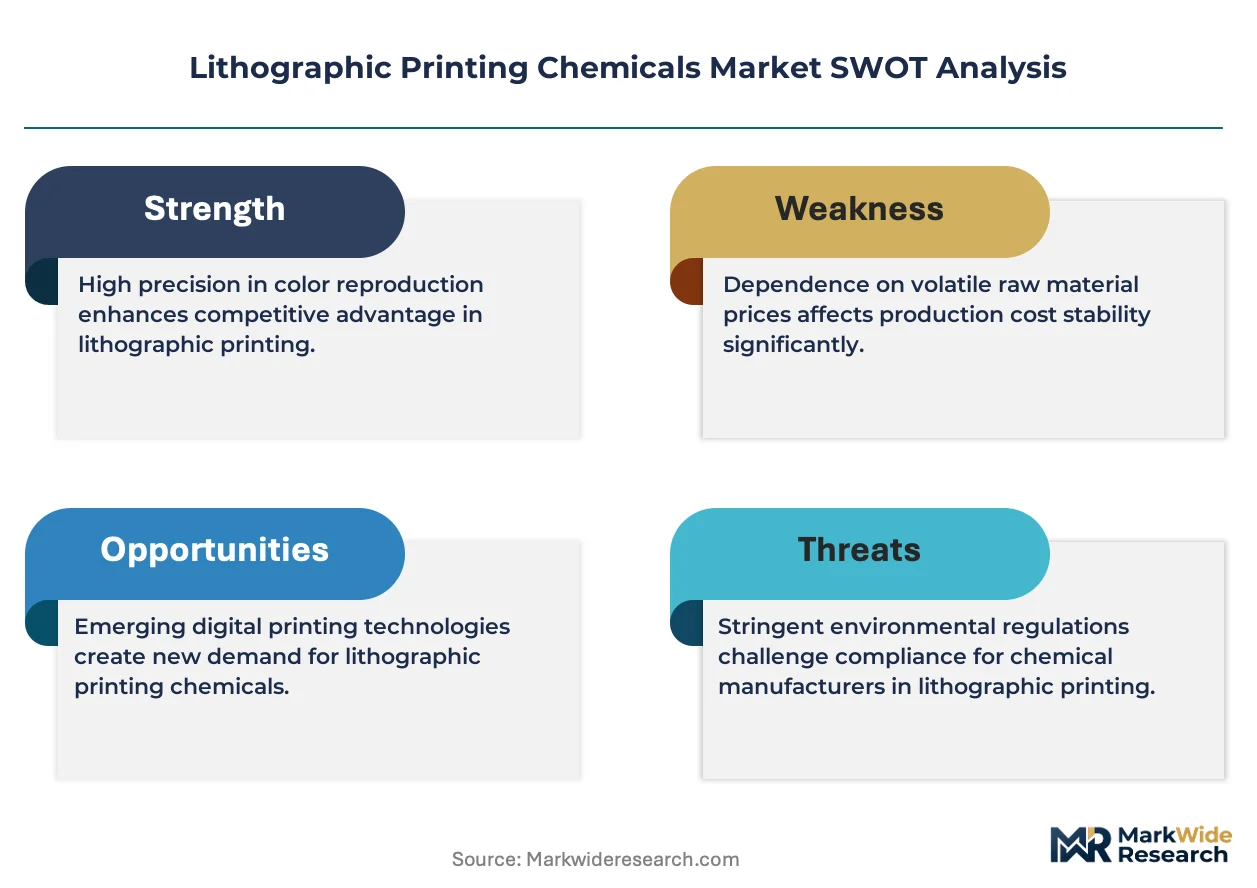
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based ink formulations in US manufacturing facilities, while REACH and the EU Green Deal in Europe mandate disclosure and substitution of Substances of Very High Concern in printing chemicals. China's MEE enforces progressively stricter VOC discharge limits for printing operations in the Yangtze River Delta and Pearl River Delta industrial clusters. Stakeholders must monitor whether dual carbon goals in China and evolving state-level air quality rules in California and Texas will accelerate capital redeployment toward electron beam or LED-UV curing infrastructure.
Market Dynamics
UV-curable ink chemistry is compressing conventional solvent-based margins as converters prioritize instant-dry finishes and reduced energy consumption. REACH disclosure mandates and EPA NESHAP thresholds are simultaneously raising compliance costs for legacy formulations while opening premium pricing tiers for compliant substitutes.
Growth Catalysts
- Food-contact packaging migration limits:Brand owners in Germany and the United States now specify low-migration UV formulations for direct-contact applications, pulling formulation upgrades across supplier portfolios.
- LED-UV curing hardware deployment:Press manufacturers in China are integrating LED-UV modules as standard equipment, expanding addressable demand for matched ink chemistry.
- MEE VOC discharge enforcement:China's Ministry of Ecology and Environment is tightening discharge permits in the Yangtze River Delta, forcing solvent-based volume toward compliant alternatives.
Market Restraints
- Photoinitiator supply concentration:Specialty photoinitiators for UV formulations concentrate among German and Japanese chemical suppliers, exposing converters to input cost volatility.
- Heatset web press installed base:North American publication printers retain substantial solvent-dependent heatset capacity, creating technical lock-in against rapid chemistry transitions.
- REACH authorization timelines:ECHA's substance evaluation delays for legacy pigment intermediates extend reformulation cycles beyond typical customer contract windows.
Strategic Opportunities
- Electron beam curing retrofit:EB technology eliminates photoinitiator dependence entirely, offering a chemistry pathway for ultra-low-migration flexible packaging in European dairy and meat segments.
- India commercial print modernization:Sheetfed operations in Maharashtra and Gujarat are replacing aging solvent-based systems, creating first-mover advantage for UV-curable suppliers establishing local blending.
- Biobased resin feedstocks:Vegetable-derived acrylate oligomers qualify for EU Green Deal procurement preferences, enabling premium positioning in public-sector print contracts.
Industry Challenges
- Colorimetric calibration expertise:UV formulations demand spectrophotometric profile management distinct from conventional density-based workflows, and skilled prepress technicians remain scarce in secondary print markets.
- Legacy fountain solution incompatibility:Hybrid shops running both conventional and UV inks face pressroom chemistry segregation costs and downtime penalties from cross-contamination incidents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithographic Printing Chemicals Market |
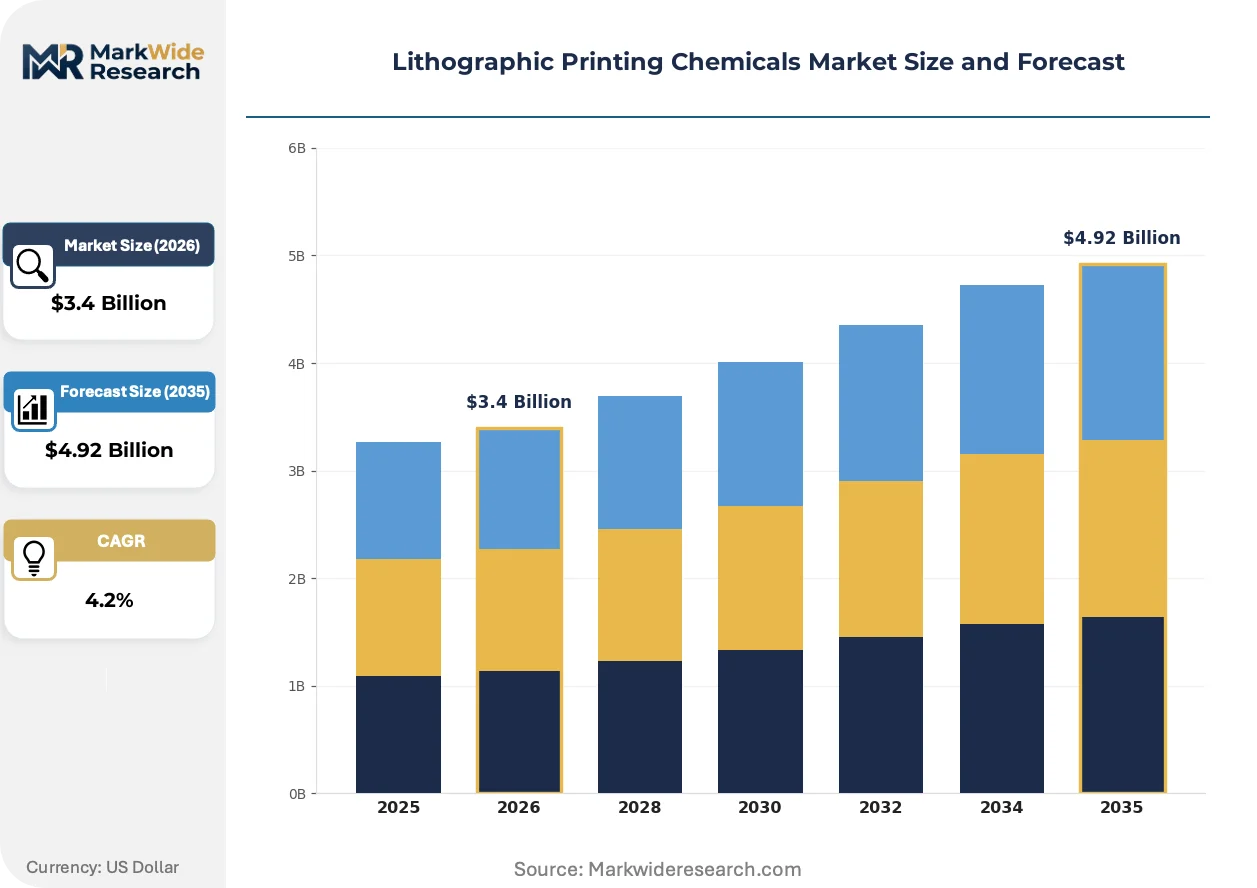
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $4.92 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inks, Coatings, Cleaners, Additives Application: Commercial Printing, Packaging, Labeling, Publishing End User: Publishers, Advertising Agencies, Print Service Providers, Packaging Companies Technology: Water-Based, Solvent-Based, UV-Curable, Conventional |
| Companies Covered | DIC Corporation, Siegwerk Druckfarben AG & Co. KGaA, T&K TOKA Corporation, Hubergroup USA, Sakata Inx Corporation, Toyo Ink Company, Sun Chemical, Tokyo Printing Ink Mfg Co. Ltd., Flint Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithographic Printing Chemicals Market Emerging Trajectories
LED-UV curing architecture is compressing the energy and space requirements of offset production, enabling chemistry suppliers to reformulate around narrower wavelength spectra. This convergence of hardware and material science is redrawing competitive boundaries between ink manufacturers and press OEMs.
Narrow-spectrum LED-UV photoinitiator packages are rewriting the economics of short-run packaging production. Mid-size folding carton converters in the United States are retrofitting single-color units with 395nm LED arrays, cutting curing energy draw by half. The technology is compressing makeready waste and enabling just-in-time production for seasonal brand campaigns previously uneconomical at conventional volumes.
REACH Annex XIV authorization expansion is forcing systematic substitution of bisphenol-based epoxy acrylates in food-contact applications. European ink formulators are accelerating aliphatic urethane acrylate development to maintain compliance without sacrificing adhesion to high-density polyethylene. The regulatory pressure is concentrating reformulation investment among suppliers with captive resin synthesis capabilities.
Brand-owner sustainability scorecards are reshaping procurement criteria for print packaging. Major beverage and personal care companies in Germany now require carbon-footprint disclosure across ink, coating, and substrate combinations. This behavioral shift is displacing spot-buying practices with multi-year formulation partnerships that lock in volume commitments against verified lifecycle data.
Lithographic Printing Chemicals Market Segmentation
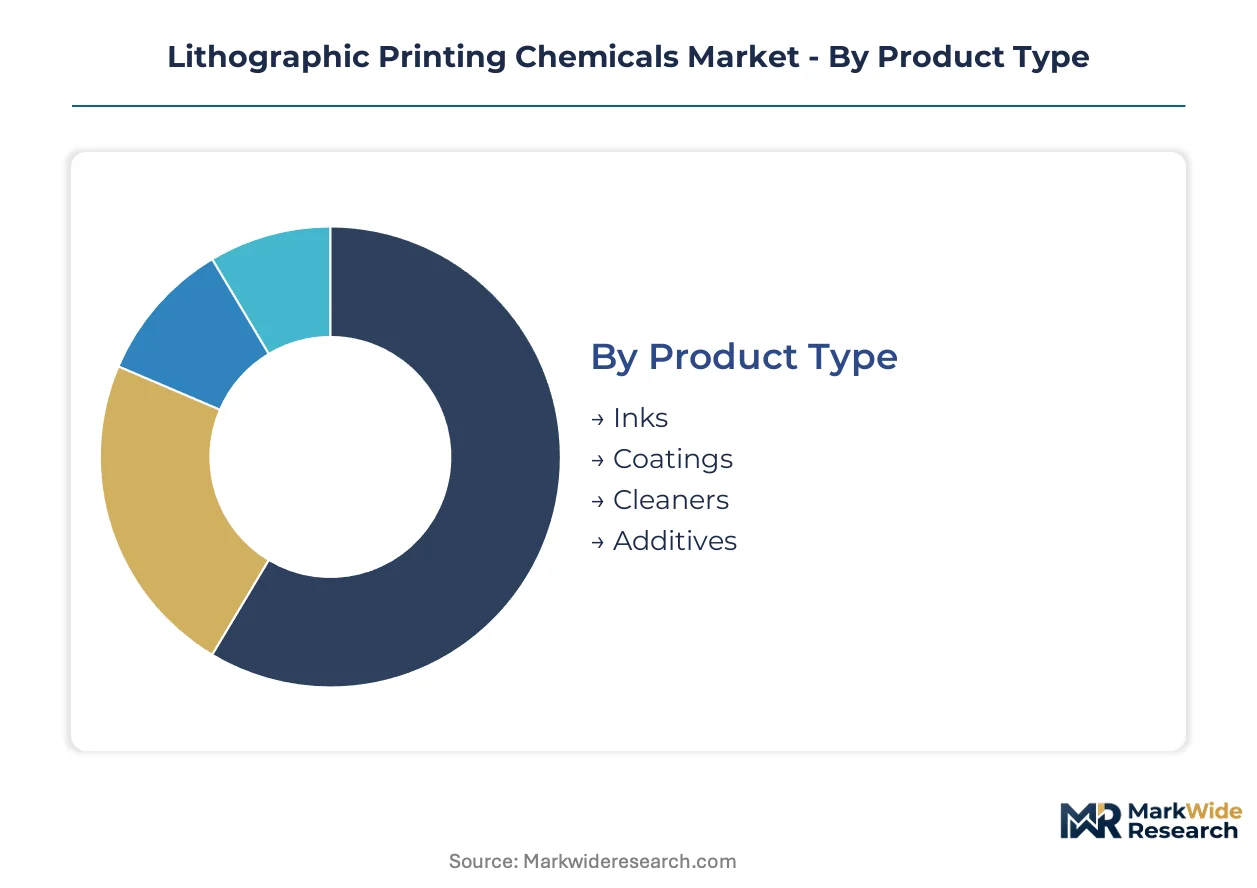
Converters in Germany, China, and the United States are fragmenting procurement across multiple chemistry platforms, forcing suppliers to maintain parallel formulation portfolios. Segmentation clarity enables targeted resource allocation toward UV-curable expansion while defending legacy positions in commercial publishing.
Product Type:
Supply concentration among integrated resin manufacturers favors ink producers with captive pigment operations over standalone coating or cleaner specialists.
- Inks:These formulations carry 15-40% pigment loading with viscosity specifications between 30-100 Pa·s, depending on press configuration. Demand concentrates in food-contact packaging across Germany and the United States, where brand owners now mandate low-migration UV formulations for direct-contact applications.
- Coatings:Overprint varnishes and protective finishes deliver scratch resistance and gloss control for premium packaging. Volume is climbing fastest in China's Yangtze River Delta, where MEE enforcement on VOC discharge is accelerating substitution of solvent-based alternatives.
- Cleaners:Pressroom maintenance chemistry removes ink and fountain solution residues from rollers and blankets.
- Additives:Driers, waxes, and rheology modifiers fine-tune ink performance for specific substrates and press speeds.
Today's leader: Inks. Tomorrow's challenger: Coatings.
Application:
Margin stratification across applications reflects diverging technical requirements and regulatory exposure.
- Commercial Printing:Sheetfed and heatset web operations produce marketing collateral, direct mail, and corporate stationery. Demand remains anchored in the United States, where North American publication printers retain substantial solvent-dependent heatset capacity creating technical lock-in against rapid chemistry transitions.
- Packaging:Folding cartons and corrugated containers require food-contact compliance and migration control. Brand owners in Germany now specify low-migration UV formulations for direct-contact dairy and meat packaging, pulling formulation upgrades across supplier portfolios.
- Labeling:Pressure-sensitive and cut-and-stack labels demand adhesion to non-porous films and specialized substrates.
- Publishing:Book and periodical production sustains water-based formulation volume where regulatory pressure on solvent emissions remains intense.
Packaging commands the steepest expansion trajectory as food-contact compliance tightens.
End User:
Procurement sophistication varies sharply between specification-driven brand owners and price-sensitive print brokers.
- Publishers:Magazine and book producers prioritize cost efficiency in long-run web operations.
- Advertising Agencies:Creative firms specify premium finishes for campaign materials and brand collateral.
- Print Service Providers:Commercial shops in Maharashtra and Gujarat are replacing aging solvent-based systems, creating first-mover advantage for UV-curable suppliers establishing local blending.
- Packaging Companies:Converters serving beverage and personal care sectors in Germany now require carbon-footprint disclosure across ink, coating, and substrate combinations.
Packaging companies are gaining procurement leverage through sustainability scorecards.
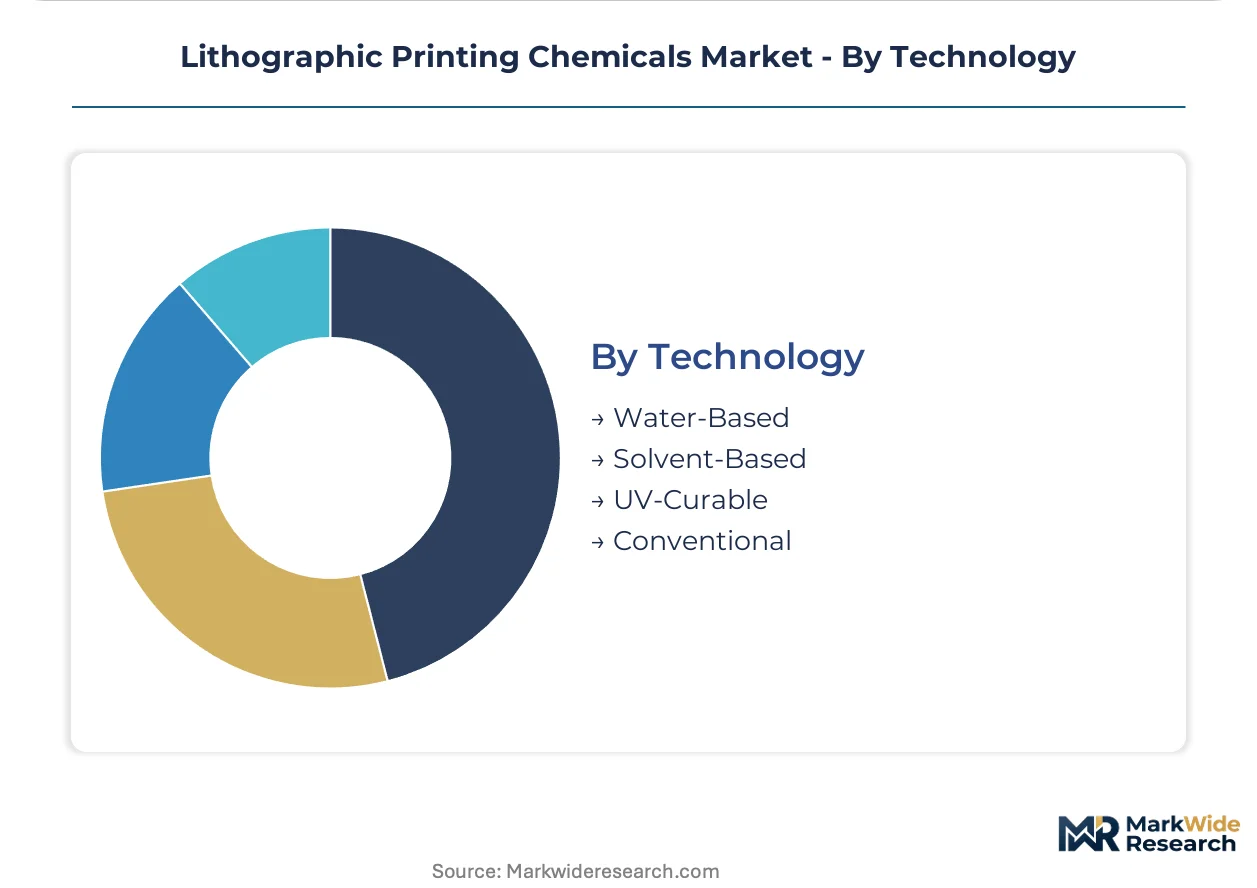
Technology:
Curing architecture determines energy consumption, throughput speed, and regulatory compliance exposure.
- UV-Curable:Photoinitiator-triggered polymerization delivers instant-dry, scratch-resistant finishes without solvent emission. LED-UV modules are becoming standard equipment on Chinese press manufacturing lines, expanding addressable demand for matched ink chemistry.
- Water-Based:Acrylic and polyurethane dispersions sustain volume leadership in commercial publishing applications. REACH and EPA NESHAP thresholds are raising compliance costs for legacy formulations while opening premium pricing tiers for compliant substitutes.
- Solvent-Based:Hydrocarbon and ester solvent systems retain niche positions in specialized label applications requiring adhesion to non-porous films.
- Conventional:Oxidative-drying vegetable oil formulations serve legacy sheetfed installations with minimal capital requirements.
UV-Curable is expanding most quickly. Water-Based defends installed volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's food-contact compliance mandates pull premium formulation upgrades faster than China's hardware-led LED-UV adoption. The United States retains substantial legacy heatset capacity, creating divergent transition timelines across major print economies.
United States
Publication printers in Wisconsin and Minnesota defend solvent-dependent heatset web capacity against rapid chemistry transitions. EPA NESHAP thresholds constrain solvent-based ink formulations in manufacturing facilities nationwide. The Chicago-Gary industrial corridor concentrates sheetfed operations serving brand owners now mandating carbon-footprint disclosure across ink and substrate combinations.
Germany
Brand owners specify low-migration UV formulations for direct-contact dairy and meat packaging applications. REACH Annex XIV authorization expansion forces systematic substitution of bisphenol-based epoxy acrylates in food-contact segments. The Rhine-Ruhr metropolitan region hosts dense concentrations of high-volume commercial sheetfed operations upgrading pressroom chemistry portfolios.
China
Press manufacturers integrate LED-UV modules as standard equipment, expanding addressable demand for matched ink chemistry. MEE enforces progressively stricter VOC discharge limits in the Yangtze River Delta and Pearl River Delta industrial clusters. Dongguan and Suzhou folding carton converters accelerate solvent-based substitution under tightening environmental permit conditions.
India
Sheetfed operations in Maharashtra and Gujarat replace aging solvent-based systems, creating first-mover positioning for UV-curable suppliers establishing local blending capabilities. BIS standards for printing ink safety create compliance benchmarks for import substitution strategies. The Ahmedabad-Vadodara industrial belt concentrates commercial print modernization investments targeting export packaging segments.
Japan
Specialty photoinitiator suppliers concentrate technical capabilities serving regional UV formulation demand. METI industrial standards guide sustainable chemistry substitution in packaging print applications. The Nagoya-Toyota manufacturing corridor sustains precision label and flexible packaging operations requiring adhesion to non-porous synthetic substrates.
Lithographic Printing Chemicals Market Vendor Landscape
Top-tier vendors anchor integrated resin and pigment operations, while mid-scale specialists compete on formulation customization for food-contact compliance. The supply base stratifies between captive raw material producers and standalone ink blenders dependent on merchant resin supply. Three archetypes dominate: integrated chemical conglomerates controlling upstream inputs, regional formulators with regulatory specialization, and coating specialists leveraging substrate expertise. Competitive moves concentrate on strategic partnerships with press OEMs and geographic expansion through local blending facilities.
Among Japanese chemical conglomerates, DIC Corporation and T&K TOKA Corporation exemplify integrated operations spanning resin synthesis through finished ink production. Siegwerk Druckfarben AG & Co. KGaA anchors the regulatory-specialist archetype with its German GmbH structure signaling technical formulation depth. Sun Chemical occupies a position representing global manufacturing scale across North American, European, and Asia-Pacific production networks. These three company structures illustrate how geographic origin and corporate form signal competitive positioning in a market where raw material control and compliance credentials determine procurement outcomes.
| Leading Market Players |
|---|
| DIC Corporation |
| Siegwerk Druckfarben AG & Co. KGaA |
| T&K TOKA Corporation |
| Hubergroup USA |
| Sakata Inx Corporation |
| Toyo Ink Company |
| Sun Chemical |
| Tokyo Printing Ink Mfg Co. Ltd. |
| Flint Group |
| Others |
Supply Flow & Price Mechanics
Captive resin synthesis among Japanese and German chemical conglomerates anchors both supply security and pricing power, insulating integrated ink formulators from photoinitiator cost volatility while forcing standalone blenders into merchant oligomer markets. This upstream control concentrates margin capture among DIC Corporation and Sun Chemical, whose in-house pigment operations buffer against REACH-driven intermediate shortages.
Pricing Analysis
Capacity additions in China are reshaping price floors for UV-curable formulations as domestic LED-UV press manufacturing expands matched ink demand. Three-tier pricing structure across premium low-migration, standard UV-curable, and economy water-based levels segments buyers by compliance requirements and volume scale. Cost compression in commodity solvent-based tiers intensifies because MEE enforcement accelerates converter migration to compliant alternatives. Brand owners in food-contact packaging demonstrate lowest price sensitivity, while commercial print brokers in India remain most cost-responsive.
Supply Chain Analysis
Dual-sourcing mandates from German packaging converters force qualification of at least two photoinitiator suppliers, complicating procurement for narrow-spectrum LED-UV formulations. Manufacturing concentrates in Germany, China, and Japan, with specialty photoinitiator synthesis anchored in German and Japanese chemical clusters. Formulation chemistry draws from acrylate oligomers, epoxy resins, and vegetable-derived feedstocks, creating dependency on petrochemical and biobased input cycles. Single-source vulnerability runs through German photoinitiator specialists for food-contact compliant grades. Distribution runs through regional blending facilities serving sheetfed and heatset web clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as brand-owner sustainability scorecards displace spot-buying with multi-year formulation partnerships anchored to verified lifecycle data.
For Market Incumbents: Extend captive resin capabilities into aliphatic urethane acrylate development to capture REACH Annex XIV substitution demand. Consolidate regional blending positions in Maharashtra and Gujarat before local competitors achieve BIS compliance scale. LED-UV wavelength standardization threatens formulation differentiation; deepen technical service capabilities in spectrophotometric profile management to defend premium positioning. For New Entrants and Emerging Players: Electron beam curing chemistry offers a technology-first wedge into European dairy and meat packaging segments seeking ultra-low-migration alternatives without photoinitiator dependence. Target India's Ahmedabad-Vadodara industrial belt for first-mover UV-curable blending, where solvent-based replacement creates procurement openness absent entrenched supplier relationships. Pursue co-development partnerships with Chinese press OEMs integrating LED-UV modules as standard equipment. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with regulatory specialization because REACH authorization timelines extend beyond typical customer contract windows, creating stranded value in compliant formulation portfolios. Focus on mid-scale European and Asian ink producers with captive resin synthesis and food-contact certification depth. Watch LED-UV hardware deployment rates in China's Yangtze River Delta as inflection indicator for matched chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive oligomer production insulates margin from REACH-driven intermediate volatility. |
| LED-UV Formulation Partnerships | Co-development with Chinese press OEMs locks in standard-equipment specification advantages. |
| Biobased Acrylate Development | Vegetable-derived feedstocks qualify for EU Green Deal procurement preferences in public-sector print. |
| Electron Beam Curing Retrofit | EB technology eliminates photoinitiator dependence for ultra-low-migration flexible packaging. |
| Regional Blending Expansion | Local formulation in India reduces logistics exposure and accelerates BIS compliance positioning. |
Methodological Framework
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market cluster through interviews with ink formulation chemists, packaging procurement managers at brand owners, press OEM technical directors, and commercial print operations heads. Secondary validation draws from EPA NESHAP filings, ECHA REACH registration databases, China MEE discharge permit records, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume estimates from regional press installations triangulate against top-down chemical consumption data.
Rate-of-change decomposition separates volume growth from value mix-shift across the projection horizon. Segmentation dimensions model product type, application, technology platform, and regional regulatory cluster. CAGRs derive from installed base turnover rates, converter capex cycles, and compliance-driven substitution elasticities. Key inputs include LED-UV hardware shipment data from Chinese press manufacturers and REACH authorization timelines for pigment intermediates.
The model holds under steady regulatory enforcement trajectories; deviation in MEE permit stringency or EPA NESHAP threshold adjustments would shift substitution timing. Forecasts reflect assumptions about brand-owner sustainability mandate diffusion and photoinitiator supply concentration persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Solvent-Based Inks Market
Printing Inks
Food Marking Inks Market
Printing Inks
Squid Ink Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
North America Ink Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Ink Resins Market
Printing Inks
Global Digital Inks Market