
 Global Flexographic Inks Market | 2026-2036
Global Flexographic Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexographic Inks Market Foresight
Buyer concentration among flexible packaging suppliers is expanding as multinational food brands consolidate vendor lists and demand single-source ink accountability. Sun Chemical leverages its pigment manufacturing network to control raw material costs across regions. Hubergroup anchors European compliance leadership through dedicated regulatory laboratories in Germany. Flint Group competes on UV curable scale with dedicated production lines serving corrugated and label segments.
Flexographic inks are low-viscosity liquid formulations engineered for transfer via flexible photopolymer plates onto porous and non-porous substrates at press speeds exceeding 300 meters per minute; their primary purpose is high-volume decorative and informational printing for consumer goods packaging. Water-based formulations lead volume in corrugated cardboard applications where absorbency supports fast drying without solvent recovery systems. UV curable inks represent the fastest-expanding chemistry class in labels and tags due to instant polymerization enabling inline finishing and reduced work-in-process inventory. Solvent-based systems retain margin concentration in plastic films where adhesion to polyethylene and polypropylene substrates remains technically demanding.
EPA regulations in the United States enforce volatile organic compound emission thresholds that push converters toward water-based and electron beam curable alternatives. ECHA maintains REACH substance restrictions that disqualify certain photoinitiators and pigment intermediates from EU market access. China's MEE enforces dual carbon goals that tighten manufacturing emissions standards for solvent-based ink plants. Stakeholders must monitor regulatory divergence across these jurisdictions when standardizing product portfolios versus maintaining region-specific formulations.
Market Dynamics
Food-grade compliance mandates from multinational brands are consolidating vendor relationships and forcing ink suppliers to absorb full regulatory accountability across entire packaging portfolios.
Growth Catalysts
- EU Green Deal packaging rules:Circular economy targets are mandating recyclable ink-substrate combinations that favor water-based chemistries in corrugated applications across Germany, France, and Italy.
- UV LED curing systems:Energy efficiency improvements and instant polymerization capabilities are displacing thermal drying infrastructure in label and narrow-web operations.
- China's flexible packaging cluster expansion:Zhejiang and Guangdong provinces are concentrating film converting capacity that demands solvent-based ink volumes for polyethylene and polypropylene adhesion.
Market Restraints
- Pigment cost volatility:Titanium dioxide and organic pigment intermediate supply from Chinese manufacturers creates input cost instability for all ink chemistry classes.
- Photoinitiator supply concentration:German and Japanese specialty chemical producers control UV curable raw material flows, creating bottleneck risk for converters scaling UV operations.
- Substrate adhesion limitations:Water-based formulations face technical barriers on non-porous films that solvent systems solve, slowing complete chemistry transition in plastic packaging.
Strategic Opportunities
- India's food packaging formalization:FSSAI enforcement expansion and organized retail growth are creating first-mover advantage for compliant ink suppliers in Mumbai and Delhi NCR converting clusters.
- Electron beam curing convergence:EB technology paired with flexographic presses eliminates photoinitiator dependency entirely, opening food-contact applications with zero migration risk.
- Digital hybrid integration:Combining flexographic base printing with inkjet variable data enables mass customization for pharmaceutical serialization and promotional packaging.
Industry Challenges
- Colorimetric technician scarcity:Specialized expertise in spot color matching across water-based, UV, and solvent chemistries is concentrating at established suppliers, constraining new market entrants.
- Dual chemistry production lines:Converters maintaining parallel solvent and water-based capabilities face capital intensity for emission control systems and drying infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexographic Inks Market |
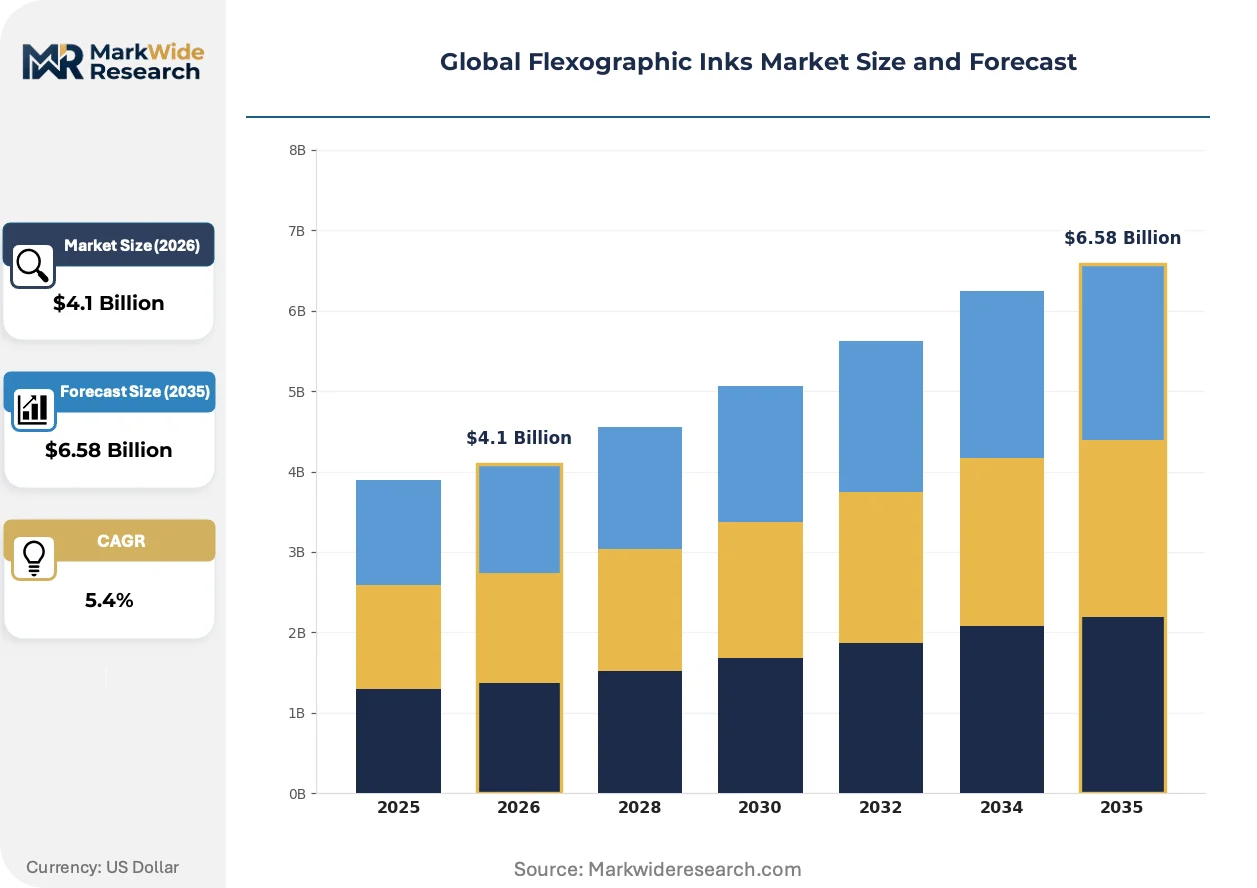
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Solvent-Based, Water-Based, UV Curable, Electron Beam Curable, Hot Melt Printing Application: Food Packaging, Corrugated Cardboard, Labels & Tags, Folding Cartons, Plastic Films End User Industry: Packaging Manufacturers, Printing Houses, Label Producers, Flexible Packaging Suppliers, Commercial Printers Distribution Channel: Direct Sales, Distributors & Dealers, Online Retailers, Wholesalers |
| Companies Covered | Toyo Ink, Hubergroup, Sun Chemical, Wikoff Color Corporation, Zeller+Gmelin, Flint Group, Sakata INX Corporation, T&K TOKA, Siegwerk Druckfarben, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexographic Inks Market Shifts & Advancements
Reformulation chemistry and curing technology are compressing production cycles while regulatory pressure on volatile compounds is redrawing competitive boundaries between ink classes.
UV LED curing systems are electrifying flexographic operations by eliminating thermal drying stages and enabling inline finishing on narrow-web presses. Pharmaceutical and cosmetics label converters in Switzerland and Germany are adopting these systems fastest. The technology is compressing work-in-process inventory cycles from hours to minutes while reducing energy consumption footprints.
REACH substance restrictions from ECHA are disqualifying specific photoinitiators and pigment intermediates from EU market access. Ink suppliers must maintain parallel formulation portfolios or absorb reformulation costs for European compliance. Labels and food-contact packaging segments are responding fastest with dedicated regulatory laboratories and pre-market substance screening protocols.
Single-source accountability contracts are consolidating procurement relationships as multinational food brands reduce approved vendor lists from multiple ink suppliers to one accountable partner. Flexible packaging converters in the United States and Germany are absorbing full compliance liability that previously sat with brand owners. This concentration is most visible in ready-meal and snack food segments where packaging failure triggers immediate supply chain penalties.
Global Flexographic Inks Market Segmentation
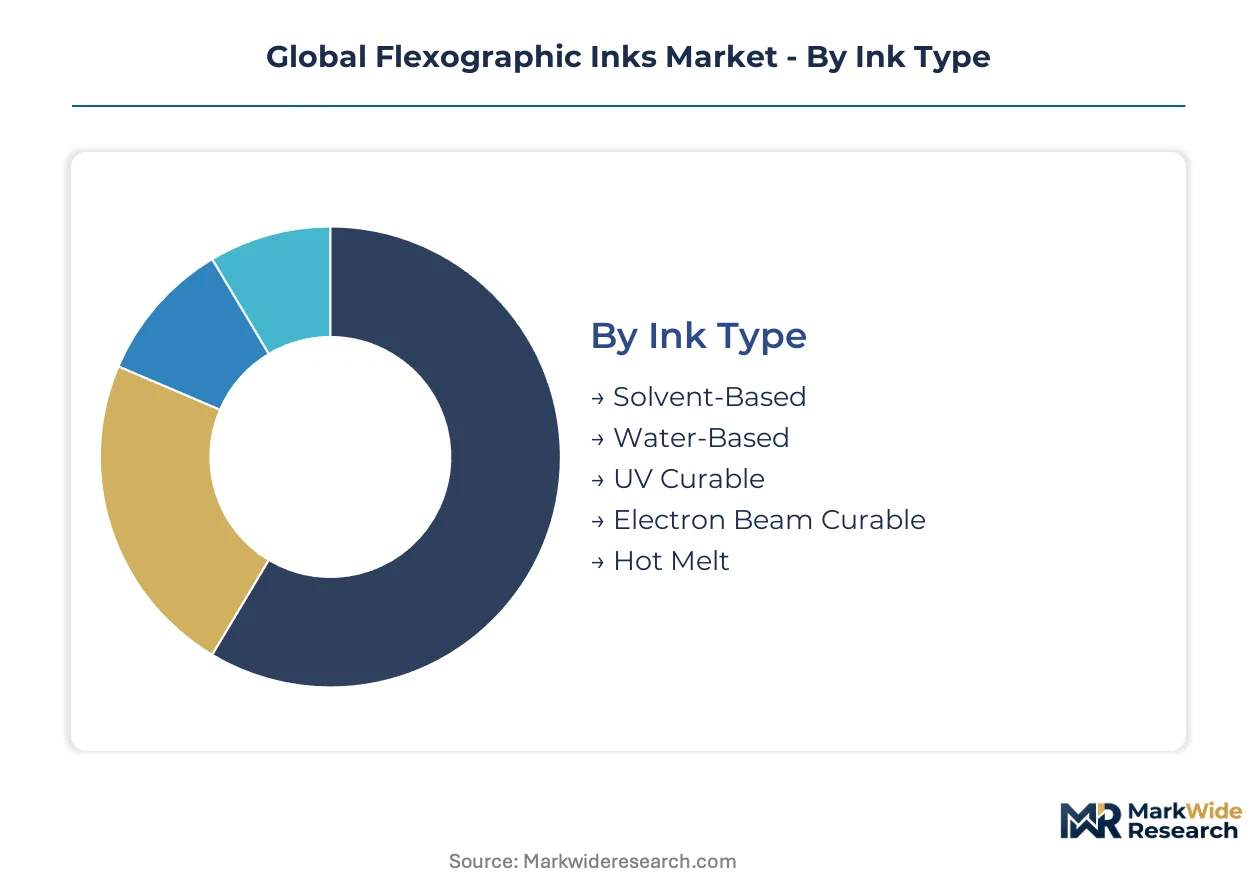
Flexographic ink purchasing patterns diverge sharply between high-volume commodity buyers and premium specification-driven customers. Chemistry selection, substrate compatibility requirements, and regulatory exposure create distinct commercial segments with different margin profiles and supplier relationship structures.
Ink Type:
Water-based formulations command volume leadership while UV curable systems capture premium pricing and fastest expansion.
- Solvent-Based:These formulations rely on organic solvents to dissolve resins and pigments, delivering superior adhesion to non-porous polyethylene and polypropylene films. Demand concentrates in China's Zhejiang and Guangdong flexible packaging clusters where MEE emissions standards are tightening but solvent systems retain technical necessity for film printing.
- Water-Based:Acrylic and polyurethane dispersions in water carriers serve corrugated cardboard applications where substrate absorbency enables rapid drying without thermal infrastructure. Germany's corrugated sector leads European adoption driven by EU Green Deal circular economy mandates for recyclable packaging combinations.
- UV Curable:Photoinitiator-triggered polymerization delivers instant curing for labels and narrow-web applications. Swiss pharmaceutical label converters are adopting UV LED systems fastest for inline finishing capabilities.
- Electron Beam Curable:High-energy electron beam polymerization eliminates photoinitiator migration risks entirely. Food-contact applications with zero migration tolerance are driving pilot deployments.
- Hot Melt:Thermoplastic formulations solidify upon cooling for specialized coating applications. Niche demand sits with barrier coating segments requiring solvent-free deposition.
Mature deployment sits with solvent-based systems in legacy film converting. Newer deployment is concentrated in electron beam curing for food-contact safety applications.
Printing Application:
Segment economics track substrate value and regulatory scrutiny intensity rather than pure print volume.
- Food Packaging:Direct and indirect food-contact applications demand full FDA, EFSA, and FSSAI compliance with migration testing documentation. Multinational brand consolidation of vendor lists is concentrating accountability on fewer ink suppliers across ready-meal and snack segments.
- Corrugated Cardboard:Porous kraft and recycled fiber substrates accommodate water-based chemistries without drying bottlenecks. E-commerce shipping box demand is expanding corrugated print capacity in the United States and Germany.
- Labels & Tags:Pressure-sensitive and shrink-sleeve applications require precise color matching across synthetic and paper facestocks. UV LED curing adoption is compressing work-in-process cycles from hours to minutes.
- Folding Cartons:Solid bleached sulfate and coated recycled board applications serve cosmetics and pharmaceutical secondary packaging. Premium color gamut requirements favor UV curable systems for brand differentiation.
- Plastic Films:Biaxially oriented polypropylene and polyethylene terephthalate substrates demand specialized adhesion promoters and surface treatment protocols. Technical barriers slow water-based substitution in this segment.
Regulatory intensity peaks in food packaging where brand liability concentrates. Operational efficiency gains are clustering in labels and tags with UV LED infrastructure.
End User Industry:
Customer scale and technical capability determine whether ink supply flows direct or through distribution intermediaries.
- Packaging Manufacturers:Integrated converters with in-house prepress and platemaking capabilities purchase ink in bulk tanker quantities. Major food brand contracts drive specification standardization across their plant networks.
- Printing Houses:Commercial sheetfed and web operations with flexographic satellite units serve regional brand accounts. Colorimetric technician scarcity constrains their spot color matching capabilities.
- Label Producers:Narrow-web specialists with UV LED curing infrastructure focus on pharmaceutical and cosmetics serialization requirements. Digital hybrid integration with inkjet variable data is expanding their service scope.
- Flexible Packaging Suppliers:Film converting specialists handling multilayer laminations and pouches require solvent-based adhesion expertise. REACH and EPA emission thresholds are forcing dual chemistry production line investments.
- Commercial Printers:Generalist operations with mixed equipment portfolios purchase through distributors for inventory flexibility. Price volatility in titanium dioxide pigments pressures their margin management.
Technical depth concentrates in packaging manufacturers and flexible packaging suppliers. Distribution dependency runs highest among commercial printers with fragmented equipment bases.
Distribution Channel:
Channel selection tracks order scale, technical service requirements, and geographic coverage needs.
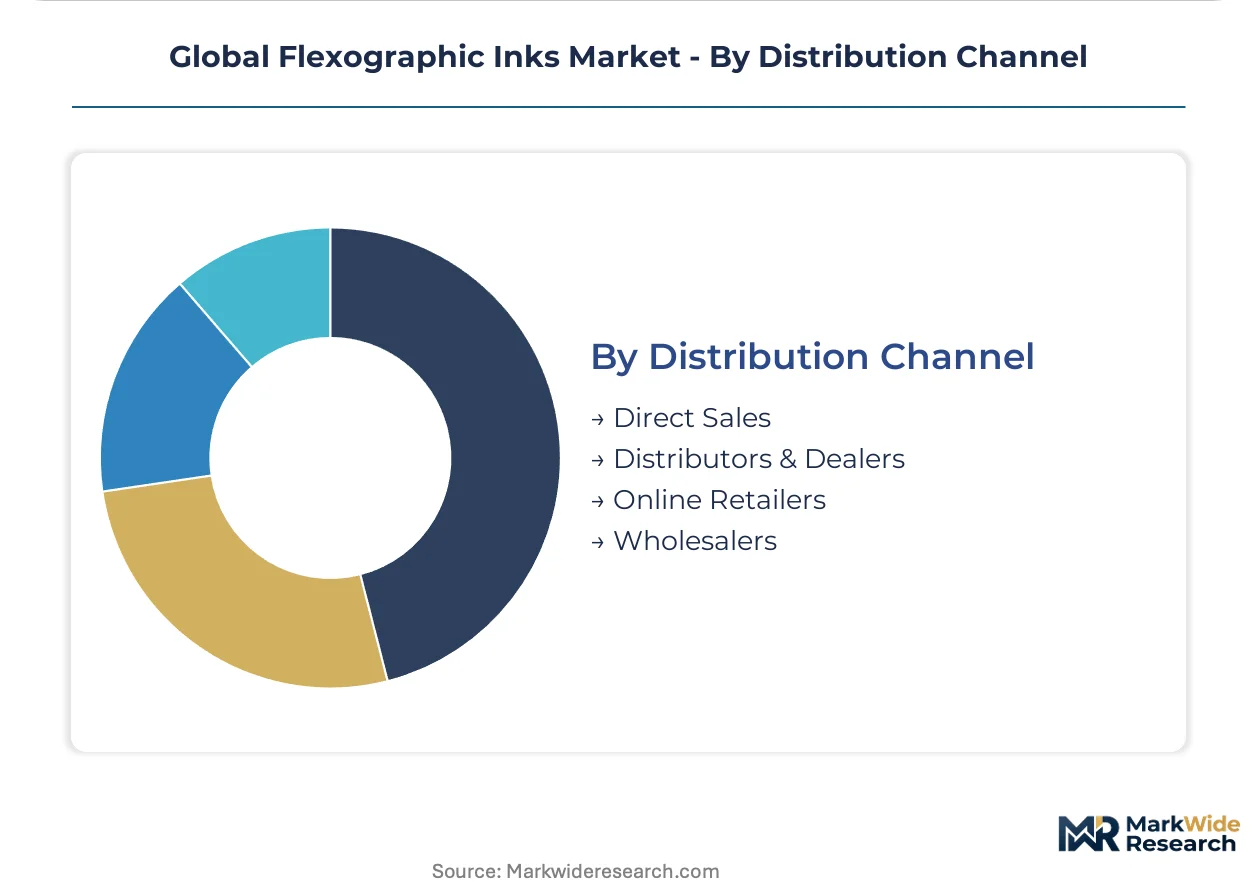
- Direct Sales:Tanker and tote deliveries from manufacturer to converter with dedicated technical service support. Major packaging manufacturers with national plant networks negotiate frame contracts with volume commitments.
- Distributors & Dealers:Regional inventory stocking with local color matching and platemaking support. Mid-scale printing houses rely on distributor technical service for spot color formulation.
- Online Retailers:Small-format packaging and specialty ink sales for prototype and short-run applications. Limited penetration due to technical consultation requirements for substrate matching.
- Wholesalers:Bulk breaking and logistics consolidation for remote geographic markets. Secondary role in established flexographic markets with mature direct sales infrastructure.
Relationship intensity peaks in direct sales with embedded technical service. Transactional efficiency dominates online and wholesale channels with minimal specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States where the largest packaging print clusters operate. Flexible packaging suppliers in these markets are scaling orders for food-grade compliant inks. Regulatory divergence across EPA, REACH, and MEE jurisdictions is forcing suppliers to maintain parallel formulation portfolios.
Germany
Corrugated cardboard producers drive water-based ink volumes as EU Green Deal circular economy mandates favor recyclable packaging combinations. ECHA maintains REACH substance restrictions that disqualify specific photoinitiators from market access. Hubergroup anchors European compliance leadership through dedicated regulatory laboratories serving converters across Bavaria and North Rhine-Westphalia.
China
Zhejiang and Guangdong provinces concentrate flexible packaging film converting capacity demanding solvent-based ink volumes for polyethylene and polypropylene adhesion. MEE enforces dual carbon goals that tighten manufacturing emissions standards for solvent-based ink plants. The Yangtze River Delta and Pearl River Delta clusters host the country's largest packaging print infrastructure.
United States
E-commerce shipping box demand expands corrugated print capacity requiring water-based formulations without solvent recovery systems. EPA regulations enforce volatile organic compound emission thresholds pushing converters toward water-based and electron beam curable alternatives. The Midwest packaging corridor and Southeast converting clusters concentrate national flexographic press capacity.
Switzerland
Pharmaceutical and cosmetics label converters adopt UV LED curing systems fastest for inline finishing capabilities. Swissmedic maintains stringent migration testing protocols for food-contact and pharmaceutical packaging applications. Basel and Zurich host specialized narrow-web operations serving premium brand accounts across Europe.
India
FSSAI enforcement expansion and organized retail growth create first-mover advantage for compliant ink suppliers. Mumbai and Delhi NCR converting clusters formalize food packaging standards previously governed by informal quality norms. Maharashtra and Gujarat states concentrate flexible packaging manufacturing serving domestic FMCG brand consolidation.
Global Flexographic Inks Market Competitive Landscape
European producers anchor one tier; Japanese specialists hold differentiated positions in photoinitiator-triggered formulations. The vendor base organizes around three tiers: integrated pigment manufacturers with captive raw material supply, regional formulators with regulatory laboratory infrastructure, and narrow-web specialists with UV LED curing expertise. Consolidation pressures intensify as multinational food brands reduce approved vendor lists from multiple suppliers to single-source accountability partners. Strategic moves cluster on backward integration into pigment manufacturing and geographic expansion through distributor network acquisition.
Within the integrated chemistry tier, Sun Chemical exemplifies upstream control over raw material costs through captive pigment production networks. Hubergroup occupies a position representing European compliance leadership with dedicated regulatory infrastructure. Flint Group anchors the UV curable scale segment with production lines serving corrugated and label applications. These three entities collectively illustrate how competitive positioning diverges between cost control, regulatory certification, and curing technology specialization.
| Leading Market Players |
|---|
| Toyo Ink |
| Hubergroup |
| Sun Chemical |
| Wikoff Color Corporation |
| Zeller+Gmelin |
| Flint Group |
| Sakata INX Corporation |
| T&K TOKA |
| Siegwerk Druckfarben |
| Others |
Supply & Pricing Matrix
Multinational flexible packaging suppliers with consolidated vendor lists command contract-based long-term offtake agreements that anchor pricing stability across water-based, UV curable, and solvent-based tiers. Their volume concentration forces ink manufacturers to absorb pigment cost volatility rather than pass through titanium dioxide and organic intermediate fluctuations.
Pricing Analysis
High-volume corrugated converters purchasing water-based formulations in bulk tanker quantities capture commodity-scale pricing, while narrow-web label specialists buying UV curable systems in smaller tote volumes pay premium-mid-economy pricing differentiation driven by photoinitiator certification tiers and inline finishing capabilities. Price differentiation separates REACH-compliant EU formulations from standard export grades. Cost compression in solvent-based tiers is intensifying because MEE emissions compliance adds abatement infrastructure burdens. Commercial printers with fragmented equipment bases exhibit highest price sensitivity; pharmaceutical label converters with serialization mandates show lowest.
Supply Chain Analysis
REACH substance restrictions and FDA food-contact certifications gate supplier qualification, filtering raw material sourcing to pre-approved pigment and photoinitiator producers in Germany, China, and Japan. Formulation chemistry draws from titanium dioxide feedstock concentrated in Chinese chloride-process plants, acrylic resin networks in Germany and the United States, and photoinitiator specialty production anchored in German and Japanese chemical corridors. Single-source vulnerability sits with photoinitiator supply from German and Japanese producers. Distribution runs through direct sales with embedded technical service for major packaging manufacturers, supplemented by regional distributors for mid-scale printing houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoinitiator supply concentration from German and Japanese specialty chemical producers props pricing power for UV curable formulations, constraining converter expansion until alternative curing technologies achieve scale.
For Market Incumbents: Extend regulatory laboratory infrastructure across multiple jurisdictions to preempt ECHA, EPA, and MEE substance restriction divergence. Absorb reformulation costs for multinational food brands consolidating vendor lists rather than cede share to competitors with captive compliance capabilities. Prioritize backward integration into titanium dioxide dispersion processing to offset Chinese pigment intermediate volatility.
For New Entrants and Emerging Players: Distributor networks with regional color matching and platemaking support represent the most accessible entry channel for building converter relationships without capital-intensive direct sales infrastructure. Target India's Mumbai and Delhi NCR converting clusters where FSSAI enforcement expansion creates first-mover advantage for compliant ink suppliers against informal quality norms. Lead with electron beam curing formulations to bypass photoinitiator supply bottlenecks entirely.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional formulators with regulatory laboratory infrastructure in Germany and regulatory certification depth in India. Long-term viability hinges on positioning for food-grade compliance consolidation as multinational brands reduce approved vendor lists. Watch UV LED curing equipment installation rates at Swiss and German pharmaceutical label converters as inflection indicator for photoinitiator demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Manufacturing | Sun Chemical's captive production network demonstrates raw material cost control across regional formulation plants. |
| Regulatory Laboratory Expansion | Hubergroup's dedicated German facilities anchor REACH compliance leadership for European converter accounts. |
| UV LED Curing Infrastructure Deployment | Swiss pharmaceutical label converters compress work-in-process cycles from hours to minutes with inline finishing. |
| Electron Beam Curing Pilot Programs | Food-contact applications with zero migration tolerance drive pilot deployments eliminating photoinitiator dependency. |
| Digital Hybrid Integration | Combining flexographic base printing with inkjet variable data enables pharmaceutical serialization compliance. |
Research Methodology
Independent corroboration across regulatory affairs directors at ink manufacturers, procurement leads at flexible packaging converters, and technical service managers at distributor networks underwrites the qualitative findings. Primary interviews with plant managers at corrugated and film converting facilities, R&D directors overseeing reformulation chemistry, and channel partners managing regional inventory combined with secondary validation from ECHA substance restriction databases, EPA emission threshold filings, and customs trade data for titanium dioxide and photoinitiator flows. Bottom-up press capacity estimates and top-down packaging print value triangulation anchored volume assessments.
Comparable historical periods spanning pre-REACH and post-EU Green Deal implementation anchored the forecast window to regulatory regime shifts. The analytical framework modeled chemistry class, substrate application, end-use industry vertical, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level demand elasticity to packaging print output growth and regulatory compliance cost pass-through rates. Pigment cost volatility indices and photoinitiator supply concentration metrics fed industry-specific forecast inputs.
Caveats apply where ECHA substance restriction expansions, MEE emissions enforcement intensification, or titanium dioxide supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory divergence persistence and curing technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Water-Based Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Global Digital Inks Market
Printing Inks
Lithography Inks Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
UV Cured Inks Market
Printing Inks
Ink Additives Market
Printing Inks
Ink Resins Market
Printing Inks
Food Grade Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Molecular Ink Market