
 UV Cured Inks Market | 2026-2036
UV Cured Inks Market Size, Share, and Industry Trends Forecast 2026-2036
UV Cured Inks Market Analytics
China is fragmenting as domestic ink producers expand UV capacity to serve regional packaging clusters. Sun Chemical leverages its pigment supply chain to sustain cost advantages across Asia-Pacific flexo operations. Siegwerk Druckfarben AG & Co. KGaA anchors European label demand through specialized low-migration formulations for food contact.
UV cured inks are photopolymerizable formulations containing oligomers, monomers, photoinitiators, and colorants that polymerize instantly under ultraviolet or LED UV radiation, eliminating volatile organic compound emissions and enabling inline processing on high-speed presses. LED UV technology leads technology adoption due to reduced energy consumption and cooler substrate temperatures, while digital inks represent the fastest-growing product type as on-demand short-run printing displaces conventional analog workflows. Packaging dominates application demand, with premium cosmetic and pharmaceutical segments generating concentrated margin pools for compliant ink suppliers.
EPA VOC regulations and REACH restrictions on hazardous photoinitiators reshape formulation requirements across North American and European markets, compelling reformulation investments. FDA indirect food contact standards and EU Printing Ink Regulation further tighten compliance thresholds for packaging applications. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D spending with emerging substance restrictions.
Market Dynamics
LED UV technology is collapsing traditional mercury-arc curing cycles, forcing packaging converters to reconfigure press lines for instant polymerization while EPA and REACH frameworks eliminate solvent-based alternatives entirely.
Growth Catalysts
- REACH VOC Restrictions:European converters face mandatory solvent reduction timelines, accelerating UV ink retrofit investments across label and flexible packaging operations.
- LED UV Energy Efficiency:Print houses in Germany and Japan reduce curing energy consumption by over sixty percent versus mercury arc, shortening payback periods for capital upgrades.
- Food Contact Compliance:FDA indirect food additive regulations and EU Printing Ink Regulation drive demand for low-migration formulations in dairy and confectionery packaging segments.
Market Restraints
- Photoinitiator Supply Concentration:Specialty photoinitiator production clusters in Chinese chemical parks, exposing formulators to export license volatility and input cost spikes.
- Substrate Compatibility Limits:Heat-sensitive films and lightweight papers suffer dimensional instability under conventional UV output, restricting application breadth in flexible packaging.
- Mercury Arc Stranded Assets:Press owners with recent mercury-arc installations face accelerated obsolescence before depreciation cycles complete, dampening near-term upgrade willingness.
Strategic Opportunities
- India Packaging Clusters:Domestic flexible packaging growth around Mumbai and Ahmedabad outpaces local UV ink supply, creating white space for technical service-intensive entrants.
- Digital-Embellishment Convergence:Hybrid presses combining inkjet variable data with UV screen white and metallic effects unlock premium cosmetic and spirits label applications.
- EU Green Deal Procurement Mandates:Public sector print purchasing specifications increasingly require verified low-carbon curing processes, privileging LED UV-certified suppliers.
Industry Challenges
- Photoinitiator Toxicology Expertise Gap:Formulation chemists with combined UV polymerization and food contact migration modeling capabilities remain scarce across mid-tier ink operations.
- Press Retrofit Integration Complexity:Legacy flexo and offset installations require mechanical modifications for LED UV narrow-waveband output, extending commissioning timelines and disrupting production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Cured Inks Market |
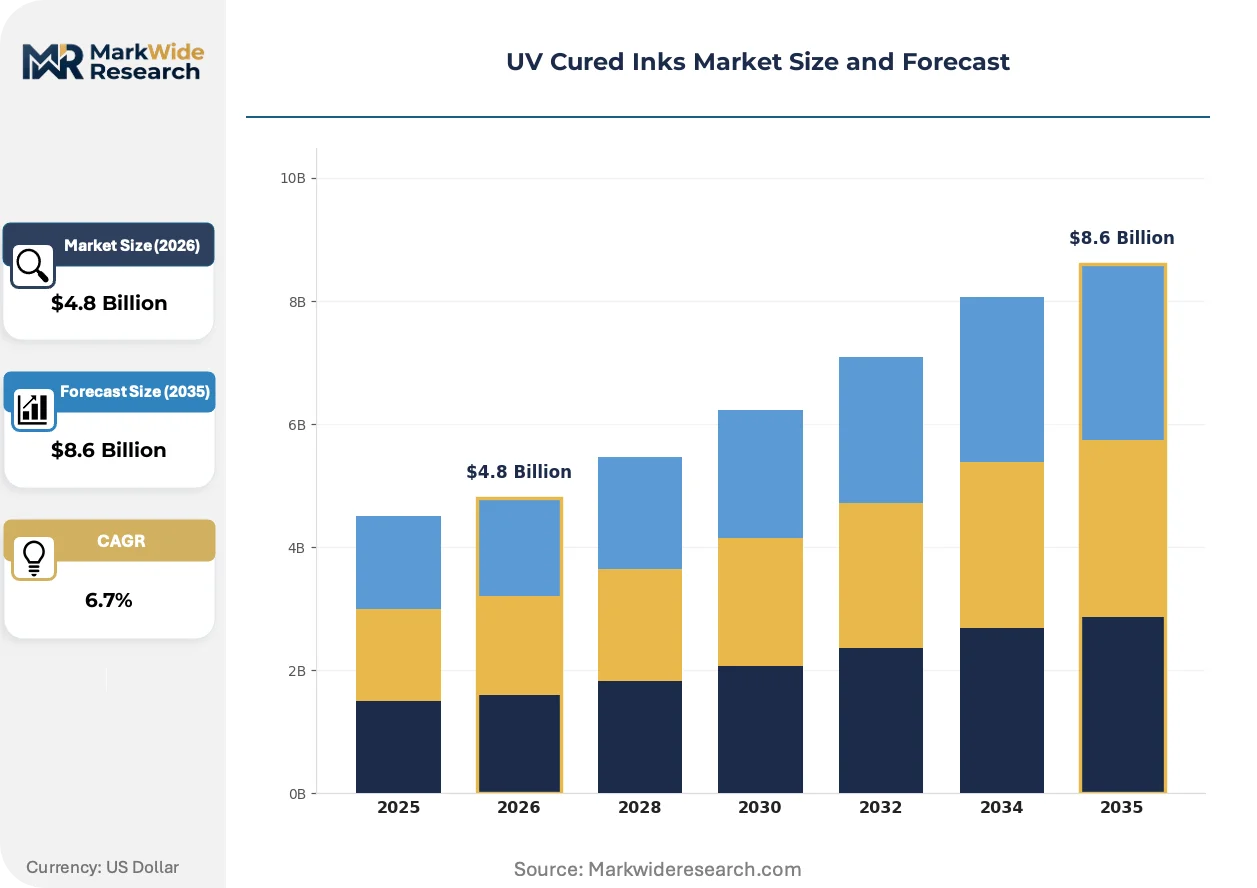
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexo Inks, Offset Inks, Digital Inks, Screen Inks Application: Packaging, Labels, Graphics, Textile End User: Printing Industry, Packaging Industry, Textile Manufacturers, Graphic Designers Technology: LED UV, Mercury Vapor, Hybrid UV, Water-Based UV |
| Companies Covered | Sun Chemical, Huber Group, artience Co. Ltd. (TOYO INK CO., LTD.), Marabu GmbH & Co. KG, SAKATA INX CORPORATION, DIC Corporation, Siegwerk Druckfarben AG & Co. KGaA, FUJIFILM Corporation, Flint Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Cured Inks Market Evolving Landscape
Formulation chemistry and curing hardware are converging to eliminate process steps that solvent systems required, compressing make-ready times and enabling mass customization workflows previously uneconomical at short run lengths.
LED UV curing systems operating at 395nm wavelength are collapsing the distinction between heat-sensitive substrate printing and high-speed production economics. Narrow-waveband output eliminates infrared bleed, allowing converters to run unsupported films and thermal papers at full press speeds without web distortion. Cosmetic and pharmaceutical label printers in Switzerland and South Korea now spec LED UV as standard for premium short-run work.
ECHA restrictions on benzophenone and ITX photoinitiators under REACH authorization are compelling systematic reformulation across European food packaging supply chains. Ink suppliers must validate replacement photoinitiators through exhaustive migration testing, extending product development cycles by twelve to eighteen months. German and Italian converters are consolidating supplier relationships to those with in-house toxicology and regulatory affairs capabilities.
Brand owners are unbundling print procurement from traditional merchant relationships, establishing direct specifications for curing technology and migration compliance that converters must meet to retain approved vendor status. This certification-driven preference shift concentrates volume with ink suppliers capable of batch-level analytical documentation. The practice is most advanced in premium chocolate and infant nutrition packaging sourced through Northern European brand headquarters.
UV Cured Inks Market Segmentation
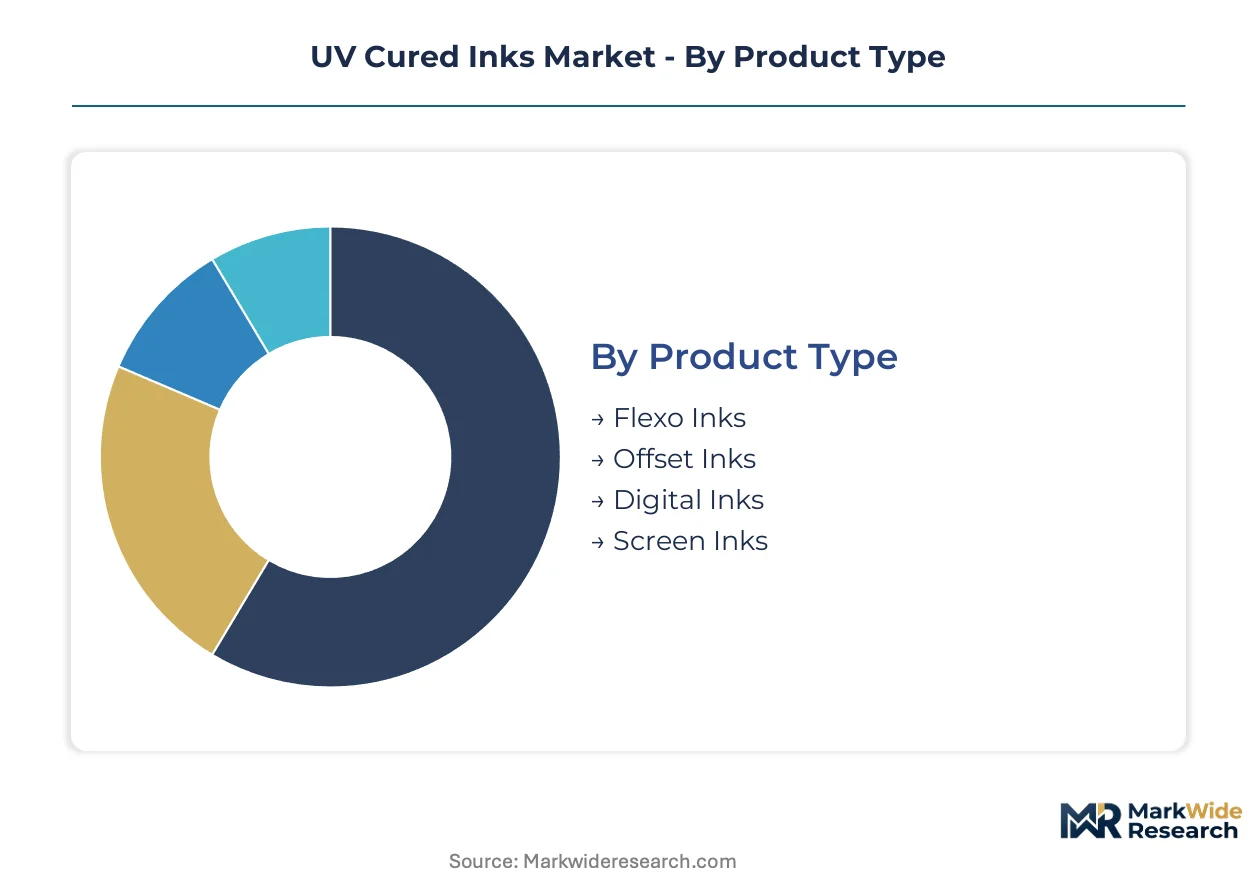
UV cured ink segments exhibit starkly different replacement cycles, with digital formulations turning over in months versus mercury vapor hardware depreciating over decades. Understanding velocity mismatches between product types and curing technologies shapes supplier portfolio priorities and R&D allocation decisions.
Product Type:
Cycle times vary dramatically across analog and digital formats, with some segments refreshing annually while others operate on fifteen-year equipment horizons.
- Digital Inks:Inkjet formulations designed for piezoelectric and thermal printheads enable variable data and short-run personalization at speeds impossible for analog systems. Demand clusters in premium cosmetic label operations across Switzerland and South Korea where brand owners mandate batch-level traceability and versioning capabilities.
- Flexo Inks:Photopolymerizable liquid coatings optimized for elastomeric printing plates deliver consistent ink transfer across corrugated and flexible film substrates. North American packaging converters around Chicago and Toronto deploy these systems for high-volume food and beverage cartonage where throughput economics dominate.
- Offset Inks:Viscous paste formulations engineered for lithographic plate compatibility serve commercial print and folding carton segments with established press infrastructure.
- Screen Inks:Thixotropic pastes formulated for mesh stencil printing address specialty industrial and point-of-purchase display applications with lower volume throughput.
Flexo inks dominate installed base across corrugated and flexible packaging. Digital inks are where expansion concentrates as on-demand workflows displace conventional make-ready economics.
Application:
Margin structures diverge sharply between regulated food contact segments and discretionary graphics work, with compliance investments creating tiered supplier participation barriers.
- Packaging:Folding carton, corrugated, and flexible film applications requiring FDA and EU Printing Ink Regulation compliance for indirect food contact. Dairy and confectionery segments in Germany and Italy generate premium pricing for validated low-migration formulations with batch-level analytical documentation.
- Labels:Pressure-sensitive and shrink-sleeve formats for beverage, pharmaceutical, and logistics tracking. Swiss pharmaceutical label printers specify LED UV curing as standard to accommodate heat-sensitive synthetic facestocks at full production speeds.
- Graphics:Wide-format display, signage, and commercial print applications with fewer regulatory constraints but intense price competition.
- Textile:Direct-to-garment and roll-to-roll fabric printing with specialized substrate adhesion and wash-fastness requirements.
Packaging commands the deepest supplier relationships through certification-driven procurement. Labels are climbing the fastest as brand owners unbundle print specifications from traditional merchant channels.
End User:
Technical service intensity varies by customer sophistication, with some segments demanding formulation co-development while others prioritize logistics reliability.
- Packaging Industry:Converters operating flexo, offset, and digital presses for brand owner supply chains. Mumbai and Ahmedabad flexible packaging clusters in India outpace local UV ink technical service capacity, creating white space for entrants with on-site formulation support.
- Printing Industry:Commercial print houses and specialty graphics operations with diverse substrate portfolios and shorter run lengths.
- Textile Manufacturers:Apparel and home furnishings producers integrating digital printing into cut-and-sew workflows.
- Graphic Designers:Creative agencies and in-house brand teams specifying print procurement parameters that cascade to converter compliance requirements.
Packaging industry relationships anchor long-term supply agreements through approved vendor programs. Printing industry demand is gaining share fastest as commercial operations retrofit for LED UV energy efficiency.
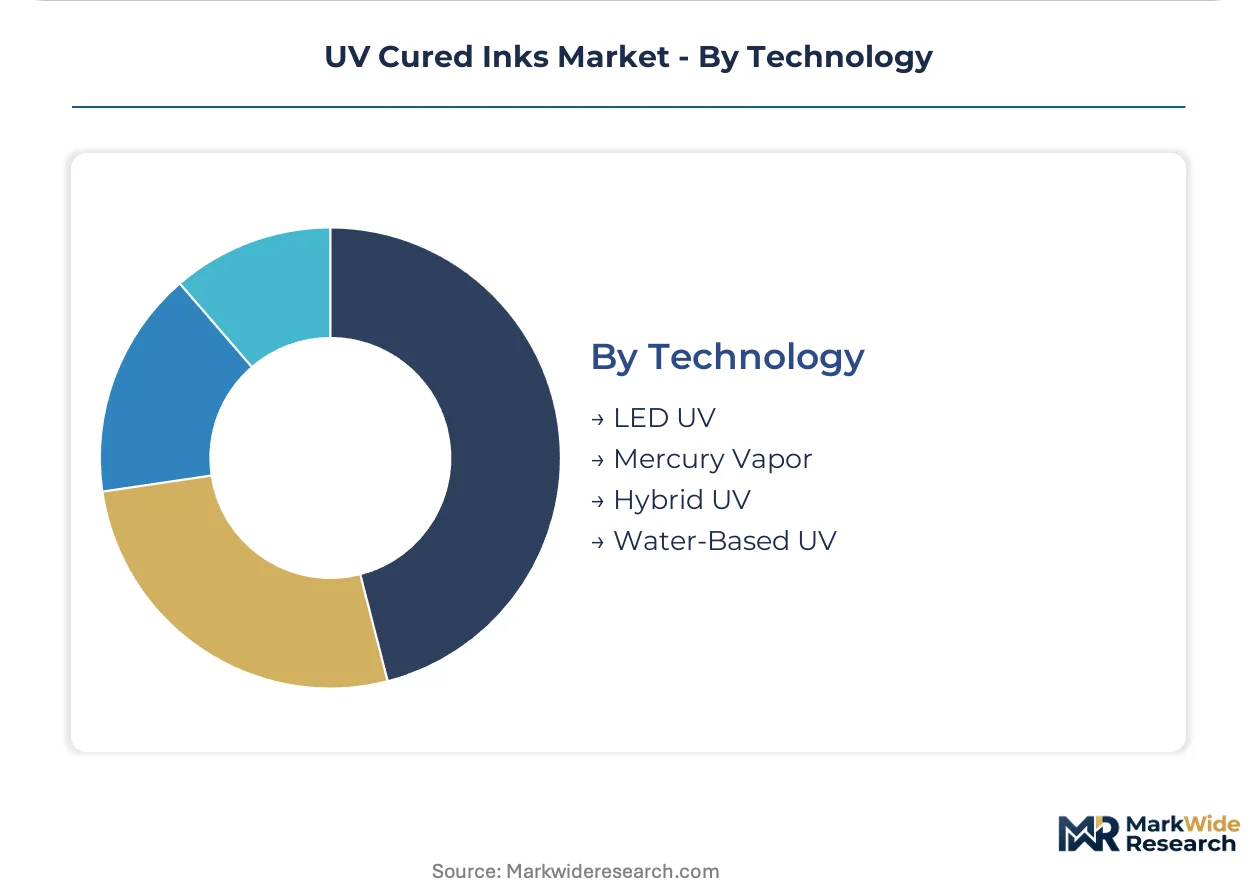
Technology:
Capital commitment horizons separate emerging narrow-waveband systems from legacy mercury infrastructure, with stranded asset risk dampening near-term upgrade willingness in some installed bases.
- LED UV:Solid-state semiconductor arrays emitting at 395nm with eliminated infrared bleed, enabling unsupported films and thermal papers at full press speeds. German and Japanese print houses reduce curing energy consumption by over sixty percent versus mercury arc, shortening capital payback periods.
- Mercury Vapor:Traditional arc lamp systems with broad spectral output and higher thermal load, now facing accelerated obsolescence before depreciation cycles complete.
- Hybrid UV:Configurations combining LED and mercury sources for transition flexibility across mixed substrate portfolios.
- Water-Based UV:Emulsion systems with reduced monomer content addressing specific food contact and odor-sensitive applications.
Mercury vapor retains substantial installed base despite regulatory pressure. LED UV is where expansion concentrates as EU Green Deal procurement mandates privilege verified low-carbon curing processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature markets prioritizing regulatory compliance and emerging economies chasing capacity scale. European converters treat UV ink procurement as a certification exercise; Asian packaging clusters optimize for throughput economics.
United States
Packaging converters around Chicago and Toronto deploy flexo systems for high-volume food cartonage. EPA VOC emission limits under the Clean Air Act accelerate solvent-to-UV retrofits across Midwestern label operations. Pharmaceutical label printers in New Jersey specify LED UV curing to meet FDA indirect food contact standards.
Germany
Print houses reduce curing energy consumption by over sixty percent versus mercury arc, shortening payback periods for capital upgrades. REACH authorization restrictions on benzophenone and ITX photoinitiators compel systematic reformulation across food packaging supply chains. Bavarian and North Rhine-Westphalian converters consolidate supplier relationships to vendors with in-house toxicology capabilities.
China
Domestic ink producers expand UV capacity to serve regional packaging clusters around Shanghai and Shenzhen. The country's national environmental regulator enforces VOC reduction mandates under dual carbon goals. Pearl River Delta flexible packaging operations outpace local technical service support, creating white space for entrants with on-site formulation expertise.
Japan
LED UV technology concentrates demand as print houses retrofit presses for energy efficiency. METI industrial efficiency standards privilege low-carbon curing processes in public procurement specifications. Cosmetic and pharmaceutical label printers in Osaka and Nagoya now specify LED UV as standard for premium short-run work.
India
Domestic flexible packaging growth around Mumbai and Ahmedabad outpaces local UV ink supply. FSSAI food contact regulations tighten compliance thresholds for dairy and confectionery packaging segments. Technical service-intensive entrants find white space in Gujarat and Maharashtra clusters where formulation support remains scarce.
UV Cured Inks Market Competitive Landscape
Capability concentration sits with specialized formulators possessing toxicology and regulatory affairs expertise; scale advantage sits with diversified chemical conglomerates commanding pigment supply chains. The market structures around three tiers: global integrated suppliers, regional specialists with food contact credentials, and domestic volume players serving price-sensitive packaging clusters. Consolidation pressures intensify as brand owners unbundle print procurement and demand batch-level analytical documentation. Dominant competitive moves include backward integration into photoinitiator supply and geographic expansion into underserved technical service markets.
Among diversified chemical groups, DIC Corporation and FUJIFILM Corporation exemplify scale-driven positions anchored in Asia-Pacific manufacturing networks. Siegwerk Druckfarben AG & Co. KGaA occupies a specialized tier focused on European label demand through low-migration formulations. Sun Chemical represents the integrated archetype leveraging captive pigment supply chains across flexo operations.
| Leading Market Players |
|---|
| Sun Chemical |
| Huber Group |
| artience Co. Ltd. (TOYO INK CO., LTD.) |
| Marabu GmbH & Co. KG |
| SAKATA INX CORPORATION |
| DIC Corporation |
| Siegwerk Druckfarben AG & Co. KGaA |
| FUJIFILM Corporation |
| Flint Group |
| Others |
Value Network & Pricing Analysis
Photoinitiator production clustering in Chinese chemical parks concentrates upstream margin capture, while downstream value pools sit with European and Japanese formulators delivering batch-level migration documentation for food contact compliance. This geographic asymmetry between raw material supply and premium formulation demand shapes pricing power distribution across the UV cured inks value chain.
Pricing Analysis
Long-term supply agreements dominate procurement relationships between multinational packaging converters and established ink suppliers, insulating premium formulations from spot market volatility. Three-tier pricing structure across certified low-migration, standard industrial, and economy commodity grades reflects compliance investment differentials. Cost compression in economy flexo segments intensifies as domestic Chinese producers expand regional capacity. Brand owners in dairy and confectionery packaging demonstrate lowest price sensitivity, prioritizing regulatory documentation over unit cost.
Supply Chain Analysis
Contract manufacturing for photoinitiator synthesis concentrates in Jiangsu and Zhejiang province chemical parks, with formulation and technical service capabilities anchored in Germany, Japan, and the United States. Specialty monomer and oligomer production draws from South Korean and Japanese petrochemical networks. Single-source vulnerability around benzophenone and ITX replacements under REACH authorization compounds reformulation risk. Distribution runs through authorized converter relationships with embedded technical service, bypassing traditional merchant channels in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists possessing combined UV polymerization expertise and food contact migration modeling capabilities remain scarce across mid-tier operations, concentrating competitive advantage with integrated suppliers investing in in-house toxicology infrastructure.
For Market Incumbents: Build regulatory affairs capabilities as a moat against emerging Asian competitors. Consolidate supplier relationships with Bavarian and North Rhine-Westphalian converters through bundled migration testing and batch certification services. Expand captive photoinitiator production to insulate margins from Chinese export license volatility. For New Entrants and Emerging Players: Technical service gaps around Mumbai and Ahmedabad flexible packaging clusters represent the most penetrable entry point for formulation-intensive entrants. Gujarat and Maharashtra converter operations outpace local UV ink support capacity. Establish on-site formulation co-development partnerships with mid-tier domestic packaging operations seeking FSSAI compliance upgrade pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European label specialists possessing low-migration formulation libraries and established brand owner certification relationships. Five-to-ten year viability hinges on successful REACH replacement photoinitiator validation timelines. Monitor ECHA authorization list updates for benzophenone and ITX restriction expansion signals indicating consolidation pressure on non-compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Captive production of specialty photoinitiators insulates Sun Chemical and DIC from Chinese export volatility. |
| Low-Migration Formulation Certification | Siegwerk's validated dairy packaging credentials unlock premium pricing from Nestlé and Danone procurement specifications. |
| LED UV Technical Service Expansion | On-site press retrofit support in India addresses white space between domestic demand and local supplier capacity. |
| Digital-Embellishment Hybrid Development | Combining inkjet variable data with UV screen effects targets premium cosmetic label workflows in Switzerland. |
| EU Green Deal Procurement Alignment | LED UV certification documentation positions suppliers for public sector print purchasing mandates in Germany. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC 10-K chemical segment disclosures, and ECHA authorization registry updates. Conversations with flexo press operators, packaging procurement managers, ink formulation chemists, and regulatory affairs specialists informed demand-side validation. Bottom-up volume modeling triangulated against top-down chemical industry association capacity estimates.
Forecast inputs include press installation databases, LED UV retrofit project pipelines, and REACH substance restriction timelines across the projection horizon. Segmentation dimensions span curing technology type, product format, application regulatory tier, and regional compliance cluster. CAGRs derived from installed base turnover analysis and technology substitution elasticity modeling, with photoinitiator supply constraints and food contact regulation evolution as scenario variables.
Practitioners should monitor ECHA candidate list expansion and Chinese dual carbon enforcement intensity for early signals of supply disruption or demand acceleration. Forecasts reflect assumptions about photoinitiator replacement validation timelines and LED UV capital payback period stability. Quarterly review of converter press retrofit announcements and brand owner procurement specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Food Marking Inks Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Low-Odor Inkjet Inks for On-Line Food Coding in Aseptic Filling Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Offset Ink Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
North America Ink Market