
 Radiation Curable Inks Market | 2026-2036
Radiation Curable Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Curable Inks Market Intelligence
Packaging printing is pivoting toward electron beam and LED-curable systems as brand owners eliminate solvent-based alternatives from food-contact workflows. Sun Chemical leverages its North American formulation network to supply low-odor UV inks for flexible packaging converters. Siegwerk Druckfarben anchors European compliance leadership through its migration-tested ink portfolios certified under EU food-contact frameworks. DIC Corporation dominates Asian supply chains for electronics-grade coatings with ultra-low extractable content.
Radiation curable inks comprise photoinitiator-loaded oligomers and monomers that polymerize instantly under UV or electron beam exposure, achieving tack-free surfaces at line speeds exceeding 300 meters per minute for web-fed printing. Ultraviolet inks sustain the largest installed base across commercial sheetfed operations, while LED-curable inks represent the fastest-growing chemistry as 395 nm diode systems displace traditional mercury arc drying on narrow-web label presses. Electron beam inks occupy premium margin pools in pharmaceutical blister packaging where zero photoinitiator content satisfies the most stringent extractable limits.
FDA food-contact notification requirements and EU Printing Ink Regulation frame product migration testing protocols that determine market access for formulated inks. REACH restrictions on specific photoinitiators and monomers are forcing reformulation cycles across European suppliers, while EPA VOC emission thresholds in the United States accelerate waterless UV adoption in offset operations. Stakeholders must monitor pending amendments to food-contact substance clearance pathways in both jurisdictions, as regulatory divergence threatens to fragment formulation standards and complicate multinational procurement strategies.
Market Dynamics
LED-curable ink chemistry is compressing mercury arc drying infrastructure across narrow-web label operations, forcing converters to reconfigure press configurations mid-contract cycle to maintain brand owner compliance mandates.
Growth Catalysts
- EU Printing Ink Regulation migration limits:Food-contact compliant UV formulations secure procurement eligibility with major European brand owners, converting solvent-based packaging lines at accelerated rates.
- Electron beam zero-photoinitiator systems:Pharmaceutical blister packaging specifications in Germany and Switzerland now mandate EB-curable inks for pediatric and immunocompromised patient applications.
- Flexible packaging web speed demands:Tack-free surfaces at 300+ meters per minute eliminate thermal drying bottlenecks, enabling just-in-time production for e-commerce fulfillment networks.
Market Restraints
- Photoinitiator supply concentration:Specialty photoinitiator manufacturing clusters in China's Jiangsu province create input vulnerability for Western formulators amid export license unpredictability.
- Mercury arc lamp disposal costs:EPA hazardous waste classifications for spent mercury vapor lamps inflate total cost of ownership for legacy UV installations in US commercial print shops.
- Acrylate monomer price volatility:Petrochemical feedstock fluctuations for hexanediol diacrylate and trimethylolpropane triacrylate compress formulation margins unpredictably.
Strategic Opportunities
- India flexible packaging conversion:FSSAI food-contact notification pathways for UV-curable inks remain underdeveloped, creating first-mover certification advantages for compliant suppliers.
- Waterless UV offset expansion:EPA VOC emission thresholds in California and Texas accelerate chemistry transitions for commercial sheetfed operations seeking grandfathered permit relief.
- 395 nm LED-diode press retrofits:Narrow-web label converters in Italy and Spain are replacing mercury arc systems mid-lease to secure energy consumption rebates under EU Green Deal industrial efficiency frameworks.
Industry Challenges
- Photoinitiator toxicology data gaps:REACH substance dossier deficiencies for novel photoinitiators stall food-contact safety assessments, freezing formulation timelines for 18-24 months.
- Press operator UV chemistry training:Converter workforces trained on solvent-based drying systems require recertification for oxygen-inhibition management and LED intensity calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Curable Inks Market |
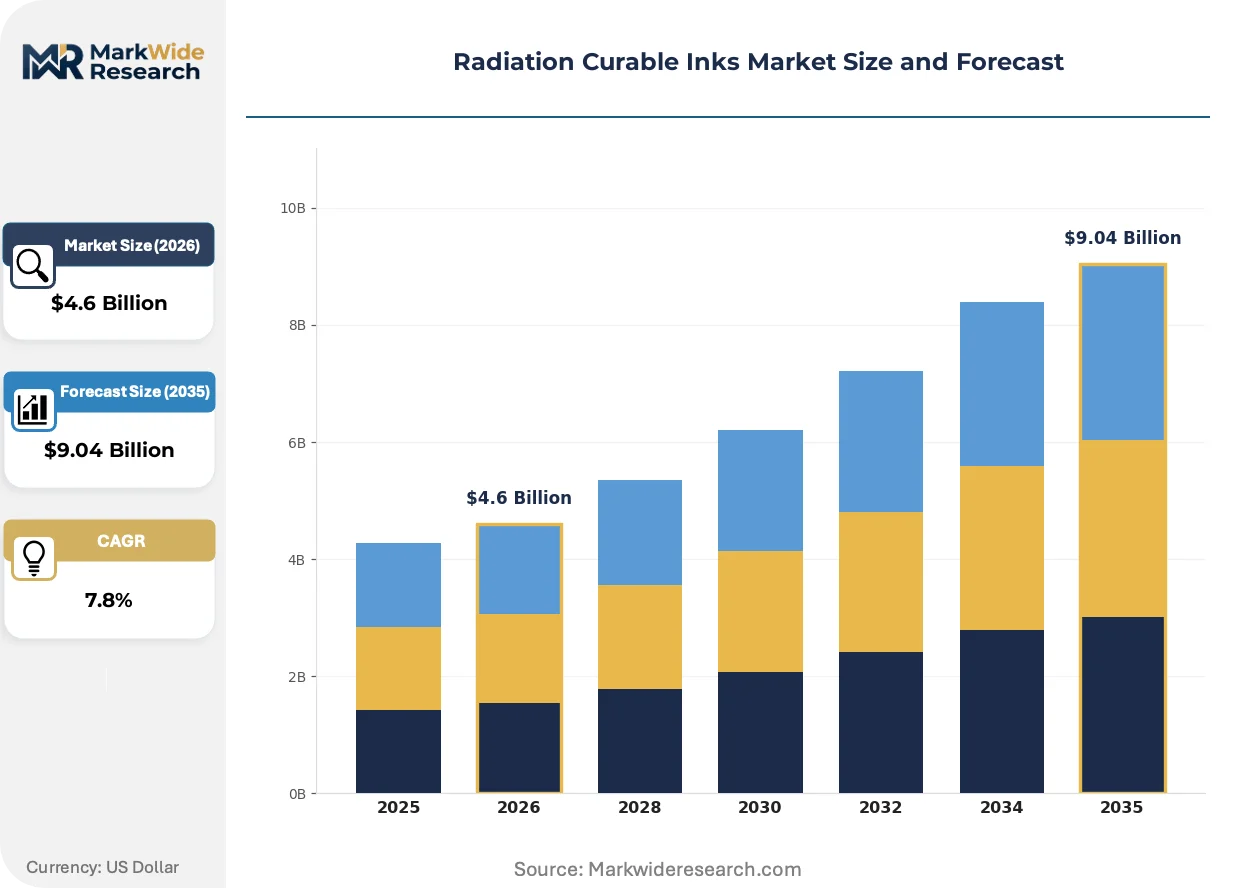
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultraviolet Inks, Electron Beam Inks, Dual-Cure Inks, LED-Curable Inks Application: Packaging Printing, Label Printing, Commercial Printing, Graphic Arts End User: Consumer Goods, Pharmaceuticals, Electronics, Automotive Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Toyo Ink SC Holdings, Siegwerk Druckfarben, Sun Chemical, HP Inc., FUJIFILM Holdings, INX International Ink Co., Flint Group, Allnex Group, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Curable Inks Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward photoinitiator-free and low-migration architectures as regulatory testing protocols tighten across multiple jurisdictions simultaneously.
LED-curable ink systems operating at 395 nm wavelength is overtaking traditional mercury arc drying on narrow-web flexo and offset label presses. Food and beverage converters in Germany and the Netherlands are specifying LED-compatible chemistries in new equipment tenders to eliminate mercury handling compliance costs. This wavelength shift is overtaking incumbent arc lamp infrastructure before standard depreciation cycles conclude, stranding capital for mid-size converters.
REACH restrictions on benzophenone and 4-methylbenzophenone photoinitiators are forcing systematic reformulation across European ink portfolios. Suppliers must generate migration testing data under EFSA protocols to retain food-contact compliance certifications, redirecting R&D resources from performance innovation toward regulatory defense. Specialty pharmaceutical and infant food packaging segments are responding by accelerating electron beam ink qualification to bypass photoinitiator risk categories entirely.
Brand owner sustainability scorecards now weight curing energy consumption and volatile organic compound elimination alongside print quality metrics. Major European retail chains are unbundling traditional ink supply contracts to require standalone carbon footprint disclosures for curing processes. This behavioral shift is most visible in French and UK grocery private label procurement, where converters must document kWh-per-thousand-impressions to maintain preferred supplier status.
Radiation Curable Inks Market Segmentation
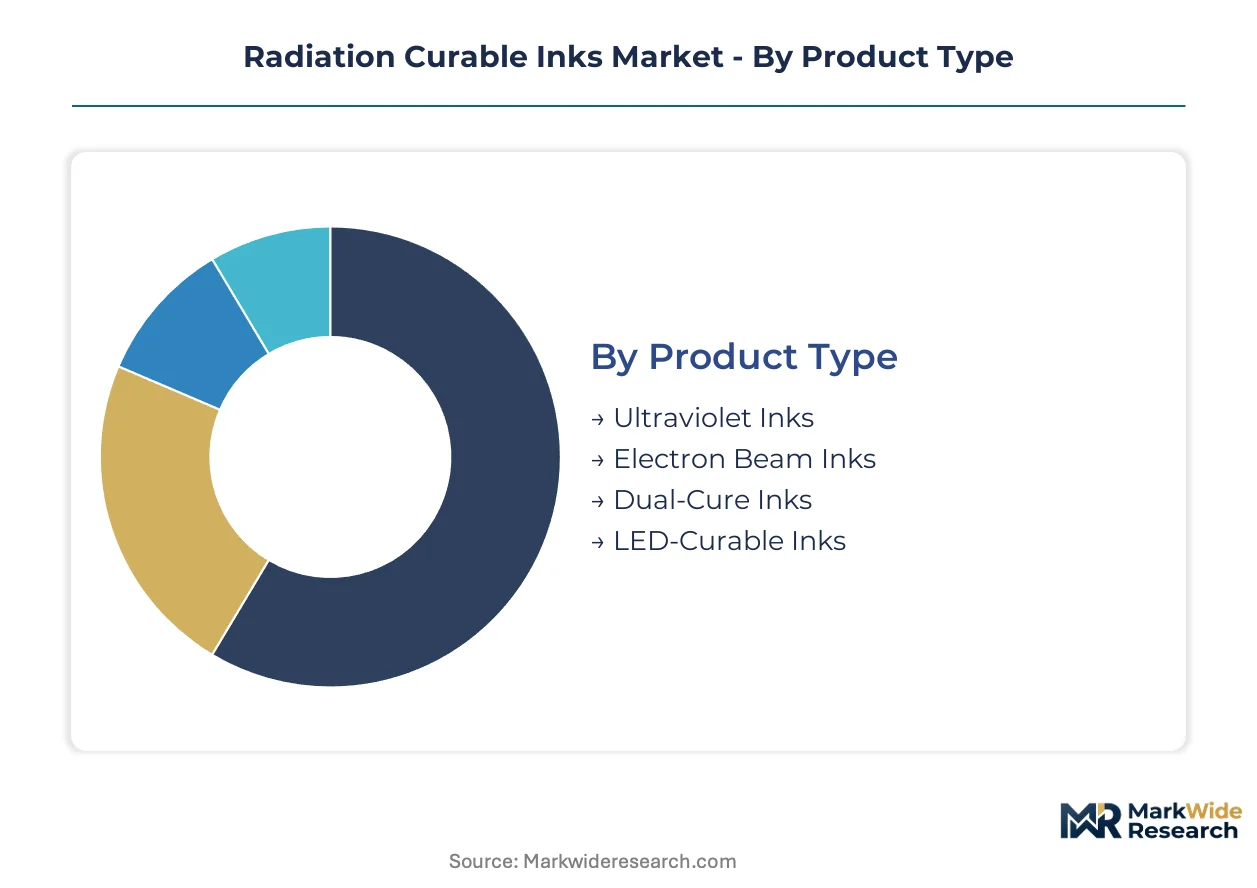
Radiation curable ink formulations vary dramatically in capital requirements, from LED retrofit compatibility to dedicated electron beam infrastructure. Procurement decisions hinge on press configuration, regulatory exposure, and end-use migration limits rather than unit cost alone.
Product Type:
Capital intensity stratifies sharply across curing technologies, with electron beam systems demanding the highest upfront investment for shielding and beam generation infrastructure.
- Ultraviolet Inks:Photoinitiator-loaded oligomer systems polymerize under mercury arc or microwave-powered UV lamps. Commercial sheetfed operations in Germany and the United States sustain the largest installed base, though mercury lamp disposal costs under EPA hazardous waste rules are compressing margins for legacy installations.
- LED-Curable Inks:Photoinitiator formulations optimized for 395 nm diode arrays eliminate mercury handling entirely. Narrow-web label converters in Italy and Spain are retrofitting presses mid-lease to secure EU Green Deal energy rebates, driving steepest expansion trajectory among all chemistry types.
- Electron Beam Inks:Zero-photoinitiator acrylic systems cure under ionizing radiation in nitrogen-inerted chambers. Pharmaceutical blister packaging specifications in Germany and Switzerland mandate EB systems for pediatric applications.
- Dual-Cure Inks:Hybrid formulations combining UV and moisture-cure mechanisms accommodate substrates with low surface energy. Automotive interior trim suppliers in the US Midwest use dual-cure for polycarbonate decorative films.
Ultraviolet inks absorb the bulk of installed capacity; LED-curable formulations are expanding most quickly.
Application:
Application segments diverge by regulatory stringency and line speed requirements, with food-contact packaging commanding the most rigorous migration testing protocols.
- Packaging Printing:Flexible web and folding carton applications demand tack-free surfaces at 300+ meters per minute for e-commerce fulfillment networks. EU Printing Ink Regulation compliance has become a procurement gate for major European brand owners.
- Label Printing:Narrow-web flexo and offset operations prioritize LED compatibility to eliminate mercury arc lamp compliance costs. French and UK grocery private label procurement now requires standalone carbon footprint disclosures for curing processes.
- Commercial Printing:Sheetfed offset operations face EPA VOC emission thresholds in California and Texas, accelerating waterless UV adoption for grandfathered permit relief.
- Graphic Arts:Point-of-purchase display and decorative laminate applications tolerate higher odor profiles than food-contact segments. UV screen printing dominates rigid substrate decoration in North American retail environments.
Packaging printing commands the largest revenue pool; label printing is climbing the fastest as brand owners unbundle ink supply contracts for sustainability scorecard compliance.
End User:
End-user concentration tracks regulatory exposure, with pharmaceutical and food-contact segments driving premium formulation development.
- Consumer Goods:Food and beverage packaging converters specify low-migration UV formulations to meet EU food-contact frameworks. REACH restrictions on benzophenone photoinitiators are forcing systematic reformulation across European supplier portfolios.
- Pharmaceuticals:Blister packaging and insert printing demand zero-extractable chemistries for immunocompromised patient safety. German regulators now mandate electron beam inks for pediatric dosage forms.
- Electronics:Printed circuit board and membrane switch applications require ultra-low ionic content to prevent conductivity failures. DIC Corporation dominates Asian supply chains for this specification tier.
- Automotive:Interior trim and instrument panel overlays prioritize scratch resistance and UV stability over migration limits. Tier-1 suppliers in Michigan and Bavaria specify dual-cure systems for polycarbonate substrates.
Consumer goods absorbs the majority of formulation volume; pharmaceuticals is gaining share fastest on zero-photoinitiator qualification requirements.
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with direct relationships dominating large converter accounts.
- Direct Sales:Formulation houses maintain technical service teams for press-side color matching and curing optimization. Major flexible packaging converters in Germany negotiate direct supply agreements for food-contact certified portfolios.
- Distributors:Regional ink distributors stock standard UV formulations for mid-size commercial print shops. Inventory concentration in China's Jiangsu province creates input vulnerability for Western formulators.
- Online Retail:E-commerce channels serve small-format digital press operators with standardized LED-curable chemistries. California-based converters purchase 395 nm compatible inks through specialized industrial supply platforms.
- Wholesale:Bulk ink brokers aggregate demand from independent label converters across fragmented European markets. Italian narrow-web specialists rely on wholesale channels for spot color matching.
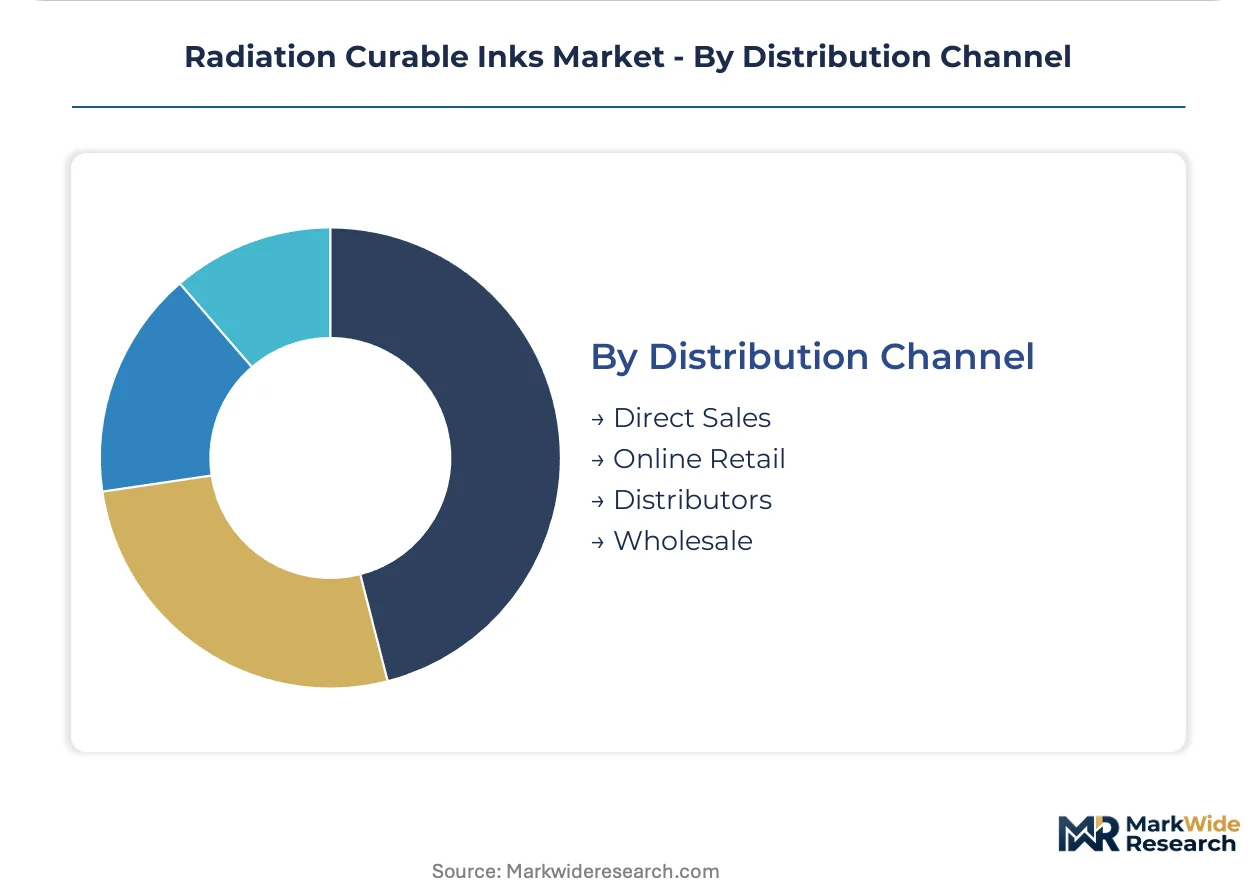
Direct sales captures the largest share of revenue; online retail is expanding most quickly among small-format digital press installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Jiangsu province concentrate photoinitiator manufacturing, creating input vulnerability for Western formulators amid export license unpredictability. Tax incentives in Gujarat's industrial corridors attract ink formulation investments targeting food-contact packaging certification.
United States
California and Texas commercial sheetfed operations drive waterless UV adoption to secure EPA VOC emission permit relief. FDA food-contact notification requirements frame migration testing protocols that determine market access for formulated inks. The Pacific Northwest hosts narrow-web label converters retrofitting presses for LED-curable chemistry compatibility.
Germany
Flexible packaging converters in Bavaria and North Rhine-Westphalia specify low-migration UV formulations to meet EU Printing Ink Regulation compliance. REACH restrictions on benzophenone photoinitiators force systematic reformulation across supplier portfolios. Frankfurt's pharmaceutical cluster mandates electron beam inks for pediatric blister packaging applications.
China
Jiangsu province's specialty chemical zones supply photoinitiators to global ink formulators, though export license unpredictability creates input vulnerability. Shanghai's flexible packaging corridor accelerates LED-curable press installations for e-commerce fulfillment networks. The national chemical regulator maintains GB standards for food-contact substance clearance that diverge from EU frameworks.
India
FSSAI food-contact notification pathways for UV-curable inks remain underdeveloped, creating first-mover certification advantages for compliant suppliers. Maharashtra's flexible packaging converters in Nashik and Pune seek low-migration formulations for export-oriented food brands. Gujarat's industrial zones attract formulation investments targeting domestic certification leadership.
Switzerland
Swissmedic pharmaceutical packaging specifications mandate zero-photoinitiator electron beam systems for immunocompromised patient safety. Basel's pharmaceutical manufacturing cluster drives premium EB ink qualification for blister and insert applications. The country's central location positions suppliers to serve German and French compliance requirements simultaneously.
Radiation Curable Inks Market Key Industry Players
Top-tier vendors anchor formulation chemistry leadership, while mid-scale specialists occupy regional certification niches. The vendor base stratifies across photoinitiator-loaded oligomer systems, LED-optimized chemistries, and zero-initiator electron beam architectures. Strategic archetypes include diversified chemical conglomerates with cross-divisional raw material access, specialized ink houses with press-side technical service capabilities, and regional formulators with localized regulatory expertise. Competitive moves concentrate on food-contact certification portfolio expansion and LED-diode press retrofit partnerships.
Among diversified chemical conglomerates, Toyo Ink SC Holdings and DIC Corporation exemplify integrated raw material-to-formulation architectures that secure input cost stability. Siegwerk Druckfarben occupies a position within the specialized European ink house tier, representing migration-tested portfolio leadership under EU food-contact frameworks. Sun Chemical anchors North American supply relationships through its formulation network serving flexible packaging converters. These three entities collectively represent the strategic spectrum from upstream chemical integration to regional compliance specialization.
| Leading Market Players |
|---|
| Toyo Ink SC Holdings |
| Siegwerk Druckfarben |
| Sun Chemical |
| HP Inc. |
| FUJIFILM Holdings |
| INX International Ink Co. |
| Flint Group |
| Allnex Group |
| DIC Corporation |
| Others |
Cost & Logistics Intelligence
LED-diode press retrofits across European narrow-web operations are simultaneously collapsing mercury arc lamp maintenance costs and concentrating procurement leverage among early-adopting converters. This wavelength migration from 395 nm systems restructures both formulation premiums and supplier tiering as brand owners rewrite ink supply contracts around energy disclosure requirements.
Pricing Analysis
Short lead-time premiums for REACH-compliant photoinitiator alternatives command substantial markups over standard acrylate formulations. Three-tier pricing structure across food-contact certified, industrial-grade, and economy spot-color portfolios reflects migration testing burden and certification investment. Pricing pressure stems from benzophenone photoinitiator phase-outs forcing emergency reformulation cycles. Mid-size commercial print shops exhibit highest price sensitivity, while pharmaceutical blister packaging converters absorb premiums for zero-photoinitiator electron beam systems.
Supply Chain Analysis
Freight cost volatility for photoinitiator shipments from China's Jiangsu province compounds input unpredictability for Western formulators. Specialty chemical manufacturing concentrates in China, Germany, and Japan, with oligomer synthesis anchored in North Rhine-Westphalia industrial corridors. Raw material dependencies include hexanediol diacrylate, trimethylolpropane triacrylate, and benzophenone derivatives. Single-source vulnerability around Jiangsu photoinitiator clusters threatens formulation continuity amid export license turbulence. Distribution runs through direct technical service relationships for large converters and regional distributors for mid-tier commercial shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED-curable chemistry is displacing mercury arc infrastructure faster than depreciation cycles allow, compressing the window for legacy asset recovery. This technology transition phase demands immediate repositioning across all stakeholder tiers.
For Market Incumbents: Anticipate accelerated brand owner unbundling of ink supply contracts by embedding carbon footprint disclosure capabilities into technical service offerings. Deepen backward integration into photoinitiator alternatives ahead of REACH substance restrictions. Prioritize certification investment for FSSAI pathways in India before first-mover windows close. For New Entrants and Emerging Players: EU Green Deal industrial efficiency frameworks in Italy and Spain open a window for 395 nm LED retrofit service bundling alongside compliant ink supply. Target underdeveloped FSSAI notification pathways in Maharashtra and Gujarat for food-contact certification leadership. Pursue wholesale channel partnerships with fragmented Italian narrow-web specialists lacking technical service depth. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized ink houses with anchored EU food-contact portfolios and press-side technical service density. Long-term viability hinges on regulatory certification moats rather than formulation performance differentiation. Watch for LED-diode press retrofit penetration rates in Iberian and Italian markets as inflection indicators for chemistry transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Alternatives | REACH benzophenone restrictions force captive supply of compliant photoinitiators for European formulations. |
| LED-Diode Press Retrofit Partnerships | EU Green Deal rebates in Italy and Spain accelerate converter equipment transitions requiring chemistry alignment. |
| FSSAI Certification Investment | India's underdeveloped food-contact notification pathways reward first-mover suppliers with procurement lock-in. |
| Electron Beam Infrastructure Expansion | Swissmedic and German pediatric packaging mandates create premium margin pools for zero-photoinitiator systems. |
| Carbon Footprint Disclosure Integration | French and UK grocery private label procurement now requires standalone kWh-per-thousand-impressions documentation. |
Research Approach
Document review covered EU Printing Ink Regulation compliance filings, REACH substance dossiers, and FSSAI notification pathways, complemented by interviews with ink formulation R&D directors, flexible packaging procurement managers, narrow-web press operators, and regulatory affairs specialists at chemical suppliers. Secondary sources included customs trade data for photoinitiator and acrylate monomer flows, SEC 10-K disclosures from diversified chemical conglomerates, and energy consumption benchmarking from EU Green Deal industrial efficiency frameworks. Bottom-up formulation volume estimates triangulated against top-down packaging converter capacity assessments.
Segmented outputs across ultraviolet, LED-curable, electron beam, and dual-cure chemistries trace value capture through packaging printing, label printing, commercial printing, and graphic arts applications. Modeled dimensions include curing technology type, end-use regulatory exposure, and geographic compliance cluster. CAGRs derive from converter equipment installation trajectories and brand owner contract unbundling velocity. Key inputs encompass mercury arc lamp disposal cost inflation under EPA hazardous waste rules and benzophenone photoinitiator phase-out timelines under REACH restrictions.
The model assumes a particular technology adoption path; alternative pathways for electron beam infrastructure in pharmaceutical packaging would alter the outlook for photoinitiator-free formulation premiums. Forecasts reflect assumptions around EU regulatory harmonization and FSSAI pathway development timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
Specialty Ink Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
United States Printing Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Functional Printing Market
Printing Inks
Brazil Commercial Printing Market
Printing Inks
Ink Resins Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Waterborne Ink Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Food Grade Inks Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Security Printing Market