
 Flexographic Printing Inks Market | 2026-2036
Flexographic Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Flexographic Printing Inks Market Analysis
European ink production is rebalancing toward water-based and UV-curable platforms as converters retrofit presses for compliance. Hubergroup Holding SE leverages its integrated resin operations to secure raw material continuity across German and Scandinavian plants. Sun Chemical Corporation anchors North American supply through captive pigment manufacturing and direct-to-converter technical service networks. Siegwerk Druckfarben AG & Co. KGaA specializes in food-contact compliant formulations, differentiating its portfolio against commodity solvent-based alternatives.
Flexographic printing inks are fluid colorant systems formulated from pigments, resins, solvents or water carriers, and additives, designed for transfer via photopolymer relief plates rotating at 300–600 meters per minute on flexible substrates. Their primary commercial purpose is high-speed, high-volume decoration of packaging materials where substrate flexibility and food-safety compliance are mandatory. Water-based inks lead volume in corrugated cardboard applications where absorbency supports rapid drying without thermal curing, while UV-curable inks command premium positioning in label and shrink-sleeve segments where instant polymerization enables finer halftone reproduction on non-porous plastic films. Solvent-based inks retain share in flexible packaging for retort pouches and lidding where adhesion to treated polyolefins remains technically superior.
EPA regulations in the United States enforce National Emission Standards for Hazardous Air Pollutants on printing operations, compelling solvent-based users toward carbon capture or reformulation. REACH and the EU Green Deal in Europe restrict Substances of Very High Concern in packaging inks, directly elevating demand for certified bio-based and water-borne alternatives. FDA food-contact notification requirements govern migration limits for inks in direct or incidental food contact, creating a technical barrier that favors suppliers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving state-level extended producer responsibility laws and substrate-specific recycling mandates that will redefine compatible ink chemistries before the decade closes.
Market Dynamics
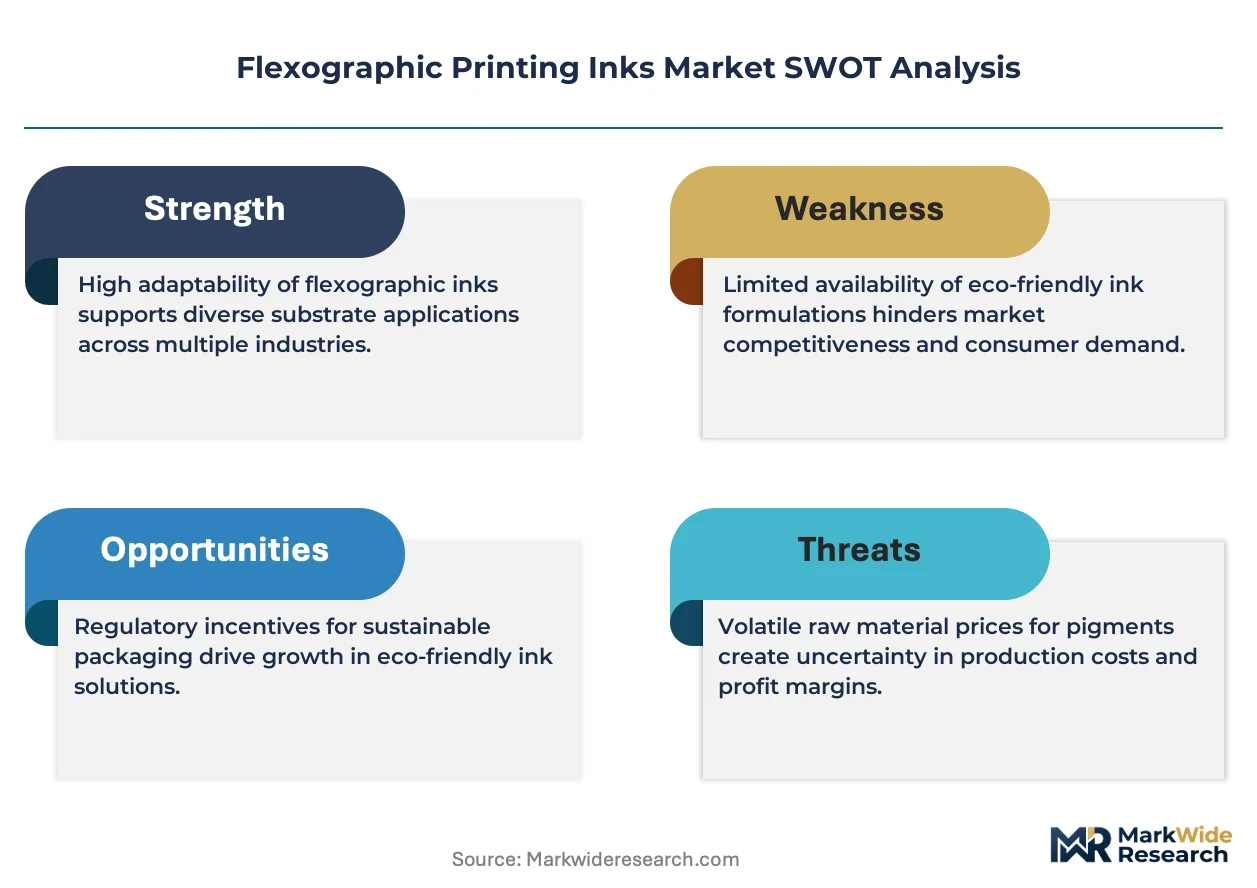
Water-based and UV-curable ink platforms are displacing solvent-based systems as European REACH compliance deadlines and FDA food-contact migration limits tighten formulation requirements across converter operations.
Growth Catalysts
- EU Green Deal packaging mandates:Substances of Very High Concern restrictions are redirecting flexible packaging converters toward certified bio-based ink alternatives.
- Corrugated cardboard absorbency:Water-based ink penetration accelerates in e-commerce shipping box applications where rapid air-drying eliminates thermal curing energy costs.
- Shrink-sleeve label demand:UV-curable systems capture premium positioning in beverage and personal care segments requiring halftone precision on non-porous plastic films.
Market Restraints
- Petrochemical resin volatility:Acrylic and polyurethane raw material costs fluctuate with crude oil indices, compressing margin stability for water-based formulation producers.
- German resin supply concentration:Hubergroup's integrated operations and Scandinavian plant network create dependency risk for converters lacking multi-source pigment security.
- Retort pouch adhesion limits:Solvent-based chemistries retain technical superiority for high-temperature sterilization applications, blocking full water-based substitution.
Strategic Opportunities
- India flexible packaging expansion:FSSAI food-contact regulations are maturing, creating first-mover advantage for compliant ink suppliers as domestic converter capacity scales.
- Digital flexo hybrid presses:Convergence of fixed imaging arrays with rotary flexo stations enables short-run customization without plate changeover downtime.
- Extended producer responsibility laws:State-level recycling mandates in California and New York are forcing substrate-ink compatibility certification, favoring suppliers with dedicated regulatory infrastructure.
Industry Challenges
- Photopolymer plate optimization:Converters lack technical personnel trained in simultaneous ink-plate-substrate matching for UV-curable systems at high line speeds.
- Carbon capture retrofit costs:EPA National Emission Standards compliance requires solvent-based operations to fund thermal oxidizer or adsorption system capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexographic Printing Inks Market |
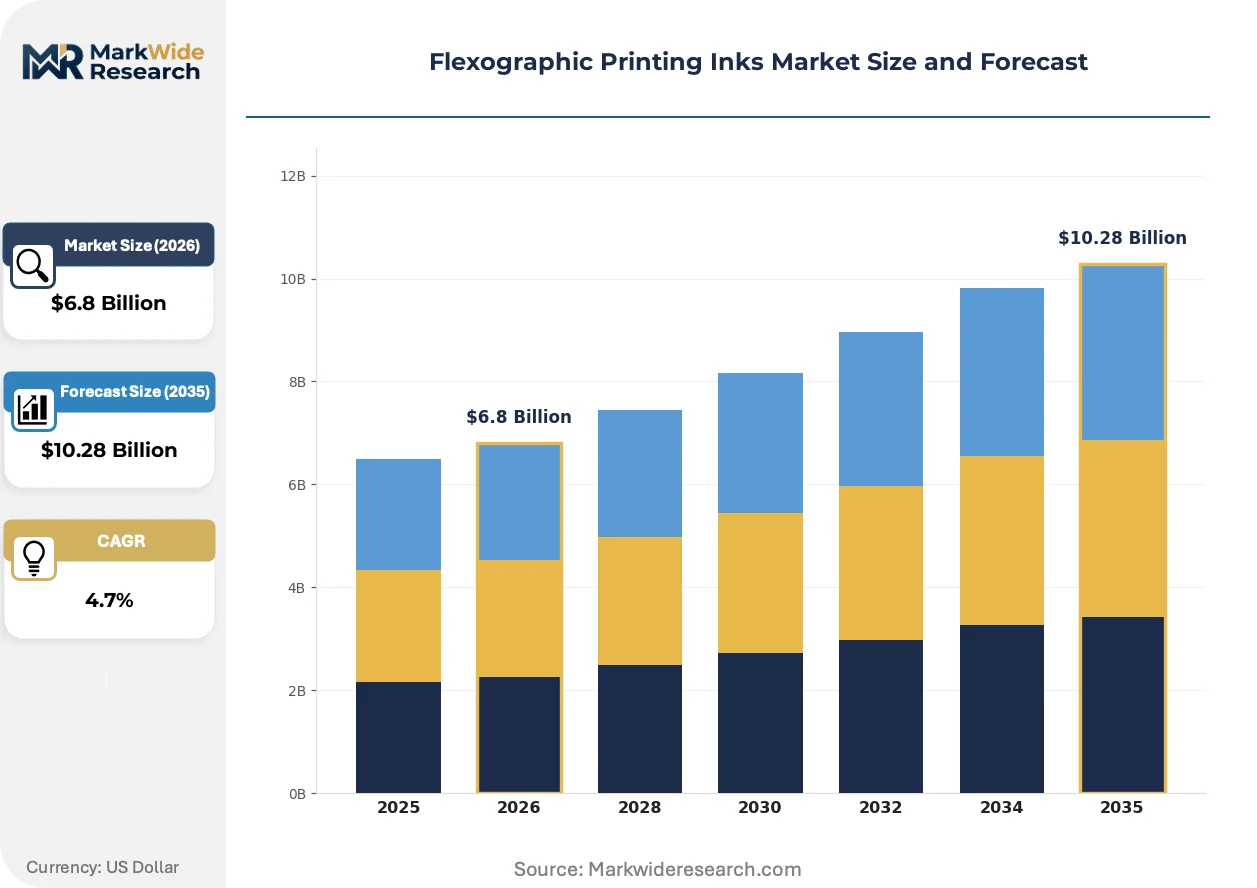
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Inks, Solvent-Based Inks, UV-Curable Inks, Oil-Based Inks Application: Flexible Packaging, Labels, Corrugated Cardboard, Newspaper End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Goods Print Substrate: Plastic Films, Paperboard, Metal Foils, Non-Woven Fabrics |
| Companies Covered | Toyo Ink, Hubergroup Holding SE, Sun Chemical Corporation, T&K Toka, INX International Ink Co., Flint Group Holdings, Sakata INX Corporation, Wikoff Color Corporation, Siegwerk Druckfarben AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexographic Printing Inks Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and converter procurement patterns are undergoing simultaneous transformation as sustainability mandates intersect with operational efficiency imperatives.
Electron beam curing technology is modularizing flexographic press configurations by eliminating photoinitiator dependencies and enabling instant polymerization at lower energy input than conventional UV systems. Narrow-web label converters in North America are retrofitting existing flexo stations with compact EB modules to serve pharmaceutical serialization requirements. The technology is modularizing equipment investment decisions, allowing phased capacity expansion without full press replacement.
REACH Annex XVII SVHC candidate list expansions are forcing systematic substance screening across ink portfolios, with ECHA notifications now covering over 230 chemicals of concern in packaging applications. German and Benelux converters are accelerating substitution timelines ahead of 2026 authorization deadlines. Food-contact compliant water-based alternatives are capturing share in lidding and pouch segments previously dominated by solvent systems.
Brand-owner sustainability scorecards are compressing supplier qualification cycles, with Unilever and Nestlé mandating cradle-to-gate carbon disclosure for all packaging ink purchases. Technical service relationships are displacing transactional procurement as converters seek formulation partnership for substrate-specific compliance documentation. This behavioral shift concentrates volume with suppliers maintaining captive analytical laboratories and regulatory affairs teams in Düsseldorf and Chicago corridors.
Flexographic Printing Inks Market Segmentation
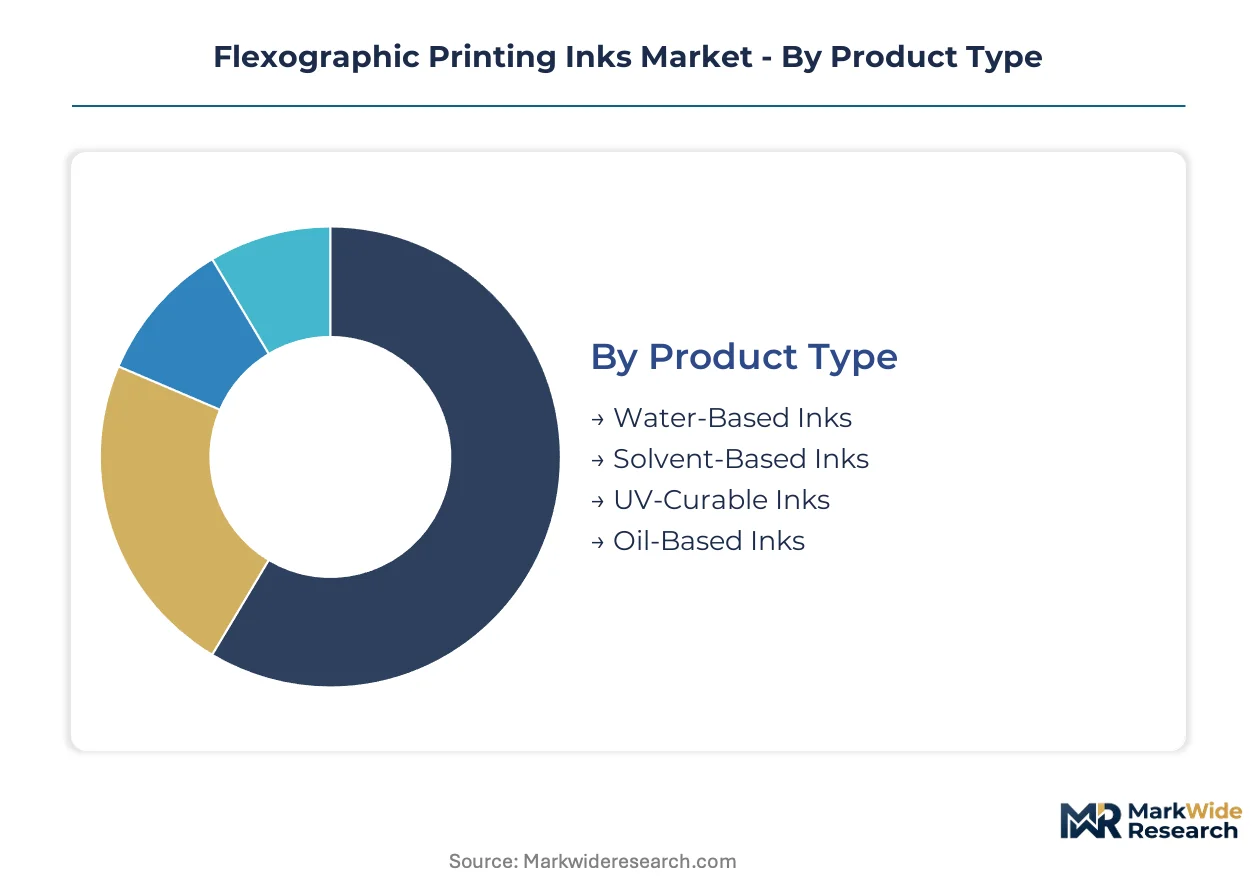
Flexographic ink purchasing decisions hinge on substrate compatibility, regulatory clearance tiers, and curing infrastructure investments. Segmentation reveals how formulation chemistry aligns with end-use compliance burdens and converter capital deployment patterns.
Product Type:
FDA food-contact notification and EU REACH SVHC restrictions impose divergent certification timelines across formulation platforms, reshaping converter procurement toward pre-certified alternatives.
- Water-Based Inks:Acrylic and polyurethane resin dispersions in water carriers achieve compliance through lower migration risk for direct food contact. Demand concentrates in corrugated cardboard applications across German and Benelux e-commerce supply chains where rapid air-drying eliminates thermal curing capital expenditure.
- UV-Curable Inks:Photoinitiator-triggered acrylic oligomer systems polymerize instantly under mercury or LED lamps, enabling halftone precision on non-porous substrates. Adoption is accelerating in shrink-sleeve label segments serving US beverage and personal care brands requiring serialization compliance.
- Solvent-Based Inks:Polyamide and nitrocellulose resin solutions in alcohol-ester blends retain technical superiority for high-temperature retort applications.
- Oil-Based Inks:Mineral oil and vegetable oil carriers serve newspaper and publication gravure-to-flexo conversions with minimal press modification.
Leading the category by volume: Water-Based Inks. Expanding most quickly: UV-Curable Inks.
Application:
End-use packaging formats dictate ink performance specifications around barrier properties, sterilization tolerance, and shelf-life extension requirements.
- Flexible Packaging:Multi-layer film structures for pouches, lidding, and wrappers demand adhesion to treated polyolefins and polyester with migration limits governed by FDA 21 CFR 175.105 and EU 10/2011. Water-based alternatives are displacing solvent systems in German converter operations ahead of REACH authorization deadlines.
- Labels:Pressure-sensitive and shrink-sleeve formats require halftone dot reproduction on non-absorbent plastic films and metallic stocks.
- Corrugated Cardboard:Absorbent kraft linerboard supports direct water-based ink application without primer or thermal curing stages.
- Newspaper:Coldset web offset conversions to flexo utilize low-viscosity oil-based formulations on uncoated newsprint.
Volume leadership sits with Flexible Packaging. Steepest expansion trajectory belongs to Labels.
End User:
Brand-owner sustainability scorecards and retailer compliance mandates create tiered procurement barriers across consumer-facing sectors.
- Food & Beverage:Migration testing, organoleptic neutrality, and cradle-to-gate carbon disclosure requirements dominate supplier qualification. Nestlé and Unilever procurement frameworks favor ink suppliers with captive analytical laboratories and documented bio-based content certification.
- Personal Care:Shampoo, cosmetics, and household product packaging emphasizes shelf appeal through metallic effects and tactile coatings.
- Pharmaceuticals:Serialization mandates and tamper-evident labeling drive narrow-web label demand with track-and-trace ink compatibility.
- Consumer Goods:Electronics and durables packaging prioritizes scuff resistance and outdoor weatherability.
Food & Beverage commands the largest share. Pharmaceuticals is climbing the fastest on regulatory serialization investment.
Print Substrate:
Surface energy, porosity, and thermal stability determine ink adhesion mechanisms and curing system selection.
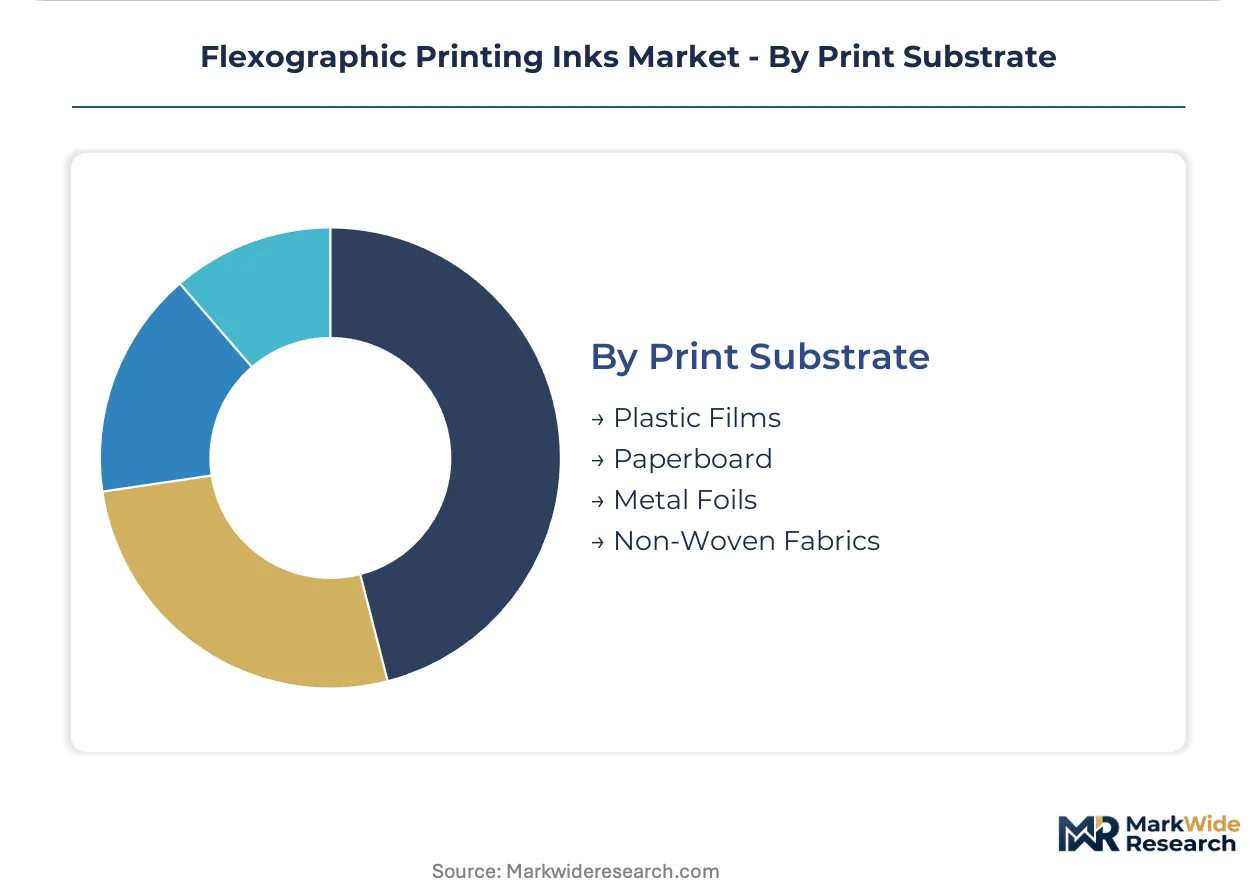
- Plastic Films:Polyethylene, polypropylene, and polyester substrates require corona or flame treatment for water-based and UV ink adhesion. Retort pouch applications in US and European markets retain solvent-based ink dominance due to sterilization temperature requirements.
- Paperboard:Coated and uncoated folding carton stocks absorb water-based inks without surface modification.
- Metal Foils:Aluminum lidding and blister packs demand heat-resistant formulations with low odor taint for pharmaceutical and dairy applications.
- Non-Woven Fabrics:Hygiene product packaging utilizes breathable film laminates with flexo-printed branding layers.
Plastic Films leads substrate consumption. Metal Foils is gaining share fastest on pharmaceutical blister pack growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German resin production anchors European flexographic ink supply chains, with acrylic and polyurethane dispersions manufactured in the Ruhr industrial corridor feeding converter operations across Central Europe. REACH authorization deadlines and EU Green Deal packaging mandates are redirecting formulation strategies toward lower-VOC alternatives in multiple jurisdictions.
Germany
Flexible packaging converters in the Düsseldorf-Cologne corridor consume water-based inks for corrugated e-commerce applications where rapid air-drying eliminates thermal curing capital expenditure. ECHA REACH Annex XVII SVHC restrictions are accelerating substitution timelines ahead of 2026 authorization deadlines. Hubergroup Holding SE operates integrated resin plants in Hamburg and Scandinavian locations, securing raw material continuity for German converter networks.
United States
Shrink-sleeve label demand from beverage and personal care brands drives UV-curable ink adoption in narrow-web converter operations. EPA National Emission Standards for Hazardous Air Pollutants compel solvent-based users toward carbon capture retrofits or reformulation investments. Sun Chemical Corporation anchors North American supply through captive pigment manufacturing and direct-to-converter technical service networks in Chicago-area corridors.
India
Domestic flexible packaging capacity expansion in Maharashtra and Gujarat is intensifying ink demand as FSSAI food-contact regulations mature. FSSAI migration testing protocols are creating first-mover advantage for compliant suppliers as converter infrastructure scales. Siegwerk Druckfarben AG & Co. KGaA positions compliant formulation portfolios to serve emerging converter clusters in Pune and Ahmedabad industrial zones.
Japan
Pharmaceutical serialization mandates and tamper-evident labeling requirements drive narrow-web label ink demand in Kanto and Kansai manufacturing belts. METI chemical substance management frameworks align with REACH-equivalent substance screening for packaging applications. Toyo Ink and T&K Toka occupy positions within domestic supply chains serving precision label segments with track-and-trace compatibility requirements.
China
Corrugated cardboard production for export packaging and domestic e-commerce channels supports water-based ink volume in the Yangtze River Delta and Pearl River Delta manufacturing clusters. MEE environmental compliance inspections and dual carbon policy targets are pressuring solvent-based formulation operations toward water-borne platform conversions. INX International Ink Co. and Sakata INX Corporation represent positions within regional supply networks adapting to tightening emission controls.
Flexographic Printing Inks Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and digital hybrid press compatibility. The vendor base stratifies across integrated resin manufacturers, pigment specialists, and formulation houses with regulatory affairs infrastructure. Three archetypes dominate: captive raw material producers securing supply continuity, food-contact compliance specialists differentiating against commodity alternatives, and technical service-oriented suppliers embedding with converter operations. Competitive moves concentrate on backward integration into resin production and geographic expansion into underpenetrated compliance-maturing jurisdictions.
Within the integrated manufacturing tier, Hubergroup Holding SE exemplifies upstream control through captive resin operations spanning German and Scandinavian production locations. Sun Chemical Corporation represents the technical service archetype with direct-to-converter analytical support networks. Siegwerk Druckfarben AG & Co. KGaA occupies a position within food-contact specialization, differentiating formulation portfolios against solvent-based commodity alternatives in European and emerging Asian markets.
| Leading Market Players |
|---|
| Toyo Ink |
| Hubergroup Holding SE |
| Sun Chemical Corporation |
| T&K Toka |
| INX International Ink Co. |
| Flint Group Holdings |
| Sakata INX Corporation |
| Wikoff Color Corporation |
| Siegwerk Druckfarben AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
UV-curable ink platform adoption simultaneously compresses unit economics and concentrates supply power among photoinitiator and oligomer specialists. REACH authorization timelines and FDA food-contact migration testing are forcing converters toward pre-certified formulations, reshaping procurement premiums across German and North American supply chains.
Pricing Analysis
Technical service bundling separates premium suppliers from commodity competitors, with regulatory documentation and substrate-specific formulation support included in long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with food-contact compliant water-based alternatives commanding premiums over solvent-based equivalents. Price erosion runs through economy-tier solvent-based formulations as EPA emission compliance costs accumulate. Small and mid-sized converters lacking in-house regulatory affairs show highest price sensitivity, while multinational food brands prioritize compliance assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German resin production, where Hubergroup's integrated Hamburg and Scandinavian plants supply acrylic and polyurethane dispersions to Central European converter networks. Raw material flows draw from petrochemical feedstocks in Germany, China, and the United States, with pigment concentrates hinging on captive manufacturing at Sun Chemical's Chicago-area facilities. Tariff exposure on photoinitiator imports from China creates formulation cost volatility for UV-curable producers. Distribution runs through direct-to-converter technical service relationships, displacing traditional distributor intermediaries in compliance-intensive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance infrastructure as REACH deadlines and FDA migration limits force smaller formulation houses toward acquisition or exit. Capital deployment favors suppliers with captive analytical laboratories and documented bio-based certification pathways.
For Market Incumbents: To counter emerging bio-based specialists, Sun Chemical and Hubergroup should deepen backward integration into resin production and expand regulatory affairs teams in Düsseldorf and Chicago corridors. Capacity additions in India and Southeast Asia capture converter scaling ahead of FSSAI compliance maturation. For New Entrants and Emerging Players: Mid-tier Indian flexible packaging converters seeking FSSAI-compliant alternatives represent the most penetrable buyer archetype, with Pune and Ahmedabad industrial clusters offering first-mover positioning. Bio-based certification and digital flexo hybrid press compatibility provide differentiated entry angles against established solvent-based portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated chemical majors seeking food-contact compliance capabilities and regional converter relationships. Five-to-ten year viability hinges on regulatory affairs infrastructure depth and captive resin supply security. The signal to watch is EU Green Deal packaging mandate acceleration and state-level extended producer responsibility law adoption in California and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Hubergroup's captive Hamburg and Scandinavian plants secure supply continuity against petrochemical volatility. |
| Regulatory Affairs Infrastructure Expansion | Sun Chemical's Chicago and Düsseldorf laboratories embed technical service relationships with multinational food brands. |
| Bio-Based Certification Investment | EU Green Deal SVHC restrictions elevate demand for certified alternatives ahead of authorization deadlines. |
| Geographic Expansion into India | FSSAI migration testing maturation creates first-mover advantage for compliant suppliers in Pune and Ahmedabad clusters. |
| Digital Flexo Hybrid Press Compatibility | Convergence of fixed imaging with rotary flexo stations enables short-run customization without plate changeover downtime. |
Methodological Framework
Trade publications, chemical industry association reports, and regulatory filing databases formed the secondary backbone, cross-referenced with primary interviews involving ink formulation chemists, flexible packaging procurement managers, and press equipment engineers. Bottom-up and top-down triangulation validated volume estimates across water-based, UV-curable, and solvent-based platform segments.
Historical trendline analysis of formulation chemistry shifts and converter capital expenditure patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, application format, end-use sector, print substrate, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through and FDA food-contact notification timelines.
Revisions become necessary when EU authorization deadlines accelerate, EPA emission standards tighten, or photoinitiator supply disruptions materialize. Forecasts reflect assumptions about converter retrofit rates and brand-owner sustainability scorecard enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Printing Toners Market
Printing Inks
Functional Printing Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Offset Ink Market
Printing Inks
Ink Additives Market