
 Ink Resins Market | 2026-2036
Ink Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Ink Resins Market Analysis
Software-defined color management and predictive maintenance subscriptions is decoupling hardware sales from recurring revenue in ink formulation systems. BASF SE leverages its Ludwigshafen resin complex to sustain captive supply of acrylic and polyurethane intermediates for European flexographic customers. Evonik Industries AG anchors its position through high-purity specialty acrylates serving UV-curable inkjet segments. Arakawa Chemical Industries dominates rosin ester derivatives for Asian gravure and offset applications.
Ink resins comprise polymeric binders—acrylics, polyamides, polyurethanes, and modified rosins—typically formulated at 30–50% solids content to confer adhesion, gloss, and drying speed to printing inks. These resins function as the film-forming backbone that locks pigment to substrate across packaging, publishing, and decorative surfaces. Acrylic resins lead formulation value in waterborne flexographic and digital printing systems where clarity and fastness requirements have tightened. Polyurethane resins represent the fastest-growing chemistry as brand owners specify higher mechanical resistance for retort pouches and industrial labels. Rosin resins occupy a mature, cost-sensitive niche in newspaper and book offset inks where raw material volatility compresses margin pools.
The EPA regulates volatile organic compound emissions from solventborne ink operations under the National Emission Standards for Hazardous Air Pollutants, pushing converters toward waterborne and UV-curable alternatives. REACH registration requirements in Europe restrict certain phthalate plasticizers and aromatic solvents common in legacy gravure formulations, reshaping resin specification sheets. China's MEE enforces increasingly stringent VOC discharge limits for packaging printers in the Yangtze and Pearl River Delta clusters. Stakeholders must monitor regulatory divergence across these jurisdictions when situating resin production and qualifying formulations for cross-border supply.
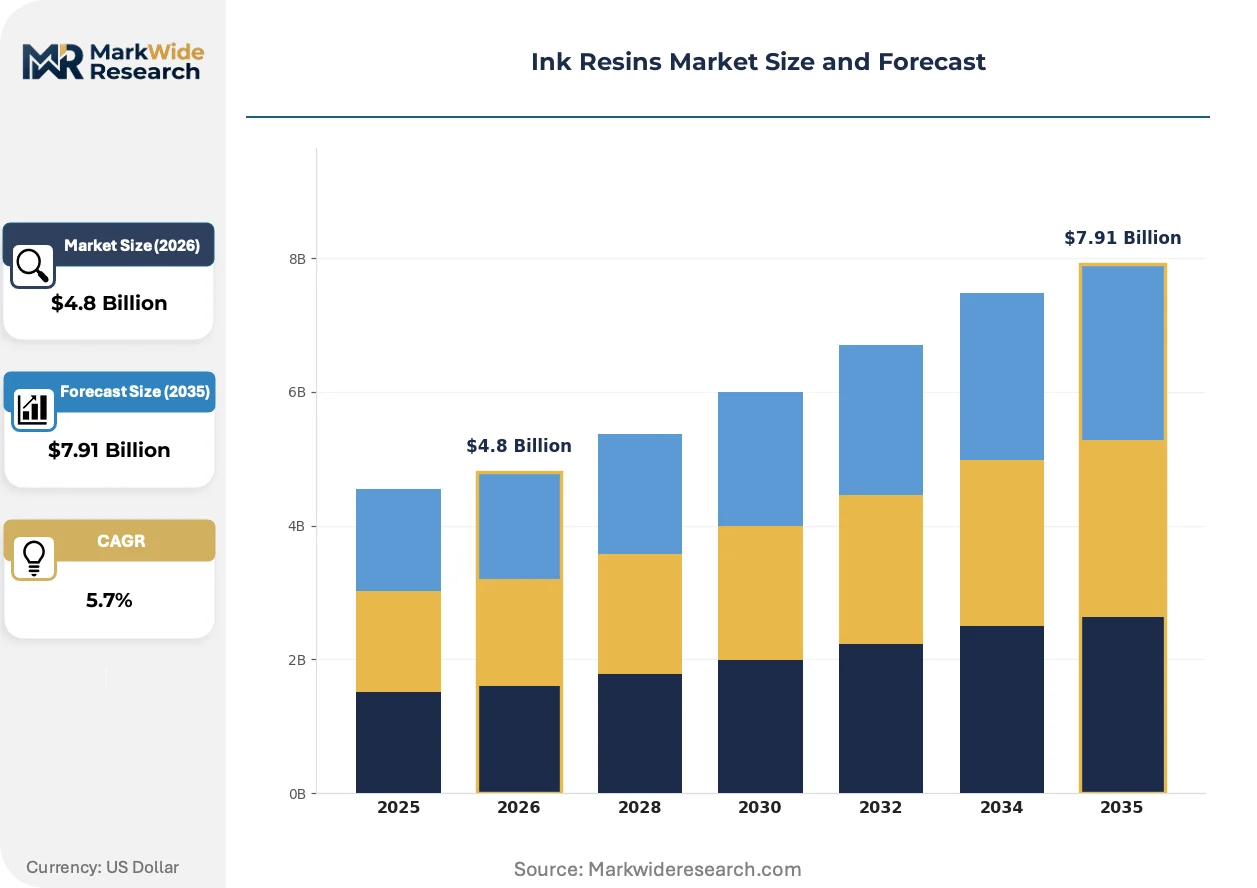
Market Dynamics
Waterborne formulation conversion is compressing solventborne resin capacity while EU REACH and China's MEE regulations accelerate chemistry substitution timelines across packaging converters.
Growth Catalysts
- REACH chemical restrictions:European converters face mandatory phase-outs of aromatic solvents and phthalate plasticizers, forcing resin specification upgrades toward compliant acrylic and polyurethane systems.
- Flexible packaging expansion:Food and beverage brand owners specify waterborne flexographic inks for sustainability credentials, pulling demand for compatible resin binders.
- Yangtze River Delta cluster:China's domestic label and carton output scales concentrate ink resin procurement in Shanghai, Jiangsu, and Zhejiang provinces.
Market Restraints
- Crude gum rosin volatility:Harvest fluctuations in China and Indonesia create input cost instability for modified rosin ester producers serving newspaper and book offset segments.
- Acrylic acid supply concentration:Captive production at Ludwigshafen and select Asian complexes limits merchant availability for independent European formulators.
- UV-curable inkjet curing depth:Oxygen inhibition constraints restrict thick-film applications in industrial decorative coatings despite faster drying speeds.
Strategic Opportunities
- Retort pouch specifications:Brand owners demand higher mechanical resistance for sterilizable flexible packaging, opening polyurethane resin penetration in lamination adhesives.
- Software-defined color management:Predictive maintenance subscriptions decouple hardware from recurring revenue, enabling resin suppliers to embed formulation intelligence in service contracts.
- India BIS standards alignment:Packaging printers preparing for mandatory quality certifications create qualified supplier windows for waterborne acrylic resin imports.
Industry Challenges
- Formulation chemist scarcity:Expertise in waterborne polyurethane dispersion stability and UV oligomer selection concentrates at major resin houses, constraining independent converter R&D.
- Cross-border qualification timelines:Divergent VOC testing protocols between EPA NESHAP, REACH registration dossiers, and China's GB standards extend product approval cycles for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ink Resins Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Resins, Polyamide Resins, Polyurethane Resins, Rosin Resins Application: Flexographic Printing, Gravure Printing, Offset Printing, Digital Printing Formulation Type: Waterborne, Solventborne, UV-Curable, Electron Beam End User: Commercial Printing, Packaging Industry, Publishing, Labels |
| Companies Covered | BASF SE, The Dow Chemical Company, Evonik Industries AG, Covestro AG, Lawter, IGM Resins, Arakawa Chemical Industries, Kraton Corporation, Indulor Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ink Resins Market Emerging Trajectories
Digital printing integration and regulatory chemistry bans are fragmenting legacy resin portfolios while creating premium niches for specialty acrylates and polyurethane dispersions.
Waterborne polyurethane dispersions are absorbing share in flexible packaging laminations where retort resistance and heat-seal strength requirements exceed acrylic capabilities. Converters in Germany and Italy adopt these systems for premium snack and pet food pouches. The technology is absorbing margin pools previously captured by solventborne polyamides as brand sustainability mandates harden.
REACH registration requirements for polymer intermediates are compressing the qualified supplier base for European gravure and offset formulators. ECHA dossier costs and substance evaluation timelines favor integrated resin manufacturers with dedicated regulatory affairs capacity. Small and mid-sized Asian exporters face exclusion from EU supply chains without representative-only registration structures.
Brand owners now unbundle ink formulation specification from press hardware procurement, issuing resin-qualified supplier lists independent of OEM service contracts. This disintermediation pressures captive resin distribution tied to German and Japanese press manufacturers. The practice is most visible in North American corrugated packaging where converter consolidation has concentrated purchasing leverage.
Ink Resins Market Segmentation
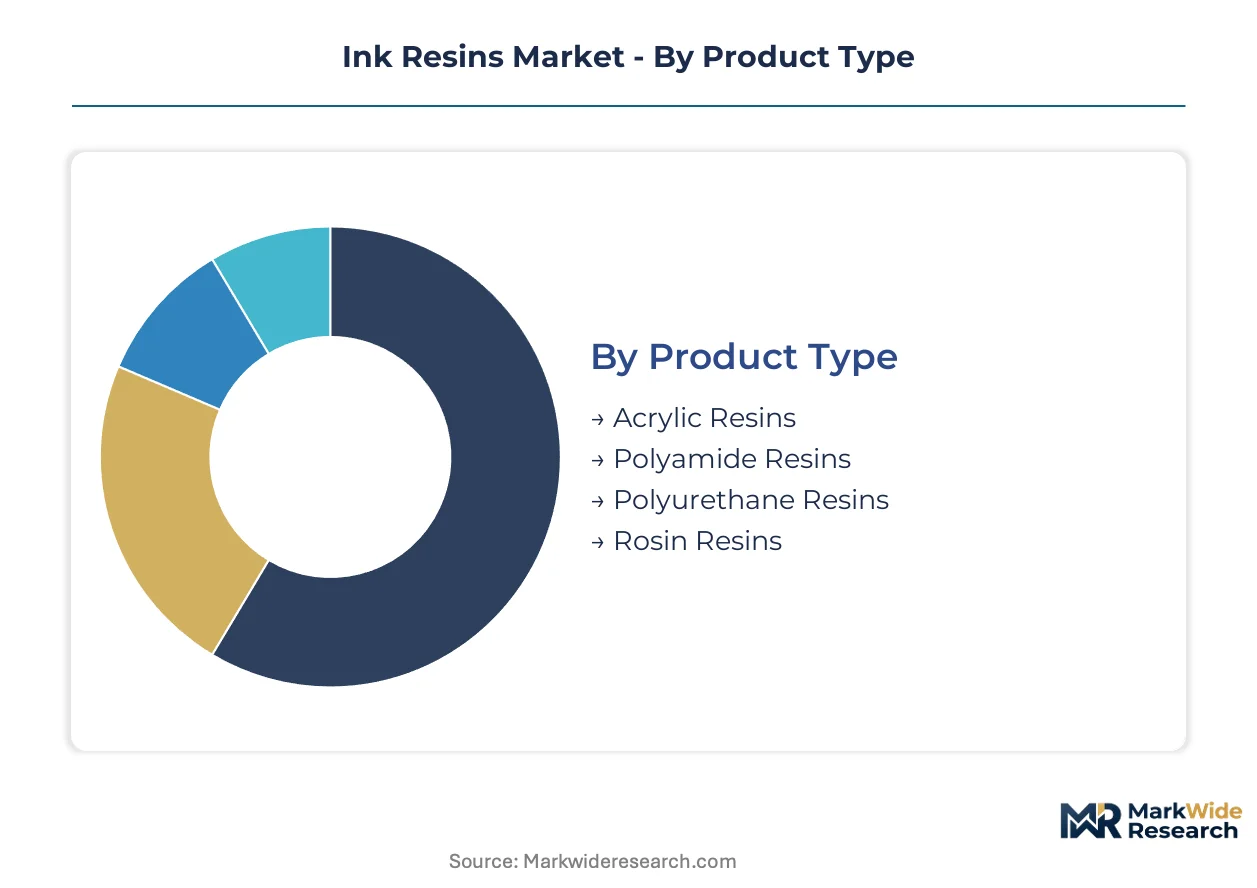
Ink resin specifications cascade through multiple selection criteria—chemistry type determines adhesion mechanics, printing process dictates viscosity windows, and end-use durability requirements filter qualified suppliers. Segmentation discipline separates commodity volume plays from specialty margin capture.
Product Type:
Supply concentration for acrylic and polyurethane intermediates favors integrated resin houses with captive feedstock positions.
- Acrylic Resins:Thermoplastic copolymers of methyl methacrylate and butyl acrylate deliver clarity and UV stability for waterborne flexographic systems. Demand clusters in Germany and Italy where premium snack packaging converters specify fast-drying, low-odor formulations for brand-owner sustainability mandates.
- Polyurethane Resins:Aliphatic and aromatic polyether-urethane dispersions provide exceptional mechanical resistance for retort pouches and industrial labels. Procurement from Shanghai and Jiangsu provinces is accelerating as Chinese domestic label output scales and converters upgrade from acrylic-only specifications.
- Polyamide Resins:Solventborne polyamides retain share in high-speed gravure publication printing where alcohol solubility and gloss retention matter.
- Rosin Resins:Modified ester derivatives of gum rosin serve cost-sensitive newspaper and book offset segments in Indonesia and Brazil.
Today's leader: Acrylic Resins. Tomorrow's challenger: Polyurethane Resins.
Application:
Cost tier separation runs deepest in digital versus conventional printing, with inkjet commanding formulation premiums per liter.
- Flexographic Printing:Anilox roll metering of waterborne and UV-curable inks dominates corrugated packaging and flexible film applications. The Yangtze River Delta cluster concentrates converter investment, with Zhejiang province alone accounting for substantial procurement volume of compatible acrylic and polyurethane binders.
- Digital Printing:Piezoelectric inkjet and electrophotographic systems require ultra-low viscosity oligomers and precisely controlled molecular weight distributions. UV-curable inkjet in industrial decorative coatings is expanding most quickly despite oxygen inhibition constraints on thick-film builds.
- Gravure Printing:Cylinder-engraved solventborne systems persist in high-volume publication and decorative laminate production.
- Offset Printing:Lithographic sheetfed and heatset web applications favor rosin-modified phenolic resins for cost-efficient newspaper and magazine output.
Volume concentrates in flexographic systems. Value migrates toward digital specification.
Formulation Type:
Customer type bifurcation separates sustainability-mandated brand owners from cost-optimized publication printers.
- Waterborne:Acrylic and polyurethane dispersions at 30-50% solids content serve EPA NESHAP-compliant flexographic packaging across the United States and REACH-aligned European converters. The EU ECHA restrictions on aromatic solvents are forcing accelerated specification upgrades in Germany, Italy, and France.
- UV-Curable:Acrylate-functional oligomers and monomers enable instant polymerization for inkjet and narrow-web label presses. China's MEE VOC discharge limits in the Pearl River Delta are pulling adoption ahead of regulatory deadlines.
- Solventborne:Polyamide and nitrocellulose-compatible resins retain niche positions where drying speed and substrate adhesion override environmental compliance costs.
- Electron Beam:Cationic and free-radical curing systems without photoinitiator requirements serve food-contact sensitive flexible packaging in premium North American applications.
Compliance pressure elevates waterborne and UV-curable formulations. Solventborne capacity faces structural compression.
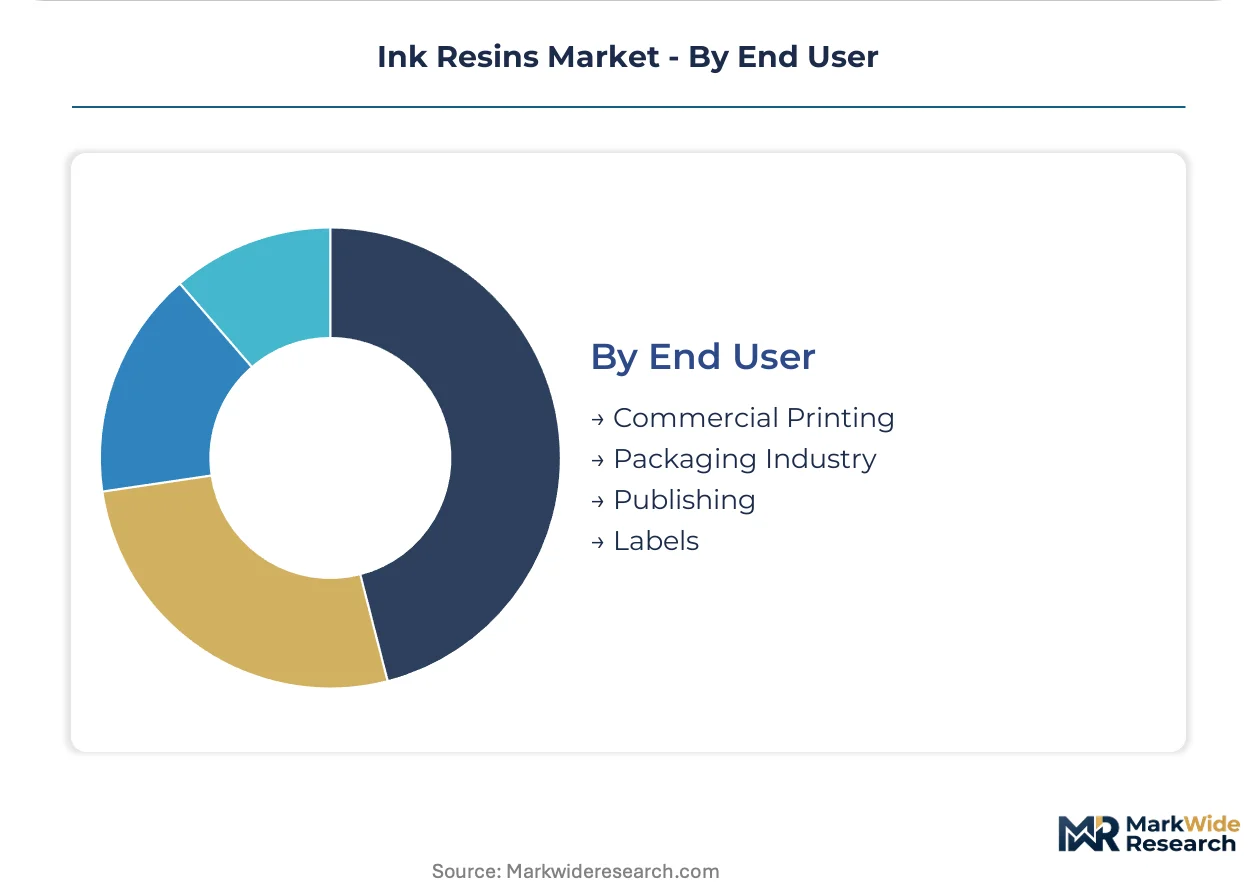
End User:
Maturity gradients separate established publishing demand from packaging growth vectors.
- Packaging Industry:Flexible food and beverage pouches, corrugated shipping containers, and folding cartons specify resins for heat-seal strength, retort resistance, and print durability. India's BIS standards alignment for packaging quality certifications is creating qualified supplier windows for waterborne acrylic imports.
- Labels:Pressure-sensitive adhesive face stocks and in-mold decoration require low-migration polyurethane dispersions and UV-curable overprint varnishes. Demand concentrates in pharmaceutical and logistics applications with serialization requirements.
- Commercial Printing:Marketing collateral, direct mail, and point-of-purchase displays utilize conventional offset and digital toner systems with standard acrylic binders.
- Publishing:Newspaper, book, and periodical production relies on mature rosin-based formulations with thin margin pools and raw material volatility exposure.
Packaging commands formulation innovation investment. Publishing resists price recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's flexographic packaging sector commands premium resin specifications, while China's domestic label output scales faster across broader volume tiers.
United States
EPA NESHAP compliance deadlines accelerate waterborne acrylic adoption across corrugated packaging converters in Wisconsin and Pennsylvania. The agency's volatile organic compound emission limits for flexographic operations force specification upgrades away from solventborne polyamides. Procurement concentrates in the Great Lakes manufacturing belt where food and beverage brand owners mandate sustainability credentials.
Germany
Premium snack packaging converters in Bavaria and Baden-Württemberg specify fast-drying, low-odor polyurethane dispersions for retort pouch applications. REACH registration dossiers for polymer intermediates compress the qualified supplier base for gravure formulators. The Ludwigshafen chemical complex anchors captive acrylic acid supply for integrated resin manufacturers serving European flexographic customers.
China
Domestic label and carton output scales concentrate resin procurement in Shanghai, Jiangsu, and Zhejiang provinces. MEE enforcement of VOC discharge limits in the Yangtze River Delta pulls adoption of waterborne and UV-curable formulations ahead of regulatory deadlines. Zhejiang province alone accounts for substantial procurement volume of compatible acrylic and polyurethane binders.
India
Packaging printers preparing for mandatory BIS quality certifications create qualified supplier windows for waterborne acrylic resin imports. Maharashtra and Gujarat-based converters upgrade from solventborne systems as brand sustainability mandates penetrate domestic supply chains. The Delhi-NCR corridor concentrates commercial printing demand for standard acrylic binders in marketing collateral applications.
Japan
High-purity specialty acrylate demand for UV-curable inkjet segments anchors resin specification in Kanto and Kansai industrial zones. METI guidelines on chemical substance management align converter procurement with international sustainability frameworks. Osaka-based formulators concentrate expertise in low-migration polyurethane dispersions for pharmaceutical label applications.
Ink Resins Market Vendor Landscape
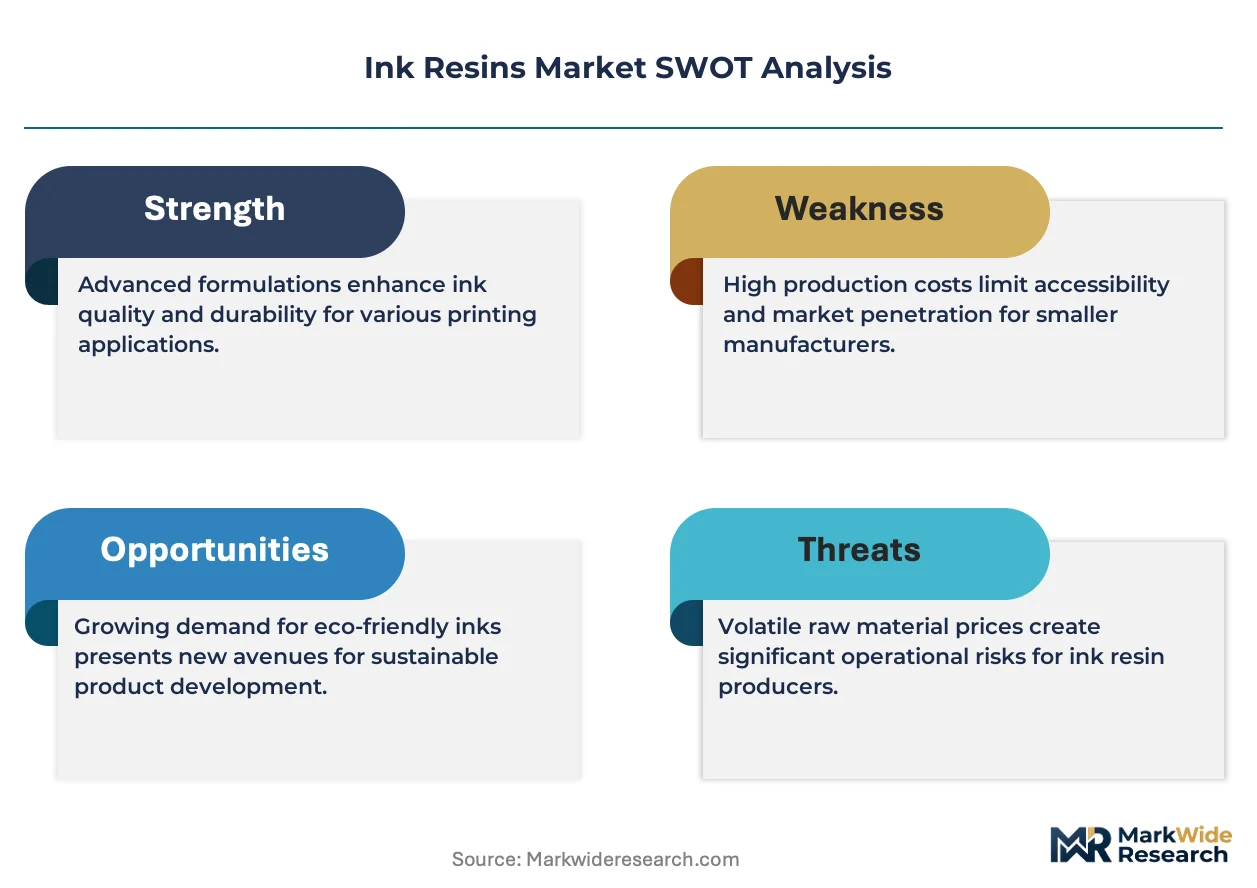
Top-tier vendors anchor integrated chemical complexes with captive feedstock positions, while specialized resin houses occupy formulation-specific niches. The market structure favors backward integration into acrylic acid and polyurethane intermediates over merchant supply reliance. Three archetypes dominate: diversified chemical conglomerates with resin divisions, pure-play specialty resin manufacturers, and regional rosin derivative processors. Competitive moves concentrate on regulatory registration capacity expansion and waterborne formulation technology licensing.
Within the diversified chemical tier, BASF SE and Evonik Industries AG exemplify integrated positioning through Ludwigshafen-based captive supply and high-purity acrylate specialization respectively. Arakawa Chemical Industries occupies a distinct archetype as a rosin ester specialist serving Asian gravure applications. These three entities represent the span from petrochemical-integrated resin manufacturing to natural feedstock-dependent derivative processing.
| Leading Market Players |
|---|
| BASF SE |
| The Dow Chemical Company |
| Evonik Industries AG |
| Covestro AG |
| Lawter |
| IGM Resins |
| Arakawa Chemical Industries |
| Kraton Corporation |
| Indulor Chemie GmbH |
| Others |
Supply Flow & Price Mechanics
Flexible packaging converters in the Yangtze River Delta cluster negotiate resin supply through annual contract structures that embed volume commitments and regulatory compliance tiers. This buyer concentration enables three-tier pricing stratification across premium polyurethane specifications, standard acrylic dispersions, and economy rosin derivatives.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang provinces are reshaping price floors for waterborne acrylic resins as domestic Chinese producers expand merchant supply. Pricing stratifies across premium, standard, and economy tiers based on solids content purity and REACH registration status. Cost compression in economy rosin segments is intensifying because crude gum rosin harvest volatility in Indonesia feeds through to modified ester producers. Publication printers remain most price-sensitive, while pharmaceutical label converters absorb premiums for low-migration polyurethane specifications.
Supply Chain Analysis
Direct-to-converter channels handle major flexible packaging demand in Germany, China, and the United States, bypassing distributor markups for qualified high-volume accounts. Raw material supply draws from Ludwigshafen for acrylic acid, Shanghai for aliphatic isocyanates, and Fujian for gum rosin feedstock. Single-source vulnerability concentrates in European acrylic acid where BASF's captive production limits merchant availability. Distribution runs through regional resin warehouses co-located with flexographic ink formulation plants in Wisconsin, Bavaria, and Zhejiang.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ink Resins Market functions as a stable compounder where regulatory chemistry substitution mandates provide durable demand visibility for compliant resin suppliers.
For Market Incumbents: Deepen backward integration into acrylic acid and polyurethane intermediate production to defend margin pools against merchant supply volatility. Expand REACH registration dossier capacity to exclude smaller Asian competitors from European gravure supply chains. Prioritize waterborne formulation technology licensing to converters in India's emerging BIS certification window. For New Entrants and Emerging Players: UV-curable oligomer specialization for inkjet segments offers the most penetrable technology wedge, as oxygen inhibition constraints have slowed incumbent R&D cycles. Target pharmaceutical label applications in Japan's Kanto industrial zone where low-migration specifications command formulation premiums. Pursue joint development agreements with digital press OEMs to bypass established converter qualification barriers. For Investors and Strategic Acquirers: Chemical conglomerates with packaging sector adjacencies are the most active acquirer in this space, seeking resin capabilities to complement adhesive and coating portfolios. Evaluate targets with demonstrated ECHA registration capacity and established waterborne polyurethane dispersion expertise. Monitor MEE enforcement intensity in China's Pearl River Delta as the signal indicating acceleration in chemistry substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive supply from Ludwigshafen complex locks in feedstock cost advantage for European flexographic customers. |
| REACH Registration Dossier Expansion | ECHA compliance capacity filters qualified suppliers and compresses competition in gravure resin segments. |
| Waterborne Formulation Licensing | Technology transfer agreements penetrate India's BIS preparation window ahead of domestic capacity buildout. |
| UV-Curable Oligomer R&D Partnership | Collaboration with inkjet OEMs addresses oxygen inhibition constraints limiting thick-film decorative applications. |
| Regional Distribution Hub Consolidation | Co-location with converter formulation plants in Zhejiang reduces logistics costs and qualification cycle times. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate resin demand signals. Primary fieldwork engaged resin plant managers, procurement leads at flexible packaging converters, distribution channel partners, and technical R&D directors at ink formulation houses. Secondary validation drew from customs and trade data, Cefic chemical industry reports, EPA NESHAP regulatory filings, and SEC disclosures from diversified chemical conglomerates. Bottom-up volume modeling across chemistry types and printing processes was cross-checked against top-down market sizing from production capacity aggregates.
Segment-weighting approaches distributed value across acrylic, polyurethane, polyamide, and rosin chemistries, further disaggregated by waterborne, UV-curable, solventborne, and electron beam formulation types. The analytical framework incorporated end-use durability requirements, regional regulatory cluster alignment, and converter qualification status across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and substitution rate assumptions for chemistry transitions. Forecast inputs included MEE enforcement schedules, REACH substance evaluation timelines, and flexible packaging capacity expansion pipelines.
The model holds under stable regulatory enforcement intensity; deviation in EPA, ECHA, or MEE inspection stringency would shift substitution timelines and resin specification premiums. Forecasts reflect documented assumptions regarding crude gum rosin harvest yields and acrylic acid merchant market availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
North America Printing Inks Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Global Printing Blanket Market
Printing Inks
North America Ink Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Global Printing Toners Market
Printing Inks
Food Grade Inks Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Printing Plate Market
Printing Inks
Specialty Ink Market