
 North America Printing Inks Market | 2026-2036
North America Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Printing Inks Market Analytics
High-performance low-migration ink specifications is rotating toward the center of procurement criteria for food-contact packaging across North America. Sun Chemical Corporation leverages captive resin and pigment synthesis to control formulation consistency for sensitive applications. INX International Ink Co. anchors its position through dedicated service labs in Chicago and Toronto that support just-in-time color matching for regional packaging converters.
Printing inks comprise fluid or paste formulations of pigments, resins, solvents or carriers, and additives engineered to transfer image or text onto substrates via mechanical or digital impression, with viscosity typically ranging from 500 to 5000 centipoise depending on print process. The primary commercial purpose centers on enabling high-fidelity visual communication, brand differentiation, and regulatory-compliant product labeling across consumer and industrial goods. UV-curable formulations command premium positioning due to instant polymerization and elimination of drying energy, while water-based systems gain volume in corrugated and flexible packaging as VOC constraints tighten. Digital printing technology captures the fastest expansion trajectory, driven by shorter run lengths and variable-data requirements in commercial and label segments.
EPA National Emission Standards for Hazardous Air Pollutants and California Air Resources Board rules constrain solvent-based ink use, redirecting capital toward compliant chemistries. FDA food-contact notification requirements and Health Canada PMRA guidelines govern migration limits for indirect additives, forcing reformulation cycles that favor qualified suppliers with regulatory dossiers. Stakeholders must monitor state-level patchwork enforcement and cross-border harmonization gaps between US and Canadian compliance protocols.
Market Dynamics
Reformulation pressure from EPA National Emission Standards for Hazardous Air Pollutants and California Air Resources Board VOC rules is compressing solvent-based ink volumes while redirecting R&D capital toward water-based and UV-curable platforms across the region.
Growth Catalysts
- Low-migration ink specifications:FDA food-contact notification requirements and Health Canada PMRA guidelines on indirect additive migration are forcing converters toward qualified compliant systems for sensitive food-contact applications.
- Digital printing adoption:Shorter run lengths and variable-data requirements in commercial and label segments are pulling investment toward inkjet and toner platforms.
- Querétaro packaging cluster expansion:Mexico's central manufacturing corridor is attracting multinational flexible packaging converters seeking nearshoring advantages and duty-free access under USMCA.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas price swings directly impact resin and solvent input costs, compressing formulation margins for commodity ink grades.
- Qualified supplier concentration:Regulatory dossier requirements for food-contact compliance favor established players with dedicated toxicology and migration testing capabilities.
- Curing energy infrastructure:UV-curable systems require capital-intensive LED or mercury vapor lamp installations that smaller converters defer.
Strategic Opportunities
- Biobased resin platforms:USDA BioPreferred program recognition and state-level procurement preferences create pull for vegetable-oil-derived binders in corrugated and publication segments.
- Smart packaging integration:Convergence of conductive inks with printed electronics enables RFID and sensor functionality for pharmaceutical cold-chain monitoring.
- Service lab proximity models:Dedicated color matching and technical support facilities in secondary markets reduce converter downtime and switching costs.
Industry Challenges
- Cross-border harmonization gaps:Divergent FDA and Health Canada notification timelines and data requirements complicate unified North American product registrations.
- Skilled formulation chemist scarcity:Retirement-driven attrition in color science and polymer chemistry functions outpaces university pipeline output.
- Legacy press retrofit complexity:Water-based ink transitions on solvent-configured gravure and flexo equipment demand doctor blade, drying, and anilox modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Printing Inks Market |
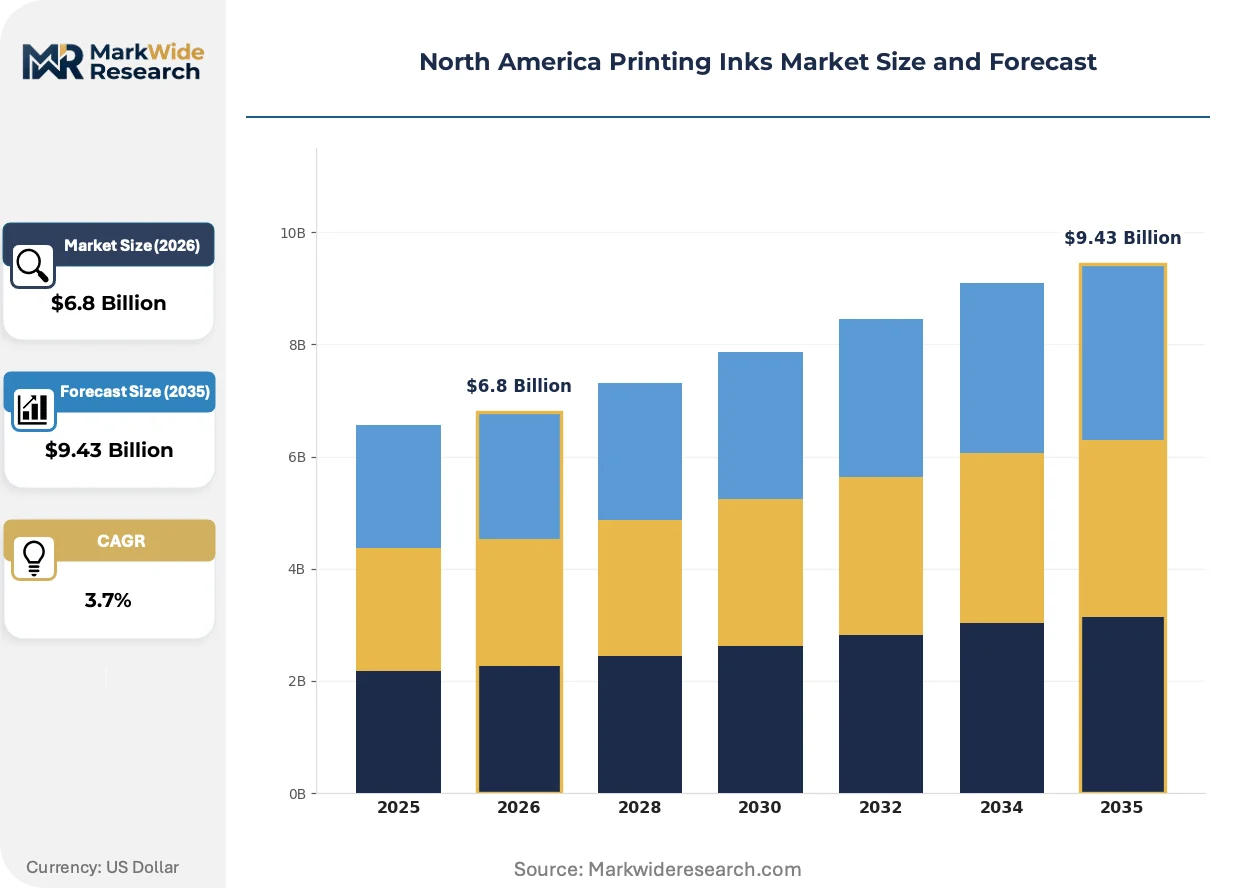
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, UV-curable, Oil-based Application: Packaging, Commercial Printing, Labeling, Publication End User: Food & Beverage, Pharmaceutical, Electronics, Textile Technology: Digital Printing, Flexographic, Gravure, Offset |
| Companies Covered | Sun Chemical Corporation, INX International Ink Co., Flint Group, Siegwerk Druckfarben AG & Co. KGaA, Nazdar Ink Technologies, Wikoff Color Corporation, DIC Corporation, hubergroup Deutschland GmbH, Altana AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Printing Inks Market Evolving Landscape
Reformulation chemistry and digital hardware are jointly restructuring competitive capabilities, with regulatory compliance emerging as the primary technical differentiator rather than color performance alone.
UV-LED curable ink technology is supplanting conventional mercury vapor systems through instant polymerization and 60-80% energy reduction. Flexible packaging converters in the snack and confectionery segments are adopting these platforms fastest. The shift is compressing drying line footprints and enabling thinner film substrates that reduce material costs.
California Air Resources Board SCM 2007 and subsequent amendments are tightening VOC content limits for lithographic and flexographic inks statewide. Formulators are accelerating water-based and energy-curable platform development to maintain market access. The corrugated segment faces the steepest compliance trajectory given its historical reliance on solvent-borne coatings.
Brand owners are consolidating supplier panels and demanding comprehensive migration testing documentation upfront. Regional packaging converters are responding by embedding regulatory affairs functions within technical service teams. The food and beverage vertical exhibits the most pronounced certification-driven preference shift, with low-migration specifications now gating vendor qualification.
North America Printing Inks Market Segmentation
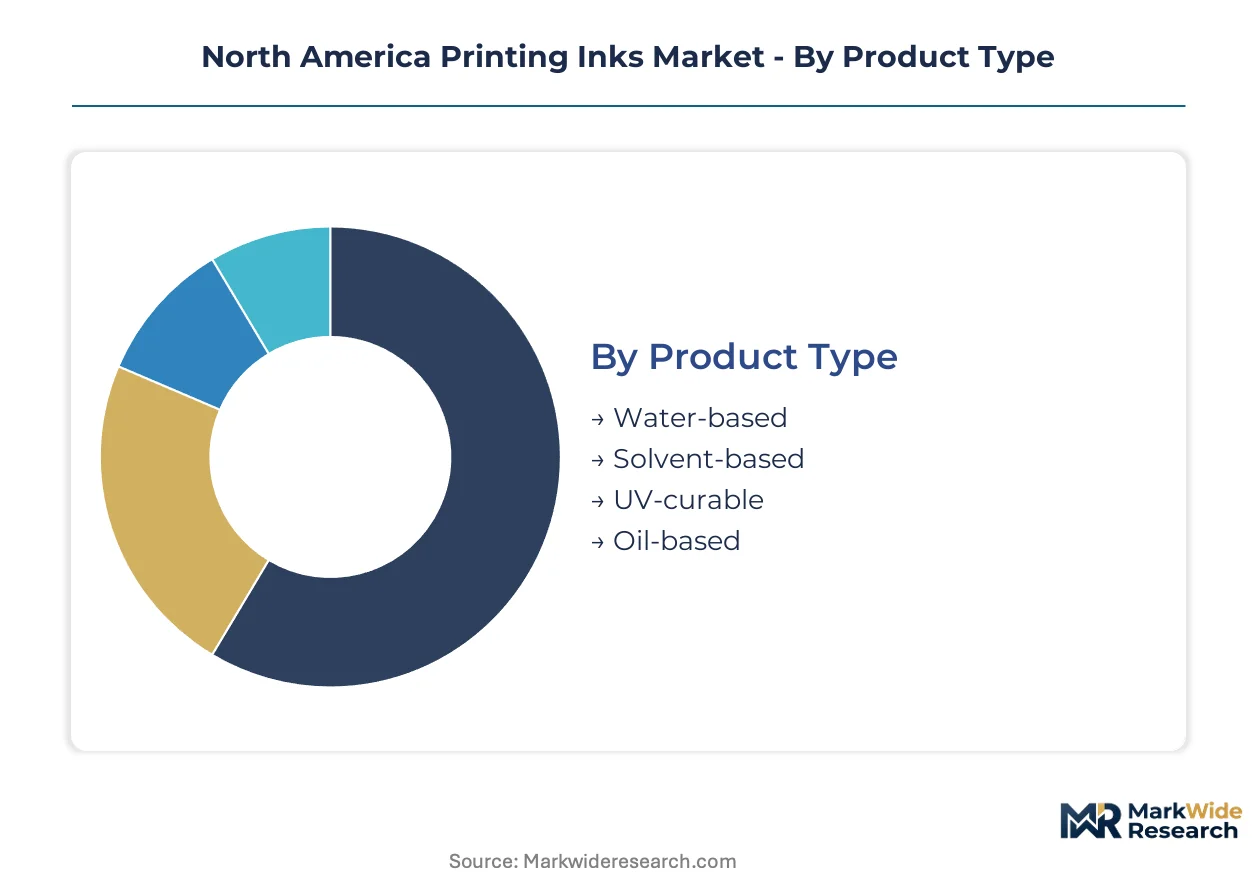
Segmentation in the North America Printing Inks Market reveals how regulatory pressure and substrate requirements split demand across distinct formulation platforms. Understanding these divisions exposes where capital is concentrating and which chemistries face displacement.
Product Type:
Water-based and UV-curable formulations dominate domestic production, while solvent-based volumes increasingly serve export-oriented packaging in Mexico.
- Water-based:Acrylic and polyurethane dispersions formulated below 250 g/L VOC content. Corrugated converters in the US Great Lakes corridor and Ontario are converting legacy flexo lines to capture California Air Resources Board compliance. The segment absorbs the steepest capital redirection from EPA National Emission Standards enforcement.
- UV-curable:Photoinitiator-activated acrylate oligomers polymerizing under 395nm LED or mercury vapor exposure. Snack and confectionery flexible packaging in Chicago and Toronto clusters are retrofitting drying tunnels to exploit instant cure and thinner film compatibility.
- Solvent-based:Nitrocellulose and polyurethane systems in ester-ketone blends, now concentrated in Querétaro export platforms serving Central American markets with less stringent VOC regimes.
- Oil-based:Linseed and soybean alkyd vehicles retaining niche position in sheet-fed commercial work where rub resistance and gloss retention outweigh drying speed requirements.
Water-based holds the largest share; momentum sits with UV-curable as energy infrastructure costs decline.
Application:
Cost tier stratification separates commodity corrugated from premium pharmaceutical labeling, with margin structure determining supplier qualification thresholds.
- Packaging:Flexible films, folding cartons, and corrugated containers requiring migration-compliant formulations for food-contact surfaces. FDA food-contact notification dossiers now gate entry to major CPG supplier panels.
- Commercial Printing:Brochure, catalog, and direct-mail applications where sheet-fed offset and digital toner platforms compete on run-length economics. The segment bleeds volume to electronic media substitution.
- Labeling:Pressure-sensitive and shrink-sleeve formats for beverage and pharmaceutical primary packaging. Variable-data inkjet is climbing fastest in craft spirits and cannabis compliance labeling.
- Publication:Heatset web offset for magazines and directories, collapsing under digital displacement except for high-insert direct-mail co-packs.
Packaging commands the revenue concentration; labeling expands most quickly on pharmaceutical serialization mandates.
End User:
Customer-type segmentation exposes how regulatory stringency concentrates purchasing power among risk-averse multinationals.
- Food & Beverage:The most migration-sensitive vertical, where Health Canada PMRA and FDA indirect additive limits force qualified-supplier consolidation. Low-migration specifications now appear in 80% of RFPs from top-20 CPG brands.
- Pharmaceutical:Cold-chain packaging and compliance labeling requiring thermal-transfer and UV-inkjet durability. Printed electronics integration for temperature-monitoring sensors is emerging in insulin and vaccine distribution.
- Electronics:Conductive and dielectric inks for membrane switches, RFID antennas, and flexible circuit prototyping. The segment sources from specialized formulators outside commodity ink channels.
- Textile:Sublimation and pigment inks for polyester sportswear and soft signage, concentrated in Los Angeles and Mexico City garment districts with short-run digital adoption.
Food & Beverage absorbs the strictest compliance investment; pharmaceutical presents the steepest technology upgrade trajectory.
Technology:
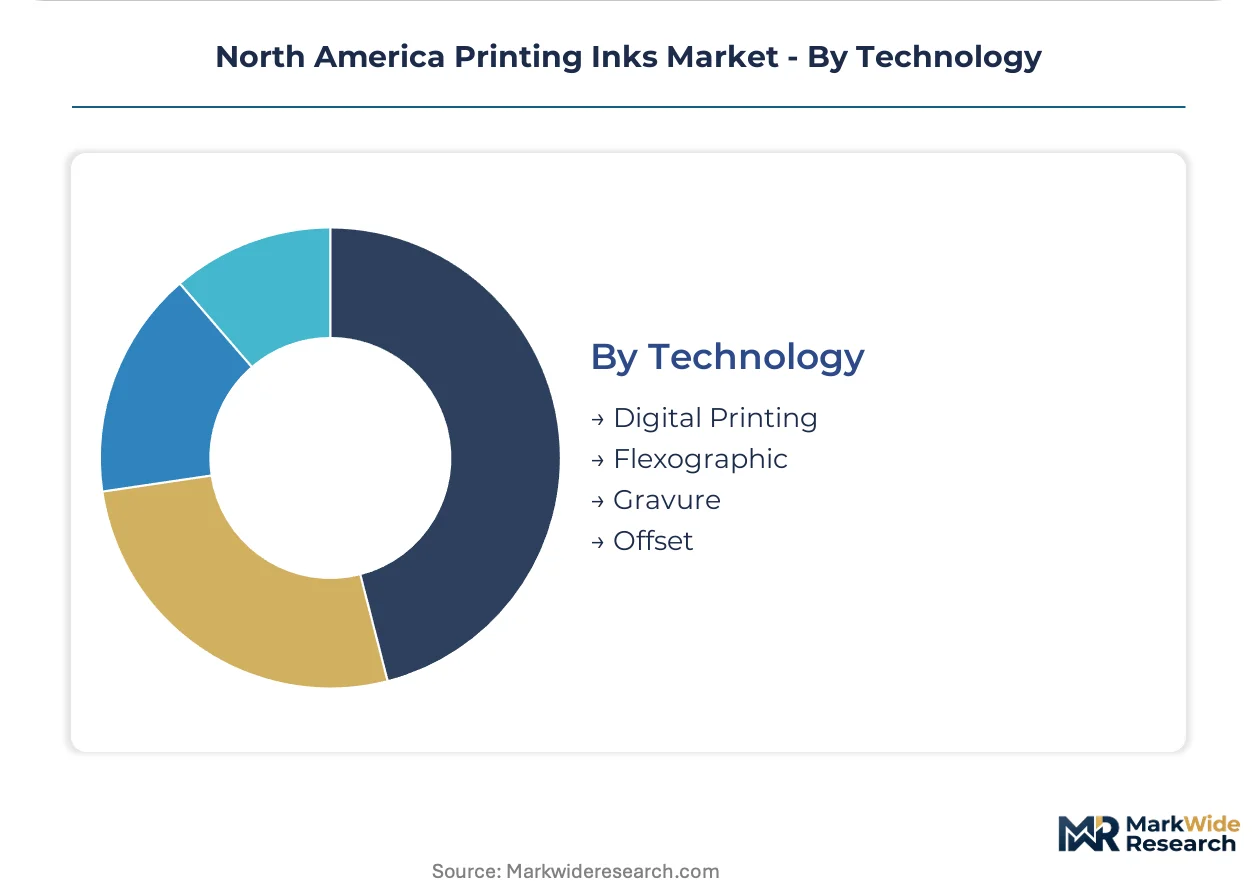
Volume concentration in legacy analog processes masks the margin migration toward digital platforms serving shorter runs and versioning requirements.
- Digital Printing:Inkjet and electrophotographic systems eliminating plate costs and enabling variable-data personalization. Commercial and label segments in Chicago, Toronto, and Los Angeles are adding single-pass inkjet capacity for run lengths below 5,000 impressions.
- Flexographic:Central impression cylinder and stack presses dominating corrugated and flexible packaging. Doctor blade and anilox modifications absorb reformulation capital as water-based inks displace solvent systems.
- Gravure:Cylinder-engraved long-run publication and decorative packaging, retreating to wallpaper and laminate applications where cylinder amortization still computes.
- Offset:Sheet-fed and heatset web lithography for commercial and publication work, losing ground to digital in runs under 10,000 sheets.
Flexographic retains the installed base dominance; digital is gaining share fastest on label and commercial versioning demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented packaging production in Mexico balances import-dependent formulation supply in the United States and Canada. Cross-border chemical trade flows concentrate resin and pigment inputs through Great Lakes logistics corridors. Regional supply chains adapt to divergent VOC enforcement timelines across federal and state jurisdictions.
United States
Flexible packaging converters in the Chicago and Milwaukee corridor are retrofitting flexographic lines for water-based ink compliance. EPA National Emission Standards for Hazardous Air Pollutants enforcement is accelerating capital redirection away from solvent-based gravure platforms. The US Great Lakes manufacturing belt hosts the densest concentration of food-contact qualified ink production facilities serving CPG brand panels.
Canada
Ontario's packaging cluster around Toronto is absorbing reformulation investment to meet Health Canada PMRA migration limit guidelines for indirect food-contact additives. Provincial air quality regulations in partnership with federal standards are compressing solvent-based ink volumes in corrugated applications. Montreal and Vancouver serve as technical service hubs supporting just-in-time color matching for regional converters.
Mexico
Querétaro's central manufacturing corridor is attracting multinational flexible packaging investment seeking USMCA duty-free access and nearshoring cost advantages. Mexican federal environmental regulations maintain less stringent VOC thresholds than US EPA standards, preserving solvent-based ink demand for export-oriented production. The Bajío region's automotive and electronics packaging sectors are driving conductive and specialty ink qualification programs.
North America Printing Inks Market Competitive Landscape
Listed leaders compete with private specialists across formulation consistency and regulatory dossier capabilities. The vendor base organizes around three tiers: multinational integrated suppliers with captive resin synthesis, mid-scale regional formulators with dedicated service infrastructure, and niche digital ink specialists. Competitive positioning hinges on migration testing documentation depth and proximity to converter technical service demands. Consolidation pressure favors players with pre-qualified food-contact portfolios, while biobased resin partnerships represent an emerging alliance vector.
Within the integrated multinational tier, Sun Chemical Corporation and DIC Corporation exemplify scale-driven players with backward control over pigment and resin supply chains. INX International Ink Co. occupies a position among mid-scale specialists emphasizing regional service lab density. Nazdar Ink Technologies represents the niche digital segment, anchoring inkjet formulation expertise for variable-data commercial and label applications. These archetypes illustrate how competitive separation is concentrating around regulatory qualification speed rather than color performance alone.
| Leading Market Players |
|---|
| Sun Chemical Corporation |
| INX International Ink Co. |
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| Nazdar Ink Technologies |
| Wikoff Color Corporation |
| DIC Corporation |
| hubergroup Deutschland GmbH |
| Altana AG |
| Others |
Value Network & Pricing Analysis
FDA food-contact notification requirements and Health Canada PMRA compliance dossiers simultaneously gate supplier qualification and enable price premiums for qualified low-migration ink systems across North American packaging markets. This dual filtering mechanism concentrates purchasing power among risk-averse multinationals while compressing margins for non-compliant commodity grades.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify pricing across food-contact certification tiers, volume scale commitments, and technical service bundling. Price differentiation hinges on FDA notification dossier completeness and Health Canada PMRA migration testing documentation depth. Cost compression in commodity solvent-based grades is intensifying because EPA enforcement redirects demand toward compliant water-based and UV-curable platforms. Corrugated converters in the US Great Lakes corridor exhibit highest price sensitivity due to thin margins and capital retrofit burdens, while pharmaceutical packaging buyers show lowest sensitivity given compliance-driven vendor consolidation.
Supply Chain Analysis
Inventory lead times for photoinitiators and acrylate oligomers stretch across trans-Pacific shipping lanes, tethering UV-curable formulation costs to container freight volatility. Raw material sourcing draws from China for specialty pigments, Germany for photoinitiator chemicals, and domestic US production for acrylic resin dispersions. Single-source vulnerability concentrates in photoinitiator supply where three global manufacturers control qualified pharmaceutical-grade output. Distribution runs through Great Lakes chemical logistics corridors with secondary blending facilities in Chicago, Toronto, and Querétaro serving regional converter clusters with just-in-time color matching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American printing ink demand follows packaging capital expenditure cycles, with food and beverage converter expansion in Querétaro and the US Great Lakes corridor signaling trough exit conditions.
For Market Incumbents: Shield qualified supplier positions by deepening backward integration into captive resin synthesis and expanding toxicology testing capacity ahead of FDA notification backlog expansion. Prioritize service lab proximity in secondary packaging markets to reduce converter switching incentives. Regulatory dossier acceleration represents the critical defensive lever against mid-scale regional formulators with thinner compliance infrastructure. For New Entrants and Emerging Players: Differentiate on biobased resin platforms targeting USDA BioPreferred procurement preferences in corrugated and publication segments. White-space concentration sits with conductive ink formulations for pharmaceutical cold-chain sensor integration, where specialized electronics formulators currently outsell commodity ink channels. Target Querétaro export platforms with solvent-based systems optimized for Central American VOC regimes as a near-term revenue bridge. For Investors and Strategic Acquirers: EPA National Emission Standards enforcement acceleration reshapes the acquisition landscape by devaluing solvent-based formulation assets and premiuming water-based and UV-curable platform capabilities. Long-term viability centers on suppliers with pre-qualified food-contact portfolios and backward-integrated pigment supply. Monitor California Air Resources Board amendment timelines as the signal for reformulation capital deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Sun Chemical and DIC control formulation consistency through captive acrylic and polyurethane dispersion production. |
| Service Lab Geographic Expansion | INX International anchors converter loyalty through dedicated color matching facilities in Chicago and Toronto. |
| UV-LED Curing Infrastructure Partnership | Equipment financing alliances reduce capital barriers for flexible packaging converters adopting instant polymerization platforms. |
| Biobased Resin Platform Development | USDA BioPreferred recognition opens state procurement channels for vegetable-oil-derived binders in corrugated applications. |
| Migration Testing Documentation Investment | Comprehensive toxicology dossiers gate entry to consolidated CPG supplier panels demanding upfront compliance verification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, FDA food-contact notification filings, and customs trade records for resin and pigment imports. Primary interviews engaged formulation chemists at integrated multinational suppliers, procurement directors at flexible packaging converters, technical service managers at regional formulators, and regulatory affairs leads at CPG brand owners. Secondary validation drew from SEC 10-K disclosures, Health Canada PMRA guidance documents, California Air Resources Board rulemaking records, and USMCA trade flow statistics. Bottom-up volume estimates triangulated against top-down packaging production capacity data across the Great Lakes, Ontario, and Querétaro clusters.
Segmentation dimensions modeled span formulation chemistry, application substrate, end-use vertical, and print technology platform across the projection horizon. Water-based, UV-curable, solvent-based, and oil-based chemistries split by corrugated, flexible packaging, labeling, and commercial print applications. Food and beverage, pharmaceutical, electronics, and textile end-use verticals cross-cut with flexographic, gravure, offset, and digital print technologies. CAGRs derived from converter capital expenditure surveys, press retrofit pipeline tracking, and regulatory compliance deadline mapping.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity, stable petrochemical feedstock pricing, and continued USMCA duty-free access would require recalibration. Forecasts reflect assumptions regarding reformulation technology adoption curves and converter capital availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Digital Inks Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Printing Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Food Grade Inks Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Printing Plate Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Flexo-Ink Market
Printing Inks
United States Flexographic Printing Market