
 South Africa Computed Tomography Market | 2026-2036
South Africa Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Computed Tomography Market Analytics
Semiconductor-based detector materials is hardening cost structures across CT system manufacturing. GE Healthcare leverages deep service networks across sub-Saharan Africa to sustain installed-base loyalty. Siemens Healthineers anchors premium positioning through advanced reconstruction algorithms. Philips competes on integrated diagnostic workflow solutions spanning radiology departments.
Computed tomography is an X-ray-based medical imaging modality that reconstructs cross-sectional anatomical slices from multiple angular projections, typically employing rotating gantry architectures with detector arrays capturing attenuation data at sub-millimeter spatial resolution. Its primary purpose is non-invasive diagnostic visualization of soft tissue, bone, and vascular structures for clinical decision-making. Spiral technology dominates routine clinical throughput in South African facilities due to speed and cost efficiency. Cone Beam systems occupy specialized niches in dental and maxillofacial imaging where volumetric accuracy at lower dose protocols matters. Dual Source configurations represent the fastest-growing technology segment among tertiary academic centers performing cardiac and pediatric examinations.
SAHPRA mandates registration and quality compliance for all imported CT equipment, while the country's National Health Laboratory Service enforces radiation safety protocols through inspectorate oversight. The Department of Health's centralized procurement frameworks shape public sector demand patterns and vendor qualification requirements. Stakeholders must monitor SAHPRA's evolving software-as-medical-device classifications and provincial tender restructuring to align distribution strategies with institutional buying behavior.
Market Dynamics
Public hospital procurement expansion through the Department of Health's centralized frameworks is concentrating CT demand into institutional tenders, reshaping vendor qualification requirements and service contract structures across South African radiology departments.
Growth Catalysts
- SAHPRA Registration Mandates:The South African Health Products Regulatory Authority's quality compliance requirements for imported equipment is elevating standards and filtering out substandard suppliers from the procurement pipeline.
- Dual Source Technology:Advanced cardiac and pediatric imaging capabilities at tertiary academic centers are accelerating replacement cycles for aging single-source systems in Gauteng's urban corridor.
- Spiral CT Dominance:Speed and throughput advantages in high-volume public hospitals are consolidating preference for helical acquisition protocols over conventional step-and-shoot architectures.
Market Restraints
- Semiconductor Detector Costs:Hardening prices for scintillator crystals and photodiode arrays are compressing manufacturing margins and elevating system price points.
- Import Dependency:Concentrated sourcing of gantry bearings, X-ray tubes, and reconstruction hardware from European and Asian suppliers exposes procurement timelines to currency volatility and shipping bottlenecks.
- Radiation Safety Inspectorate:The National Health Laboratory Service's enforcement protocols impose extended commissioning timelines that delay revenue recognition for installed systems.
Strategic Opportunities
- Cone Beam Dental Expansion:Maxillofacial and orthodontic practices in Cape Town and Durban are creating specialized niches for volumetric imaging at reduced dose protocols.
- Software-as-Medical-Device Reclassification:SAHPRA's evolving guidance on AI-enabled reconstruction algorithms opens pathways for subscription-based diagnostic tool monetization.
- Provincial Tender Restructuring:Eastern Cape and KwaZulu-Natal health departments are consolidating radiology equipment purchases into multi-year framework agreements favoring integrated service providers.
Industry Challenges
- Clinical Engineer Scarcity:Specialized training for CT system maintenance and tube replacement is concentrated in Johannesburg and Pretoria, leaving peripheral facilities dependent on flown-in technical support.
- Legacy PACS Integration:New reconstruction workstations face interoperability friction with existing picture archiving infrastructure in public sector hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Computed Tomography Market |
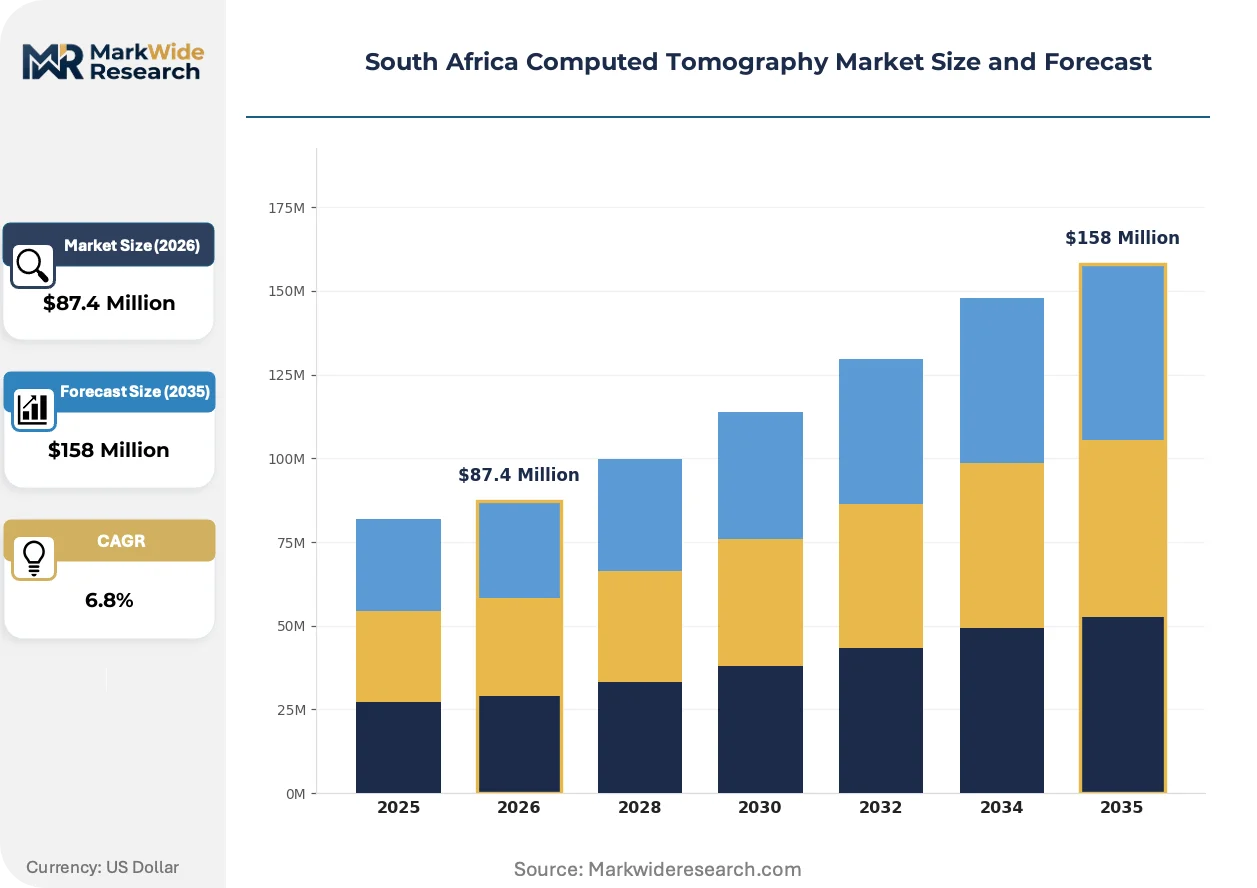
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Source, Detector, Software, Accessories End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: Cone Beam, Spiral, Flat Panel, Dual Source Application: Oncology, Neurology, Cardiovascular, Trauma |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips NV, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Shimadzu Corporation, Shanghai United Imaging Healthcare Co., LTD., Carestream Health, Dentsply Sirona, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Computed Tomography Market Evolving Landscape
Photon-counting detector architectures and iterative reconstruction algorithms are compressing dose-exposure protocols while expanding spectral imaging capabilities across South African diagnostic networks.
Photon-counting CT is electrifying the premium system segment by replacing energy-integrating detectors with direct X-ray photon measurement, enabling material decomposition at sub-millisievert doses. Tertiary centers in Johannesburg and Cape Town are piloting these platforms for cardiac calcium scoring and renal stone characterization. The technology is electrifying competitive positioning by forcing incumbent vendors to accelerate reconstruction software roadmaps or cede high-margin academic accounts.
SAHPRA's software-as-medical-device classification guidance is recalibrating regulatory pathways for AI-enabled image reconstruction and automated lesion detection tools. Manufacturers must now submit algorithm training datasets and performance validation studies alongside hardware registrations. Radiology departments in Gauteng province are prioritizing vendors with pre-cleared diagnostic AI modules to accelerate procurement approvals.
Service contract unbundling is fragmenting traditional full-coverage agreements into component-specific arrangements covering tube replacements, detector calibrations, and software maintenance separately. Public hospital procurement officers are driving this decomposition to match expenditure profiles with annual budget cycles. The Western Cape Department of Health has structured its latest tender to permit third-party engineering support for mechanical subsystems while retaining OEM software updates.
South Africa Computed Tomography Market Segmentation
CT procurement patterns in South Africa diverge sharply between public hospital tenders and private diagnostic networks. Understanding these segment boundaries clarifies where equipment specifications, service contract structures, and regulatory compliance requirements cluster.
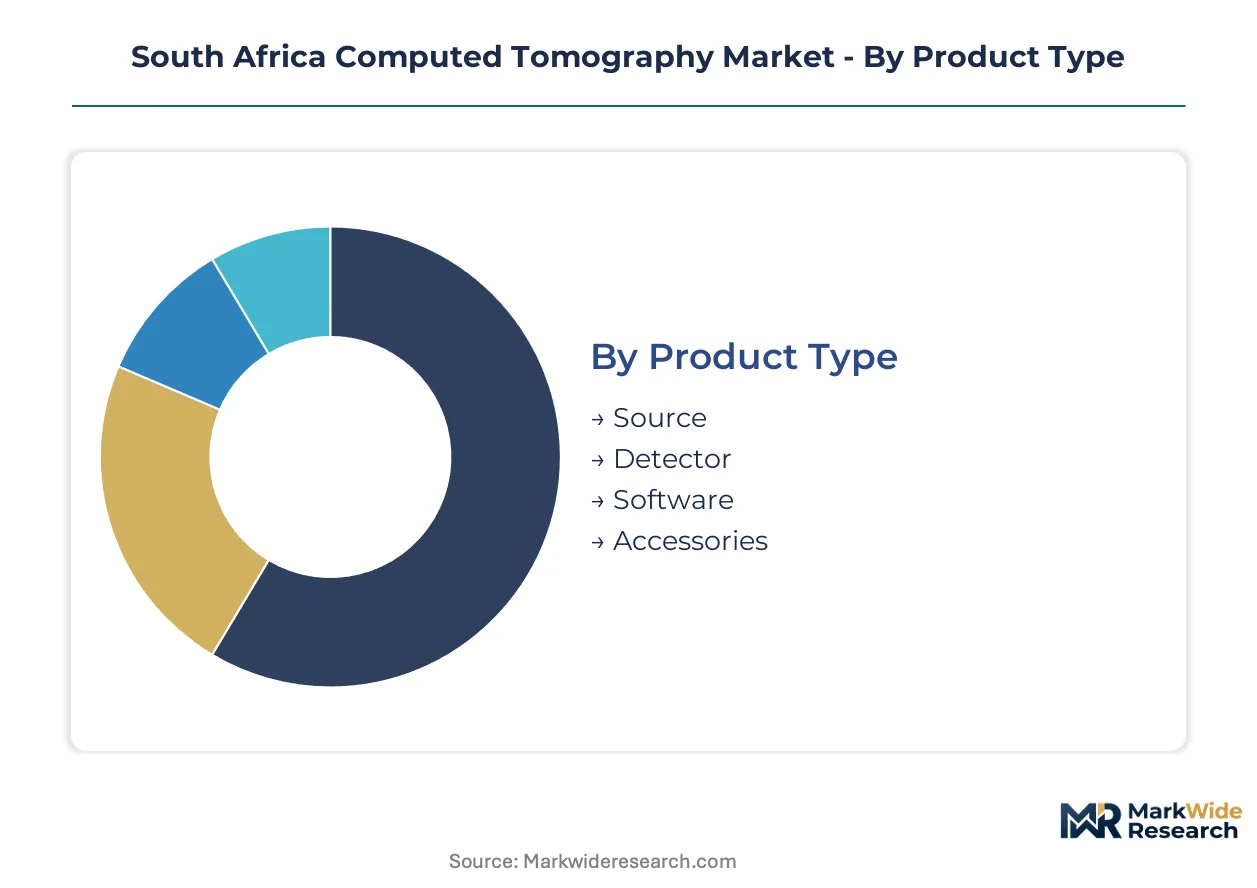
Product Type:
Buyers prioritize detector reliability and reconstruction software performance over gantry specifications when evaluating total cost of ownership across multi-year depreciation cycles.
- Source:X-ray tube assemblies with liquid metal bearings dominate tender specifications for high-throughput public hospitals. Gauteng's academic centers specify dual-source configurations to enable cardiac gating without beta-blocker protocols.
- Detector:Scintillator-photodiode arrays with 64+ slice coverage anchor mid-tier system pricing. Semiconductor crystal shortages are extending lead times for energy-integrating detector modules sourced from European suppliers.
- Software:Iterative reconstruction licenses and AI-enabled denoising packages are unbundling from hardware bundles. SAHPRA's software-as-medical-device pathway is creating separate procurement tracks for algorithm updates.
- Accessories:Contrast injector systems, patient positioning aids, and radiation shielding comprise recurring consumable revenue streams for service providers.
Detector hardware leads on scale; software modules lead on momentum.
End User:
Capital allocation authority separates segments more than clinical application differences.
- Hospitals:Public sector centralized procurement through the Department of Health concentrates volume into framework tenders with 7-10 year service attachments. Tertiary academic hospitals in Johannesburg and Cape Town specify premium systems with cardiac and pediatric capabilities.
- Diagnostic Centers:Private imaging chains in Gauteng and KwaZulu-Natal optimize throughput-per-square-meter with 128-slice spiral platforms. These operators negotiate unbundled service contracts to match expenditure with patient volume fluctuations.
- Research Institutions:Universities and medical research councils acquire specialized spectral imaging platforms for phantom studies and algorithm development.
- Imaging Clinics:Independent radiology practices in Durban and Pretoria prioritize 16-64 slice systems with rapid installation timelines and minimal civil works requirements.
Hospitals command procurement volume; diagnostic centers drive replacement velocity.
Technology:
Acquisition speed and dose efficiency trade off against system cost and maintenance complexity.
- Cone Beam:Flat-panel detector geometry enables volumetric imaging at reduced dose for maxillofacial and dental applications. Cape Town orthodontic practices and oral surgery centers are expanding installations for implant planning.
- Spiral:Continuous patient translation during gantry rotation delivers sub-minute whole-body coverage. Public hospitals standardize on helical platforms for emergency department throughput.
- Flat Panel:Large-area digital detectors support interventional CT-guided procedures in hybrid operating theaters.
- Dual Source:Two X-ray tubes offset at 90 degrees enable temporal resolution below 75 milliseconds for coronary imaging without heart rate control. Academic centers in Johannesburg are gaining share fastest for cardiac and pediatric protocols.
Spiral platforms anchor installed base scale; dual source configurations expand most quickly.
Application:
Reimbursement pathway stability and referrer confidence determine equipment utilization rates.
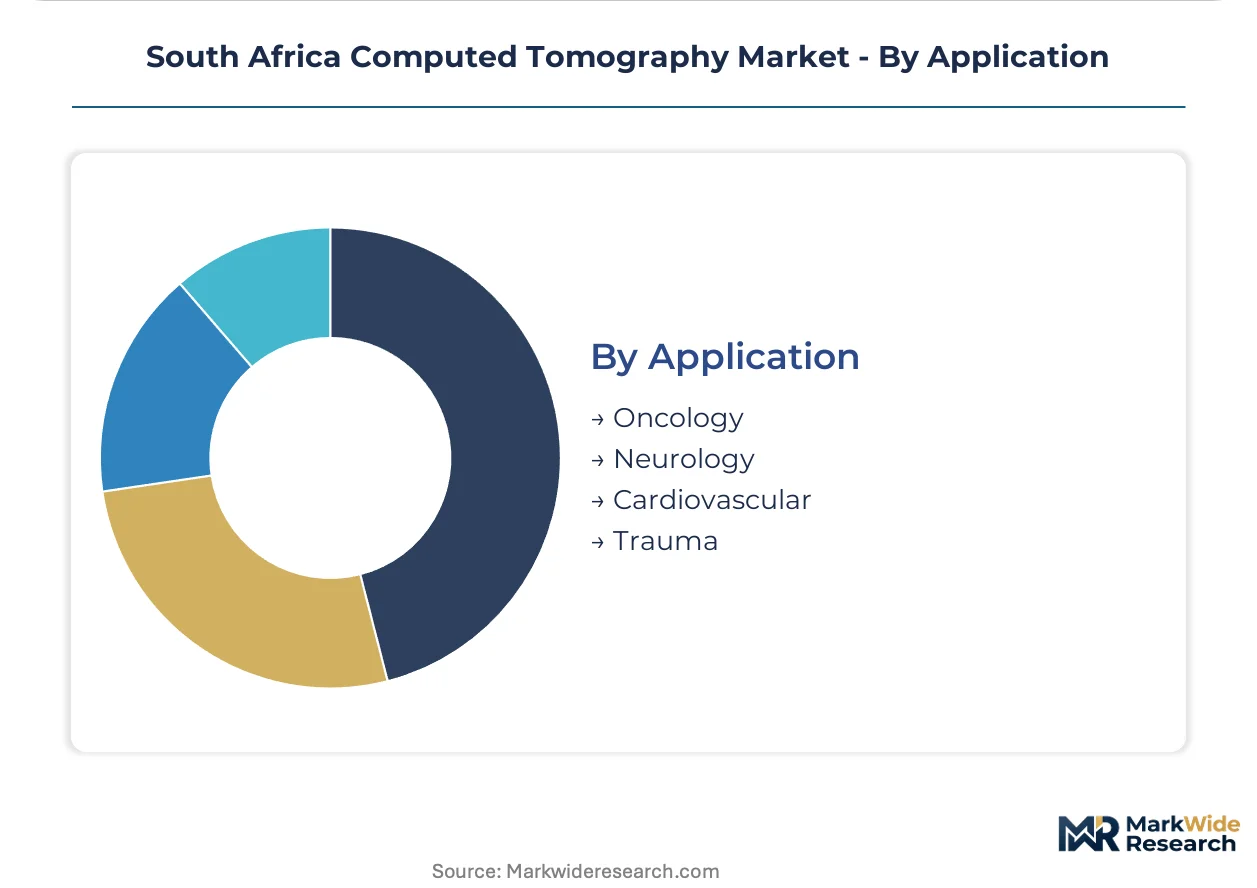
- Oncology:Staging and treatment response monitoring for lung, colorectal, and prostate malignancies generates consistent scan volume. Radiation therapy planning integration drives demand for simulation-capable wide-bore systems.
- Neurology:Stroke protocol imaging and trauma assessment require 24/7 availability with rapid reconstruction. Perfusion imaging capabilities differentiate premium tier offerings for academic medical centers.
- Cardiovascular:Calcium scoring and coronary CT angiography are expanding in private diagnostic networks with direct-pay cardiology referrers.
- Trauma:Whole-body polytrauma protocols in emergency departments prioritize speed over resolution, favoring 64-slice spiral platforms with automated exposure control.
Oncology commands procedure volume; cardiovascular applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province's urban healthcare corridor concentrates CT procurement volume through Johannesburg and Pretoria's tertiary hospital networks. Provincial health departments in Eastern Cape and KwaZulu-Natal are consolidating radiology equipment purchases into multi-year framework agreements.
Gauteng Province
Johannesburg's academic medical centers drive dual-source CT adoption for cardiac and pediatric protocols. SAHPRA's centralized registration requirements filter equipment imports through quality compliance checkpoints. Pretoria's public hospital clusters anchor the country's highest CT scanner density per capita.
Western Cape
Cape Town's private diagnostic networks optimize throughput with 128-slice spiral platforms for cardiology referrers. The provincial Department of Health permits third-party engineering support for mechanical subsystems in its latest tender restructuring. Stellenbosch University's medical campus pilots photon-counting detector architectures for research applications.
KwaZulu-Natal
Durban's imaging clinics prioritize rapid-installation 16-64 slice systems with minimal civil works requirements. The provincial health department consolidates radiology equipment purchases into multi-year framework agreements favoring integrated service providers. Pietermaritzburg's regional hospitals expand emergency department CT capacity for trauma protocols.
Eastern Cape
Port Elizabeth's public hospitals face extended commissioning timelines from the National Health Laboratory Service's radiation safety enforcement. The provincial health department restructures tenders to match expenditure profiles with annual budget cycles. Mthatha's rural facilities depend on flown-in technical support from Johannesburg-based clinical engineers.
South Africa Computed Tomography Market Competitive Landscape
Service contract unbundling dominates the current landscape as public hospital procurement officers fragment traditional full-coverage agreements into component-specific arrangements. The vendor base clusters around three strategic archetypes: multinational imaging conglomerates with deep sub-Saharan service networks, Asian manufacturers competing on system cost, and specialized dental imaging specialists. Geographic expansion through provincial tender participation and technology licensing for AI-enabled reconstruction algorithms represent the dominant competitive moves.
Among the multinational imaging conglomerates, GE Healthcare leverages its established service infrastructure across sub-Saharan Africa to sustain installed-base loyalty. Siemens Healthineers AG anchors premium positioning through advanced reconstruction algorithm offerings. Koninklijke Philips NV competes on integrated diagnostic workflow solutions spanning radiology departments.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Shanghai United Imaging Healthcare Co., LTD. |
| Carestream Health |
| Dentsply Sirona |
| Others |
Value Network & Pricing Analysis
Public hospital procurement consolidation through the Department of Health's centralized frameworks is concentrating purchasing power into institutional tenders, forcing suppliers to restructure service bundling and compress hardware margins to qualify for multi-year agreements.
Pricing Analysis
Semiconductor detector costs pass through directly to system pricing, with scintillator crystal and photodiode array shortages elevating manufacturing input expenses. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers from public hospitals and private imaging clinics. Pricing pressure stems from unbundled service contracts as procurement officers fragment full-coverage agreements into component-specific arrangements. Public sector buyers exhibit highest price sensitivity due to annual budget cycle constraints, while tertiary academic centers prioritize cardiac and pediatric capabilities over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle Gauteng's academic medical center demand, while distributor networks serve provincial health departments in Eastern Cape and KwaZulu-Natal. Manufacturing concentrates in Germany, China, and Japan for gantry bearings, X-ray tubes, and reconstruction hardware. South African procurement draws from concentrated European and Asian suppliers for energy-integrating detector modules and liquid metal bearing assemblies. Single-source vulnerability in semiconductor crystal sourcing exposes lead times to shipping bottlenecks and currency volatility. Distribution runs through OEM service subsidiaries and authorized third-party engineering providers for mechanical subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's CT market compounds steadily as public hospital procurement expansion institutionalizes replacement cycles and technology upgrade pathways across provincial health networks.
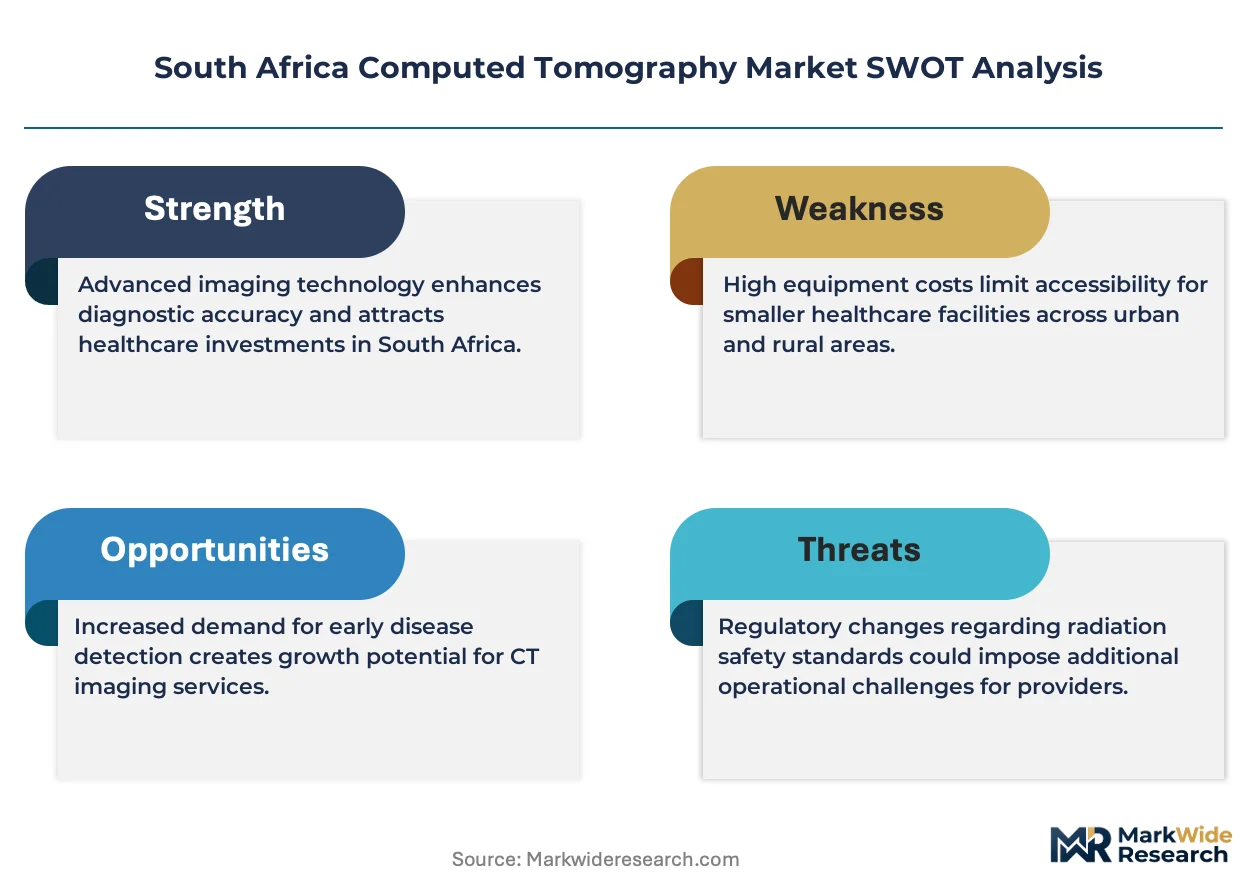
For Market Incumbents: Deepen service infrastructure in Johannesburg and Pretoria to defend against Asian manufacturers competing on system cost. Establish captive technical training programs to address clinical engineer scarcity threatening peripheral facility support contracts. Anchor premium positioning through SAHPRA pre-cleared AI-enabled reconstruction modules before software-as-medical-device pathways mature. For New Entrants and Emerging Players: Independent service organizations represent the most penetrable channel partner type for mechanical subsystem support under Western Cape's tender restructuring. Target Cone Beam dental expansion in Cape Town and Durban orthodontic practices where volumetric imaging demand outpaces specialized supplier presence. Pursue rapid-installation 16-64 slice positioning to capture imaging clinic procurement in Durban and Pretoria with minimal civil works requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated diagnostic workflow providers possessing SAHPRA registration expertise and established provincial tender relationships. Long-term viability favors vendors with software subscription monetization capabilities as AI-enabled reconstruction algorithms separate from hardware bundles. Monitor SAHPRA's evolving software-as-medical-device classifications as inflection indicator for regulatory moat formation.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Software-as-Medical-Device Registration | Pre-cleared AI reconstruction modules accelerate Gauteng procurement approvals for premium system vendors. |
| Provincial Tender Framework Participation | Eastern Cape and KwaZulu-Natal multi-year agreements favor integrated service providers with maintenance infrastructure. |
| Clinical Engineer Training Investment | Johannesburg-based technical capacity addresses peripheral facility dependence on flown-in support. |
| Photon-Counting Detector Pilot Programs | Stellenbosch University research partnerships establish premium positioning for cardiac calcium scoring applications. |
| Service Contract Unbundling Capability | Component-specific arrangements align with public hospital annual budget cycle expenditure profiles. |
Research Methodology
Coverage spans South Africa's nine provinces, with primary inputs from each major urban healthcare corridor. The analysis combines structured interviews with hospital procurement officers, biomedical engineers, radiology department heads, and GPO contracts managers alongside secondary validation through SAHPRA registration databases, Department of Health tender documentation, and National Health Laboratory Service radiation safety protocols. Bottom-up equipment installation tracking and top-down healthcare expenditure modeling triangulate market sizing across public and private diagnostic networks.
Segmentation granularity extends to technology type, end-user category, application area, and provincial procurement authority across the projection horizon. CAGRs derive from equipment replacement cycle analysis, technology diffusion curves, and institutional budget allocation patterns. Modeled inputs include tertiary academic center dual-source adoption rates, public hospital spiral platform standardization, and Cone Beam dental segment expansion in metropolitan orthodontic practices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAHPRA regulatory pathway evolution and provincial health department restructuring timelines. Projections reflect assumptions regarding semiconductor supply stabilization, currency volatility moderation, and clinical engineer training program expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Echocardiography Market
Medical Imaging
Ultrasound Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Neurophotonics Market